

In mid 2012 during the midst of MOOC mania, I wrote a post noting that we should pay attention to future generations of the concept and that there were four barriers that the MOOC vendors would have to overcome to have any long-lasting impact.
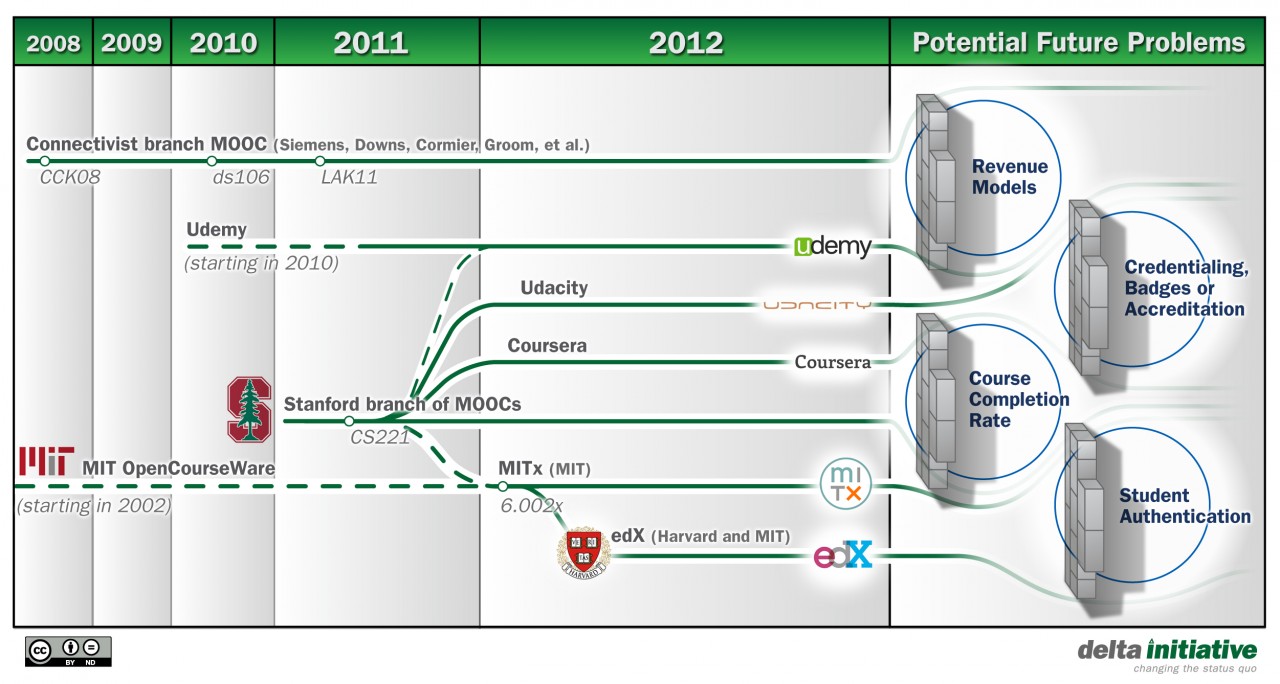
Given this short timeline and the nature of investment-backed educational experiments, I think the real focus should be on whether and how MOOCs or successor models build on current scalability and openness while overcoming these four barriers.
Six years later, it is becoming increasingly clear that the next-generation model for MOOCs in higher education is to become a form of Online Program Management (OPM) providers, including the near-term focus on master’s degrees. The OPM market has demonstrated revenue models (tuition revenue sharing mixed with fee-for-service), the end credential is the already-accepted degree, course completion rates are higher for paying and matriculated students, and degree programs have methods for student authentication. In other words, the MOOC-based OPM model is the next-generation designed to address these challenges.
The shift into the OPM market has been documented in a series of posts in July of 2017, March, April, and May of 2018; and from Dhawal Shah from Class Central . In the May e-Literate post:
The picture one gets is of a chaotic market that is not for the faint of heart, and one that will likely see further consolidations and category changes. 2U, for its part, has been successful partially due to a niche strategy where they go after elite master’s programs and mostly avoid direct competition or engagement with the rest of the market. And recently we have started to see the MOOC providers become OPM providers – where the primary revenue for Coursera and FutureLearn are based on revenue sharing with online programs, albeit with lower sharing rates and with very different marketing approaches. In other words, there seems to be several efforts to enter into the same OPM race, but if possible to avoid being in the mainline rev-share OPM market.
Last week Julia Stiglitz from GSV Advisors, in their first podcast episode, interviewed Coursera CEO Jeff Maggioncalda who joined the company summer 2017. This interview gives the clearest view yet of Coursera’s emerging business model, and by extension it helps explain the new subset of MOOC-based OPM that includes FutureLearn, edX, and Udacity as vendors. ((Outside of Georgia Tech legacy contract, Udacity has moved to corporate professional development market, which is a different approach to same problem.)) I think that the media narrative of tuition revenue-sharing vs. fee-for-service OPM models is overblown, especially since there is a spectrum in that respect more than a binary choice of OPM vendor types. What the MOOC-based OPM entry introduces is a more fundamental characteristic of how traditional institutions develop online programs – namely low-cost vs. full-cost online degrees.
The first note from the interview is that the Coursera of 2018 is not the Coursera of 2012. While Maggioncalda still shows aspects of that old-time MOOC belief system, his approaches are very much rooted in focusing Coursera on a solid business model. And the difference shows. The second note is that 2U’s success in the OPM market and a successful IPO had a big influence on Coursera’s shift. [Emphasis added in transcript]
Julia: You know when you first joined. You spent some time looking at Coursera’s strategy, and really digging in and looking at the different businesses that Coursera had, and one of them that you were particularly attracted to, and you have put increased attention on here at Coursera is the online degrees business. What was it about online degrees that excited you?
Jeff: Yeah. This is sort of I think another good example of what good entrepreneurs have to do, is you have to have feedback loops; you need to get information from multiple sources to understand the nature of a problem so that you can come up with solution. The nature of an opportunity so you can develop a strategy to go after it. It’s really actually pretty simple. I came in – you were on the team, too, we did a lot. We call them deep dives. We went all through the business model, and there’s a great book Business Model Generation that really, to me, gives a nice framework for saying this is what a business model is. It is a target customer. It is a value proposition and offering that solves their needs. It’s a set of channels of how you acquire those customers. It’s a servicing models of how you service the models. Internally it’s the key activities and resources you bring to bear on that. It’s the partners that you work with. It’s the financial revenues and costs, and is your competition. So and that’s the framework. And we stepped through every one of those. I wrote 250 questions across that business model that we as an executive team went through. You know step by step by step, so that everybody learned the nature of our business. And what became very obvious is we had a few things that nobody else really has.
We had 36 million learners, at the time it was 25 million. 25 million learners from all around the world. That’s a pretty big asset. We had university partners. Now there are competitors out there like LinkedIn Learning, previously Lynda, like PluralSight, like SkillSoft. You know there’s YouTube, there’s Khan Academy – there’s a lot of content out there. You were one of the ones who told me in one of those early meetings, “Hey we’re worried that content, generic content, might become a commodity.” Well, we don’t want to play a commodity game. So what is it about my partners that’s super distinctive? Well our partners are universities, and they’re not just the universities, they’re the best universities in the world, and they’re spread around the world. So you say, well I’ve got a resource that almost no one has, which is this network of universities. Right now they’re publishing MOOCs, and there’s something special about MOOCS, but MOOCs are a little more susceptible to that commoditization just as MOOCs. But what was not very susceptible to commoditization are degrees. So that’s OK. We have an asset nobody else has, and what they do really well is degrees, and they still have market sizing. How big is the market for degrees? 1.5 trillion dollars. Okay, well that’s a pretty big opportunity. And then you say, what’s the likelihood that that industry could be transformed due to technology . . . You know, some industries it’s easier to transform, others, it’s harder. The provision of education is absolutely set up nicely to be enhanced, transformed by technology.
I think Uber and Lyft were really smart when they said “you know on-demand transportation, called a taxi, it’s a big market, but it’s a broken product. And if we just do some sort of digital view of this kind of redesign what on-demand transportation looks like, it’ll be a much bigger market.” I’m looking at degrees, I’m not saying it’s broken altogether, but if you look at the student debt out there, you look at the the lack of access, and you look at how inconvenient it is for people to have to stop their lives – especially for master’s degrees – quit their job, move their family, pay hundreds of thousands of dollars, forfeit their income. That’s a broken product. So I thought we got partners who are really good, and a massive economic opportunity, and a product that is just ready to be dramatically improved by technology, and so I thought this is pretty good. We should go after this. By the way we also had 2U trading at like a 12 times forward multiple. So clearly Wall Street loved the idea of online degrees, and 2U’s been doing great. They’re growing really rapidly, so there’s a data point out that says, hey this company is doing really, really well; We should be able to do pretty well here, too.
Julia: Could you share a little bit about what this redesign looks like? Because the online degrees aren’t new. You know 2U is doing them. And before 2U there were a whole set of online degree providers that were out there, so why is what Coursera is doing different?
Jeff: Yeah I think it’s a few things. The number one, I would say, is quality. When I say quality, I mean the quality of the credential. So a lot of people have spent a lot of money on for-profit college degrees that just don’t have very good credential value, they’re not recognized in the job market. You pay a lot of money, you don’t get much back for it. One of the reasons that people pay so much for the top universities is that those types of degrees means something in the job market. There have been a lot of online degrees out there, from universities, that charge a lot and don’t get you very far. Our partners happen to be the best universities in the world, with the highest credential value in the world. When these degrees come online, and these degrees online are the same degrees as on campus, you’re getting something as a credential that’s extremely valuable. That should have a very high ROI. Because we’re doing it online the cost is often less than half. So it’s a top quality credential at half the price. Same credential you get on campus.
Different Assumptions on Tuition
There’s a lot of useful insight in the full interview, but I’d like to call out the fundamental question that gets raised about online education with this market view. Should online degrees from traditional universities cost the same as face-to-face offerings, or should they cost significantly less?
For full-service revenue-sharing segment of the OPM market, some core assumptions are built on the assumption of high revenue share percentages and full-priced online degrees. 2U is probably the best-known and arguably the most successful OPM company, and like Coursera they target elite institutions as partners. In 2U’s website under “Our Approach” they describe how their online programs typically charge the same as on-campus programs.
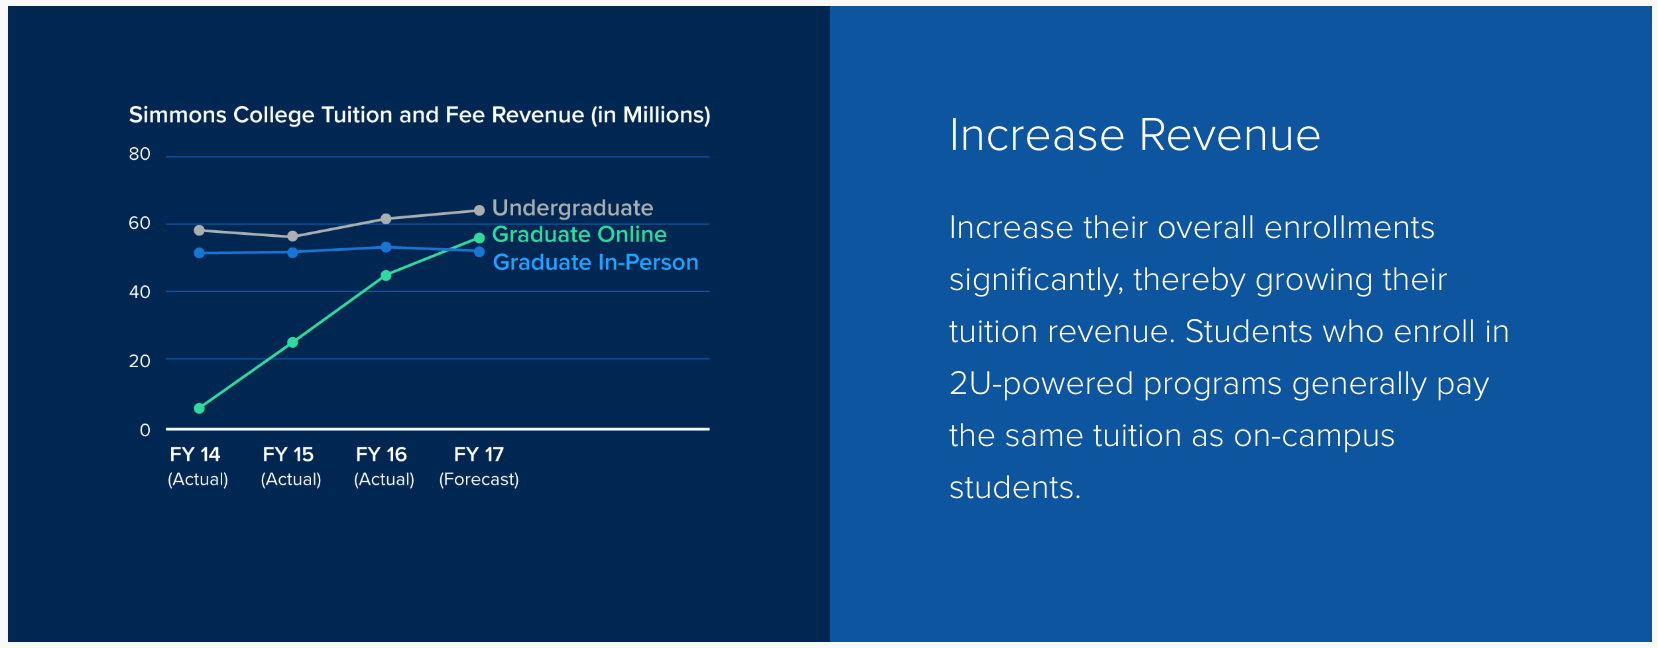
Most of the full-service revenue-sharing segment of the OPM market is similar in its view, whether from Pearson, Wiley, Academic Partnerships, or others – relying on consistent tuition as for online programs, and if there are lower prices they tend to be marginally lower. ((Disclosure: 2U and Pearson are sponsoring participants in our Empirical Educator Project.)) The Coursera approach is in direct contrast with this view, based on the interview as well as several of their online degree programs. There are arguments for either approach. With full-cost tuition, the idea is that the online degree gives at least as much value to students as the face-to-face, or on-campus, degree, and therefore students will be willing to pay the same. With low-cost tuition, the idea is that while students get the same value, “because we’re doing it online” the costs should necessarily be lower. Online infrastructure and marginal costs are much lower than investment in physical facilities. The point here is that this is a fundamentally different set of assumptions.
Writing about the Illinois $22,000 iMBA program, Marc Ethier described this different approach to pricing:
For most, the initial appeal of the program was certainly the price tag. Illinois’ iMBA costs a fraction of a degree from an elite school, where the median cost is roughly $171,000 and can break the $200,000 mark at the far end of the scale. Illinois’ own residential two-year MBA costs more than $100,000. Arshad Saiyed, executive director of online programs at the Gies College, acknowledges that the low cost brought the program to many prospective students’ attention — but says the iMBA has kept students around through a combination of high-quality instruction and successful community building.
Different Assumptions on Student Recruiting
For OPM full-service vendors, the largest expense is typically marketing and sales – i.e. recruiting potential qualified students. The predominant approach to OPM student recruitment has been based on digital marketing – advertising and outreach on social media platforms, search engine placement, digital advertisements in articles. With the MOOC-based OPM subset of the market, there is now an alternative approach based on having a multi-sided platform model. Coursera views their 36 million registered learners as an asset – a natural base of potential students for online degrees that can be reached without external advertising. In addition, the original aim and design of large-scale MOOCs is based on ability to easily sign up new learners for low- or no-cost, with the opportunity to move these students into higher-cost credentials and degrees over time, not requiring full financial commitments from students up front. While a Coursera or FutureLearn might use digital marketing for recruitment, that is not their primary method.
Different Assumptions on Course Size
Related to the above assumptions, in 2U’s case the class size is small – typically 10 – 20 students leveraging the platform’s design around small discussion groups, using both synchronous and asynchronous learning. This 2018 article about Washington University’s two programs partnering with 2U partially describes this approach.
But what is it like for student to pursue a graduate degree in law fully online? How could a pre-recorded lecture support the active teaching that’s integral to discipline? After all, watching a video isn’t the same as participating in a conversation. To support such engagement, 2U created a new tool.
“Through building an online LLM [master’s of law] program with Washington University in St. Louis, we learned how to design one of the most important tools we provide today: the bidirectional learning tool, or BLT,” said Chip Paucek, co-founder and CEO of 2U. “Socratic-style teaching is fundamental to all law curriculum and coursework. As such, it was imperative for us to design a way to conduct Socratic-style group discussions for Wash U once we signed their online LLM program.
“What we didn’t realize is that while we were developing a software tool to help solve the challenge of teaching the Socratic method online, we were simultaneously creating a way to facilitate discussion-based learning in an asynchronous environment that would eventually be used in all of our future partner programs.”
The approach that 2U and Wash U Law conceived relies upon the ingenious integration of asynchronous and synchronous course components. Instead of lecturing from a podium, faculty address small groups of student actors. At key points, the instructor breaks the fourth wall and addresses the online student, who is prompted to answer without the benefit of knowing how his or her peers have responded. In other words, students can’t piggyback like they might in an in-person class.
After responding, online students can review one another’s answers. They might be prompted to answer follow-up questions, or they might be asked to come to the next live class prepared to defend whatever position they’ve chosen. The preparatory work that might otherwise happen during an in-person class is accomplished in advance through the pre-recorded sessions, enabling faculty to make better use of live, synchronous time.
In contrast, consider a Class Central interview with Maggioncalda when talking about scaling and its challenges.
I think about systems. As the system gets bigger, where would the bottlenecks emerge? My sense is that the bottlenecks will emerge in live sessions and in grading. That’s my guess. The grading, I’m actually not so concerned about because I think the ability to automate grading at scale will become pretty good. The live sessions get tricky. From a technology perspective, I’m not that worried about it. It’s the professor’s time and attention. My thought is it’s going to be a little bit like pyramid, where the number of hours that the main professor puts in won’t really change. If you think about how medical systems have worked, a doctor is in the system, but the number of minutes and hours that a doctor spends [with each patient] becomes an increasingly smaller portion of the total time [during which medical treatment is being delivered]. I think it will probably be somewhat similar for education. The size of the classes could be big, let’s say 10,000. But that will be broken into sections of say 50. And each of those sections has an expert who’s probably not the professor. Also, there will be a lot more collaborative learning among the peers in the class. If you think about it, a lot of learning does actually happen among the folks in a class. The expert just dispensing wisdom is not the way most learning happens. I call it “high engagement learning at scale.” A major piece of high engagement learning at scale is utilizing your classmates to provide a highly valuable learning experience.
Coursera is pursuing a path to enable high enrollments in low-cost programs, and they view their challenge to balance scale and student engagement, with class sections of ~50 students.
Good Enough vs. Better Enough
In two posts recently, Michael described a battle in the digital curricular materials market. Focusing on Cengage Unlimited in the first one, he described this dynamic.
Make no mistake; this is a potential inflection point in the curricular materials market. There is a war raging between curricular materials that are “good enough,” meaning that the lower price has a bigger impact on student outcomes than any differences in the quality of more expensive alternatives, versus “better enough,” meaning both instructors and students believe the product makes a sufficient difference in student outcomes that the more expensive product is worth the premium. Cengage is betting the farm on “good enough” beating out “better enough” and, win or lose, their bet could cause tectonic shifts in how curricular materials are developed, purchased, and used. It will have implications for inclusive access, adaptive courseware, textbook companies, textbook authors, and the landscape of options available to students and teachers.
Elaborating in the second post:
The distinction I’m trying to make between two strategies is a little tricky. I’m not arguing that Cengage, for example, thinks that their products aren’t great or that they think all anybody needs is the cheapest PDF possible. And on the other hand, “better enough” no longer means better editing or better production values, which is the way that textbook publishers used to position themselves against OER (and still do sometimes, although that reflex is beginning to fade). Rather, it’s about improving student outcomes.
What we are seeing in the OPM market, with the introduction of MOOC-based degrees, is a new battle. MOOC providers and its partner institutions, represented by Coursera, betting on “good enough”; and 2U and its partners betting on “better enough”. Like the curricular materials market, the product is based on student outcomes, which wraps in the value of the credential coming from the university along with the academic and administrative experience enabled by the company. Coursera obviously believes in the quality of their experience, and their partners have some programs that are not deeply discounted, but their market position is based on the program price being the compelling feature for students, including free or low-cost on-ramps. 2U understands that students are seeking more cost effective options, which was one driver behind creating the short-course segment with the acquisition of GetSmarter, but their market position is based on quality of experience and value of credential being the compelling feature for students. But the difference in approaches is stark and significant.
While there is likely room in the market for both approaches, the Coursera of 2018 (and not the Coursera of 2012) deserves careful observation to understand future trends with online degrees. Win or lose, their bet on low-cost online degrees will have big implications in the market.
