e-Literate

Present is Prologue

Tag: Grand Canyon University

  • Fate of EDU For-Profits: A look into recent enrollment changes and shut downs

    Fate of EDU For-Profits: A look into recent enrollment changes and shut downs

    One month ago the Education Corporation of America (ECA) was the latest for-profit system to shut down, as described by Inside Higher Ed:

    Education Corporation of America owns more than 75 campuses and enrolls at least 20,000 students in mostly certificate-granting professional disciplines such as cosmetology, culinary arts and medical and dental assistant programs. It operates chains including Virginia College and Brightwood College.

    A week later Adtalem Global Education completed their sale of for-profit systems:

    Adtalem Global Education (NYSE: ATGE), a leading global education provider, today announced the completion of the transfer of ownership of DeVry University (DVU) and its Keller Graduate School of Management to Cogswell Education LLC. Today’s announcement closely follows Adtalem’s disclosure of the transfer of ownership of Carrington College to San Joaquin Valley College, Inc. (SJVC Inc.) which was completed on Dec. 4, 2018. Post divestitures, Adtalem Global Education’s U.S. postsecondary degree-granting institutions serve the high-demand, rapidly growing medical and healthcare markets.

    The centerpiece of Adtalem’s remaining portfolio ((Disclosure: Adtalem is a former client of MindWires and past subscriber of our LMS Market Analysis service.)) is Chamberlain University, a growing system of nursing-based programs, and a look at the underlying data reveals that Chamberlain is one of only two large for-profit systems with significant growth.

    Given all the changes in for-profits, we tend to see either anecdotes about specific institutions or aggregate data on all for-profits combined. What is missing, though, is a view in between, showing enrollments and changes to a select group of for-profit schools, to help understand the different fates of different institutions.

    Why does this matter? For one, many for-profit chains are accredited as a number of different institutions, and they need to be combined to understand overall company strength. Second, following Tolstoy’s idea that “All happy families are alike; each unhappy family is unhappy in its own way”, the decline of for-profit institutions has a number of unhappy families with different lessons. In the case of ECA there is something unseen in other cases – ECA abruptly shut down despite growing enrollment by 32% year-over-year across Virginia College and Brightwood Colleges in the most recent IPEDS.

    The chart below shows differences from the Fall 2012 IPEDS enrollment report (grad + undergrad) for the 13 largest degree-granting systems as of that date, running through the Fall 2017 report (the most recent data available). I’ve added notes to show the various changes in ownership, control, and status for these systems – converting to non-profit status with a for-profit operating entity, merging of institutions, sale of institutions as with DeVry, going bankrupt withy full shut-down of systems, or taking the company private as with the U of Phoenix. Click on image for full size version.
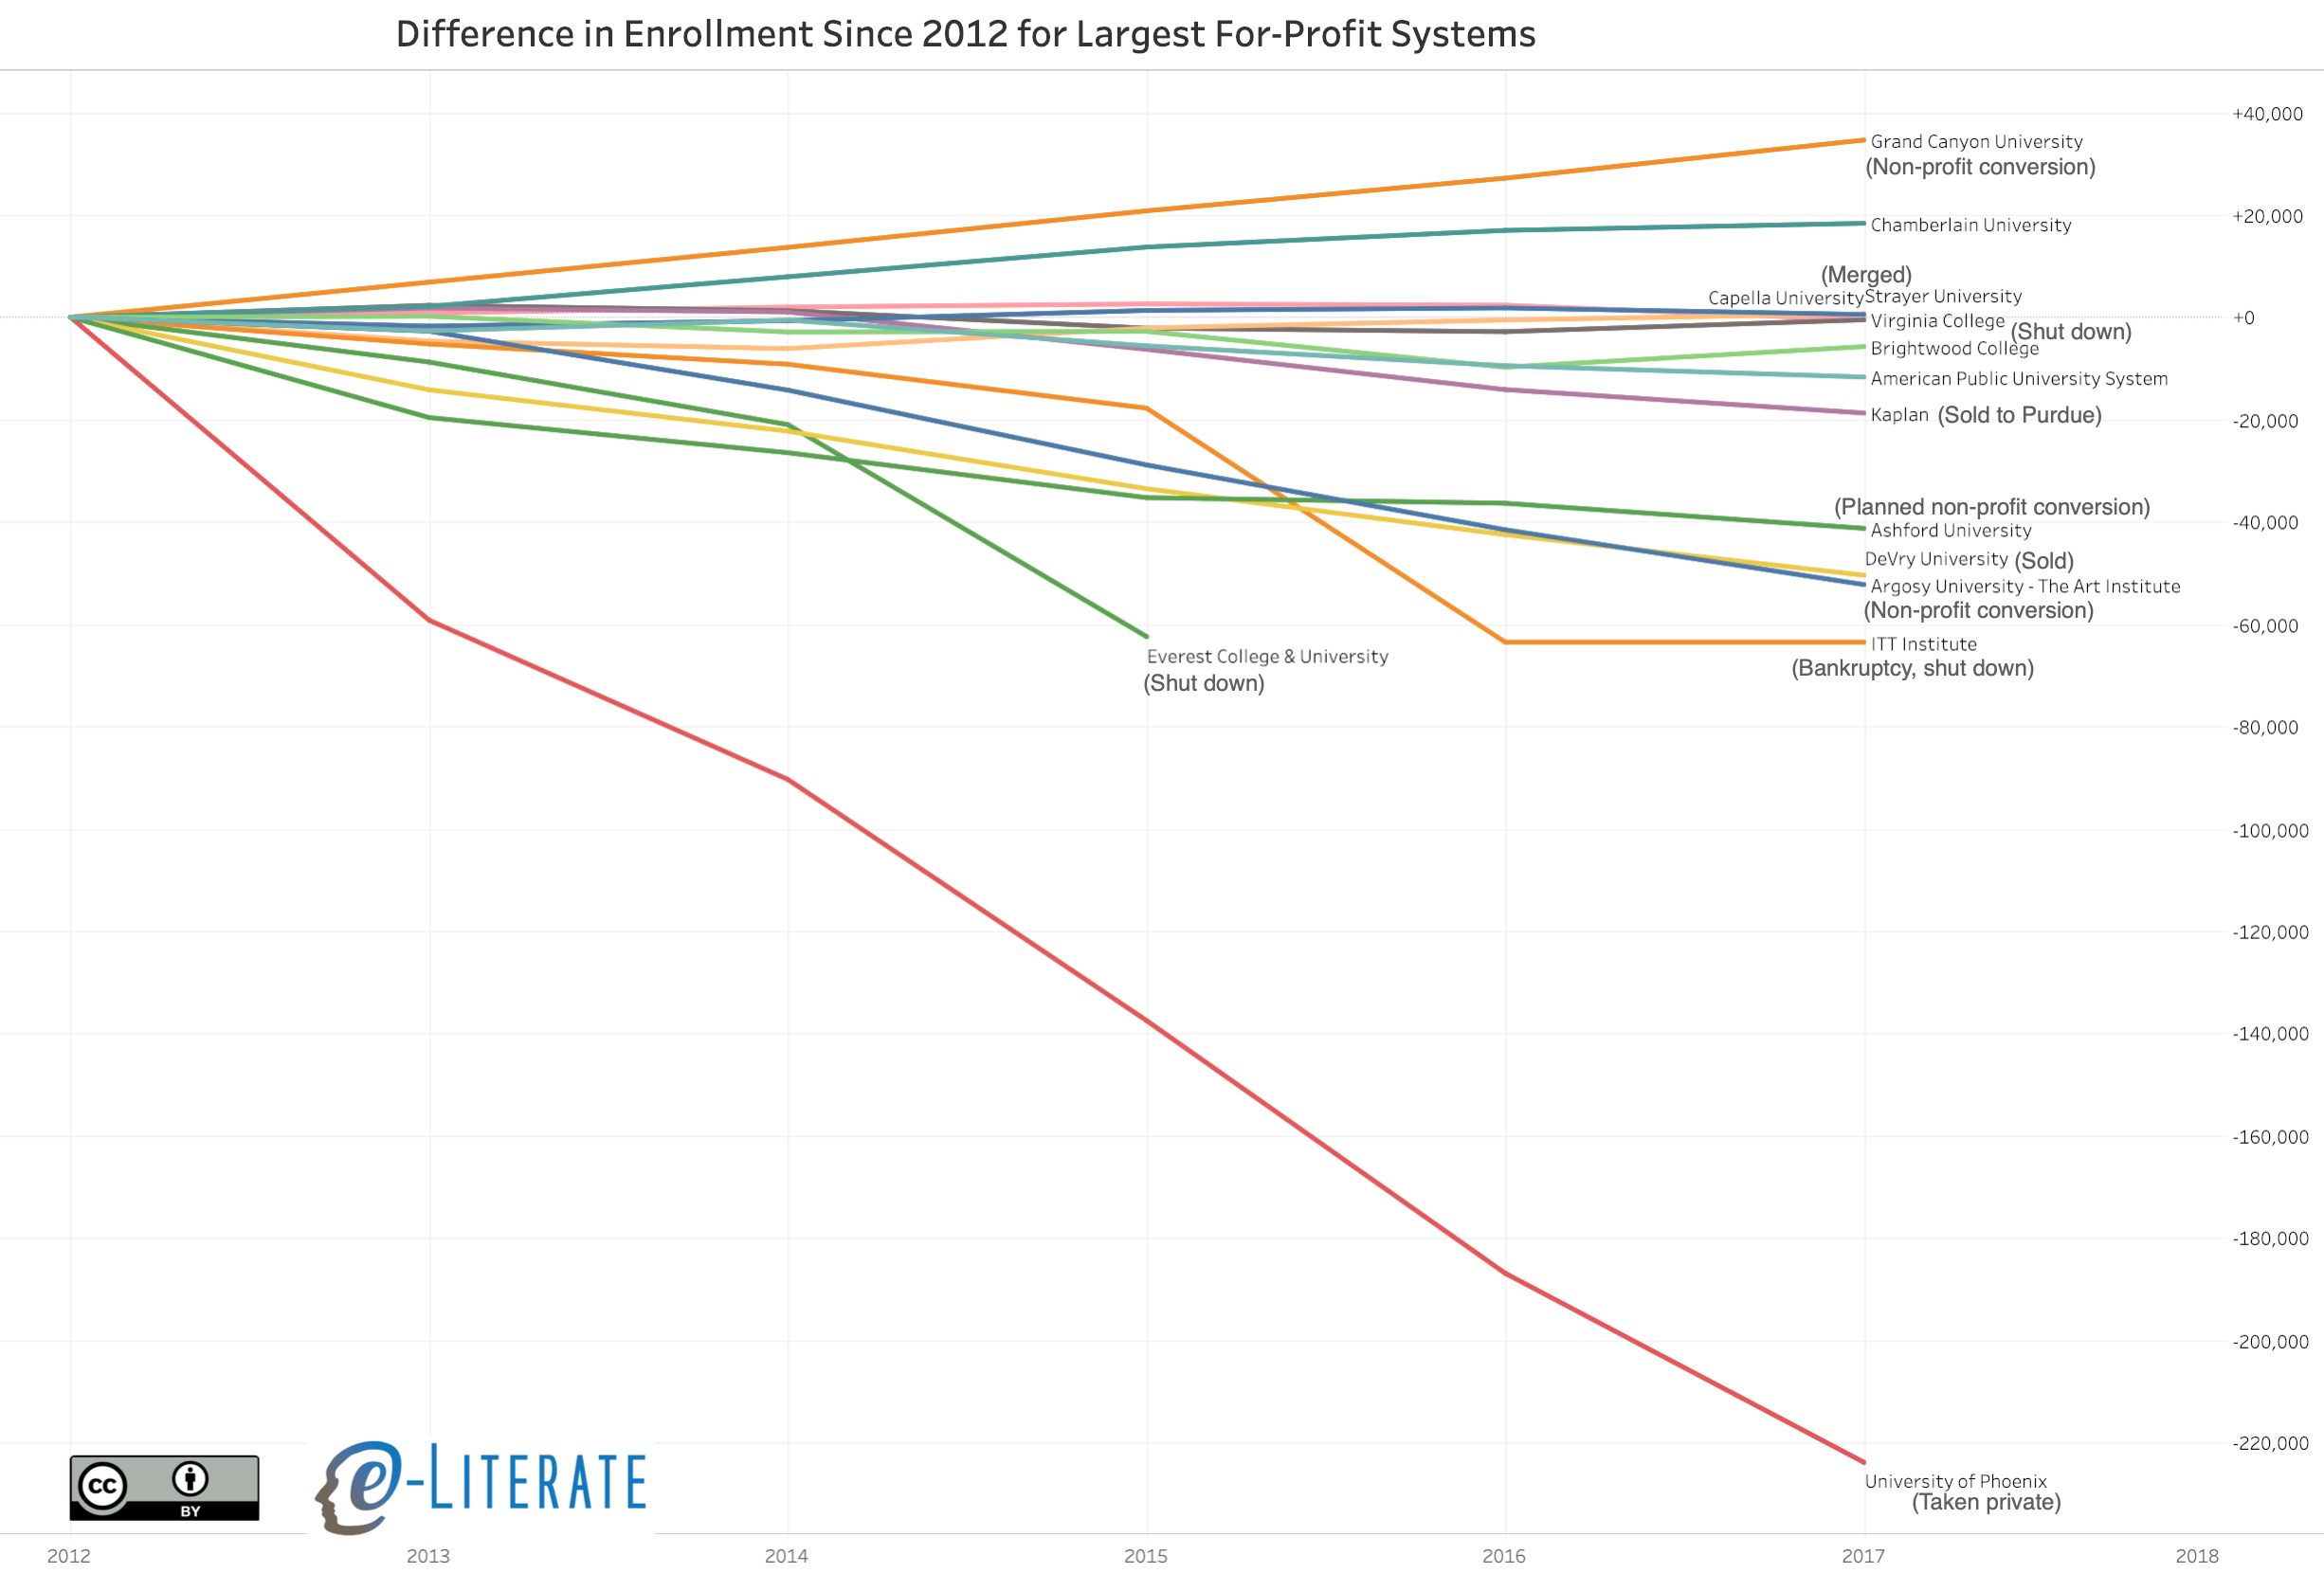
    Largest for-profits - changes from 2012

    Some notes:

    • To read the chart properly, note that Chamberlain University had almost 20,000 more students in Fall 2017 than they had in Fall 2012, while DeVry University had roughly 50,000 fewer students in that same time period;
    • Seen together, it is startling the extent of changes in ownership, control and status among these former high-flying for-profit systems;
    • The only significant growth for these large systems came from Grand Canyon University and Chamberlain;
    • The changes to Virginia College and Brightwood College are not that significant; and
    • By far the largest decrease in enrollment has been the University of Phoenix.

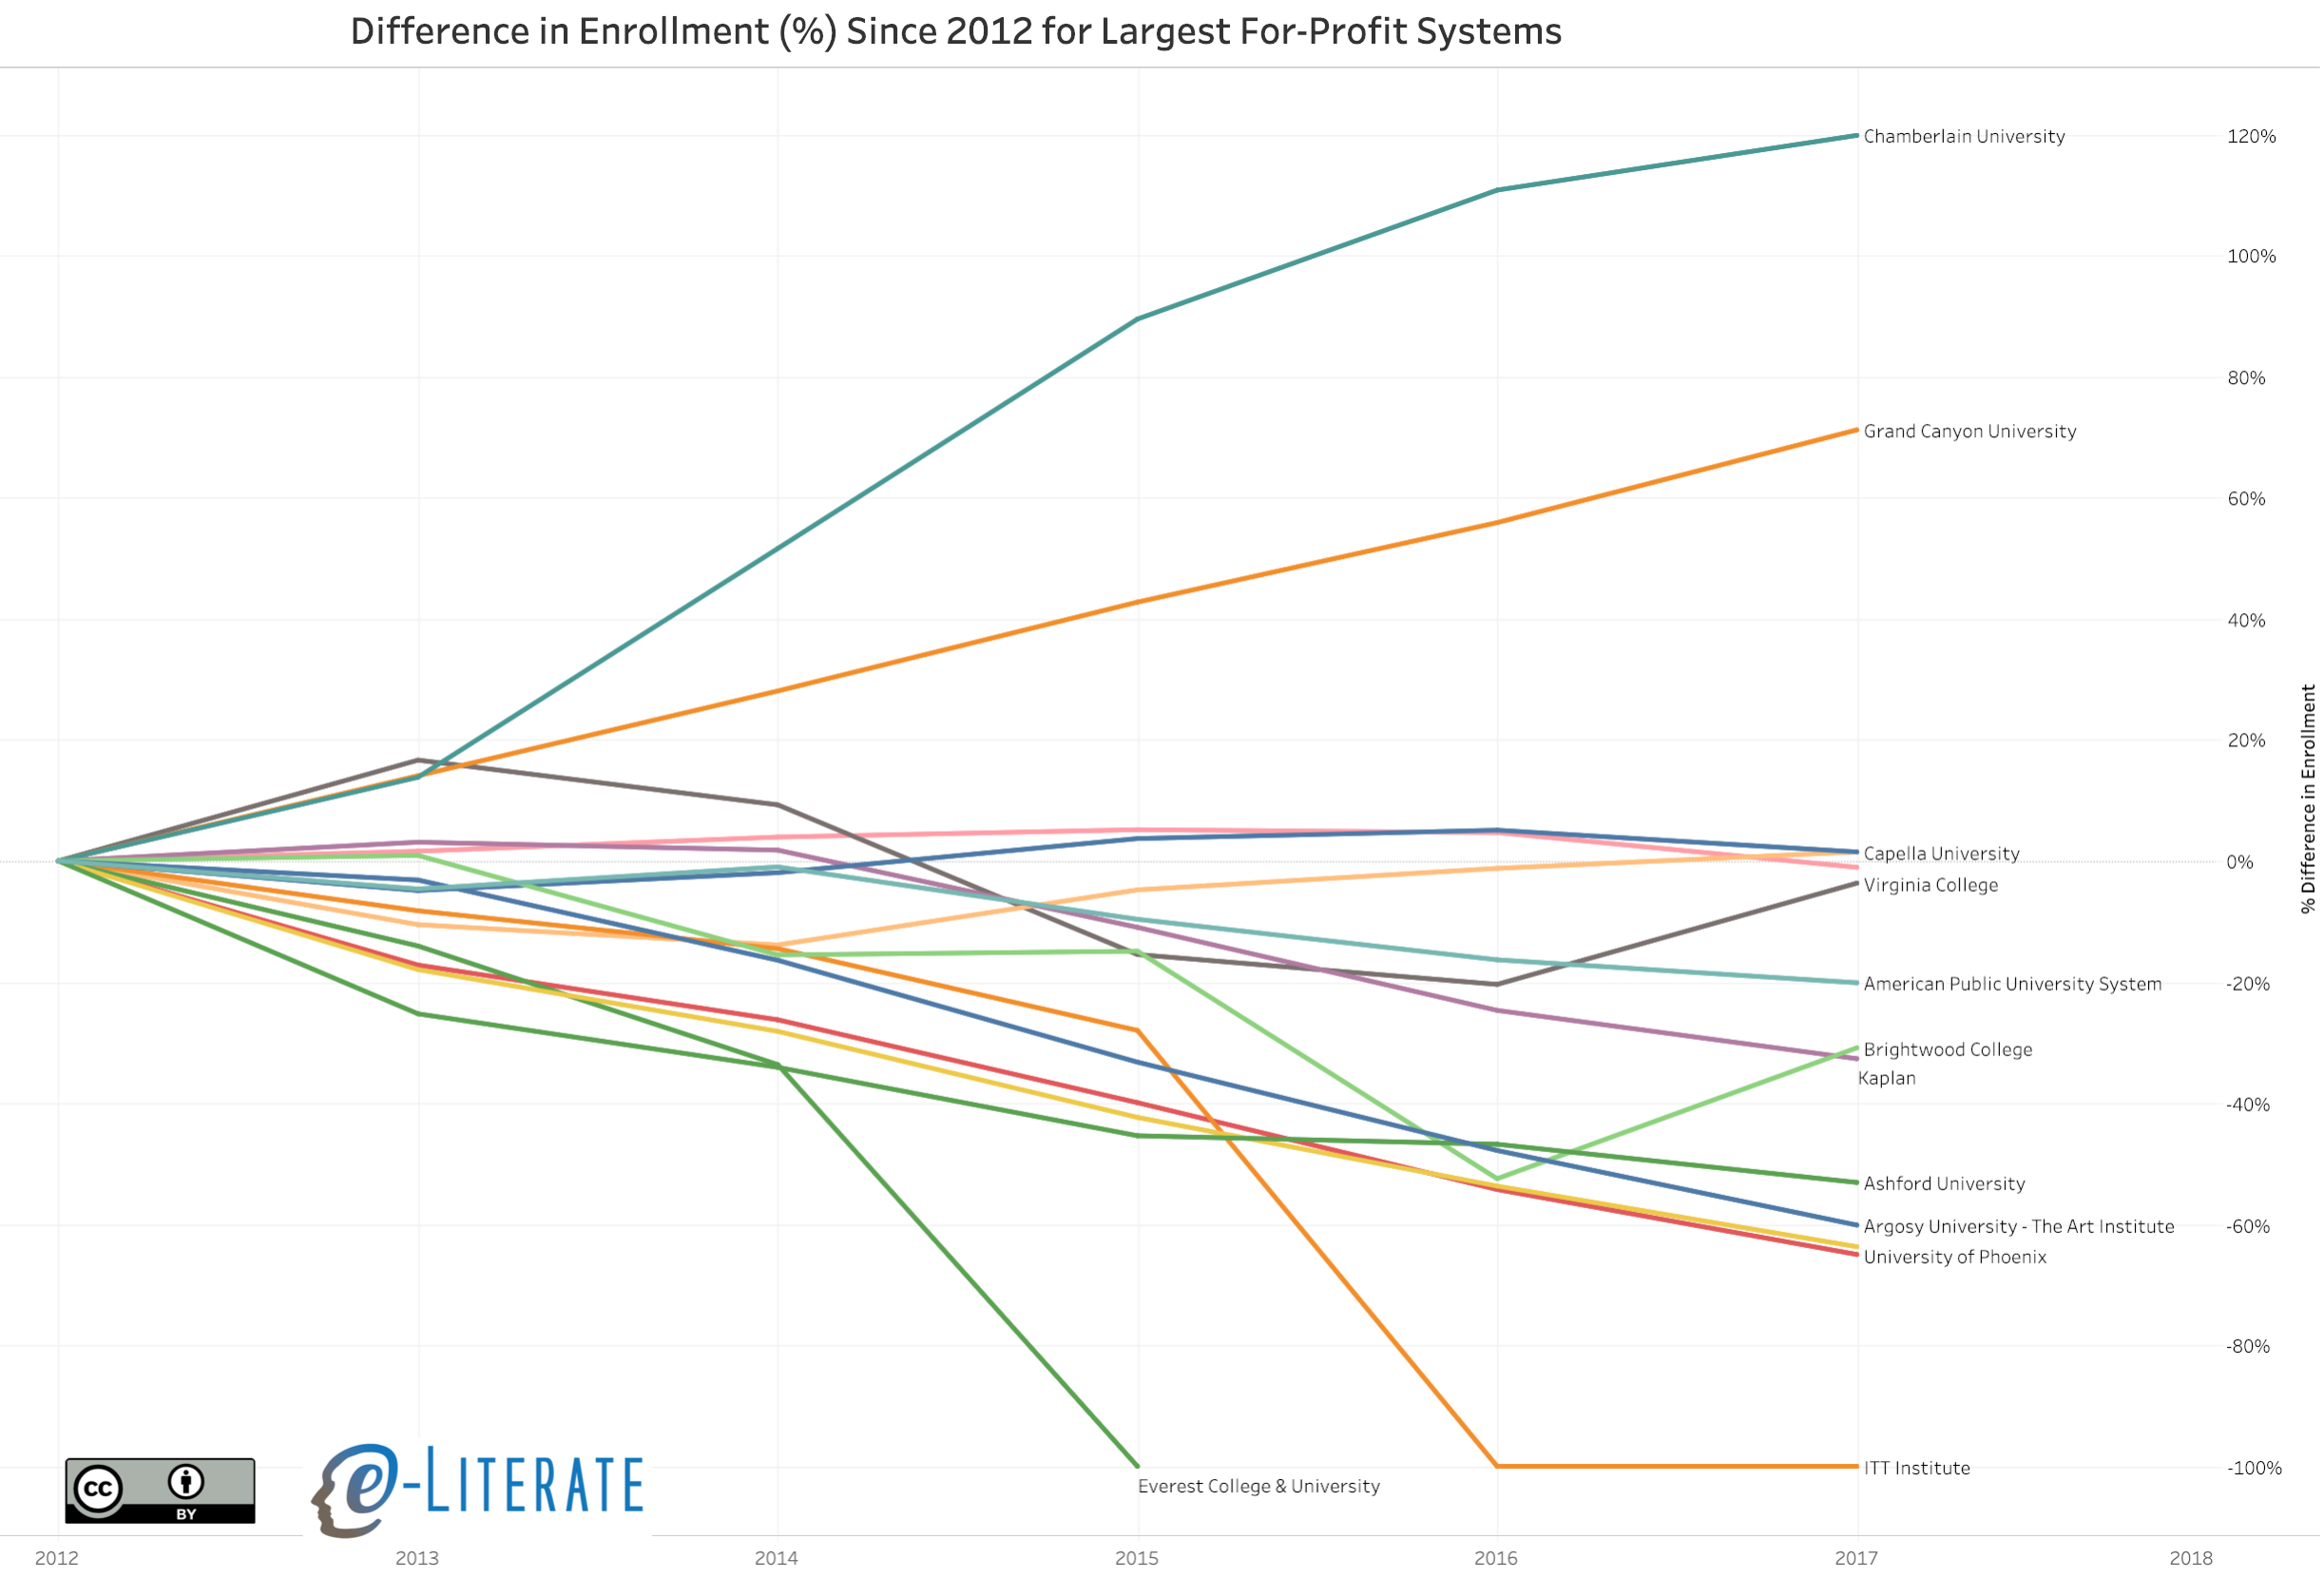
    While that view shows enrollment changes in total numbers, it is also useful to see relative changes for these same systems since 2012 to take into account the different enrollment sizes of the systems.
    Some notes:

    • To read the chart properly, note that Chamberlain University grew roughly 120% from Fall 2012 to Fall 2017, while DeVry University shrank more than 60% in that same time period;
    • In percentage terms, Chamberlain’s growth exceeds Grand Canyon University’s, which surprised me, but it seems to be leveling off;
    • Likewise, in percentage terms, DeVry University’s decline is roughly the same as the University of Phoenix’s;
    • Virginia College and Brightwood College actually grew from Fall 2016 – Fall 2017; and
    • We can see the shutdown of Corinthian Colleges (Everest) and ITT with 100% declines (ITT reported data in 2016 and 2017 even with no students).

    Let’s focus on just the four brands mentioned in last month’s stories – DeVry University & Chamberlain University for Adtalem, and Virginia College and Brightwood College for ECA.

    With this view, Adtalem’s strategy of selling DeVry while keeping Chamberlain makes a lot of sense, even if several years late and if they essentially gave away DeVry.

    ECA’s shut down, however, is not easily explained by the data. Unlike ITT and Everest, Virginia College and Brightwood College were not in enrollment free fall, and in fact there was instead recent enrollment gains getting them roughly back to 2012 levels. So why such an abrupt shutdown of ECA? The answer seems to lie with how the Department of Education and its accreditor handled recent troubles, based on IHE reporting.

    The shutdown follows years of declining enrollment for the chain. More recently, the privately held company scrambled to turn around its troubled finances by closing about a third of its campuses and pursuing a corporate overhaul through a court-approved receivership. But ECA continued to be dogged by creditors after falling behind on payments and rent for many campus locations. In October the company filed a lawsuit, which was later dismissed, against the U.S. Department of Education in an attempt to maintain its access to federal student aid.

    In an email to campus employees Wednesday morning, ECA CEO Stu Reed said that the Department of Education had added new restrictions on its access to Title IV student aid. And on Tuesday night, the Accrediting Council for Independent Colleges and Schools suspended the colleges’ accreditation. Those steps meant the company couldn’t secure the additional capital needed to operate its campuses, he said.

    I do not have enough knowledge to judge whether the ED should have shut off access to financial aid at the time that they did, but it does appear that students are paying the price despite signs that the schools were making significant enrollment gains. From the news coverage, there were significant outcomes issues beyond financial health of the parent company, but to my knowledge, this is a new situation among for-profit colleges in having a shut down despite very recent enrollment gains.

  • Grand Canyon Education Acquires Orbis: We have new segment of OPM market

    Grand Canyon Education Acquires Orbis: We have new segment of OPM market

    Nine months ago we wrote about the new movement for the companies formerly know as “for-profits” in the education space to convert the actual schools into non-profit entities and declare their intent for parent companies to become a new form of Online Program Management (OPM) providers. Kaplan University, Grand Canyon University, Ashford University (Bridgepoint Education) all made similar declarations, but the problem was that each one was a single-client OPM – serving only their supposedly independent non-profit schools. That’s not much of a new market segment.

    Today the movement became real as Grand Canyon Education announced their agreement to buy Orbis Education Services for more than $362 million.

    Grand Canyon Education, Inc. (NASDAQ: LOPE), a publicly traded shared services partner dedicated to serving colleges and universities, announced today that it has entered into a definitive agreement to acquire Orbis Education Services, LLC, an education services company that supports healthcare education programs for 17 regionally accredited universities across the United States (“Orbis Education”), for $362.5 million in cash. The transaction is expected to close during the first quarter of 2019, subject to customary closing and regulatory conditions.

    The acquisition combines the strengths of two of the nation’s most innovative service providers in higher education in an effort to align their expertise and better address a nationwide shortage in licensed healthcare professionals.

    “This is a natural extension of what Grand Canyon Education is already doing as an education services partner,” said Brian Mueller, GCE’s CEO. “We are very impressed with the quality of nursing and healthcare education that Orbis Education’s client institutions are providing. GCE can help grow that by providing investment capital and advanced technologies with behind-the-scenes support that will help University partners accomplish their goals and increase the number of licensed healthcare professionals they educate with the same high-quality outcomes.

    While they use the phrase “education services partner” instead of OPM, Grand Canyon in one move became a competitive provider worth watching. This news is significant.

    The large for-profit chains all developed scalable processes for the same functions that OPM vendors provide for non-profit schools – marketing & recruitment, course & curriculum development, technology platform & data analysis, and student support & retention services – and the basic idea of this market change is for the for-profit parent companies to provide these same services for other non-profit schools. With the Orbis acquisition, Grand Canyon will pick up 17 partner institutions.

    Orbis Education is a niche-market full-service OPM provider serving pre-licensure healthcare programs (mostly nursing) and was founded in 2003. Parter institutions include Concordia University, Northeastern University, Marquette University and Mercer University.

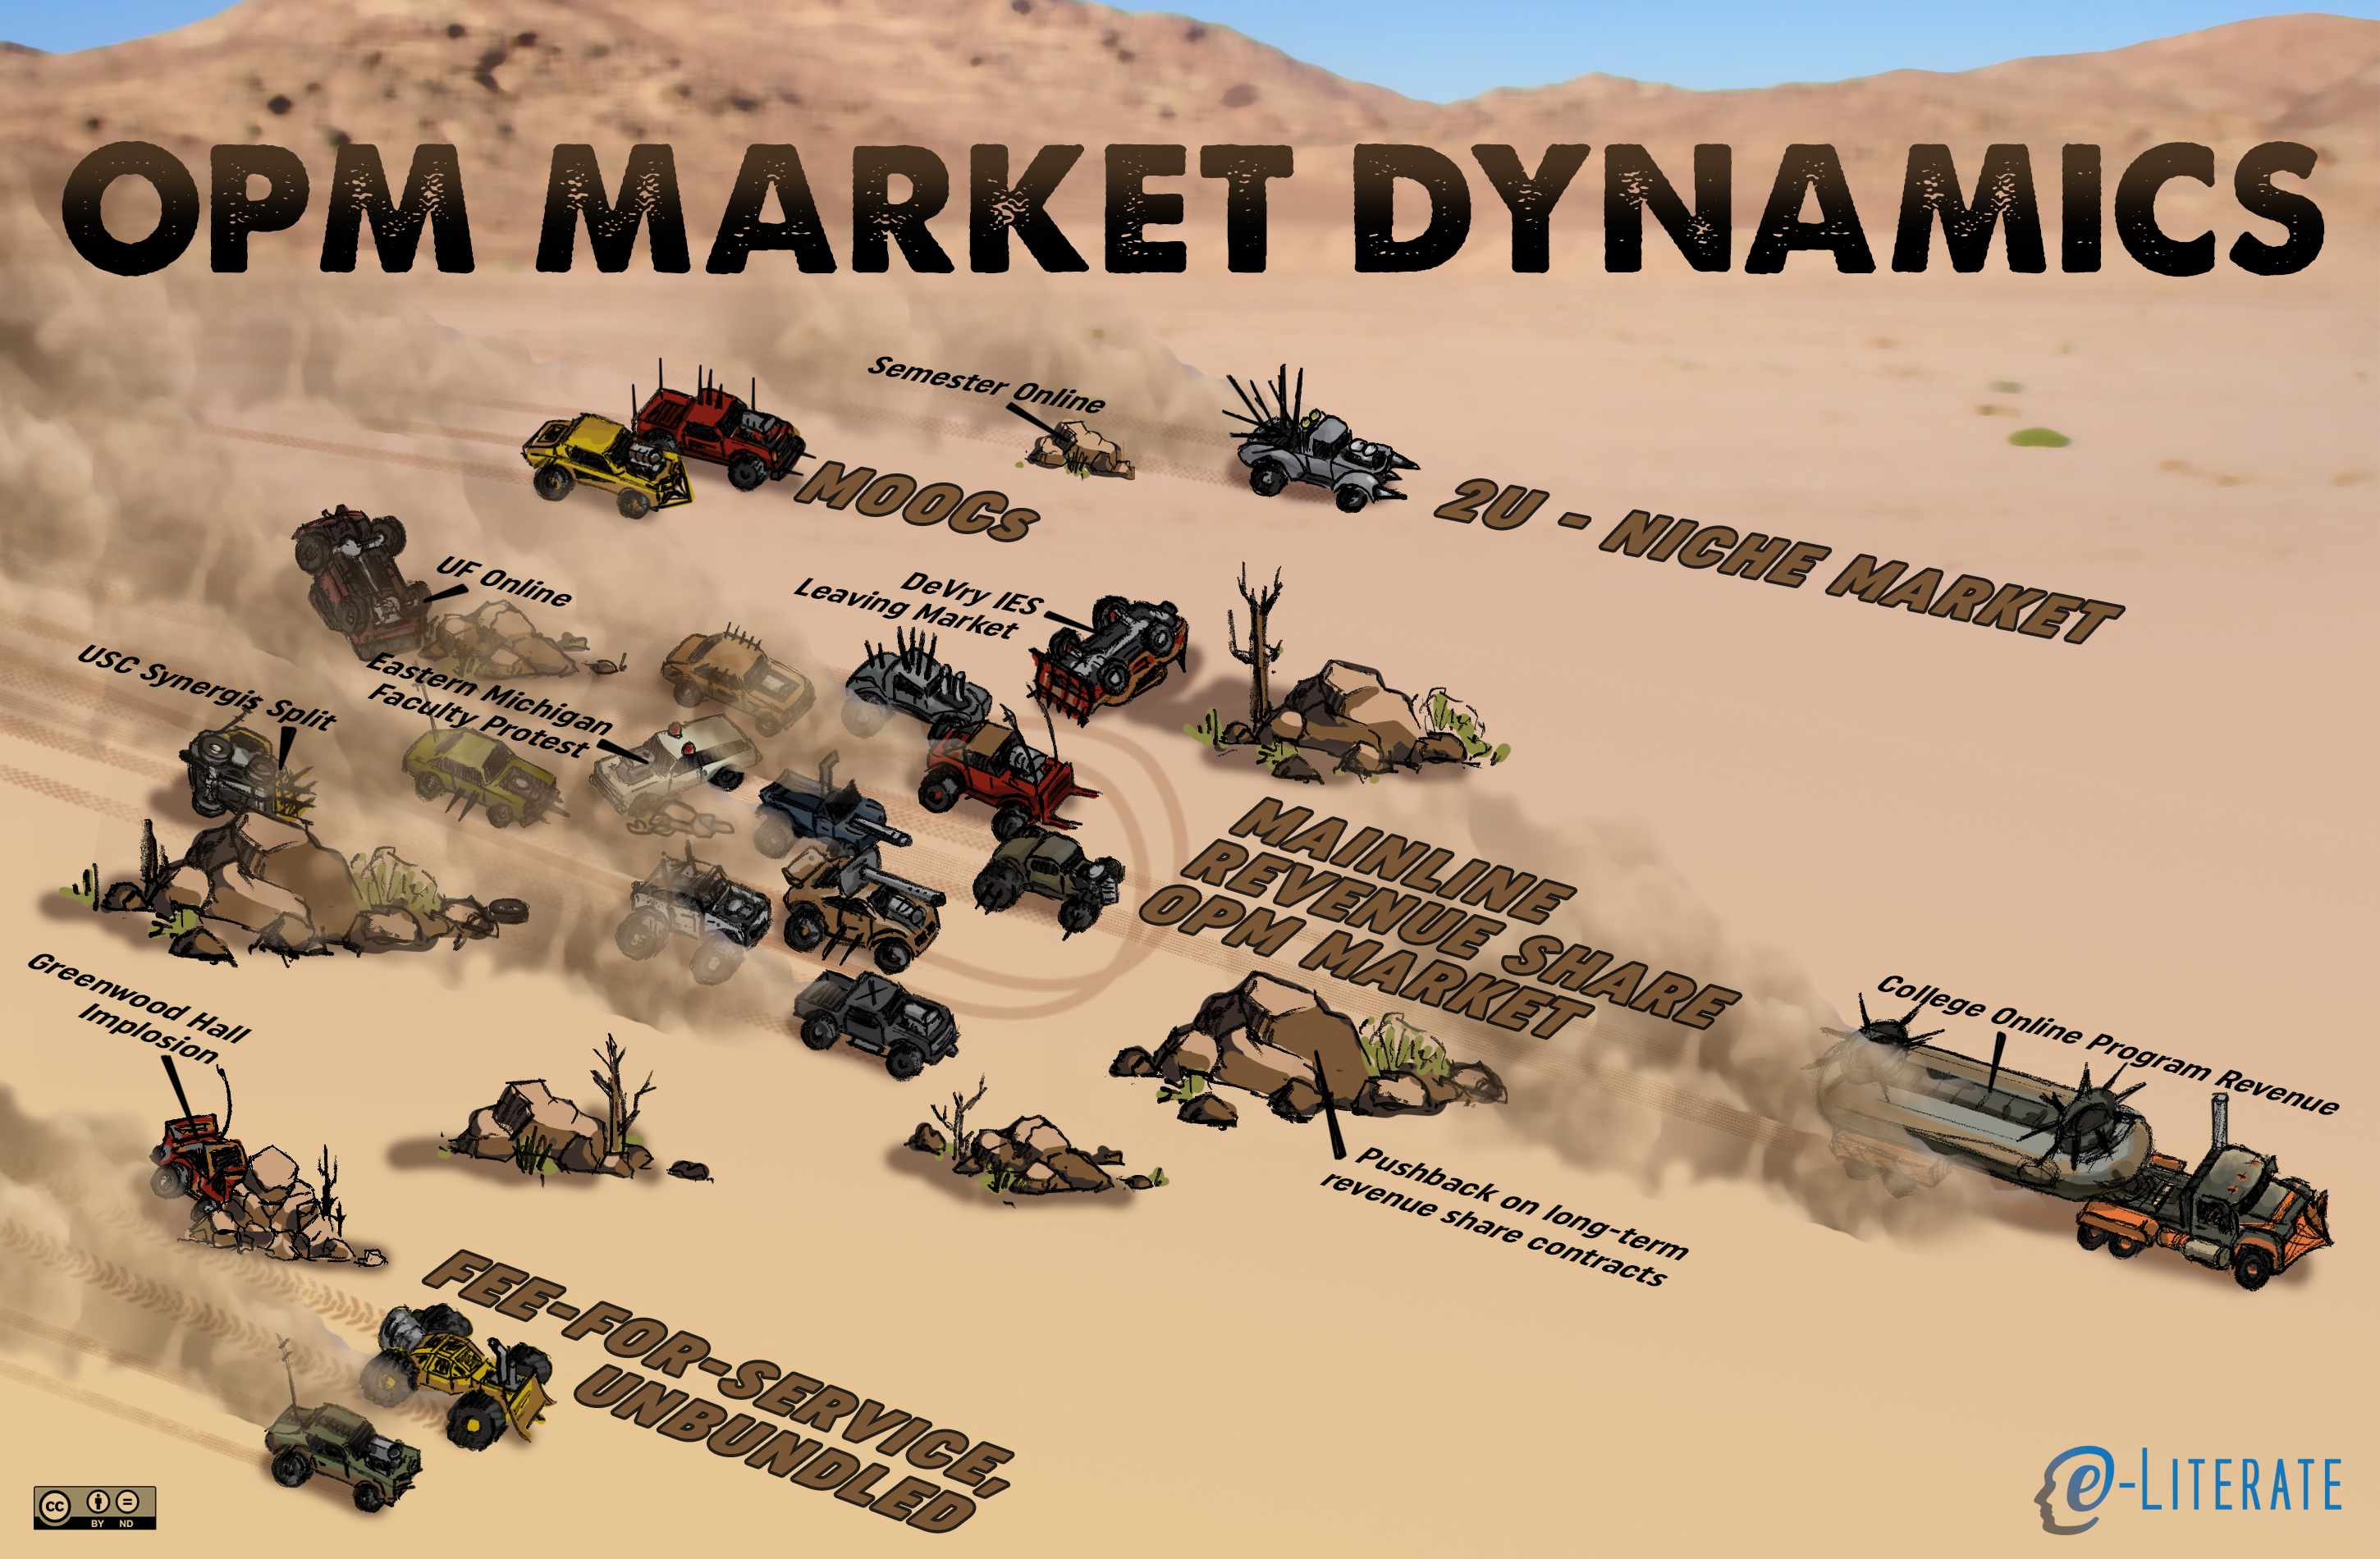
    In a broader sense, this acquisition follows the Wiley acquisition of Learning House for $200 million announced this fall. We’ll need to update our graphics, but the OPM market is profitable and growing, but it is also messy and chaotic. OPM vendors are in a battle to have the financial strength and customer scale to survive the chaos and grow in an expensive model.

    For those keeping track, Pearson paid $650 million for EmbanetCompass in 2012, and Wiley paid $220 million for Deltak, also in 2012. Hmm, something about that year . . .

    We’ll follow this story and others like it while sharing information on the likely impacts on the overall OPM market. For now the biggest issue is establishing that this for-profit-turned-OPM segment is real.

  • Fall 2017 Top 30 Largest Online Enrollments In US – With LMS Usage and Trends Since 2012

    Fall 2017 Top 30 Largest Online Enrollments In US – With LMS Usage and Trends Since 2012

    The National Center for Educational Statistics (NCES) and its Integrated Postsecondary Education Data System (IPEDS) provide the most official data on colleges and universities in the United States. This is the sixth year of data on distance education enrollments, and we have an opportunity to view trends over time.

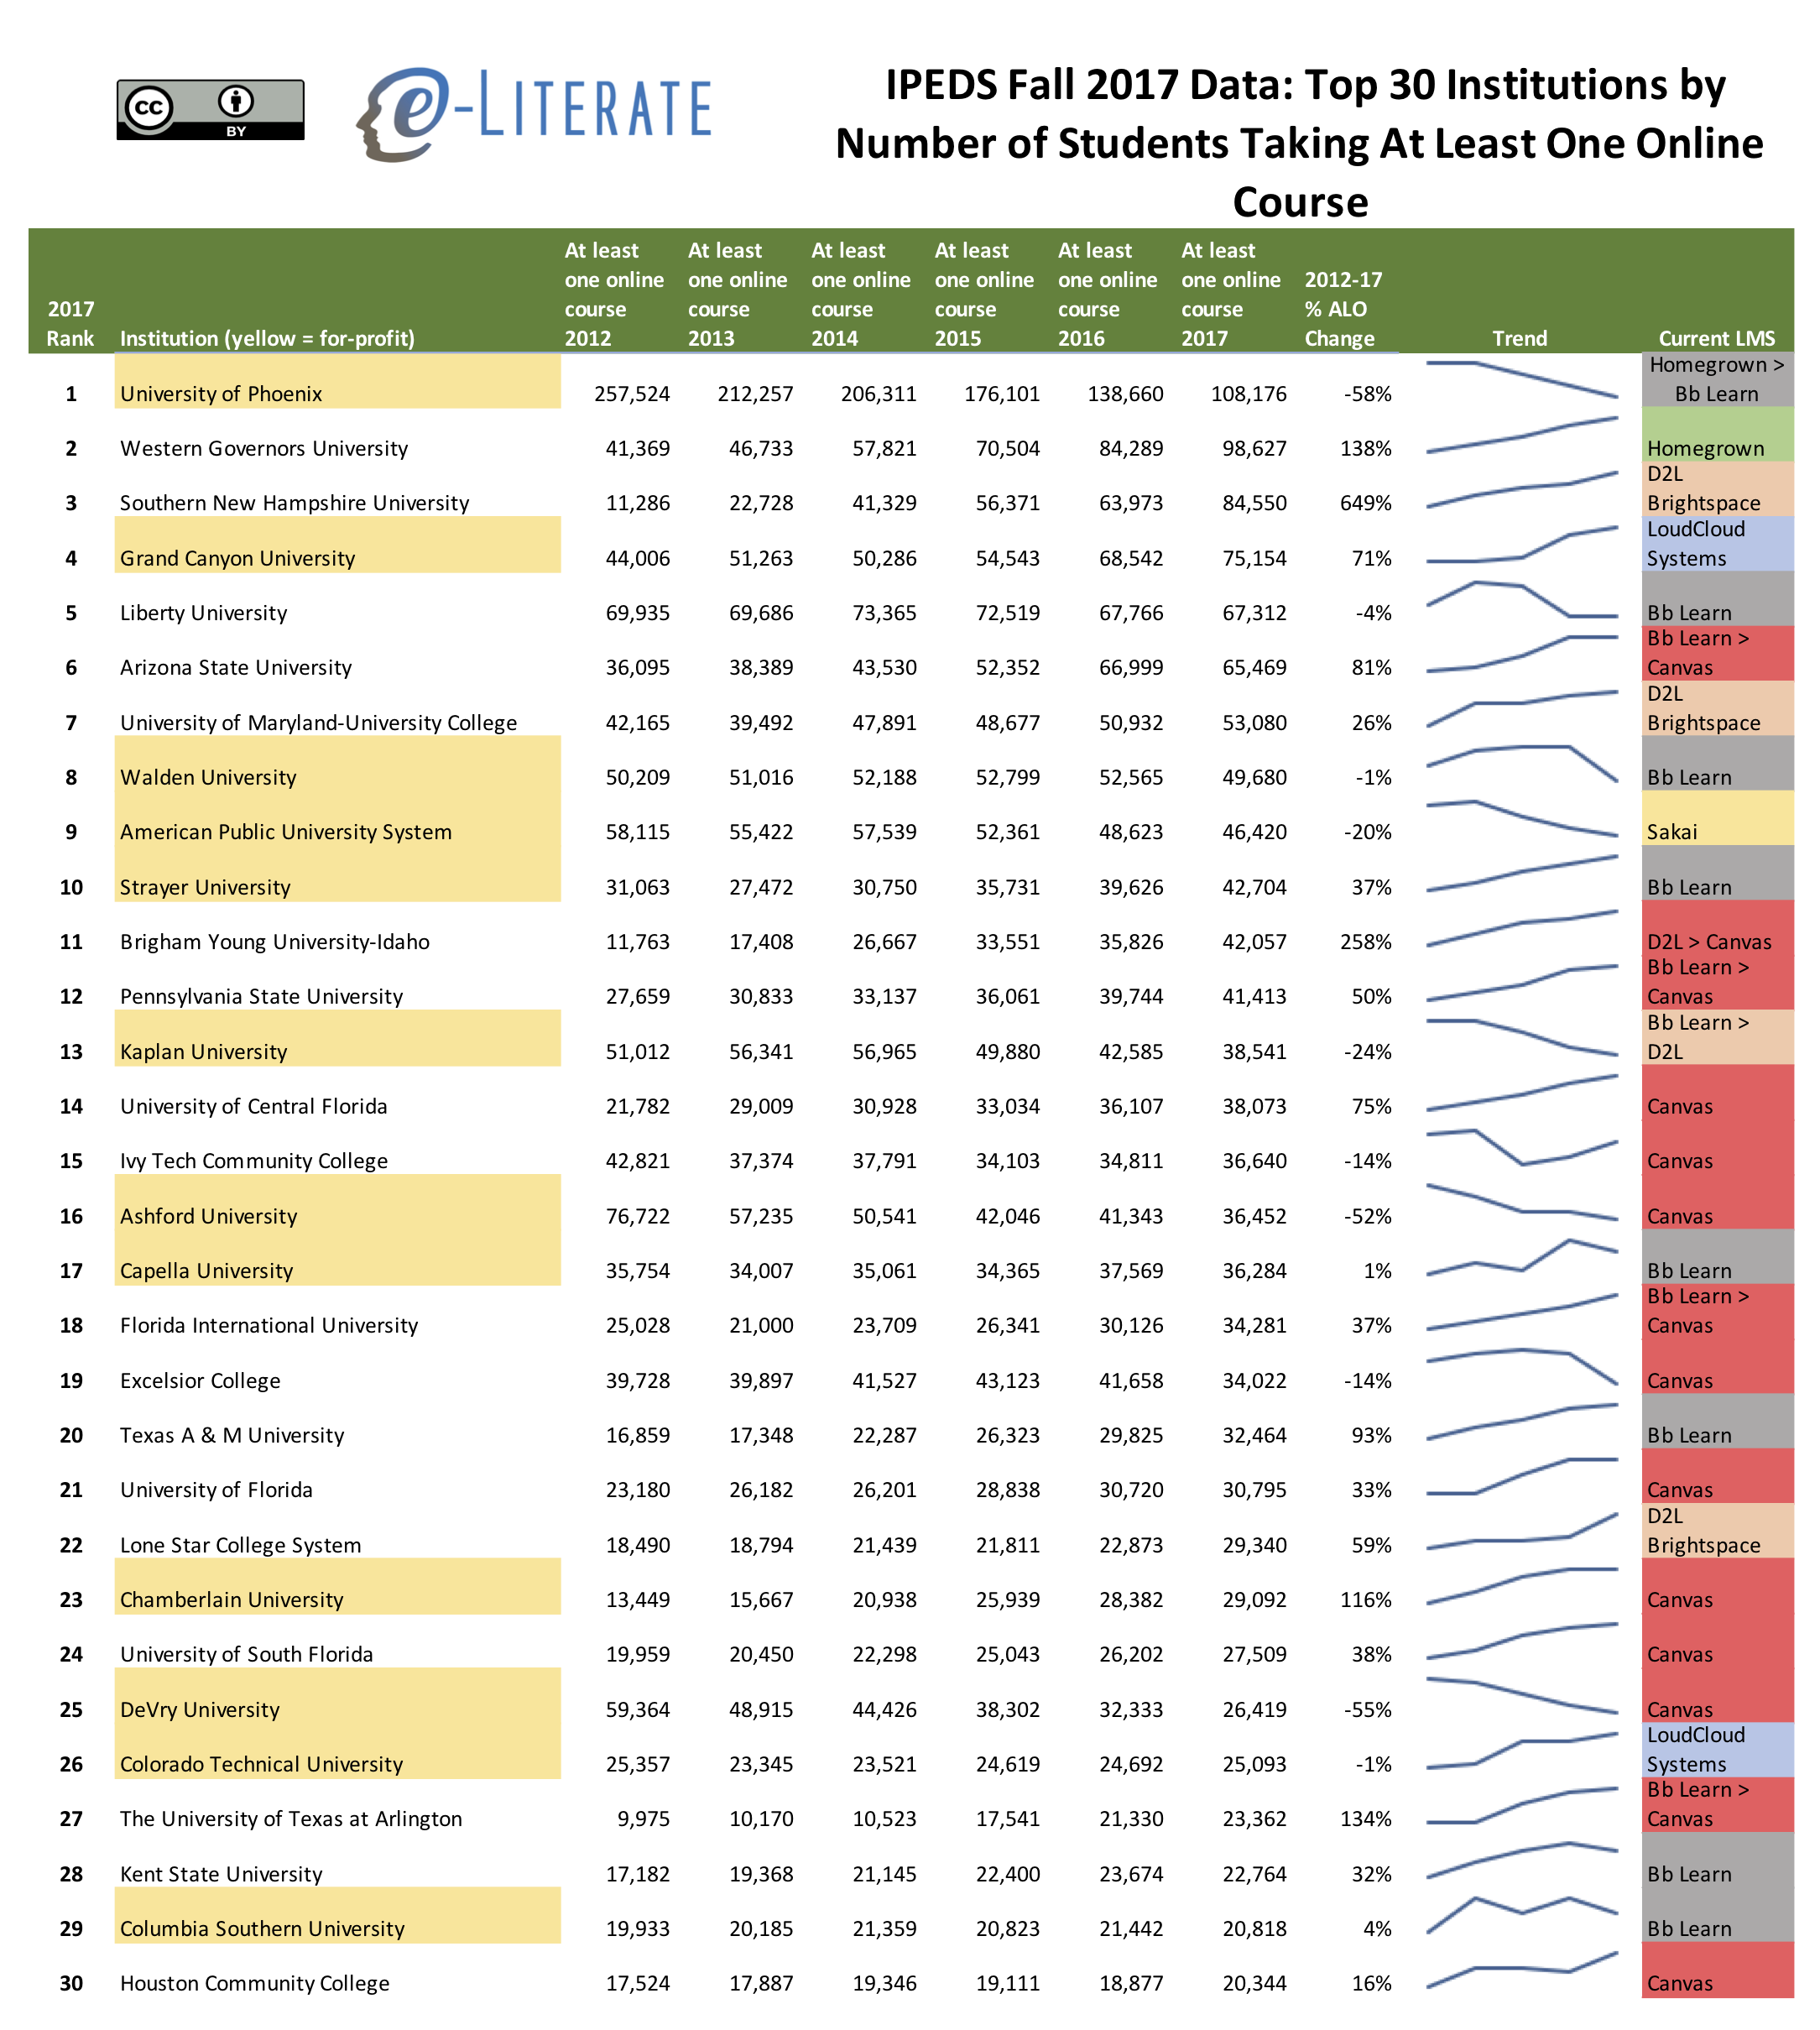
    Let’s look at the top 30 online programs for Fall 2017 (in terms of total number of students taking at least one online course for grad and undergrad levels combined) in the US. Some notes on the data:

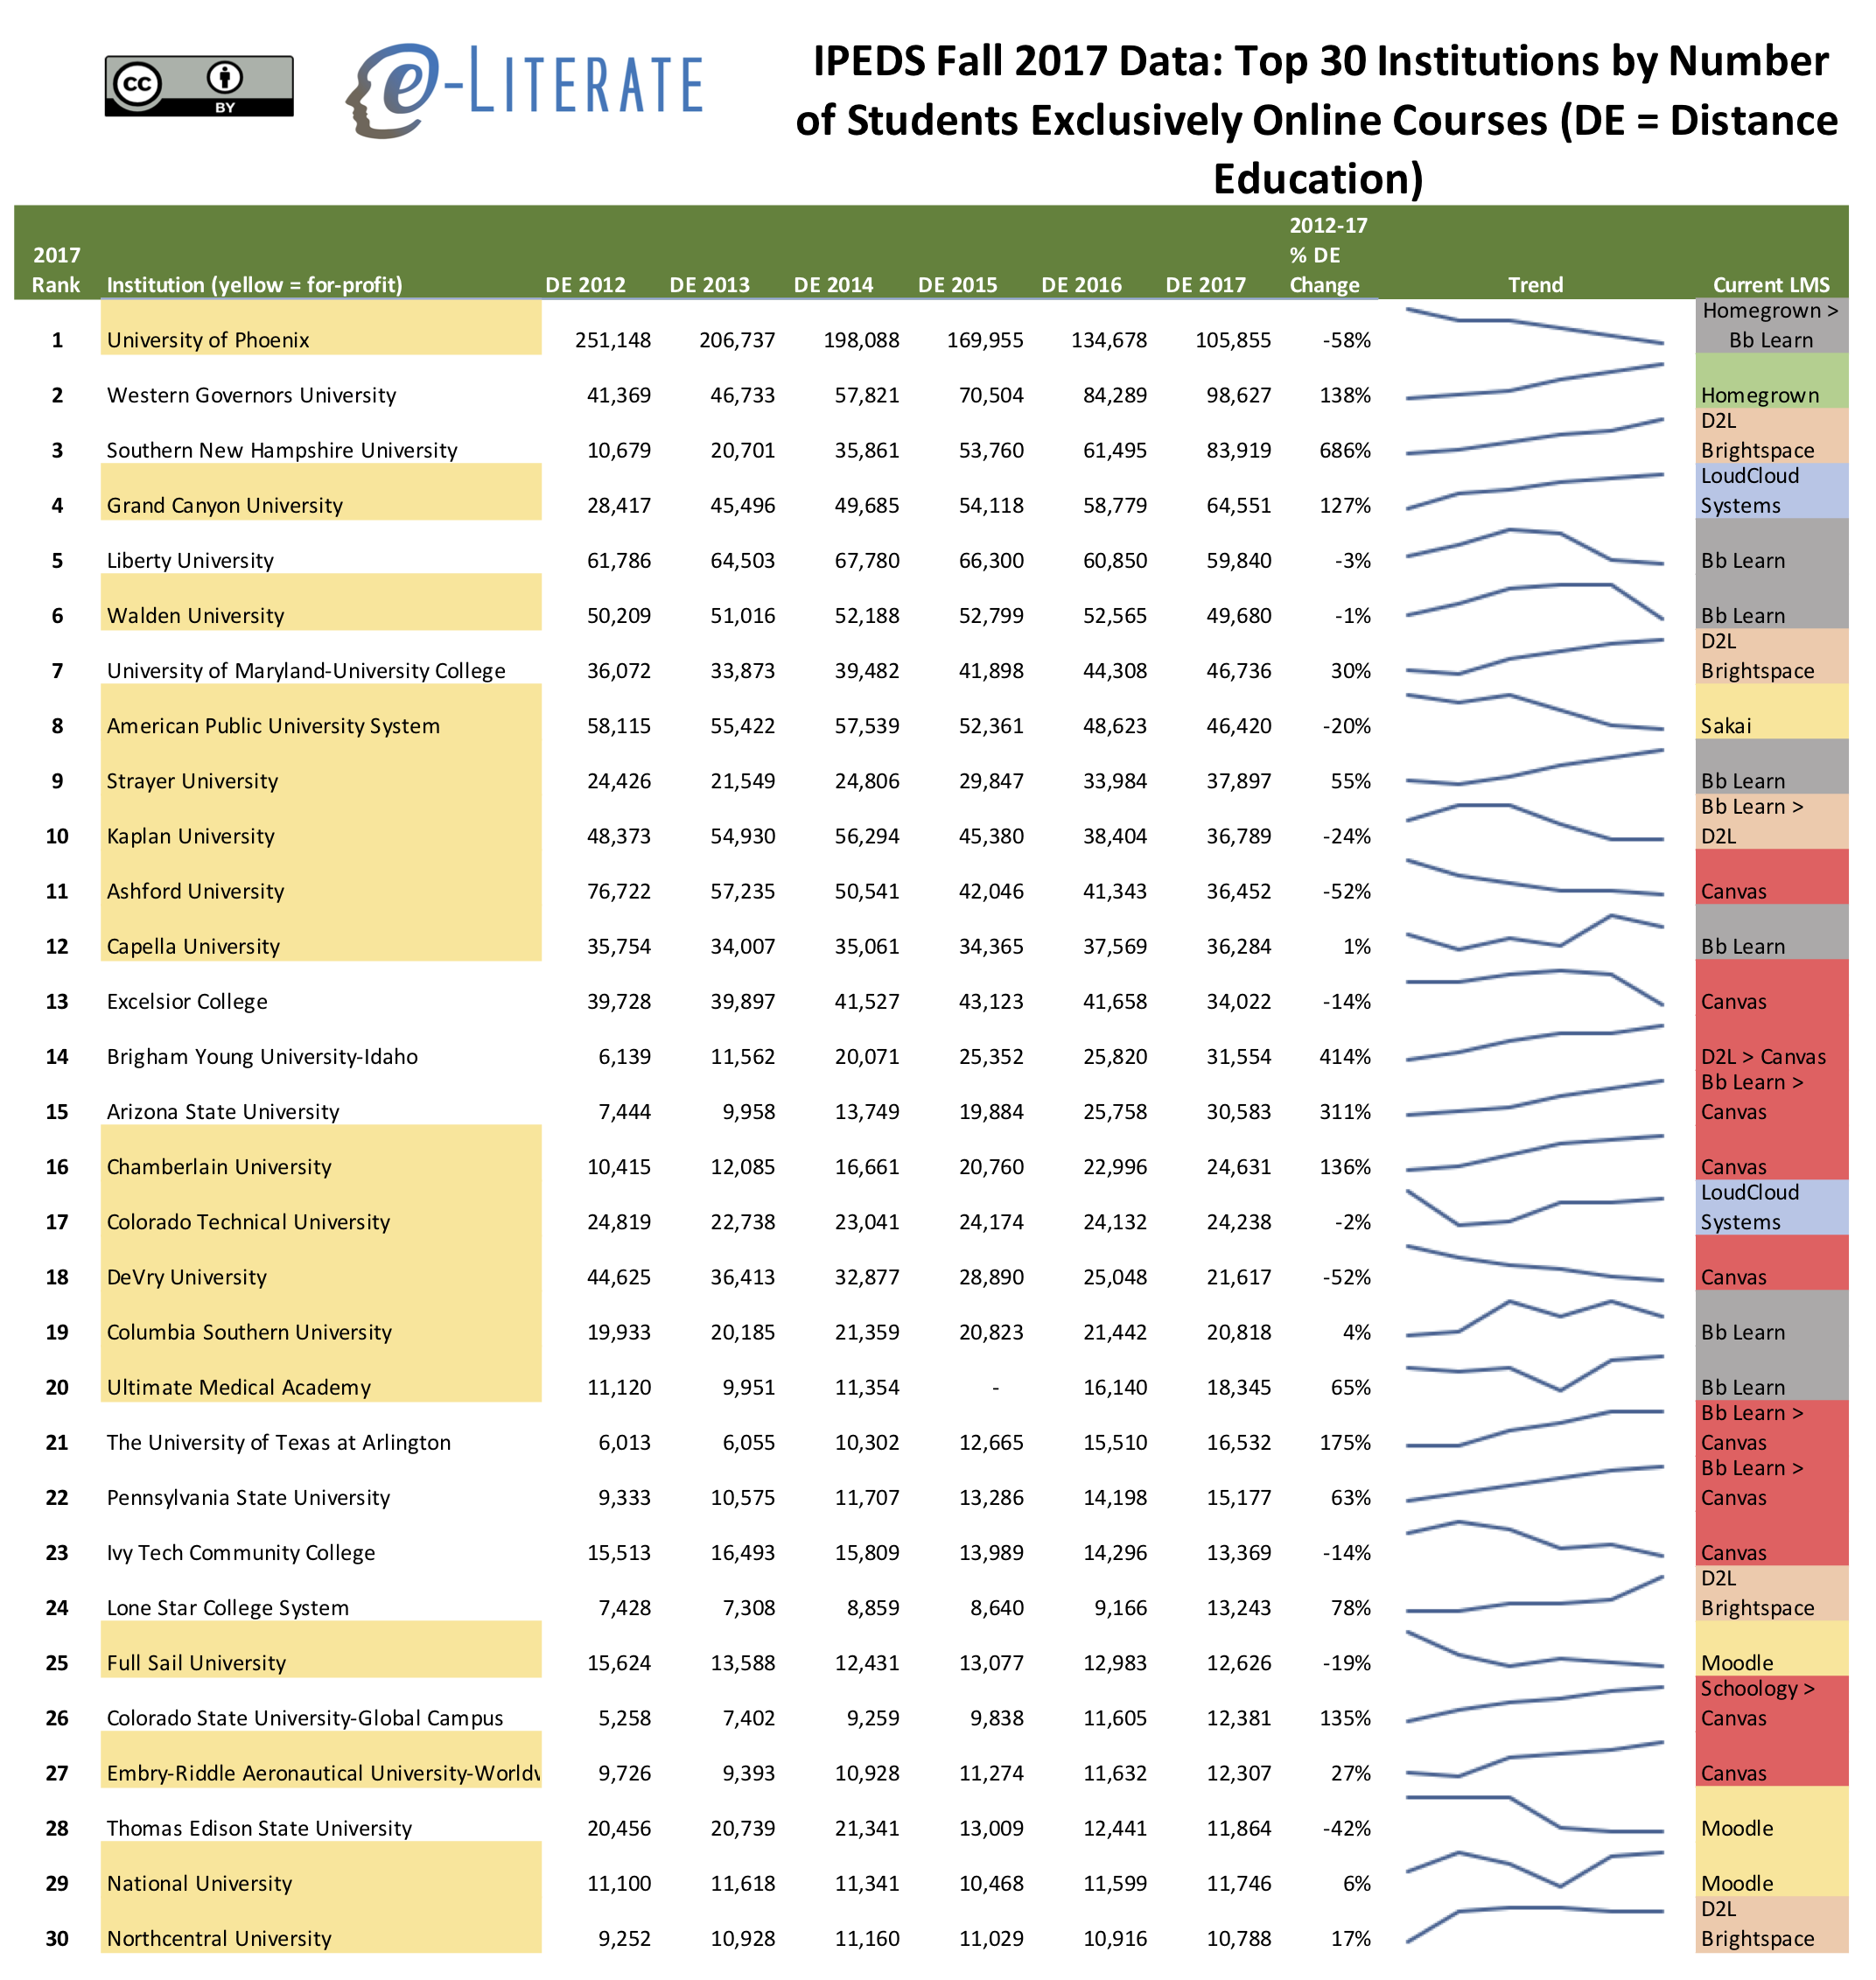
    • The first view combines the categories ‘students exclusively taking distance education courses’ and ‘students taking some but not all distance education courses’ to obtain the ‘at least one online course’ category; the second view shows just the ‘students exclusively taking distance education courses’.
    • Note that IPEDS captures distance education enrollment data based on Fall 20xx reports using a census date of October 15; this approach does not fully capture programs with multiple start dates throughout the year.
    • IPEDS tracks data based on the accredited body, which can differ for systems – this data has combined most for-profit systems into one institution entity as well as Arizona State University and a handful of not-for-profit systems that operate as one entity.
    • There is a new column this year showing changes in enrollment in each case between Fall 2012 and Fall 2017 data.
    • Both views highlight for-profit institutions in yellow and added sparklines to help visualize trends. There has been a wave of for-profits converting in one form or another of not-for-profit institutions (e.g. Grand Canyon University, Kaplan / Purdue Global), but these conversions for the most part had not taken place as of the Fall 2017 reporting period.
    • There is another new column this year showing which LMS is currently in usage at each of the schools listed, and in cases where there is a transition in 2018, both systems are shown with a direction > sign.
    • See this post for Fall 2017 profile by sector and state.

    Largest 30 online enrollments in US

    Looking at the case where students exclusively take online courses in a distance education (DE) mode, we see some differences in the list with a greater concentration of for-profit schools.

    Top 30 distance ed institutions

    Finally, it’s worth looking at the top 30 trend over time. Obviously the University of Phoenix is no longer the 800 pound gorilla in distance education, with two not-for-profits – Western Governors University and Southern New Hampshire University – poised to overtake Phoenix in the next year or two. This view also shows the tendency for most institutions to top out at approximately 60,000 students, but this may be changing with the three counter-examples above as well as Grand Canyon University.

    IPEDS Top 30 trend 2012-17

    Based on a reader request, I have added a Google Sheet for the data used above. There are tabs for Top 200 and Top 30 listings for each category (ALO and DE), but the LMS data was added manually and only available in Top 30.

    Update 11/26: Fixed mistake in 2012-17% calculations, updated first two images. Added downloadable Google Sheet for data access.

  • If At First You Don’t Succeed, Try To Be An OPM: Conversion of for-profits and MOOCs

    If At First You Don’t Succeed, Try To Be An OPM: Conversion of for-profits and MOOCs

    Two weeks into March, this has already been a busy month already for the transformation of for-profits and MOOCs. For-profit universities are in a race to become nonprofit by separating academic programs from behind-the-scenes services, and MOOCs are focused primarily on monetization and moving beyond free and open courses. The common thread tying these messy transitions together is the move to become new forms of Online Program Management (OPM) providers.

    Best Way to Make Money? Go Nonprofit

    Arguably the biggest news was March 5th when the Higher Learning Commission (HLC), the regional accreditor, approved the Kaplan University / Purdue University deal to create Purdue Global. This was the final approval step as Purdue acquires Kaplan, leaving Kaplan University, leaving Graham Holdings (Kaplan’s parent company) to serve as a single-client OPM provider.

    The following day Grand Canyon University announced that it had received approval from HLC to convert into a nonprofit institution. As described in their press release, the remaining for-profit company will become an OPM, even if they choose not to use that name [emphasis added]:

    As part of the transition, GCE will sell certain academic-related assets to a non-profit entity that will carry the Grand Canyon University name. Following the sale, GCE will operate as a third-party provider of educational and related services to GCU and potentially, in the future, to other universities. The structure is similar to that at hundreds of non-profit universities in the country that outsource services to third-party providers.

    And yesterday, Bridgepoint Education announced that they were formally seeking to convert Ashford University into a nonprofit in a similar deal as Grand Canyon. At least they are more direct about the OPM tie-in as described at Inside Higher Ed yesterday.

    Bridgepoint will continue on as an online program management (OPM) provider — a booming space in higher education. The company will negotiate with Ashford to enter into a shared services agreement, with Bridgepoint likely handling data management, course management software and services, technology, and financial aid processing for the nonprofit university.

    “As an OPM, Bridgepoint Education will bring years of technological and academic innovation and intellectual property development to other colleges and universities that desire to serve students through online education programs,” Schray said in a written statement.

    In an interview here at e-Literate when Purdue and Kaplan announced their acquisition plans last April, Trace Urdan (now at Tyton Partners) described the market forces involved in some of these moves.

    • Non-profit entities – both public institutions and private non-profit institutions – “wanting to get into the adult market and the online market”. This is the big push behind the Online Program Management (OPM) market, kick-starting these non-profits into online programs targeting adult education.
    • For-profit entities “feel like they are being burdened by being for-profit”. One part of this is the regulatory burden from the Department of Education and even accreditors. But there is also a marketplace burden as non-profits like Southern New Hampshire University keep growing enrollments while for-profits are dropping.
    • There is a “the investor enthusiasm for the services model” with OPMS, “and this is a model that investors love – it gives you access to the growth in online education, affiliation with strong brands, and it’s more or less free from the regulatory hostility” of the for-profit sector.

    Beyond the market forces, however, there is another underlying factor affecting these moves. As described by legal team at Cooley Education:

    So, why did this happen? First, and most obviously, we are in a different regulatory environment – at least as far as the federal Department of Education is concerned. In late 2017, the Department of Education dropped its opposition to for-profit conversions vehemently articulated by then-Secretary John King, most recently approving the sale of South and Argosy Universities and the Art Institutes owned by Education Management Corporation to a nonprofit created by the Dream Center Foundation. This change in federal policy shifted the emphasis on approvals back to the accreditors and the states.

    At the accreditor level, the politics may be less important in understanding the outcome than the process. At about the same time that Kaplan-Purdue was first announced, HLC began working on revising its policies and procedures to establish new benchmarks by which such transactions would be measured. HLC made two significant changes: it updated its procedures for review of Change of Control transactions and, in a politically astute move, also established a policy that Department of Education approval must be obtained before HLC acts on a change of control application, thus insulating itself from second-guessing in Washington. (HLC’s change was telegraphed in late 2016 when it deferred acting on the sale of the parent of the University of Phoenix to a private equity group pending prior ED approval.)

    Significantly, HLC now has relatively clear guidance governing what is needed for OPM relationships and for-profit conversions.

    How Do We Make Money? The Answer Is Simple – Volume

    Meanwhile Coursera announced their plans to further focus on the monetization of supporting online degrees, as described at EdSurge on March 5th.

    These days, though, many MOOC platforms are courting the traditional higher-ed market they once rebuked, often by hosting fully-online masters degrees for colleges and universities. And today, one of the largest MOOC providers, Coursera, announced it’s going one step further in that direction, with its first fully online bachelor’s degree.

    Coursera is not alone here – most notably Georgia Tech and Udacity launched an online master’s of computer science in 2013. In a related move, edX has begun its work supporting online master’s degrees through its MicroMasters program, and FutureLearn – spun out of the Open University of the UK – supports multiple degree programs.

    While the Coursera news focused on the new bachelor’s program, the bigger news was the expansion its graduate programs as described at Inside Higher Ed.

    Online education platform Coursera has set a goal of offering 15 to 20 degree programs by the end of 2019. The company took another step toward that goal Wednesday, announcing new degree offerings from the University of Illinois at Urbana-Champaign and France’s HEC Paris.

    “This is our coming-out party for online degrees on Coursera,” Nikhil Sinha, Coursera’s chief business officer, said in an interview.

    FutureLearn announced their own expansion of online degrees last month.

    For the MOOC providers, their move into the OPM space seems to be driven by their leverage of current registered learners as a marketing channel, as described in a separate IHE article.

    Roughly half of the students in Coursera’s current degree programs took one of the open online courses first, essentially enabling students to “try these degrees before they buy them,” Maggioncalda says. So not only do students have a chance to see how they like a professor, or how well they perform, before enrolling in the for-credit program, but Coursera also asserts that it can drive down the cost of acquisition of students by tapping into its 31 million users.

    Coursera’s institutional partners “share a certain percentage of the learner fee with us in exchange for distribution to our world of learners, and the whole delivery of the system on our platform,” Maggioncalda says.

    New OPM Models

    Two years ago we described how the OPM market has evolved beyond its full-service tuition revenue-sharing origins to add unbundled service offerings – not to replace the previous model but to augment it. What we are now seeing are two new models within the OPM market becoming much more clear: the remnants of for-profit conversions into nonprofit status, and MOOCs supporting online degree programs. Both of these models are driven by markets that need to move beyond their origins as well. A lot of changes happening in the education space.

  • Enrollment Implications Regarding Directive for Online Community College in California

    A month ago Governor Jerry Brown directed Eloy Oakley, Chancellor of the California Community College System (CCCS) ((Disclosure: The Online Education Initiative from CCCS is a client of MindWires. The views in this and future posts represents my independent views and not OEI’s.)) to “take whatever steps are necessary” to establish a fully-online college. At first glance this directive appears to be a solution in search of a problem, so it is worth looking beyond the headline see what is motivating this move.

    In an article from Community College Daily:

    Noting that the system has significantly expanded the number of online courses, Brown said, “I believe it is time now for our community colleges to increase even further the availability of online courses and degree programs – and make college far more accessible and affordable.”

    Reaching more students

    “The governor has been interested in realizing the promise of online education for a number of years,” Oakley said in an interview with CCDaily. He added that Brown also wants a way to reach more nontraditional students.

    “We have literally tens of thousands of working adults with some college and no credentials and a couple of million working adults who are unemployed or underemployed,” Oakley said. “This is a wonderful opportunity to reach a population that really needs a community college to achieve economic mobility.”

    The details are not yet worked out, and Oakley is pulling together a group to advise on the options available to make this directive a reality, with the recommendations due in November. Oakley’s comments clearly establish access for nontraditional students to be the ultimate driver. In an interview with Inside Higher Ed, Oakley commented further:

    “Part of this is the governor’s desire to reach more students in California through a technology platform,” said Eloy Ortiz Oakley, chancellor of the California Community College system. “The 114 campuses are designed in a traditional manner, so we’re reaching a traditional population that is students coming out of high schools.”

    But a new online-only college could reach students those traditional brick-and-mortar campuses are currently missing — adults who are unemployed or underemployed, he said.

    To achieve these goals of reaching more working adult students, there are some real challenges to address.

    View of CCCS Enrollment Mix

    It is worth viewing the historical headcount numbers available from the Chancellor’s office, focusing on age group to get a better understanding of the status quo.

    The headcount for CCCS peaked in 2009 at 2.93 million students and has since dropped to the current 2.36 million level, a reduction of 19%. Across the state, colleges are looking for ways to increase, or at least slow the decrease, in overall enrollment.

    What is most striking in the data, however, is the shift from older students (age 25 and above, or “adults”) to younger students (age 24 and blow, or “traditional”) for the community college system, with the mix roughly reversed from 25 years ago. Chancellor Oakley and Governor Brown are right to note that the older student population is not being served well, at least if we use actual enrollment as a proxy. And the situation is getting worse, not better. However, while the majority of students in CCCS are 24 or younger, there are also a large number of older adult students. In other words, there appears to be an overlap between the students in the current 114 colleges and the target students for the new fully-online college. This will present quite a challenge for Oakley and other planners to make the following statement from the IHE interview a reality.

    “We don’t want to cannibalize the system, and we wouldn’t want to create a college to take enrollment from other colleges,” Oakley said. “Any solution would have to complement what we do, and it has to have an opportunity to share revenue with the colleges and really enhance their ability to serve students.”

    This statement is sounds good on paper and will be crucial in terms of getting at least tacit support from the current colleges to the creation of a new, full-online college. But the data shows there is not a clear and easy path to serve adult, non-traditional students without affecting existing colleges.

    National Trends

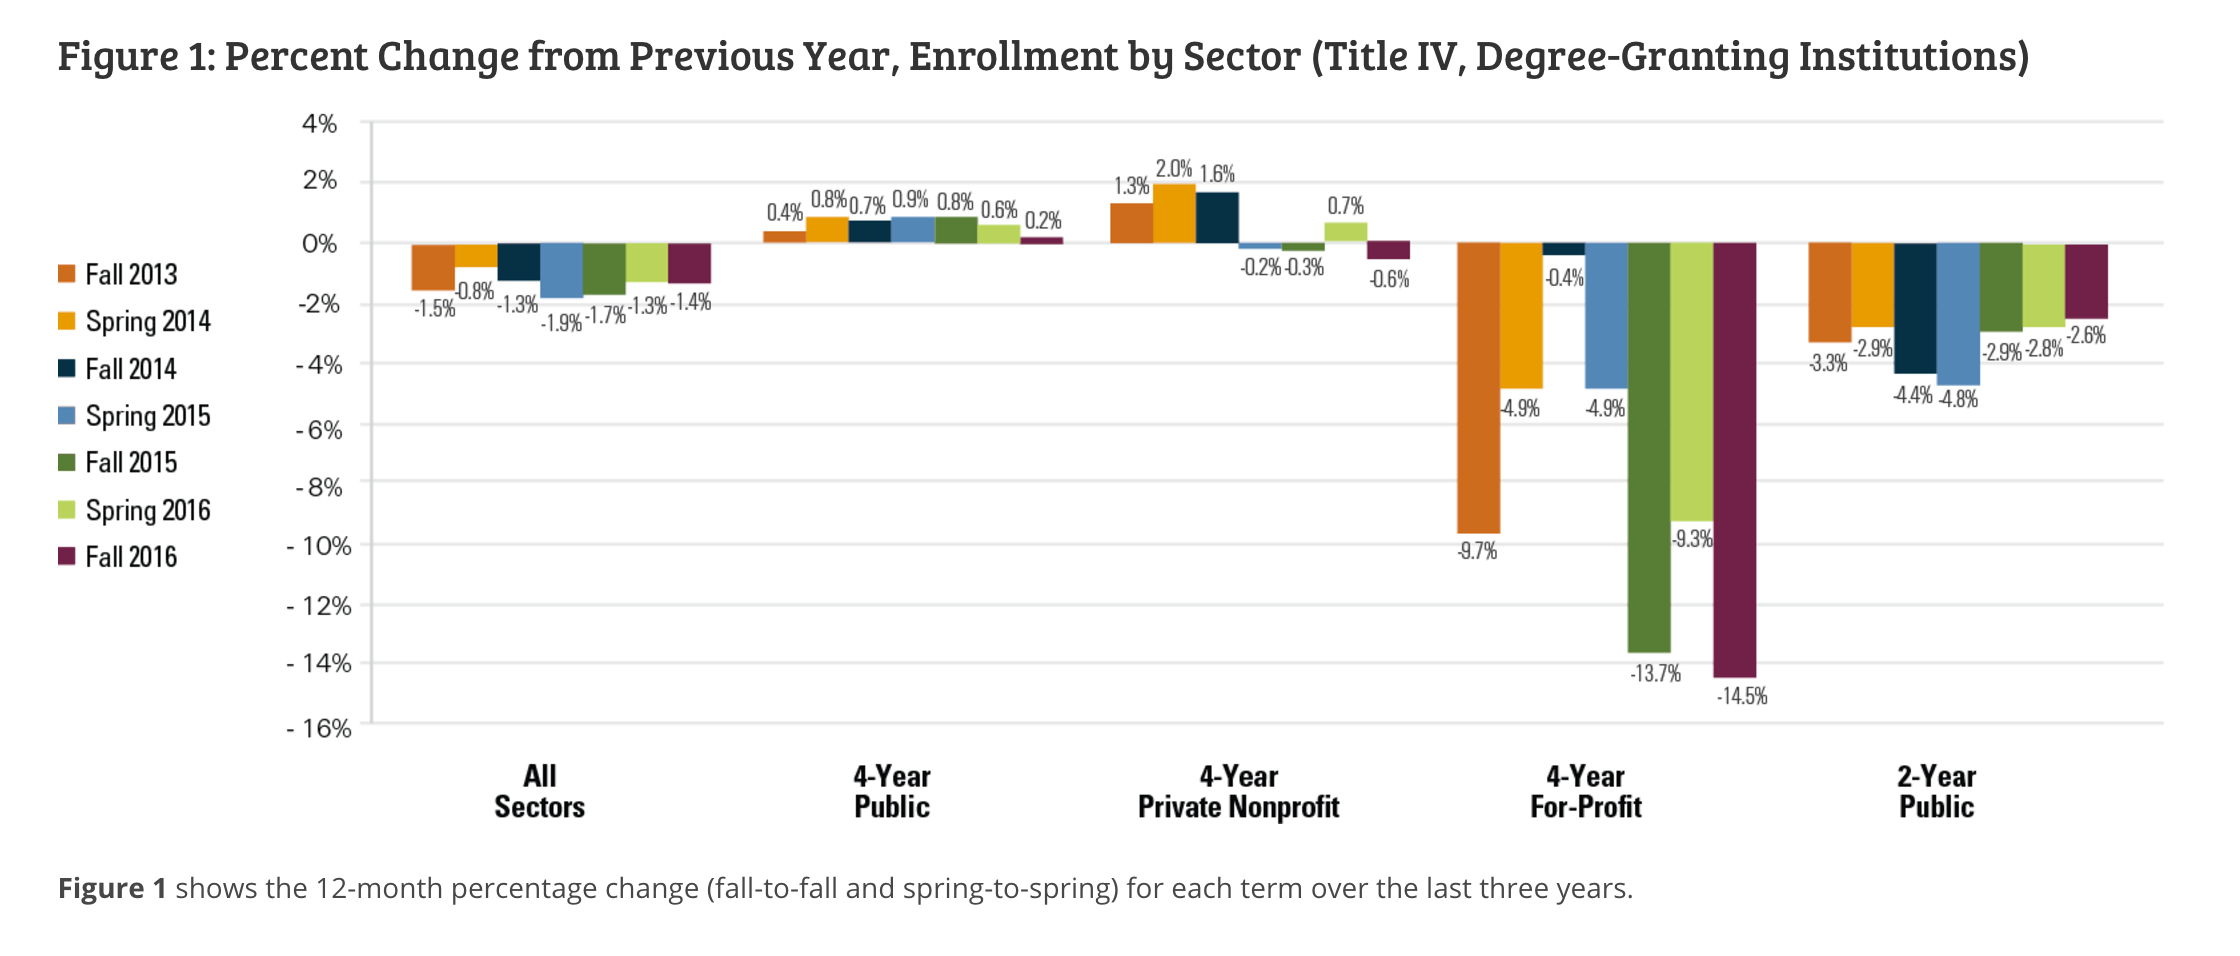
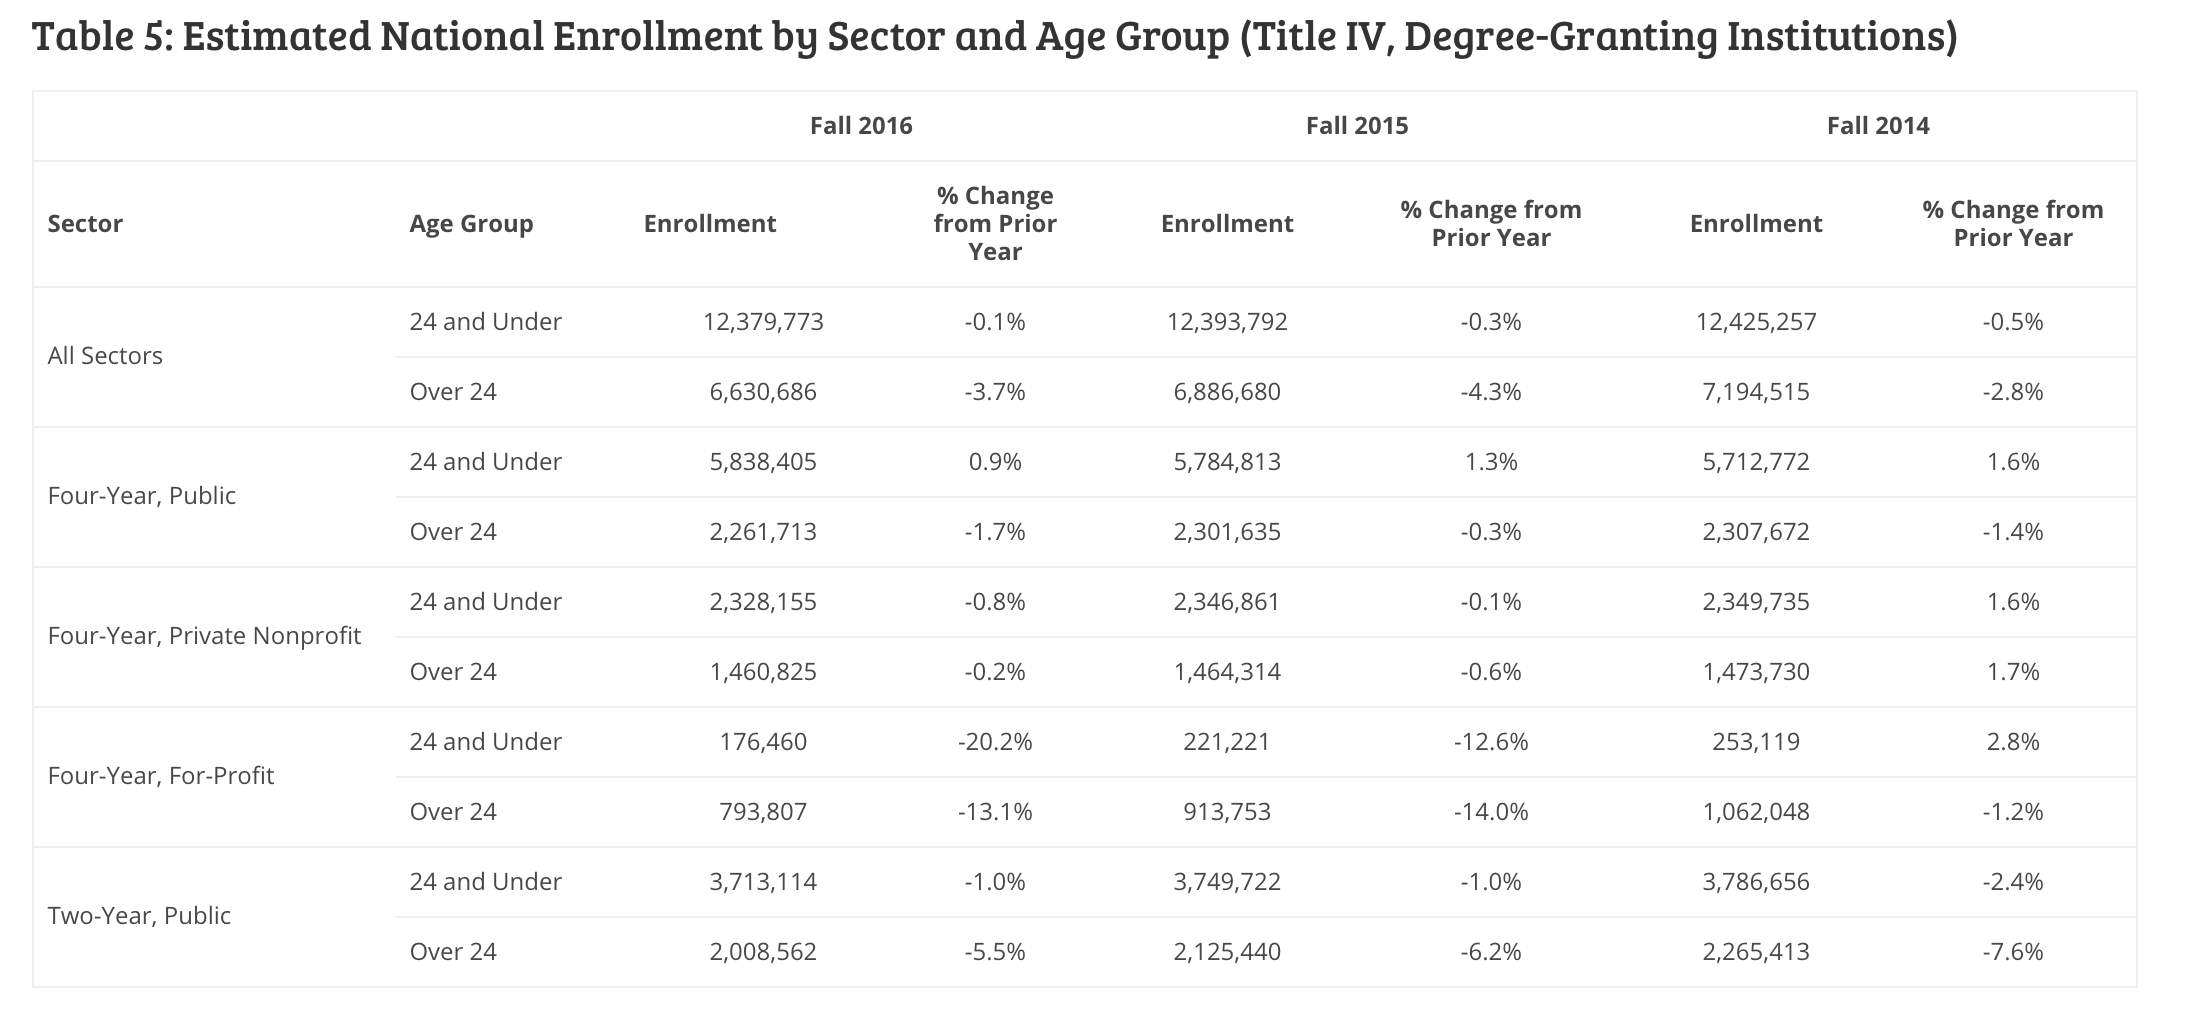
    In this situation California is not alone. The National Student Clearinghouse research for Fall 2016 shows first that community college (2-year public) enrollments have been dropping nationwide.

    And just like in California, adult student enrollment has been dropping much faster than 18-24 year old enrollment. 24 and under groups have dropped 1.0 – 2.4% per year while 25 and above groups have dropped 5.5 – 7.6% per year (see bottom two rows).

    This will be another challenge for the CCCS planning team, as there is no indication that California is screwing up while other states have the same problem figured out – the reduction in community college enrollments, particularly for adult students, appears to be a nationwide demographic trend.

    Comparison Colleges

    Assuming that the plan works out and they find new enrollment opportunities that don’t cannibalize existing college student groups, it is also worth considering how large this college might become. I pulled together the IPEDS data for several of the top-growing online undergraduate colleges ((The comparison colleges might not be exclusively online, but they have become at least predominantly online.)) to get some idea of what the best-case scenario might be in terms of enrollment growth. This data looks at fall enrollment numbers which will be lower than full-year headcount numbers.

    Once we get past the “holy crap, look at Southern New Hampshire University’s (SNHU) growth”, there are a few observations to make.

    • We’ll have to see where SNHU goes, but there has traditionally been a ceiling to the size of online enrollment per institution of around 80,000 – 100,000. The primary exception has been the University of Phoenix that reached a quarter of a million online students back in 2010, but their enrollment has been dropping since then and are more of the exception that proves the rule. All others have peaked well under 100,000 students. Just this spring Liberty University experienced their first recent enrollment drop, leading to staff layoffs.
    • The maximum growth rate of these cherry-picked successful schools ranges from ~1,200 / year for Excelsior to ~7,700 / year for SNHU (note that Rio Salado at ~1,400 / year is the only public institution). Add to this the fact that all of these schools have been around for decades. No accreditation issues, no time-consuming establishment of core leadership team, etc.
    • There is a big difference in dealing with institutional issues and statewide issues, particularly in California. One in five US community college students in the US do so in California, and the statewide issues tend to come in large numbers. Statewide issues tend to come in hundreds of thousands while institutional issues tend to come in tens of thousands.

    What this points to is that for a new fully-online institution to get to some meaningful level of enrollment (let’s say 20,000) in the same ballpark as these comparison schools, I estimate it would take a full decade at the least. This is the reason, by the way, that Mitch Daniels and Purdue University made the Kaplan University deal even though Kaplan’s enrollments are dropping. Daniels did not want to wait a decade to get to meaningful enrollment numbers for an online college serving working adults – if everything works out, within a year Purdue will have a fully-online institution serving 30,000+ working adults. That is a big if, by the way.

    None of this analysis is to argue that CCCS should not try to establish a fully-online college. The goal of better serving nontraditional populations – adult students with and without jobs – is worth pursuing on its own merits.

    The numbers do argue, however, for a realistic view on the challenges they face:

    • Fighting against national demographic trends for adult students of community colleges;
    • Trying to avoid cannibalizing enrollment from existing California Community Colleges;
    • Having the patience to support the schools while it take years to grow to a size with meaningful enrollment levels; and
    • Accepting that best case this approach probably recovers less than 10% of the enrollment drop since 2009.

    I would hope that the CCCS planning efforts take the hard numbers into consideration when searching for different options to satisfy the governor’s directive.

  • Purdue University Deal To Acquire Kaplan University: Interview with Trace Urdan

    Purdue University Deal To Acquire Kaplan University: Interview with Trace Urdan

    The surprise news today is that Purdue University has agree to acquire the academic operations of Kaplan University. As stated in the 8-K filing by Kaplan University’s owner Graham Holdings:

    On April 27, 2017, Kaplan Higher Education LLC and Iowa College Acquisition, LLC (collectively, “Kaplan”), subsidiaries of Graham Holdings Company, entered into a Contribution and Transfer Agreement (“Transfer Agreement”) to contribute the institutional assets and operations of Kaplan University (“KU”) to a new, nonprofit, public-benefit corporation (“New University”) affiliated with Purdue University (“Purdue”) in exchange for a Transition and Operations Support Agreement (“TOSA”), pursuant to which, among other provisions, Kaplan will provide key non-academic operations support to New University for an initial term of 30 years with a buy-out option after six years.

    Additional coverage of the deal at The Chronicle, Inside Higher Ed, The Wall Street Journal.

    This is an unprecedented move, and to get some insight, I interviewed Trace Urdan, who has long covered higher education as an investment analyst and is one of the most knowledgeable observers of the for-profit sector. The following description is based mostly on this interview, paraphrasing Trace’s explanations and adding quotes in places. (more…)