e-Literate

Present is Prologue

Category: OPMs & Program Support

The “OPMs and Program Support” category covers vendors and services that support the development of online and blended programs, including Online Program Management (OPM) vendors.

  • Coursera and 2U: MOOCs are Designed to Compete with Google AdWords.

    Coursera and 2U: MOOCs are Designed to Compete with Google AdWords.

    Coursera’s stock dropped by about 30% on Wednesday in after-hours trading after their earnings announcement. The reason for the drop and the company’s own analysis of its financial performance are both instructive. MOOCs are more or less explicitly considered to be useful primarily as marketing tools rather than educational experiences. There’s reason to believe this is a bad idea for their university partners even from a financial perspective, never mind from university brand value and mission perspectives.

    MOOCs are marketing tools

    Higher Education Dive’s analysis of the stock drop is fairly representative of the reason for the decline:

    Although Coursera reported overall revenue growth in 2022’s second quarter, revenue from the company’s degree segment declined 4% to $11.4 million, according to its latest earnings report.

    Coursera Reports Revenue Declines in its Degree Business

    This isn’t the whole story. The company missed analyst expectations for earnings growth and has guided lower on earnings growth going forward. But the conversation has focused on the degree program decline. Let’s look at what Coursera CEO Jeff Maggioncalda said about Coursera’s challenge in his own words during the company’s earnings call. Responding to an analyst question about problems in the “consumer” side of the business (which means degrees and certificates paid for by individuals rather than their employers), Maggioncalda said,

    On the Consumer side, it’s interesting because the professional surge are still performing really well, particularly in North America. In Europe, it’s kind of more of a conversion rate challenge. And so, like Ken said, maybe it’s the same kinds of effects. You asked about activity levels, I don’t think that we’re seeing any notable difference in activity levels. It seems to be an even a lot of top of the funnel seems to be similar between Europe and other regions. I will say that, generally speaking, search volume for online courses and online degrees.

    And this is not just on Coursera, which is general search volume is down. I think there’s sort of a bit of a the economy reopening and people doing things outside their house that we’re that we kind of see globally. And that probably is happening in Europe as well, but a lot of it sort of conversion rates on the Consumer segment in EMEA, and particularly Europe that we’re seeing.

    Coursera, Inc. (COUR) CEO Jeffrey Maggioncalda on Q2 2022 Results Earnings Call Transcript

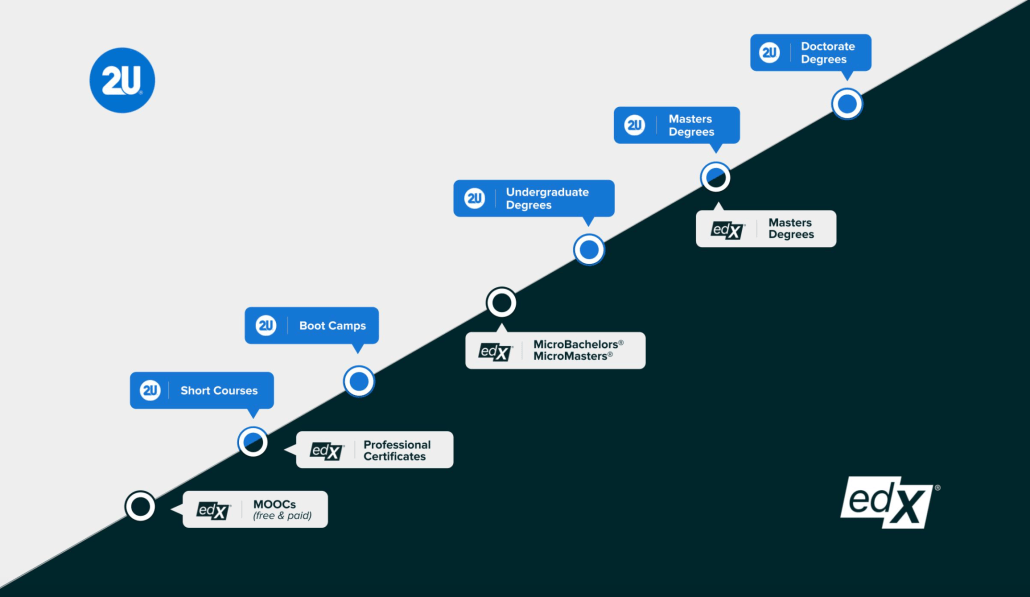
    The key phrases in this excerpt are “conversation rate,” “top of the funnel,” and “search volume.” These are marketing terms. Free MOOCs are at or near “top of the [sales] funnel.” They are designed to identify and attract paying degree candidates. Meanwhile, 2U CEO Chip Paucek said a month ago in his company’s earning call that “[m]arketing investment decisions will be made at the platform level, aggregated across business lines with the goal of increasing the lifetime value of each learner.” The “platform” he’s referring to is EdX. The “lifetime value of each learner” means 2U intends to use the EdX platform to get learners to pay for more courses.

    When 2U introduced its slogan “Free to Degree,” the company wasn’t describing their breadth of coverage. It was describing its sales funnel for getting students into paying degree programs.
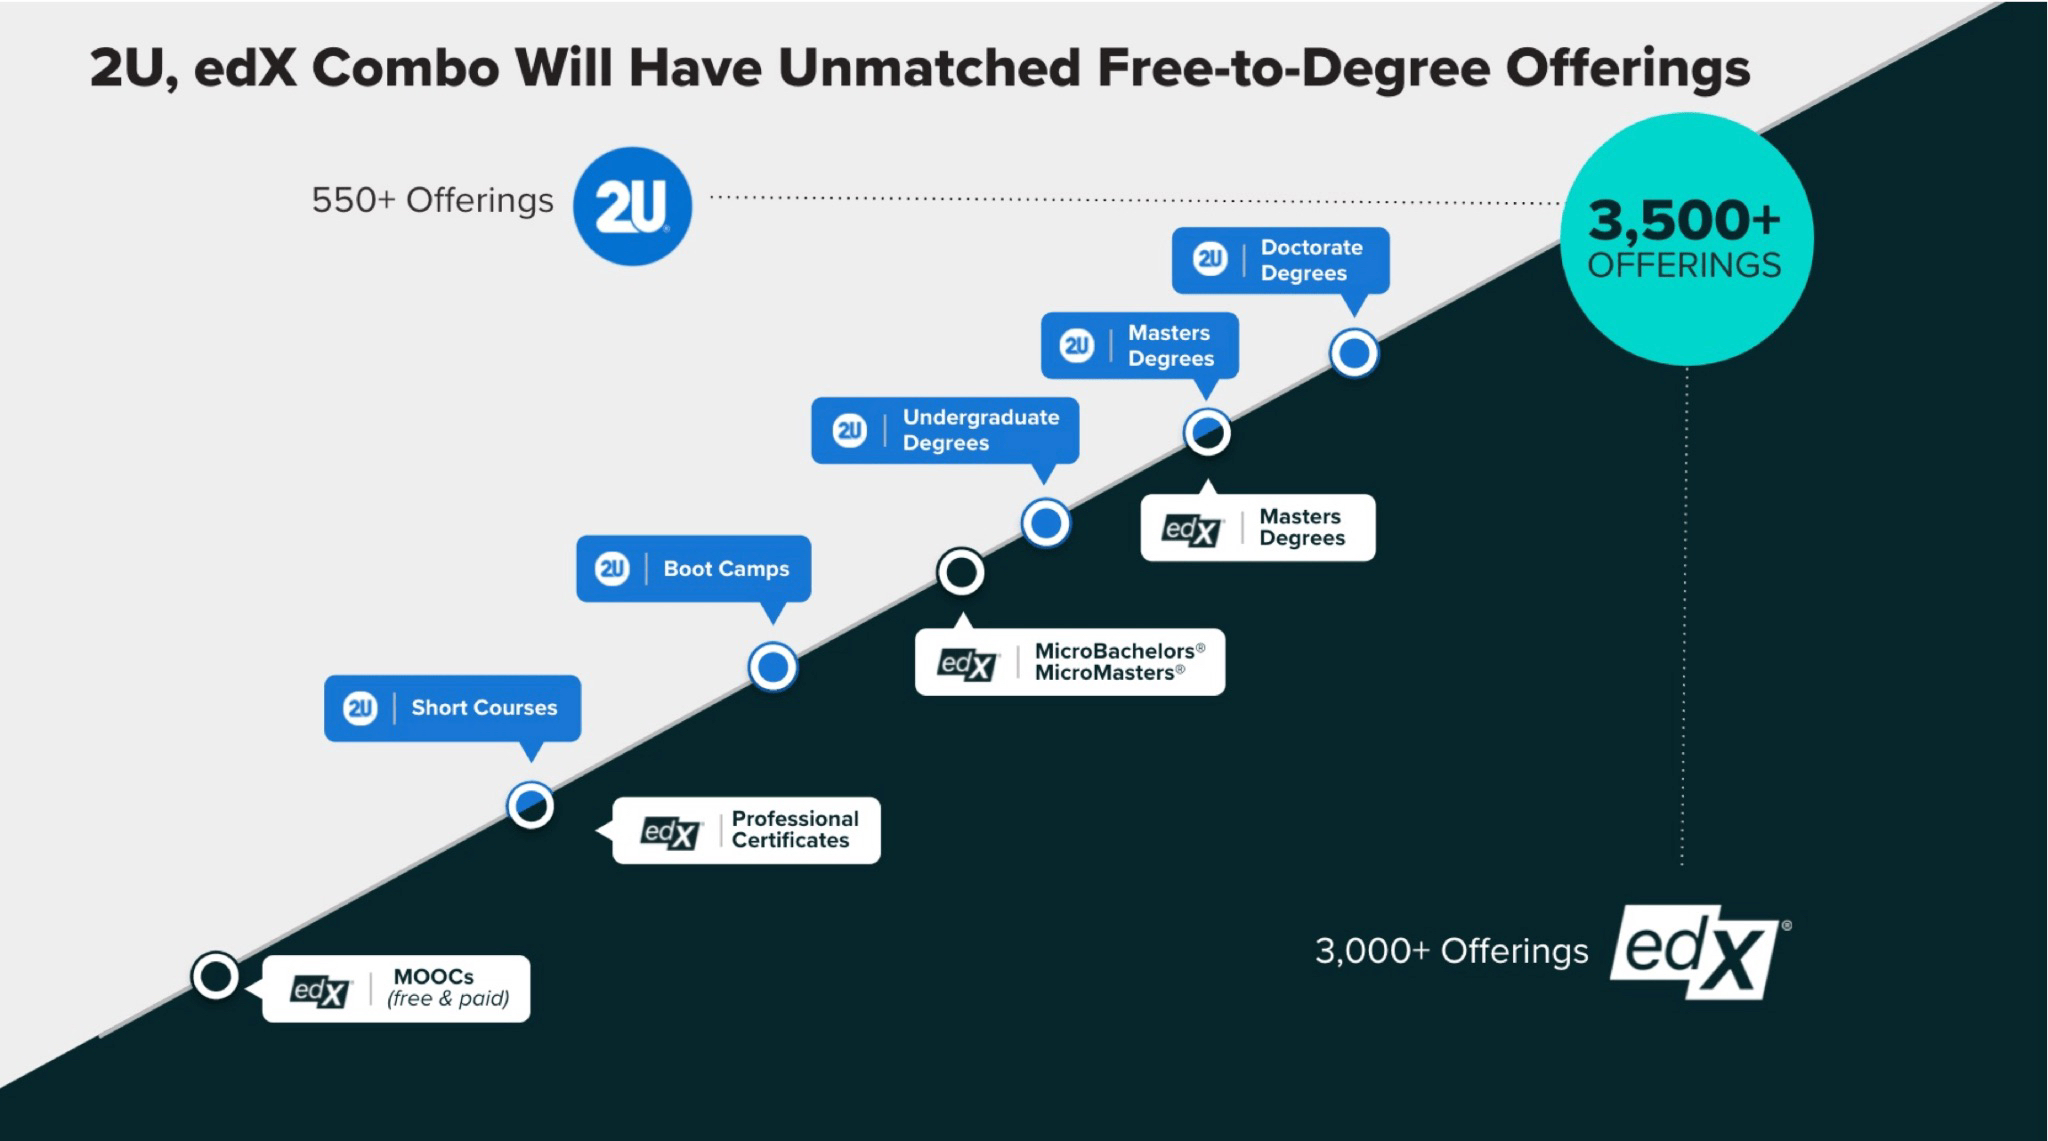
    Free to Degree: Increasing the lifetime value of each learner.

    We can see this mindset at work on the micro-scale by looking at the MOOCs produced by Coursera co-founder Andrew Ng, who now has a company called DeepLearning.AI that sells certificate programs on Coursera. Try the AI for Everyone certificate program. Don’t worry; you won’t have to pay anything to try it.

    You’ll find it is a series of short, engaging, and mildly informative lecture videos by Andrew, each of which is followed by a quiz that anyone who was halfway paying attention could pass. This is absolutely terrible education. But that’s an unfair assessment. Because this “certificate program” isn’t really intended to be education.

    Andrew Ng is at least twice as smart as me and has all the money in the world to pay high-quality learning designers. If his certificate program is not worth paying for, then the most obvious explanation is that he doesn’t really expect you to pay for it. It’s not a certificate program. It’s an infomercial designed to convince you that you need to learn more about AI. It’s the “top of the funnel” designed to “convert” you into a paying customer so that DeepLearning.AI can increase the “lifetime value” of you as a (future) enrolled and paying student in the company’s more extensive (and expensive) programs.

    None of this is new but it’s oddly still news

    In 2019 Justin Reich, possibly the single most prolific and widely respected researcher on MOOCs, co-published an article called “The MOOC Pivot: From Teaching the World to Online Professional Degrees.” The article’s abstract states, “[A]fter promising a reordering of higher education, we see the field instead coalescing around a different, much older business model: helping universities outsource their online master’s degrees for professionals.” Reich’s book Failure to Disrupt is similarly blunt (and well worth reading). MOOCs have become advertising tools to attract students into more lucrative degree programs run by OPMs. As more degree programs have gone online (driven, in part, by the success of the OPMs themselves), the cost of advertising using relevant search keywords Google AdWords has gone up. Because demand for them has gone up.

    MOOCs are attempting to disrupt Google AdWords in education.

    University stakeholders know this. Sort of. If you search the internet for articles about the cost and revenues, you won’t find anything published more recently than about 2015. After the first few years, they just stopped talking about costs and revenues. That shift wasn’t random. And of course, everybody knows how bad MOOC completion rates are and how badly they’ve failed to demonstrate consistent educational effectiveness under rigorous testing.

    When I’ve asked folks I know who are directly or indirectly with MOOC programs at their universities why their institutions are still creating and maintaining these things, I typically get one of two answers. The first is that their bosses think it’s good marketing for the institutions despite the fact that they have data showing that YouTube videos work better. The second is that they frankly don’t know why they are still doing it.

    By extension, Coursera is now an OPM. If it weren’t, then its underperformance in its relatively new online degree unit wouldn’t cause such a precipitous plunge in its stock price.

    But it gets worse

    If MOOCs turned out to be infomercials and everybody understood that to be the case, that would be disappointing but not the end of the world. Some of us never expected them to be the magic bullet.

    The problem is that Coursera’s degree programs are also MOOC-based and 2U is making worrying (though admittedly cryptic) comments suggesting that they may be moving in that direction as well. I’ve seen no good data on MOOC-based degree completion rates. Or on MOOC-based degree efficacy. Or on the perceived value of MOOC-based degrees by employers. We do know how individual MOOCs perform on these measures: badly.

    The only difference I can see between a MOOC and a MOOC-based degree is that students will be paying significantly more for them. Will this make a difference? Eh, maybe a little. I once had a conversation with Andrew Ng and Daphne Koller about research indicating that students would more highly value and be more likely to complete a course that cost $1 than one that is free. Maybe cost will matter because students will be literally invested in their education.

    But that’s a thin reed on which to bet the future of billion-dollar companies, whose future is in turn paid for by students who are participating in an uncontrolled experiment that they are paying for. It seems more likely that if 2U joins Coursera on this path they may have to change their motto to “No Front Row.”

    I get that universities need to develop more sustainable business models. pumping up degree programs through MOOC marketing and then lowering the price of those degrees by delivering them as MOOCs strikes me as a particularly risky way to try to meet financial goals, even if they’re willing to play fast and loose with their mission goals and institutional brands.
  • Is the edX Acquisition a Big Deal?

    Is the edX Acquisition a Big Deal?

    I’ve been inundated with questions regarding what I think about 2U’s acquisition of edX. What do I think? I’ve been struck by how much less I care about this deal today than I would have a few years ago. That change is entirely due to my change in focus rather than external circumstances. e-Literate used to be, in part, an EdTech industry analysis site for its own sake. While I still do some EdTech industry analysis, I’m much more focused on how EdTech influences the direction of the education sector as a whole, particularly with regard to becoming more effective at sustainably helping more students. Due to that shift in perspective, the edX acquisition moves from “a huge deal” to “somewhat interesting” for me.

    How much you should care about the edX acquisition depends on what you care about. So I’m going to write about that.

    Who cares about the edX acquisition?

    You can learn a lot about whether you, personally, should care about the acquisition by looking at who else cares and why. It’s a little early to answer this question entirely; I’m asking around at the moment. But we do have some early obvious answers.

    MIT and Harvard

    First of all, MIT and Harvard care. On one hand, edX was a money loser. Most EdTech companies are. They lose money for a very long time and then only become slightly profitable. Investors can be OK with this if “slightly profitable” is also “reliably profitable.” They can take a long view, in a way. I say “in a way” because many types of investors that put money into an EdTech company on its way to profitability sell their stakes long before their investments achieve their goal. As long as a critical mass of investors believe that these companies will eventually be profitable, then one investor may well be willing to buy a stake in an unprofitable company from another.

    On the other hand, universities aren’t in that game in the same way. As far as I’ve been able to piece together, edX was rushed out the door to get ahead of the imminent launch of Coursera. It wasn’t a strategy. It was a reaction. It was also a money loser. According to Tech Crunch, “The institutions, of course, have thrown in a cumulative $80 million in donations into edX to keep the operation free.” That’s a surprisingly shallow and naive assessment from a publication that’s all about tech companies. ((I also think their contribution number is low, but it’s hard to find hard data.)) First, edX fees to students (or lack thereof) have more or less aligned Coursera’s. Second, both edX and Coursera are two-sided markets. While edX ultimately makes its money off of student purchases, it does so via a revenue share agreement with the universities, which, once again, is not terribly different from Coursera’s revenue share agreement. The basic idea in both cases is to be the Amazon of MOOCs. Get everyone to sell everything through your storefront. Collect a small dollar amount (but a large percentage) of each transaction as your fee. Attract enough customers so that the small dollar amounts add up over time. To the degree that edX had a business plan beyond “do whatever Coursera does,” this was it. It wasn’t obvious that edX would be an asset they would ultimately sell. Their external justifications for edX were always mission-related. Since I have only been able to gather fragments of information about their internal deliberations over the year, I’ll take them at their word on that. I don’t know the degree to which they understood that their commitment entailed losing money every year for the long haul.

    When 2U swooped in, that gave MIT and Harvard an opportunity to get out of that money trap, declare victory, and make a handsome return on their investment. If Tech Crunch’s numbers are right, then the two universities made 10X on their 9-year investment. Is that good? It depends on your perspective. VCs generally look to make a 10X return in five years, and I suspect that those numbers may be less ambitious in EdTech specifically. For MIT and Harvard, I suspect it was a massive unexpected windfall that got rid of some problems and created some opportunities for them.

    2U

    Obviously, 2U wouldn’t have forked over $800 million—in cash—if they didn’t think edX would be a big deal for them. Why? Phil Hill writes:

    Coursera’s market value is roughly 18 times its annual revenue whereas 2U’s is roughly 4. These are rough numbers, but I believe 2U’s leadership believes it an command an increased value as this deal completes. Note that I am not predicting stock prices here, just showing the potential change in market perception.

    Three Charts that Help Explain the 2U/edX Acquisition

    But that only pushes the question back a level. Why do investors think that Coursera is so much more valuable than 2U? The short answer is that one of the most expensive parts of an OPM business—and Coursera definitely is an OPM, as this transaction demonstrates—is marketing for new students. Investors believe both Coursera’s and 2U’s claims that owning a MOOC business helps lower the marketing costs for their core OPM businesses. 2U’s public estimates are that they can save 15% on marketing costs. I’m somewhat skeptical of this claim but I’m also not a financial analyst, so I’ll take it at face value.

    2U has a handful of other potential business justifications, most of which I won’t break down here because, again, it’s not the focus of my writing anymore. I’ll briefly share a few of them, not because they’re the most important but because they’re illustrative and easy to explain succinctly. First, 2U has always aspired to transform the entire education sector by bringing it online. However you may feel about that aspiration—I recognize that feelings tend to run very hot about OPMs—owning a major MOOC platform gives the company’s aspiration more depth.

    All roads lead to….

    Second, edX reaches a lot of students in a lot of countries. The international EdTech market has been a long time coming, but it’s finally arrived. edX greatly expands 2U’s international footprint by some measures, which once again gives them a good story to tell.

    And this brings me to the final advantage I’ll point out in this post. 2U has always been about telling a compelling narrative about the future. One of Chip Paucek’s previous ventures was a company that had comedians explain educational concepts on a television show. He understands how to build a story. He knows how to hit the beats. When WeWork was at peak hype, he made a deal with WeWork. When code academies were red hot, he bought one of the hottest code academies. Given Coursera’s recent success in the markets, it makes sense that he would look to make the biggest, boldest MOOC move possible.

    To be clear, I’m not saying that the CEO of this publicly traded company made these deals solely or primarily to spin a good story. I’m simply pointing out that Chip has a method for responding to market changes. If he believes that getting into a particular business is good for 2U, he will not make his move by quietly dipping his toe in the water. He’s going to jump in with both feet and make a big splash in the process. The edX acquisition fits with that method.

    2U’s and edX’s university partners

    While it’s too early to make pronouncements with any confidence, early reactions I’ve heard indicate that 2U’s university partners are pretty happy with the transaction while edX’s university partners are pretty unhappy. For 2U’s partners, they already decided to go with the big publicly traded corporation that, for better and worse, is heavily associated with revenue-sharing deals. Now they can do MOOCs with the same company. This deal gives them nothing but upside. On the other hand, many edX partners specifically went with edX because they did not want to deal with the for-profit Coursera. Yes, edX had its revenue-sharing agreement too, but it was a non-profit run by universities. That made it feel different for some.

    2U may have to deal with some of the kind of backlash that Blackboard did when it bought other LMS companies—particularly Moodle support companies. They may lose some universities. Then again, 2U is definitely not Blackboard. Especially Blackboard circa 2012 (although, ironically, edX was formed the same year Blackboard acquired Moodlerooms). 2U built its business by winning over faculty senates. Also, while the company may lose some edX customers, it may gain some by cross-selling to its existing customer base. It’s hard to say how all this will play out, net-net. All I can say with confidence right now is that people at the edX schools I’ve talked to so far are understandably nervous.

    Who doesn’t care

    I doubt students will even notice. I take that as one strong indicator of how I should feel. It’s not clear to me that Coursera has done anything edX hasn’t and that would or should concern students. I could be wrong; I haven’t looked closely at this aspect. (Please correct me in the comments section if you know something I don’t.) Further, I have no reason to believe that 2U’s behavior will be worse than Coursera has been.

    MOOCs strike me as a relatively low-risk corner of EdTech for heavy corporate involvement. My sense is that, if 2U sees edX primarily as a way of making marketing dollars go further, then they have a vested interest in keeping students happily engaged. Yes, they’ll use student data to target them for marketing, but if you are shocked by that, then you should maybe take a look at all free products that you use (possibly including the email service that you are reading this blog post through). As long as the MOOCs are transparent about what they’re doing, it’s probably OK in that particular market. In fact, those particular learners may want to receive targeted ads about other learning opportunities.

    The ways in which I care

    In and of itself, I’m indifferent to this deal. I’m not opposed to revenue-share OPMs in general or 2U in particular. (This is an outdated argument anyway since the major OPMs generally offer non-revenue-sharing arrangements of various flavors these days.) At first blush, I don’t see any big harm to students or institutions in it. (I reserve the right to change my mind in either direction as I learn more.) Since xMOOCs have not turned out to be the end of academia as we know it, either in the revolutionary sense or the armageddon sense, I’m inclined to feel mildly positive toward an arrangement that gives a major provider a sustainable path forward. MOOCs are one more arrow in the quiver as we try to offer everyone in the world the opportunity to fulfill their potential through education. I’m not going to turn my nose up at that. I like the folks I know at both edX and 2U. While I don’t always agree with them, I’d like to see them make a contribution with their new venture. I’ll wait and see and wish them well.

    Beyond that, I mostly care about two aspects that I haven’t seen talked about much in any of the coverage. First, there’s the open-source code. While I frankly think the early iterations of OpenEdX were embarrassingly bad and improved over time to “surprisingly OK given how embarrassingly the foundations were,” I do think there is value in maintaining an open-source MOOC platform. I am skeptical that 2U has the DNA necessary to steward an academic open-source community. I know how good 2U can be at working with academics and I also know what it’s like to steward an academic open-source software community. These two things are not the same.

    Second and more importantly, I’m worried about the loss of research. Thanks to the efforts of researchers like Justin Reich and Rene Kizilcec, edX has been one of very few public testbeds we have for conducting credible learning efficacy research at scale. 2U, in contrast, has done nothing visible in the area of learning science. They’ve started talking about it in the past year or two, but frankly, if e-Literate were still doing the cop-on-the-beat thing, I probably would have shredded them about it by now. In 2021, there is absolutely no excuse for any EdTech company of 2U’s (or Coursera’s) size and scale not to be engaging actively with academics in serious applied learning science and contributing to our collective knowledge. If 2U can spend $800 million—in cash—for a MOOC organization that loses money every year, the company can surely afford to invest one-half of one percent of that every year in a credible program to advance the state of knowledge and literacy in effective teaching practices. And now that they own a platform for conducting such research at scale, the onus on them has only increased.

    The same goes for MIT and Harvard, by the way. Despite the excellent work of a few researchers, and despite the rhetoric of the institutions at the time that edX was launched, one reason we have not gotten more and better research out of edX is that the platform, incredibly, was poorly designed for educational research. How did MIT build a platform for massive-scale learning in 2012 and fail to think about what sorts of educational data and metadata they would need to facilitate research? What does that tell us about the real priorities behind the initial push to production? It’s a mystery.

    I’m not particularly interested in the vague promises of two rich universities to do good in the world with their $700 million windfall from a non-profit that was supposed to educate the whole world. I’d like to see a credible plan this time, including a theory of change.

  • SoP Webinar on Instructional Designer Professional Development

    Improvement in post secondary education will require converting teaching from a solo sport to a community based research activity.

    Herb Simon

    For all the talk lately of the “future of work,” we don’t talk enough about the future of work for educators. We have a growing shortage of well-trained instructional designers, course architects, accessibility experts, learning engineers, and similar specialists. This gap is only going to grow as improving student outcomes becomes increasingly critical to sustainability for colleges.

    That’s one reason why I’m pleased to announce an e-Literate Standard of Proof webinar on iDesign’s LX Pathways program, a new competency-based digital curriculum for professionals looking to develop these skills. iDesign created them, in part, to help with their own employee recruitment challenges as the company grows. This is a great resource for the sector, which was developed by iDesign, made available free or cheap—depending on which option you take and how far you go with it—to anyone, and tested with Harvard School of Education graduate students.

    Come hear iDesign Chief Learning Officer Whitney Kilgore and Patrice Torcivia Prusko, the Associate Director of Learning Design at the Harvard University Graduate School of Education Teaching and Learning Lab talk with me about LX Pathways.

    The webinar is on Thursday, February 20th, at 2 PM ET.

    Sign up here!

  • The MOOC-Courseware Convergence

    Now that Coursera for Campus—which I have occasionally erroneously referred to as “Coursera for Schools” in previous blog posts—has been launched, we have some more information about what it’s really about. (I’ll embed the launch video at the bottom of the post, but if you’d rather go straight to it, you can find it here.) I think it’s significant and portends significant trends in the sector.

    Before we get to that, let’s get one item of business out of the way related to my previous posts. As IBL Education notes, Coursera CEO Jeff Maggioncalda said, “Coursera for Campus is not a full-featured LMS. We expect many universities to stay on their LMSs.” IBL News further notes, “According to the company, Coursera for Campus’ LMS is designed to supplement the existing Canvas, Blackboard and Moodle systems.” [Emphasis in original.]

    So Coursera for Campus isn’t LMS play, at least for the foreseeable future. I was pretty harsh on Coursera’s SVP of Enterprise Leah Belsky for her disruption language, but as I’ll get into later in this post, this kind of category mistake is actually quite easy to make and one that other courseware providers have made.

    Because that is exactly what Coursera has explicitly become with their Courseware for Campus offering: a courseware provider. The less obvious part is that MOOC design and courseware design have been converging for some time now. Their increasing similarities in instructional affordances have been masked by the differences in the business models of their parent companies. And even less obvious is that the Venn diagram of courseware companies and OPM companies is starting to overlap significantly.

    “A 21st-Century textbook”

    In the launch presentation, Maggioncalda called Coursera for Campus, in part, a “21st-Century textbook.” Take that seriously. These are MOOCs repurposed as curricular materials. And it’s really not that big of a leap. Remember that the pedagogical model of the xMOOC course generally doesn’t require heavy participation from the instructor. Some instructors do participate heavily, while others, less so. A lot of instructor energy goes into course design and lecture video production. The actual live support could be from the instructor, but it also could be from TAs, or it could be self-study. Or, in the case of Coursera for Campus, it could be a different instructor. From its inception, the design model of xMOOCs began decoupling faculty course design from faculty course delivery.

    There is some messiness, of course. The biggest challenge in terms of textbook-like may be the lecture videos. Faculty may not love having some other personality featured as the star of the show. But there are two mitigating factors to that. First, Coursera’s design staff is likely guiding faculty toward authoring instructionally sound videos, which would tend to reduce the total amount of talking head content in any given course. Second, textbook-provided commercial courseware, which is still often written by star authors in their field, now also features talking heads. Here, for example, is the Cengage MindTap introductory video for Economics, by author Greg Mankiw:

    Greg Mankiw’s head, talking

    “But,” you may be thinking, “MOOCs are not designed like courseware.” One of my Twitter followers made a comment to the effect that at least courseware has an instructional design philosophy, unlike xMOOCs.

    That person is mistaken, and here is the proof:

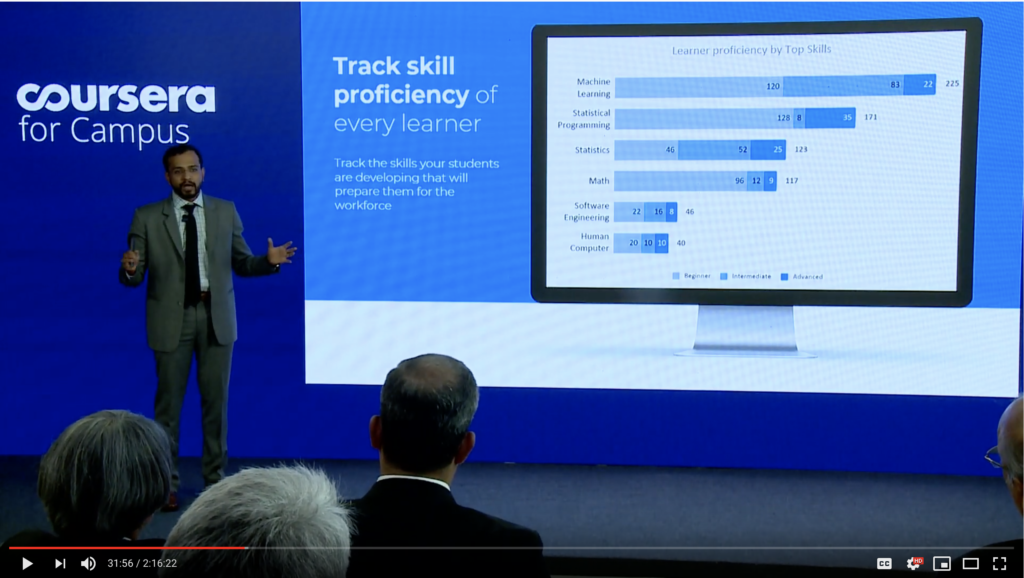
    These analytics are only possible with backward design

    During the launch presentation, a Coursera executive made the statement that “any of the courses that have been authored on Coursera come with an out-of-the-box analytics platform.” If those analytics look anything like the picture above—and I would bet money that they do—then the courses have been built on a backward design philosophy like the one I have been describing in my recent post series on content as infrastructure.

    This shouldn’t be surprising. As I wrote repeatedly throughout that series, almost every professionally designed course uses that design pattern. And Coursera is known for having strong professional course design support.

    (I’m telling you, folks. That content pattern is the revolution of our time.)

    Update: Matthew Rascoff has reminded me to acknowledge that the professional course designers on campuses play large and critical roles in the design of these courses. The larger point is that, on both sides of the fence, there are trained, professional course designers who are applying this design pattern.

    While I haven’t looked at their catalog myself in quite some time, I would not be surprised at all if many of their offerings stack up pretty well against commercial courseware titles. For one thing, while xMOOCs have a bad reputation for anemic social interaction relative to other course models, they probably have more social interaction designed into them than many commercially published courseware titles.

    Courseware platforms vs LMSs

    It’s easy to get confused about the boundary between a courseware platform and an LMS. I know because I have worked on and consulted on both. The LMS companies inevitably start thinking, “Damn, there are so many courses that get delivered through our platform, and so much money made on selling them. And guess what? Everything that faculty build and deliver through our product is a course! The textbook publishers keep rebuilding what we’ve already built. Badly. I mean, have you seen their grade books? Why can’t we be the platform and get a cut of all that money?”

    So they try to displace the publishers. And they fail. Every time.

    The textbook publishers, meanwhile, start thinking, “Damn, our customers really hate their LMSs. We’ve built all these LMS features, and they keep asking for more. I mean, we’ve already built a grade book. Wow, that was painful. Why can’t we be the platform and get a cut of all that money?”

    So they try to displace the LMS companies. And they fail. Every time.

    Here’s the critical difference:

    LMS developers have to optimize for a wide range of faculty preferences, teaching styles, and teaching conditions. They have to accommodate every grading scheme imaginable. They have to handle huge classes and tiny classes. They have to deal with face-to-face, online, and blended. Constructivist, lecture, and whatever else. That’s why they spend so much time adding grade book micro-features and then optimizing the usability to handle all those micro-features without being totally overwhelming.

    Courseware developers, in contrast, have to optimize for the content. If the subject is software development, then you need an interactive code editor and test engine. If it’s accounting, then you need a test engine that looks like a spreadsheet. If it’s chemistry, then you need a molecule visualizer and manipulator.

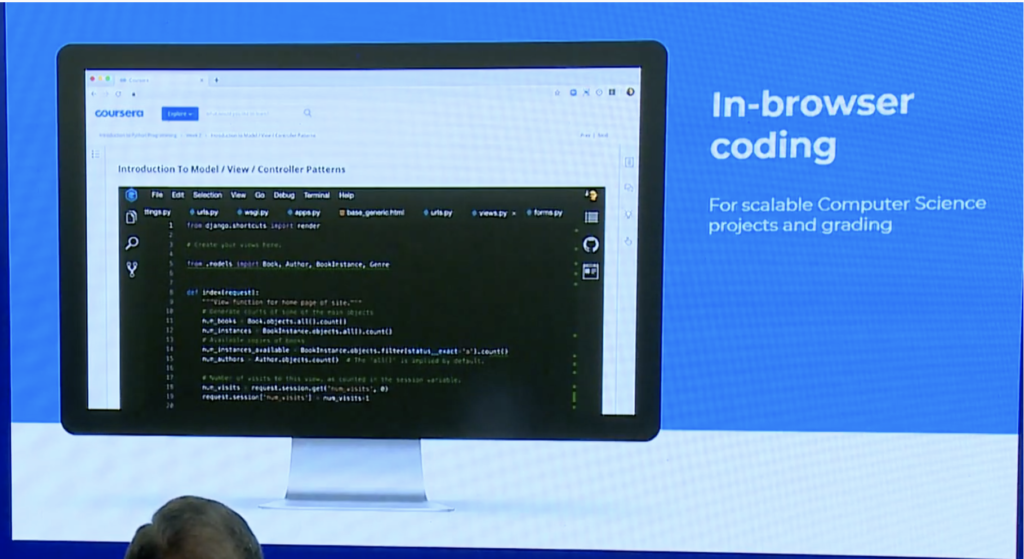
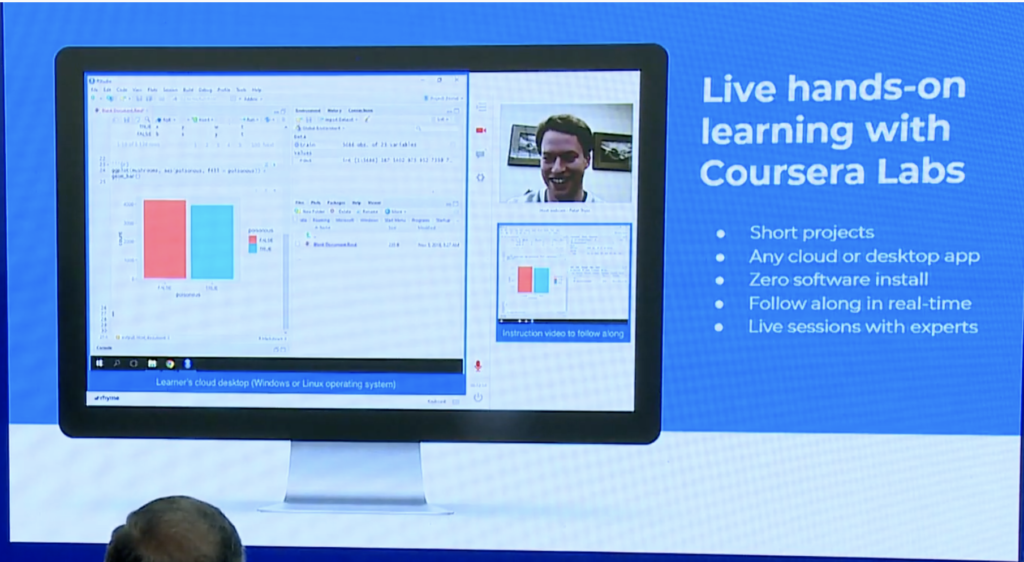
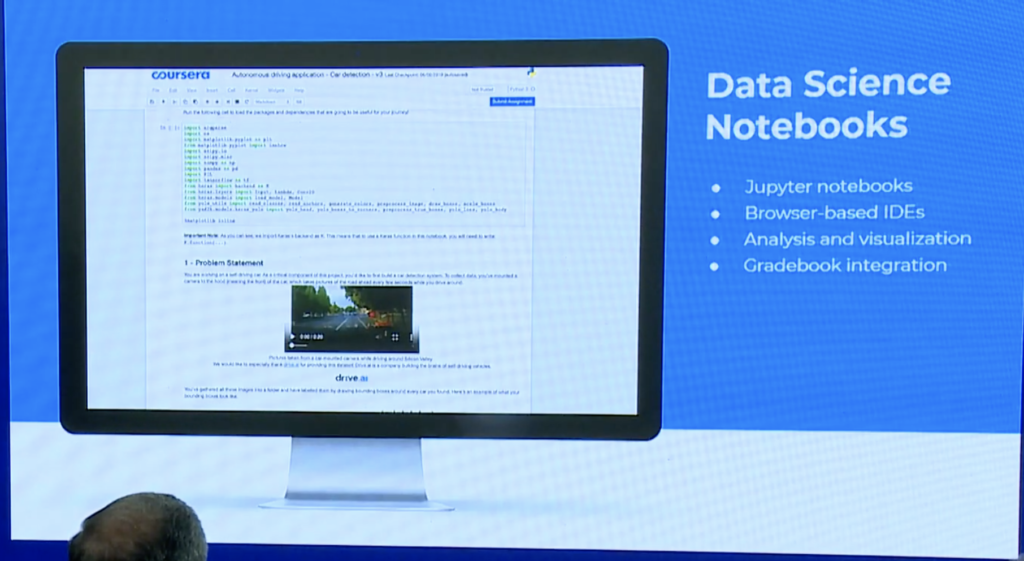
    Which side of the divide do MOOC platforms land on? Here are a couple of slides from the Coursera on Campus launch:

    In-browser coding!
    Virtual labs!
    Data science notebooks!

    These subject-specific affordances, plus competency-based analytics, were the platform highlights of the Coursera for Campus presentation. Not the grade book that can do anything. Not the test engine that can provide any kind of feedback. Not announcements or an event feed. This was all about courseware.

    “But wait,” you say. “Courseware for Campus lets faculty author their own courses. Isn’t that different?”

    Yes. And no.

    Way back the better part of a decade ago, when I was at Cengage working on the MindTap platform, the company debated whether to open it up to customers and license it without content. (“We can disrupt the LMS!”) In the end, there were two major barriers. First, as a print-centric company in the midst of a transition, the authoring tools were not remotely faculty-friendly. And second, as a publisher whose bread and butter came from royalties, there was a fear of cannibalization of the business.

    Coursera has neither of those problems. It was born as a two-sided market, which means that it never owned the content to begin with and always had an incentive to make authoring as easy as possible. It may have taken some time to fully realize that vision, but we were destined to arrive where we are now.

    Further, as textbook publishers increasingly move away from celebrity franchises and toward fee-for-service contracts with their authors, they will have motivation to make similar moves. McGraw-Hill Education doesn’t advertise it widely, but they have been licensing the authoring platform for SmartBooks for several years now. Authoring support can work with a courseware platform as long as the range of course expectations for delivery models can be constrained. And MOOC courseware fits the bill. It’s a genre.

    Coursera for Campus is a harbinger of the future, not for the LMS industry but for the textbook industry. And they are an early mover with certain advantages in their business model.

    The courseware/OPM convergence

    One critical element that I don’t want to lose in all of this is the implications for the OPM market. Let’s not forget that (a) Coursera has been pushing into that market aggressively and successfully and (b) that market has been under massive pressure and upheaval lately. 2U has been the canary in the coal mine, having lost roughly four fifths of its market value since the beginning of the year. ((Disclosure: 2U is a 2019 sponsor of EEP.))

    To be clear, I think there’s some noise obscuring the signal. Two of the reasons why 2U took such a big hit are that the stock got way ahead of itself and some self-interested players have been extraordinarily successful at generating FUD around the market category in general.

    That said, there is no question that the hype around selling an infinite number of $40K masters degrees has met its demise. There are two barriers to OPM growth, which is another way of saying that there are two barriers to conventional online degree growth, and they have both proven formidable barriers to crack. The obvious one is cost. The less obvious one is geography. It turns out that, even in an era when people can take courses from anywhere in the world, they will tend to take them from their local institution or not at all. For all the talk of “national universities” and “mega universities,” it’s not clear that such beasts really exist. For the most part, big universities have proven exceptionally good at soaking up every ounce of demand for education in their local areas. So the next sustainability play is not so much about reaching students far away as it is about serving students you already reach for 40 years rather than for four.

    And interestingly, that is essentially the pitch that the Coursera executives made about Coursera for Campus—even when they were pitching in India. They weren’t making the pitch that the American stereotype would have predicted, of reaching the rural millions. They were talking about lifelong learning. Skilling and reskilling. From an OPM perspective, this pitch gives the company with the large catalog of low-cost and constantly refreshed inventory a competitive advantage.

    That said, there was definitely a bit of hand waving going on regarding completion rate. The Coursera executives talked about University of Illinois’ degree program as having over a 90% completion rate as if that remarkable achievement could be solely attributed to the fact that it was a degree program. I suspect there are some hard-working support staff at the University of Illinois who might quibble with that clean of a causal analysis. I don’t think the Coursera folks are directionally wrong, and I don’t think they were intentionally misleading, either. But I do think that they oversimplified, and that running a highly successful program at scale with a 90%+ degree completion rate entails a lot more than just handing out a piece of sheep skin at the end. The reason I bring this up is not because I want to snark on Coursera but because the part that is being glossed over represents a number of support areas that OPMs compete on (and that more traditional OPMs and OPEs pride themselves on excelling at).

    The gap between “MOOC” the course model and “MOOC” the courseware model is very much an open question in terms of student success. The MOOC courseware model, particularly as implemented into affordable degrees at scale delivery models by pioneers like Georgia Tech and University of Illinois, are creating an alternative delivery model that could start putting pressure on OPMs supporting more traditional models. Coursera on Campus, in addition to creating an additional revenue stream for the company and putting pressure on courseware providers, potentially ups the ante in the OPM market. But we need to look to those universities which are pioneering affordable degrees at scale to understand the service gaps, marketing gaps, and cost differences between MOOC courseware and the totality of what they are doing in order to understand the what it would take to replicate their success.

    In the meantime, consider the implications of the Coursera on Campus model for the future of companies like Pearson and Wiley, which own both courseware and OPM divisions, or McGraw-Hill Education, which has begun experimenting with opening up its platform for content authoring by customers. ((Disclosure: Pearson is a 2019 sponsor of the Empirical Educator Project.)) It’s not necessarily all bad, but it is a potential accelerant to change that is already in the wind.

    It’s a wild, wild, wild, wild world, my friends.

    Here’s the full launch event for your viewing pleasure:

  • Disruption Disrupted: The Great MOOC Die-Off

    Coursera has announced, with some fanfare, their Coursera for Campus initiative, which Jeff Young at EdSurge has characterized as an attempted entrance into the courseware market but which Coursera Vice President of Enterprise Leah Belsky described as aimed at the LMS market.

    From the EdSurge piece:

    Coursera for Campus is designed specifically with colleges in mind, says Leah Belsky, Coursera’s vice president of enterprise. That means the service includes new features tailored for use in an academic environment, including plagiarism detection to spot cheaters and integration with existing student gradebooks in the learning management systems (LMS) that colleges use.

    Meanwhile, Coursera is opening up its technology platform to any college to use for free to deliver course materials on their own campuses. That means that colleges could use the Coursera software as an alternative to their learning-management system. Belsky argues that Coursera’s system is better designed for delivering online courses and interactive lessons than most LMSes. 

    “We’re talking about a potential major disruption to the LMS market,” she says. “We don’t have all the features of an LMS but what we do have is all the tools to create cutting-edge interactive learning experiences.”

    This is bad framing from a PR perspective, but more importantly, it just plain misses the real potential value proposition and chases a plainly imaginary one instead.

    First, I hear a constant stream of complaints about both major MOOC providers having platforms that are not even fully adequate for their original purpose (though the situation does seem to be improving, particularly in terms of data analytics). At least one very high-profile customer, who I won’t name here, uses the MOOC platforms basically as a store front while putting their actual courses in an LMS. This comes at a time when some Blackboard customers still balk at switching from the classic to the Ultra experience because of feature gaps on level of granularity of test question feedback. MOOC platforms are interesting and have some innovative features, but they are neither mature for their original purpose nor tuned for the broad range of usage that a campus LMS must serve. Second, disruption talk is particularly tone deaf from anyone in a product category that was very recently known for hyping that they would be disrupting the university itself. And finally, disruptive innovation is an unfalsifiable theory that has thus far shown itself to have no predictive power in higher education. It’s a provocative idea that may have some generative intellectual value, but really, it’s well past time for every company that has aspirations in education to drop the word “disrupt” from their public vocabularies. Coursera for Schools may well have a decent value proposition, but this isn’t it.

    Jeff’s framing is closer to the truth: This is primarily a courseware play. There’s a little bit of gray area because courseware platforms and LMS platforms are slowly drifting toward each other in terms of design, but if they ever do converge, it won’t be in the next couple of years. No, this is about repurposing content. And the real story here is that the content needs to be repurposed because we have an overpopulation of MOOCs that are in the midst of a die-off. I’m not saying that MOOC companies are dying off. As far as I can tell, Coursera seems to be healthy. (I have less visibility into EdX’s financial status.) What I mean is that previous generation of the Stanford/MIT/Harvard-style xMOOCs, having failed to achieve either their mission or their sustainability goals, are now being repurposed into other things. Because we don’t have better names for those things, we still call them “MOOCs.” But they don’t meet the definition of Massively Open Online Courses. Even the Stanford/Harvard/MIT definition.

    Meanwhile, there are zombie MOOCs on these platforms that are in the process of getting killed off. Not too long ago, one campus stakeholder told me that their MOOCs basically serve the same purpose as their YouTube marketing videos, except that the YouTube videos get much better viewership and cost a lot less. I don’t expect the MOOC to die entirely, but two years from now, there will be a lot fewer of them than there are now. We just may not recognize that change if we insist on continuing to call any online enrollable thing with more than 30 students a “MOOC.”

    The known failure

    What’s weird is that everybody has known that the xMOOC was a failed experiment within 12 months of it reaching peak hype, and the widely known evidence has only mounted since then. In a January 2019 article in Science that was tellingly titled “The MOOC Pivot,” authors Justin Reich and José A. Ruipérez-Valiente write in the summary,

    When massive open online courses (MOOCs) first captured global attention in 2012, advocates imagined a disruptive transformation in postsecondary education. Video lectures from the world’s best professors could be broadcast to the farthest reaches of the networked world, and students could demonstrate proficiency using innovative computer-graded assessments, even in places with limited access to traditional education. But after promising a reordering of higher education, we see the field instead coalescing around a different, much older business model: helping universities outsource their online master’s degrees for professionals (1). To better understand the reasons for this shift, we highlight three patterns emerging from data on MOOCs provided by Harvard University and Massachusetts Institute of Technology (MIT) via the edX platform: The vast majority of MOOC learners never return after their first year, the growth in MOOC participation has been concentrated almost entirely in the world’s most affluent countries, and the bane of MOOCs—low completion rates (2)—has not improved over 6 years. [Emphasis added.]

    The entire (paywalled) article is worth reading, but honestly, is any of the above a shock to you? xMOOCs, as originally designed, are not replacements for face-to-face classes. They do not lead to reliable course or credential completion. They do not do a good job of serving underserved populations. And they do not create sustainability models by giving a way expensively produced courses and making up for the cost on volume. They have value for some folks. I’m glad they exist in the world. But as an alternative system of education, they are a failure.

    We see this proven out again and again, in multiple variations. Most recently, ASU has largely shut down their Global Freshman Academy, a large undergraduate MOOC experiment designed to give students credit for their first year of college and attract them to matriculate to ASU for a degree. From the IHE article:

    Of 373,000 people who enrolled, only 8,090 completed a course with a grade of C or better, just over 2 percent of all students enrolled. Around 1,750 students (0.47 percent) paid to receive college credit for completing a course, and fewer than 150 students (0.028 percent) went on to pursue a full degree at ASU.

    Was Global Freshman Academy an experiment worth running? Absolutely. In fact, I fervently hope that ASU will be more forthcoming than they have been so far with the lessons they have learned from the experience. Did students in those courses gain value? While that article doesn’t provide significant data on this question, I strongly suspect that many did. Were MOOCs an effective vehicle for saving freshmen roughly 25% of the cost of a college tuition while still getting them on to sophomore year? Clearly not.

    So what has worked as a MOOC-like alternative to the traditional degree? What’s the closest we’ve come to fulfilling the original vision? The most high-profile success has been Georgia Tech’s affordable graduate degrees at scale. Note: I have not seen them refer to these courses as “MOOCs.” They talk about “affordable degrees at scale.” Yes, these are big classes. And yes, Georgia Tech does use MOOC platforms as part of their delivery ecosystem. But their experiment was never about “massively open.” It was about “affordable at scale.” They wanted to see how inexpensively they could offer a degree while keeping some of the same structures and conventional quality checks that their face-to-face programs have. And for Udacity, Georgia Tech’s first MOOC partner, the degree program represented a pivot. (The first of several.) They essentially acted as a kind of Online Program Enabler, which is a weird category that crosses boundaries of platform, content, and services.

    When I look at Coursera’s latest announcement, I see an offering very roughly akin to the one that Udacity originally made for Georgia Tech, but with a heavier emphasis on prepackaged content—likely because Coursera already has a lot of content on the platform that may be quite good but is apparently not going to be disrupting universities, or conventional degrees, any time soon. If Coursera were to become (in part) a two-sided market for universities to buy and sell interactive curricular materials from each other, that’s not necessarily a horrible future for either the company or its customers. But it is suggestive of the collapse in the hype we’ve seen in both the MOOC and the OPM markets.

    OPMs, courseware providers, and “MOOCs”

    I want to return to the portion of that quote from the Science article about MOOC providers turning into OPM companies, which I highlighted but didn’t address. Again, that’s obviously true. All this talk about “micro masters” and “degree pathways” essentially amounts to a claim that many working professionals would like to pursue their post-graduate education in small, career-oriented (but still accredited and tuition-burdened) chunks. Likewise, MOOC providers like to talk about how MOOCs provide an inexpensive sales funnel to get degree students.

    While I haven’t seen direct hard data to support either claim, I’m more inclined to believe the former than the latter. A “micro-masters” program is essentially a large certificate program that can count toward a larger degree. Certificate programs have been around forever, and they sell. On the other hand, I’ve seen no public evidence that the MOOC, a course genre which has trouble getting students to the end of the first course, is going to be successful at getting students to matriculate to a program in significant numbers. The ASU Global Freshman Academy isn’t a direct comparison, since it is undergraduate, but the numbers are still pretty discouraging.

    Reich and Ruipérez-Valiente have their own opinion about the competitive advantage of MOOC providers in the OPM space, and it is revealing:

    The primary competitive advantage of MOOCs relative to established school-as-a- service providers involves cutting labor costs through automation. Many “traditional” online programs include small class sizes, synchronous sessions with instructors, and human-graded assignments. Many degrees offered by universities with the technology and support of Coursera and edX will be one- half or one-quarter as expensive as typical U.S. professional online credentials, with the bulk of savings coming from a combination of larger class sizes, fewer or no synchronous sessions, reduced contact with instructors, and more autograded assignments (12).

    This is precisely the value proposition that the digital homework solution—courseware’s older sibling—brought to the face-to-face lecture hall in survey-level courses. Digital assessment is what enabled those courses to swell to 500 or more students. The authors continue,

    Because MOOC platforms support programs that look more like “traditional” online higher education, the literature on online learning can provide guidance. By most indications, students typically do worse in online courses than in on-campus courses, and the challenges of online learning are particularly acute for the most vulnerable populations of first generation college students, students from low-income families, and underrepresented minorities (13). If low-cost, MOOC-based degrees end up recruiting the kinds of students who have historically been poorly served by online degree programs, student support programs will be vital. Some recent research has explored online and text-message–based interventions for supporting these students, but most research suggests that human connections through advisers, tutors, and peer groups provide the most important student supports (14). These human supports will push against lower tuition costs. MOOC- based degree providers may find that highly effective online learning for diverse populations costs about the same to provide as highly effective residential learning (12).

    When you start playing with this balancing act in order to arrive at…ahem…an affordable degree at scale and quality, you likely end up with something that looks very much like the Georgia Tech solution. It’s not a free degree or a $1,000 degree. It might be a $7,000 degree or a $14,000 degree. And that’s at the graduate level. It’s not clear that we know how to do this at the undergraduate level yet.

    But the more interesting implication vis-a-vis MOOC providers is that their value proposition starts looking more like that of modern courseware support with some services bundled in.

    As MOOC providers compete with conventional OPMs, there are entirely separate questions of financing the program development (via revenue share or some similar mechanism) and marketing. The MOOC providers have the advantage of their portals for marketing; students may go to Coursera or EdX to look for a credential program (as opposed to a full graduate degree program) before they’d go to their local university. I’ve not seen that proven, but at least it’s plausible. And the financing is what it is. Either you want a revenue share or you don’t.

    But as a genre of course, the population of xMOOCs is dying off. We don’t see it because we’re also calling the thing that is replacing them—which isn’t open—a “MOOC.” The collection of actual xMOOCs that are still functioning as full and (more or less) open courses is slowly shrinking to fit the size and shape of the professional non-degree credential market. Forking off from that is something that looks like a MOOC but is actually prepackaged courseware, to be licensed like a textbook and taught by individual instructors at different universities, with or without a face-to-face component. Then there’s this third thing—the affordable degree at scale—that is using MOOC and courseware affordances, which are increasingly the same affordances, to teach more students with similar learning outcomes at a lower cost. So far, only in professionally oriented graduate degree programs. And finally, there are zombie MOOCs that have no strong reason to exist and are being killed off by the platform providers for whom they are loss generators (sometimes to the dismay of the universities who invested considerable time and money in creating them).

    OK, maybe I was wrong. The word “disruption” is still relevant in at least one sense.

  • OPM Readings: New policy briefing from UCT and other useful coverage

    OPM Readings: New policy briefing from UCT and other useful coverage

    Over the past eight days there have been a series of valuable articles covering Online Program Management (OPM) and the broader Online Program Enablement (OPE) markets. ((See this post to better understand the OPE concept.)) All four articles provide useful historical and academic environment context to better understand market dynamics.

    University of Cape Town Policy Briefing

    Laura Czerniewicz and Sukaina Walji from the University of Cape Town’s Centre for Innovation in Learning and Teaching (CILT) released Issues for universities using private companies for online education this week as a policy briefing for “universities who are thinking of using – or already using – private companies to develop or expand their online programmes or courses” ((I’ll stick with the South African English spelling in this section.))

    Rather than just focusing on the OPM market itself, Czerniewicz and Walji place the subject into the broader context of “marketisation, digitisation, unbundling and austerity climates.” This placement is valuable, as it frames the appropriate questions that colleges and universities should address when considering OPM or OPE vendor support.

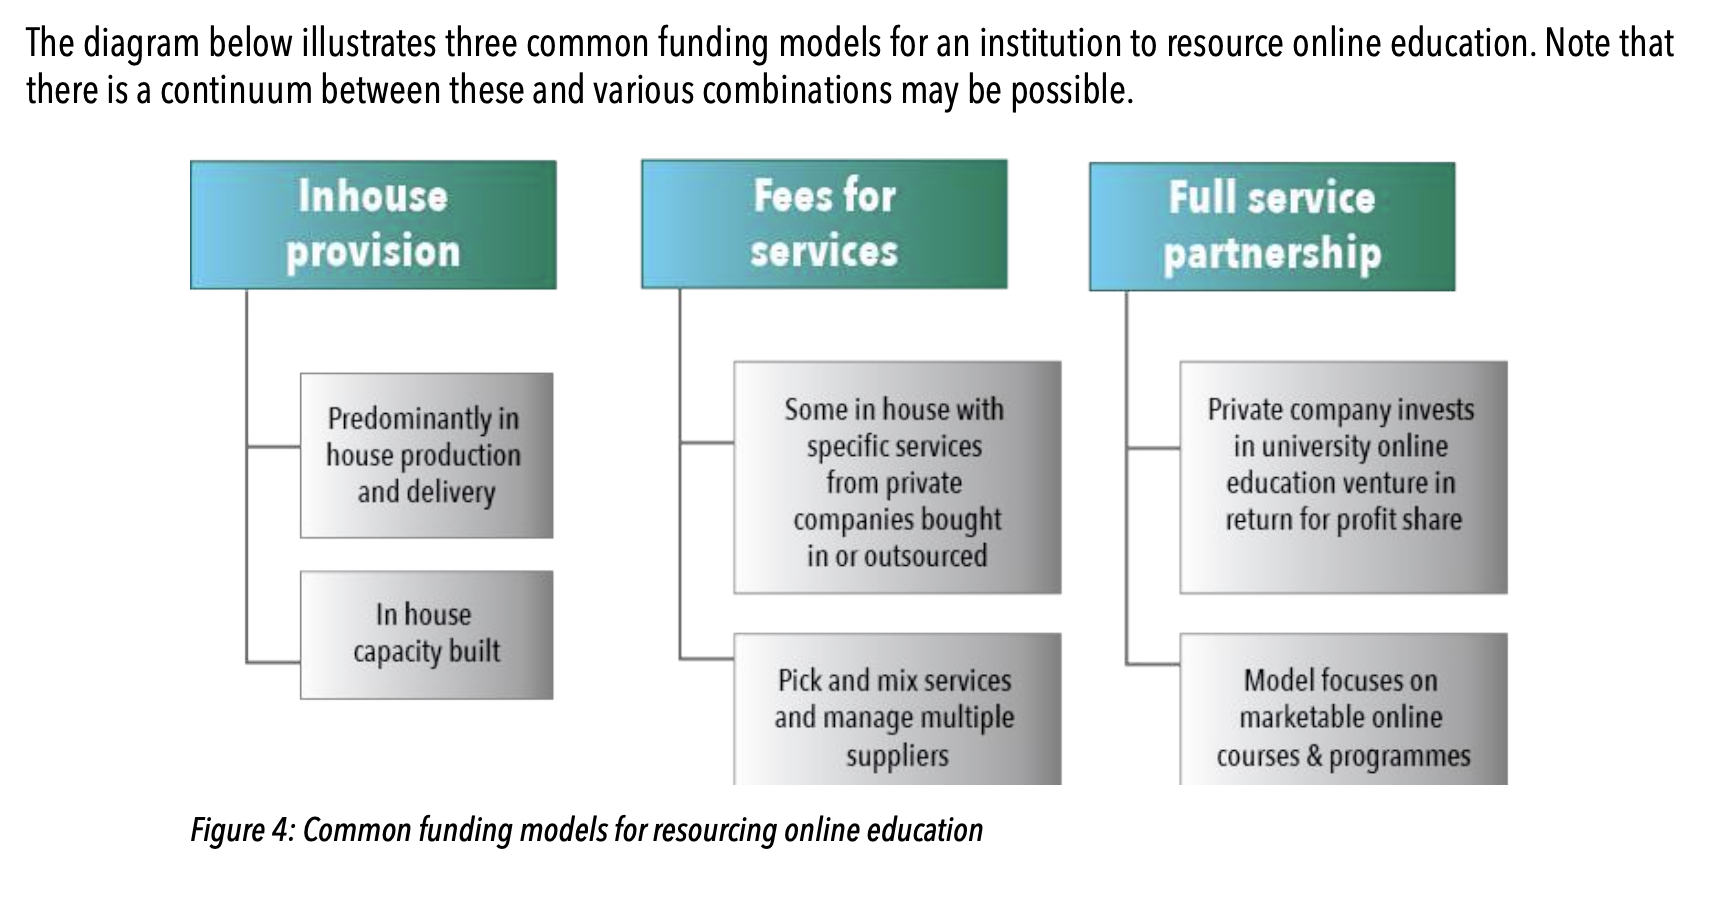
    After addressing why the OPM / OPE movement is becoming so important now – from an international perspective with some global south viewpoitns  – the briefing addresses the various funding models involved. The note in the description about these models being on a continuum with various combinations possible is crucial.

    Three common funding models - inhouse provision, fees for services, and full service partnership

    The briefing including a Strengths, Weaknesses, Opportunities, Threats (SWOT) analysis for the full-service OPM scenario and for an inhouse / fees-for-service scenario as well as use cases for different institution types. It is well-worth reading the whole report.

    EdSurge Debate on OPMs

    Last week EdSurge ran a two-article series on OPMs that missed the SNL’s Point / Counterpoint opportunity and instead tried the nuanced argument method.

    Dan, you pompous ass

    In the first post “How OPMs are the Modern Enrollment Managers”, Randy Best and Harris Pastides from Academic Partnerships described OPMs as a follow-on to the enrollment management companies that emerged in the 1970s, with OPMs partially taking credit for moving away from the for-profit sector.

    These OPMs, like enrollment management consultants decades before, assist universities in providing access to time-pressed, place-bound students for whom online education is the only choice for earning a degree. In doing so, OPMs shifted leadership in the market for online education from for-profit institutions, which dominated the landscape in the early days, to nonprofit institutions.

    After addressing four myths about OPMs, Best and Pastides position full-service revenue-sharing OPMs against the new movement of fee-for-service OPM / OPE providers.

    Given the evolution of OPMs, perhaps the time has come for a new name to describe them. They are not just managers, but partners with universities. They don’t just oversee programs, but perform operations critical to the overall success and reputation of the institution. And their efforts often result in the expansion of overall enrollment. In many ways, they should be called Enrollment Growth Partners.

    Some players in the OPM space who are not traditional comprehensive providers are trying to adopt the mantle of the future with fee-for-service or unbundled offerings. But fee-for-service simply shifts the cost and financial risk to universities. Meanwhile, by unbundling services—say by separating recruitment and retention—outside partners become solely focused on getting students in the door rather than keeping them through graduation.

    Michael wrote the second post “The ‘O’ in ‘OPM’ Could Stand for ‘Outsourcing’”, where instead of taking the simple pro / con approach to the debate, he argued for some nuance in our analysis. In particular, he took issue with the quoted description above.

    Michael’s historical context story differed from Best and Pastides, describing John Sperling’s history creating the University of Phoenix and how the current context for bundling and revenue models.

    The essential OPM characteristics of bundling and revenue sharing, both of which Pastides and Best tout as almost inherently good, contain trade-offs just like any other proposed solution to a complex problem. They balance growth opportunity against a range of risks, including risk that the up-front costs of launching the program would not be repaid, or that the universities could not execute well on essential aspects of the project (like student recruitment), or that they would let down the students by failing to maintain good quality of technology platform support or service at scale.

    There’s nothing inherently bad about managing these trade-offs through a full-service, bundled revenue sharing agreement. But there’s nothing inherently superior about the approach either. For example, universities that are more worried about the risk of failing to grow fast enough than they are about minimizing the expense of using an external vendor are often well served by finding a high-quality OPM partner, while universities with different risk profiles may come to different yet equally appropriate conclusions.

    Both posts are worth reading, and it is interesting to see the same issue described here and in the UCT briefing – about colleges and universities managing trade-offs when deciding which model is appropriate when selecting private partners to help with online programs.

    Education Dive

    Education Dive is running a three-part series on the issues involved with federal rule-making debates, and the first deep dive is “As traditional colleges grow online, OPM relationships shift”, describing the broadening market while traditional schools and systems like SUNY look to develop a strategy for online education.

    The State University of New York (SUNY) is one of several public systems looking to raise its profile online. An early pioneer with its Open SUNY platform, the 64-campus system in July issued a request for information about how it could “take the next step in creating a comprehensive environment” for online learning within and beyond New York state. [snip]

    The document, which Education Dive obtained, mentions a desire to “leapfrog competition” and “challenge current leaders in the field.”

    The article explores several of the OPM-related topics as well as motivations for traditional institutions developing online strategy, based on a series of interviews that included Michael. The key theme of the article described how the OPM market is changing, and the boundaries between online and face-to-face education are blurring.

    Soliciting OPM services for ground-based and hybrid programs can help colleges present a unified face in the market when they offer both on-campus and online versions of a program. Wiley, for example, provides full-service marketing support targeting prospective students for George Mason’s online and campus-based MBAs. That includes SEO, paid search, online advertising and social media.

    “The dialogues (are) more and more moving toward broadening the services to be more than just about the fully online student (but) to be about the student at the university no matter what their modality,” [co-president of Wiley Education Services and Learning House] Hillman said.

    That could lead to an uptick in blended and hybrid experiences, [co-founder and CEO of iDesign] Riter predicts, where learners navigate instruction online and on campus.

    “Over time there’s going to be less difference between online and face-to-face education,” he said. “It’s just going to be education, and even face-to-face residential education that exists today is going to be much more technologically infused.”

    It’s good to see four separate articles all worth reading about the emerging and broadening OPM market, with useful context.

  • Insight into Community College Students and Challenges of Online Education

    Insight into Community College Students and Challenges of Online Education

    Inside Higher Ed reported today on a new survey report on community colleges and challenges that students face.

    Most community colleges are aware of the challenges students face if they are working, raising children or struggling to afford textbooks. But a newly released survey digs into the nuances of those challenges so colleges can pinpoint ways to lift barriers to college completion and prevent students from dropping out.

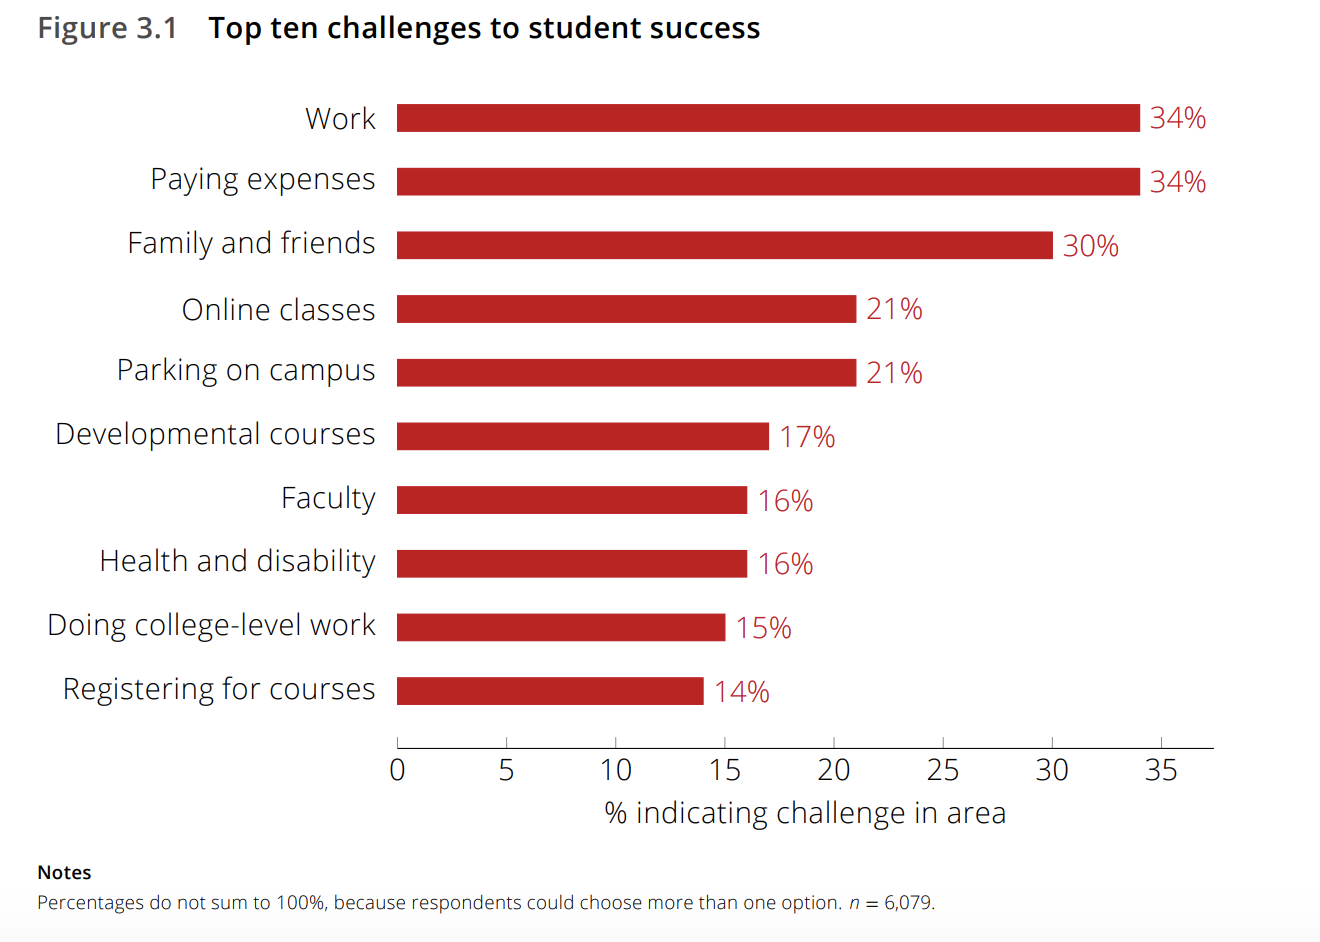
    Researchers at North Carolina State University designed and encouraged students to participate in the Revealing Institutional Strengths and Challenges survey. The survey found that working and paying for expenses were the top two challenges community college students said impeded their academic success. The researchers surveyed nearly 6,000 two-year college students from 10 community colleges in California, Michigan, Nebraska, North Carolina, South Dakota, Texas, Virginia, Wisconsin and Wyoming in fall 2017 and 2018.

    Of the top ten challenges listed, the category of online classes was tied for fourth along with parking in an ironic twist as lack of physical facilities is one of the drivers for the growth in online education. Interestingly for parking, it is not the costs. 86% of those listing parking stated it was “difficulty finding parking on or near campus” and only 10% listed parking as too expensive.

    Top Ten challenges for community college students

    The value of this survey, as described at IHE in interviews with the report authors, is in the nuance that can guide institutional planning.

    [Report authors] Umbach and Steve Porter, also a professor of higher education at the university, said they noticed a dearth of surveys that asked students about the barriers they face to completing college and wanted to provide a tool that colleges could use to eliminate those barriers and boost graduation rates.

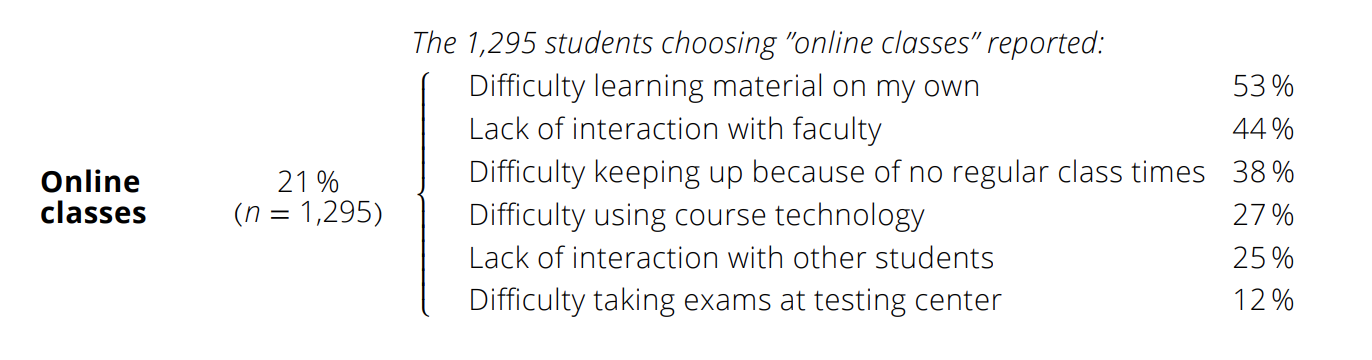
    On the topic of online education as a barrier, one view of the results could be that only one out of five students have a problem with these classes, which is not problematic as we have long known that online is not for everyone. On the other hand, the nuance provided should give institutions some insight into how they can improve their services to students.

    Reasons for online classes as a challenge

    The big issue that I’ve seen in the field is not whether a school should offer online classes – in so many cases this is the only way for students to have access to degrees – but how well-designed the courses are and how much support is provided outside of the course. Throwing courses online with no real interaction or adequate support is a recipe for disaster here, as I described in one case last year. But the school in that example is not alone in this regard. In the many cases where community colleges make these mistakes, students should have difficulty learning and the 21% number should be problematic.

    But on the opposite side, when colleges focus on improving course design and extend meaningful support services, student outcomes improve dramatically. Consider the California Community College system and their improved outcomes, where their most recent distance education report shows system-wide closing of the achievement gap between face-to-face and online students. Online education can work for community college students and is an important part of student access, but there are no silver bullets.

    I was quoted in the article about these challenges.

    Hill said the California Community College System’s Online Education Initiative, which he worked on as a consultant, is a good example of a well-designed online learning system. It helped close the gap between the rate of students successfully completing traditional courses and online classes from 17 percent in 2006 to 4 percent in 2016.

    To be clear, the California Community College System in general has been improving their provision and support of online courses for years, and OEI is not the only driver of this change.

    CCCS improvements in gap of online ed

    I don’t think the California Community College System is the only example of improvements in online education support, but I do think their focus on improving course design as well as improving advising and support structures is worth considering.

    The problem of ‘difficulty learning material on my own’  and ‘difficulty keeping up’ issues can only partially be addressed – online education is not for everyone – but more engaging and well-designed online courses can help, or at least reduce barriers. The mixing of synchronous elements of a course along with asynchronous can also play an important role.

    ‘Lack of interaction with faculty’, ‘lack of interaction with other students’, and ‘difficulty using course technology’, however, are issues that should be addressed by the institution as part of the course design and support services. It would be naive to think that these issues could be eliminated, but there is no excuse for schools to not have a coordinated effort to make improvements across all online courses.

    Online education can work, and community colleges can improve outcomes by addressing the challenges students face.

    While this post focuses on the online education angle, the whole report is worth reading. The insights into issues outside the classroom, particularly for students trying to balance work and family commitments with their education, should provide valuable input into institutional- and system-level planning.