e-Literate

Present is Prologue

Tag: IPO

  • Interview with Josh Coates, CEO of Instructure, on today’s IPO

    Instructure, maker of the Canvas (higher ed and K-12 markets) LMS and Bridge (corporate learning market) LMS, held their Initial Public Offering today. Prior to the IPO, Wall Street analysts focused on the company’s growth, its large losses, and the challenges of the education market. The company was priced on the lower end of its range ($16.00), and closed up 12.5% at $18.00.

    This IPO and its lead up have been highly watched, particularly given the rapid growth in ed tech investments and questions on whether there are real businesses to emerge based on the investments. I had the opportunity to interview CEO Josh Coates today. What follows is an edited version of the interview, focusing mostly on how Instructure’s IPO will impact education markets and existing customers. I tried to capture as much of the Q&A verbatim as was feasible, but treat the answers below as a paraphrase.

    Q. What are your impressions on how the IPO has gone so far?

    A. The market in general has been a blood bath [ed. Dow down 585, or 3.3%, for the week], but we’re doing well so far. Given market conditions right now, we’re pleased as punch. We priced in range [ed. $16 – $18], and the market responding well. We’re really focused as a company 6-12 months down the road, but it is nice to get this IPO feedback. (more…)

  • Instructure Files for IPO

    This doesn’t exactly come as a shock, but Instructure has filed for an IPO, and is expecting a post-IPO valuation of somewhere between $500 million and $800 million. Whenever a private company does this, they have to file a form called an S-1 with the SEC, which contains all kinds of financial and strategic information. You can find Instructure’s here.

    Also not a big surprise, but the numbers in the report show big growth. Subscription revenue rose 72% from 2013 to 2014. Coincidentally, Edutechinica just published its 3rd annual LMS Data Update. As you can see, Canvas went through the roof in US higher ed while the other major LMS players were either flat or close to it:
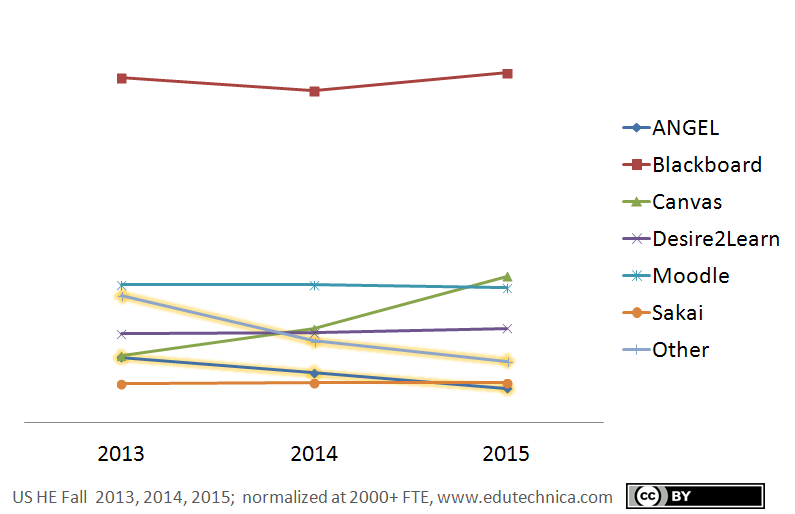
    But in order to achieve that growth, they have been running at a loss. The problem seems to be in high expenses rather than low revenues, which suggests that the losses are coming from the company bulking up rather than from them undercutting the competition on price. Also, most of those revenues still come from the US. Instructure has offices in London, Hong Kong, and Sydney. That’s not a huge international presence. And as it happens, Eductechnica has data for the UK and Australia:
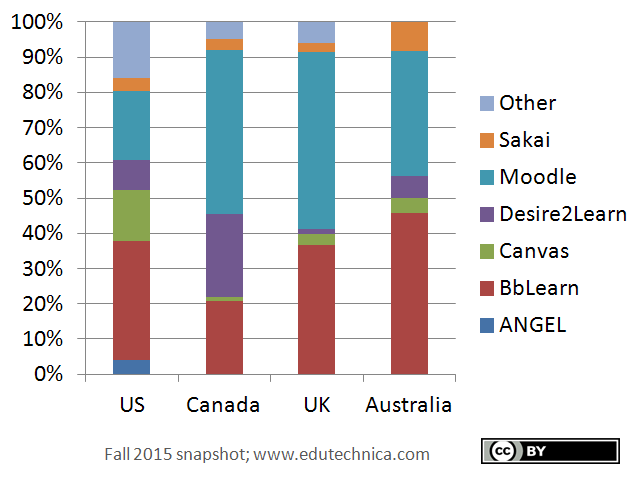
    You can see that Instructure has not made a major dent yet in either country. (You can also see that their biggest competitor by far in those two countries is Blackboard, particularly when you consider that Blackboard now owns major Moodle hosting operations in both countries.)

    One last bit that jumped out at me after a quick scan of the S-1 wasn’t financial. Their characterization of analytics was interesting. Throughout the document, they try to make the case that high user engagement and utilization lead to better learning analytics. For example,

    Strong User Engagement Leads to Robust Data Analytics

    Given today’s focus on accountability and performance, both academic institutions and companies are striving to improve learning outcomes. To do so, an organization must first understand the variables that impact results, such as attendance metrics, user engagement, and the efficacy of various learning content and technologies for individual learners. A learning management system has the potential to provide significant insight to educators and administrators on their students’ and employees’ progress toward meeting learning objectives and the factors impacting performance. In addition, such learning management systems can facilitate insightful benchmarking to allow organizations to explore other drivers of learning outcomes.

    Strong user engagement with learning management systems is critical to maximize the potential of data analytics. High utilization enables the learning management system to capture more data, and leads to more insightful analyses on user behavior, quality of individual courses and effectiveness of digital content. Better analytics enables instructors and administrators to make more informed decisions about instruction and materials that in turn drive improved learning outcomes and performance for individuals and companies. This virtuous cycle among user engagement, data analytics and learning outcomes represents the evolution of learning technology. We believe that the market increasingly is demanding learning management software that delivers both robust analytics and strong user engagement.

    They later go on to say,

    Over eight million instructors, students and employees have used our software over the 12 months ended June 30, 2015. According to self-reported data in an ECAR 2014 survey, 58% of faculty in higher education use a learning management system to share content with students, while our internal analysis of higher education institutions using Canvas shows that 71% of faculty use Canvas to share content with students.

    But their claim in terms of what they actually have for data analytics is fairly weak:

    Our platform provides users with open API access to data analytics. We deliver the analytics in an easy to understand and consumable way, that is optimized for independent analysis. This open visibility allows learners to view their own progress in real-time, educators to adjust programs and personalize curricula for maximum effectiveness and organizations to benchmark user data internally and respond to patterns observed.

    They are not arguing that they have good analytics, but rather that the high utilization of the software plus open APIs will enable customers to build good analytics themselves.
  • Reuters: Instructure has filed for IPO later this year

    Reuters is on a breaking news roll lately with ed tech. This time it is about Instructure filing for an initial public offering (IPO).

    Instructure is planning an initial public offering later this year that could value the education software company at $500 million to $800 million, according to people familiar with the matter.

    Instructure, based in Salt Lake City, has hired Morgan Stanley (MS.N) and Goldman Sachs (GS.N) to help prepare for the IPO, which has been filed confidentially, the people said. They requested anonymity because the news of the IPO was not public.

    Under the Jumpstart Our Business Startups Act, new companies that generate less than $1 billion in revenue can file for IPOs with the U.S. Securities and Exchange Commission without immediately disclosing details publicly.

    Instructure has long stated its plans to eventually IPO, so the main question has been one of timing. Now we know that it is late 2015 (assuming Reuters story is correct, but they have been quite accurate with similar stories). (more…)

  • Instructure: Accelerating growth in 3 parallel markets

    I’m not sure which is more surprising – Instructure’s continued growth with no major hiccups or their competitors’ inability after a half-decade to understand and accept what is at its core a very simple strategy. Despite Canvas LMS winning far more new higher ed and K-12 customers than any other vendor, I still hear competitors claim that schools select Canvas due to rigged RFPs or being the shiny new tool despite having no depth or substance. When listening to the market, however, (institutions – including faculty, students, IT staff, academic technology staff, and admin), I hear the opposite. Canvas is winning LMS selections despite, not because of, RFP processes, and there are material and substantive reasons for this success.

    The only competitor I see that seems to understand the depth of the challenge they face is Blackboard. Other LMS solutions are adding “cloud” options or making incremental improvements to usability, but only Blackboard is going for wholesale changes to both its User Experience (UX) and cloud hosting architecture. Unfortunately, I question whether Blackboard will be able to execute this strategy, but that is a story for another post.

    Like last year’s post about InstructureCon, I believe that the company growth chart ((The chart shows the number of clients, which is essentially the number of contracts signed with institutions, school districts, or statewide systems adopting either Canvas or Bridge LMS products.)) gives a lot more information than just “gosh, we’re doing well”. (more…)

  • 2U Learning Platform Update: Removal of Moodle, addition of accessibility options

    2U has now been a public company for over a year, and that had what is easily the most successful education IPO in recent history. Shares have almost doubled from $13.00 at IPO to $25.50 last week. At the same time, there is a swirl of news around their new partner Yale and the Physician Assistant’s program – first the announcement of program from one of the elite of elite schools, second the news that accreditation approval for the new program is not going to be as easy as hoped.

    While both aspects are newsworthy, I’d like to dive deeper into their infrastructure and learning platforms. The company is far from complacent, as they continue to make significant changes. (more…)

  • First View of Bridge: The new corporate LMS from Instructure

    Last week I covered the announcement from Instructure that they had raised another $40 million in venture funding and were expanding into the corporate learning market. Today I was able to see a demo of their new corporate LMS, Bridge. While Instructure has very deliberately designed a separate product from Canvas, their education-focused LMS, you can see the same philosophy of market strategy and product design embedded in the new system. In a nutshell, Bridge is designed to a simple, intuitive platform that moves control of the learning design away from central HR or IT control and closer to the end user.

    While our primary focus at e-Literate is on higher ed and even some K-12 learning, the development of professional development and corporate training markets are becoming more important even in the higher ed context. At the least, this is important for those who are tracking Instructure and how their company plans might affect the future of education platforms.

    The core message of Instructure regarding Bridge – just as with Canvas – is that it is focused on ease-of-use whereas the entrenched competition has fallen prey to feature bloat based on the edge cases. Despite this claim and despite Instructure’s track record with Canvas, what does this mean? I’m pretty sure every vendor out there claims ease-of-use whether or not there are elegant or terrible designs ((Although I would love to see the honest ad: “With a horrible, bloated user interface based on your 300-item RFP checklist!”)).

    Based on the demo, Bridge appears to define ease-of-use in three distinct areas – streamlined, clutter-free interface for learners, simple tools for content creation by business units, and simple tools for managing learners and content. (more…)

  • What TechCrunch Got Wrong (and Right) About Instructure Entering Corporate Learning Market

    After yesterday’s “sources say” report from TechCrunch about Instructure – maker of the Canvas LMS – raising a new round of financing and entering the corporate LMS space, Instructure changed plans and made their official announcement to today. The funding is to both expand the Canvas team and to establish the new corporate LMS team. I’m not a fan of media attempts to get a scoop based purely on rumors, and in this case TechCrunch got a few items wrong that are worth correcting.

    • Instructure raised $40 million in new financing (series E), not “between $50 to $70 million”. TechCrunch did hedge their bets with “low end of the range at over $40 million”.
    • The primary competition in the corporate LMS space is Saba, SumTotal, Skillsoft, Cornerstone – and not Blackboard.
    • The Canvas LMS was launched in 2010, not 2011. (OK, I’ll give them this one, as even Instructure seems to use the 2011 date).

    TechCrunch did get the overall story of fund-raising and new corporate product right, but these details matter.

    Instructure’s new product for the corporate learning market is called Bridge, with its web site here. This is an entirely new product, although it does share a similar product architecture as Canvas, the LMS designed for the education market (including being based on Ruby on Rails). Unlike Canvas, Bridge was designed mobile-first, with all mobile capabilities embedded in the product and not as separate applications. In an interview with Josh Coates, CEO of Instructure, he described their motivation for this new product.

    We like the idea of building software that helps people get smarter. Post education there is a void, with bad corporate software.

    (more…)