e-Literate

Present is Prologue

Tag: LMS

  • North American Higher Ed LMS Market Share by Enrollments: A consolidating market

    North American Higher Ed LMS Market Share by Enrollments: A consolidating market

    We have published market share data measured by total institutional enrollment instead of institutional count in several posts at e-Literate over the years, within the twice-annual reports of our LMS Market Analysis service, and for several of our premium subscribers of the same service. In July of this year we reported that Canvas had overtaken Blackboard as the market leader in US higher education in terms of institutional adoptions as well as scaled by enrollment. These last two posts got a fair amount of media and vendor attention.

    What we have realized, however, is that we have not made this information on market share by enrollment easy to access in one place. LMS company revenue tends to be based on the total enrollment of adopting institutions, thus this enrollment-based measure provides a more direct connection to company finances. Given the increased importance of LMS provider business models and revenue to the future trends of the market, we are sharing the information more broadly.

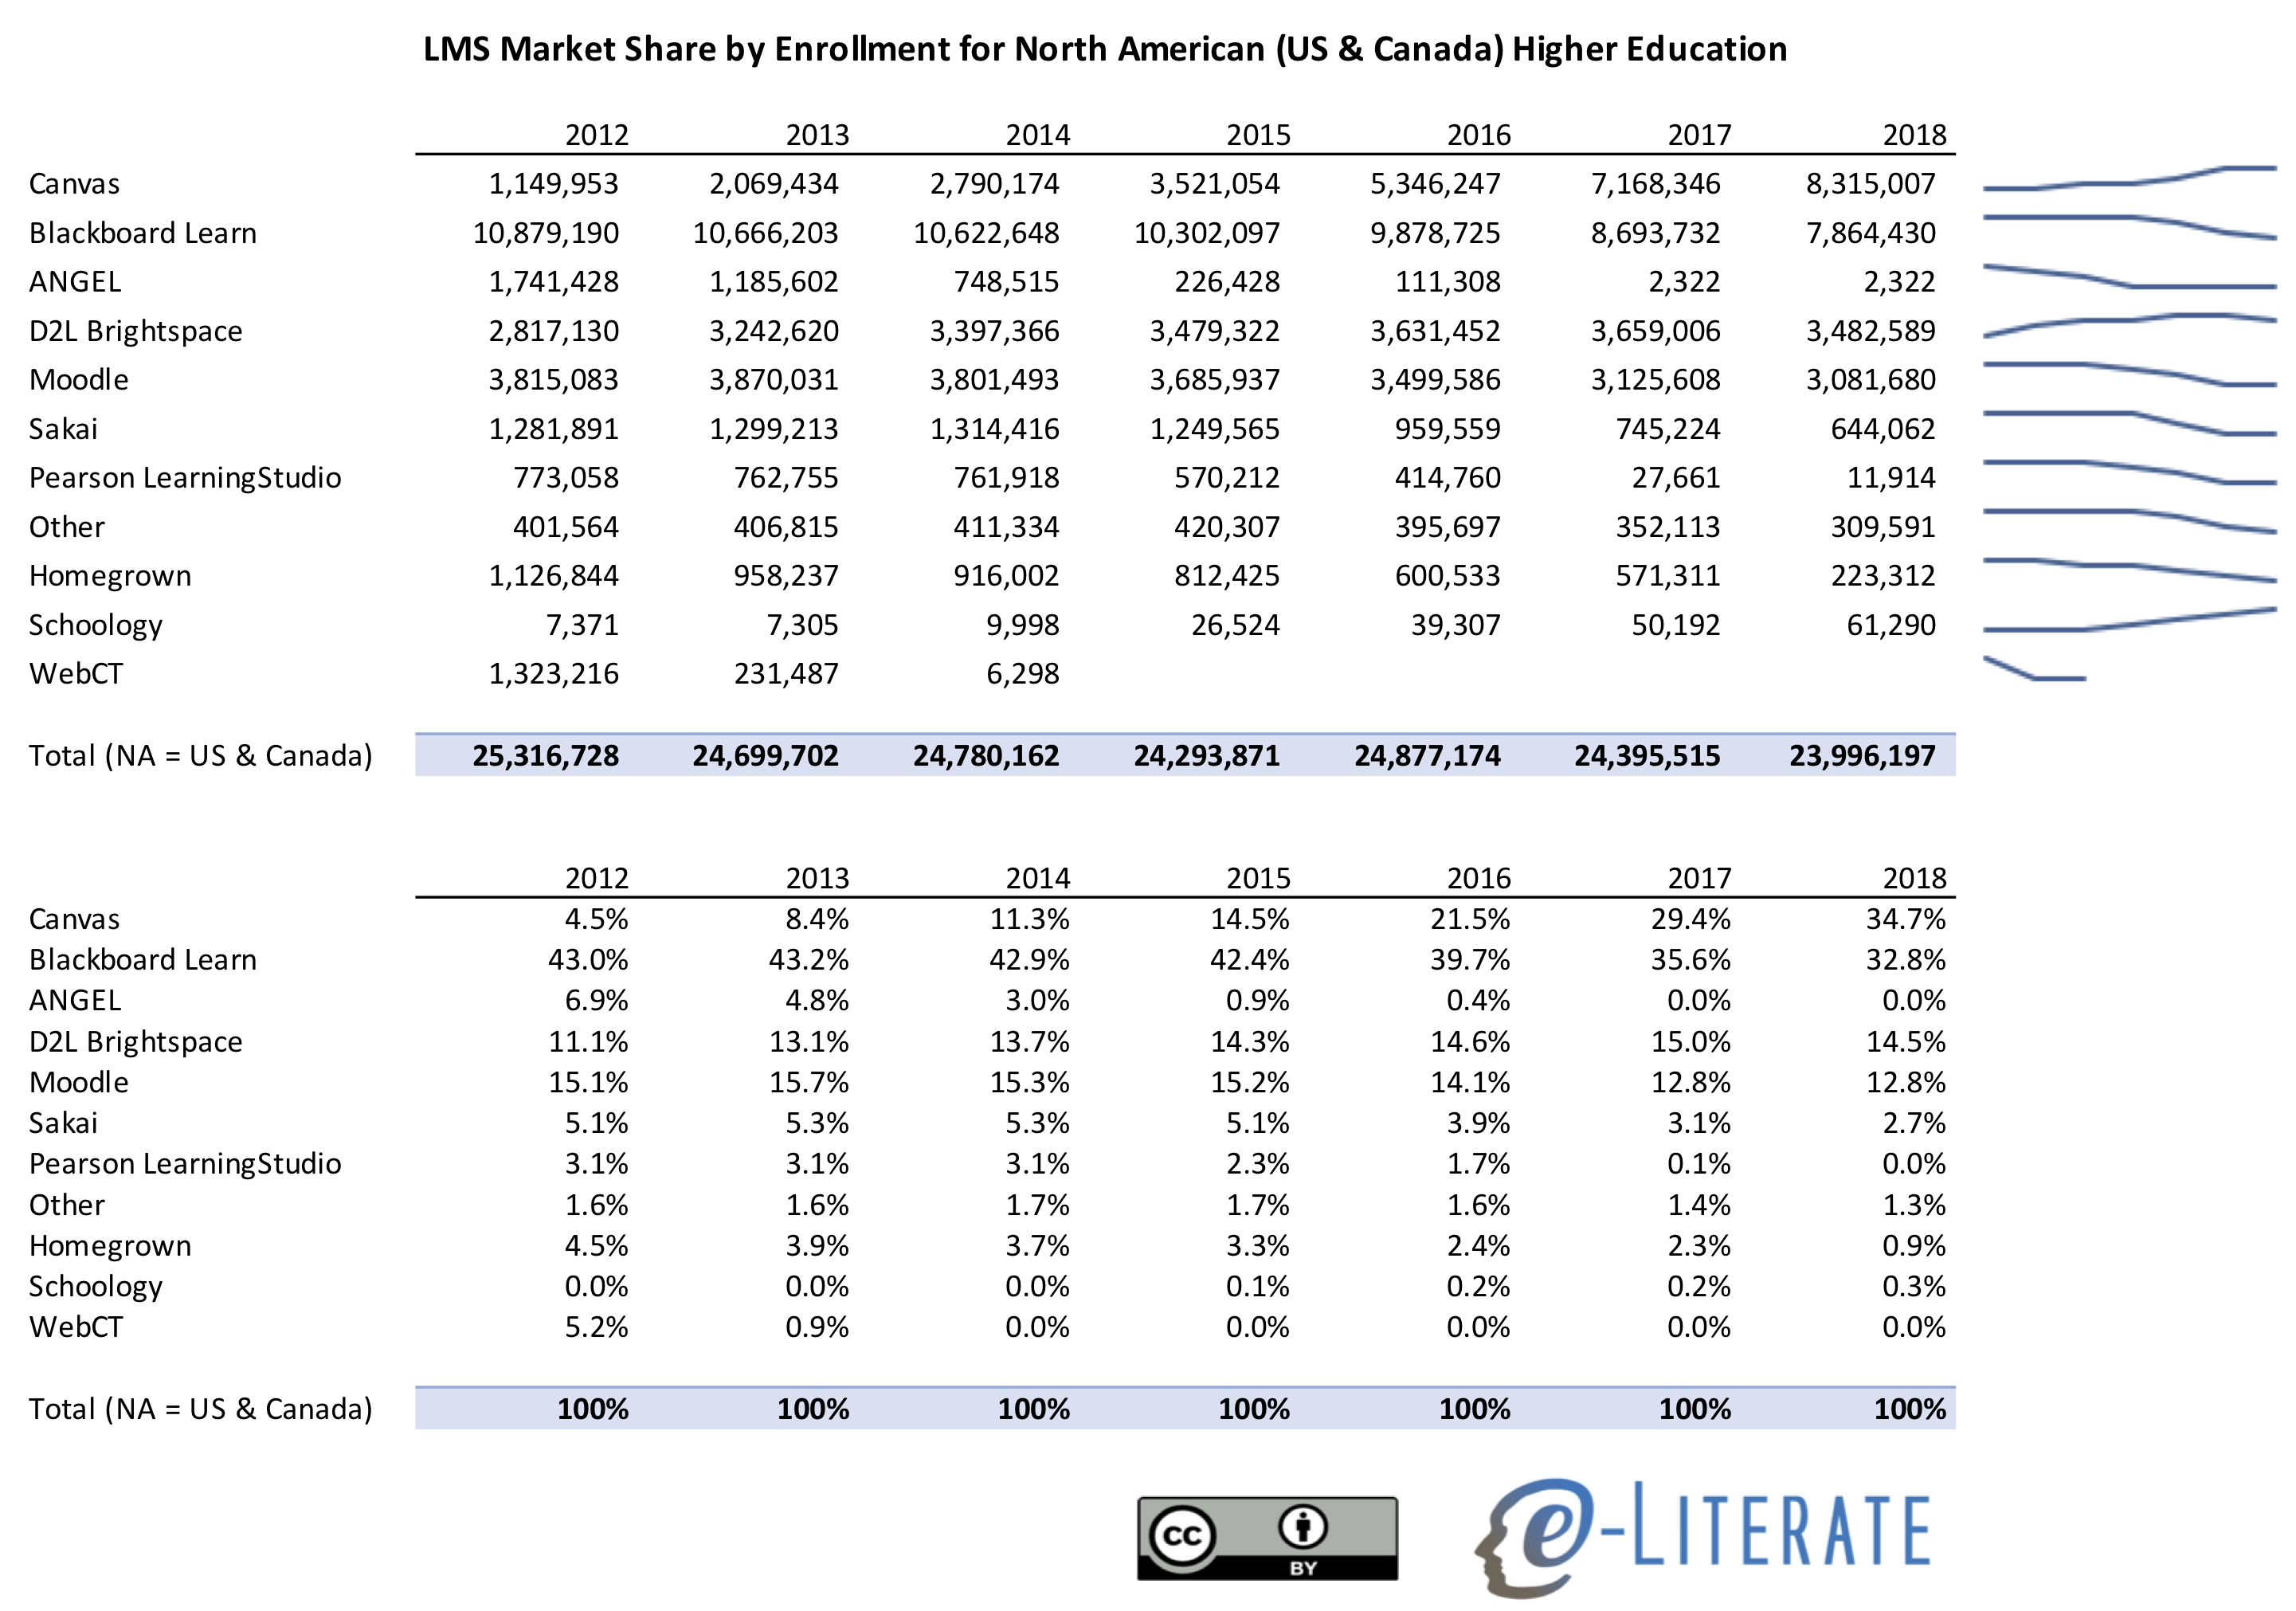
    In this view below we share North American (US and Canada combined) total enrollment for LMSs that are primary – that is, available for the entire institution. Total enrollment in this case means the institutional student count, but it does not imply that all students at that institution actually have courses using the LMS (see comment below from John Fritz). It is important to note that during an LMS transition there is often a period of time (6 – 18 months) where two systems overlap, with both available to the school. Therefore the total market share enrollments will be somewhat higher than actual total enrollments, as a subset of LMS-transitioning institutions will be counted twice.

    You can download a spreadsheet version here.

    LMS Market Share by Enrollment NA HE

    Some notes on the data worth considering:

    • Canvas has not just surpassed Blackboard Learn in this updated view, 35% to 33% – it has also expanded its lead as the most-adopted LMS in North American higher ed markets (while Moodle has clear lead worldwide in total installed base).
    • D2L Brightspace has been in third place for NA HE markets since 2016 when viewing by enrollments.
    • Moodle is fourth and has been dropping in recent years.
    • The top view of total enrollments adds in the effect of changing enrollments – both at a national level and an institutional level.
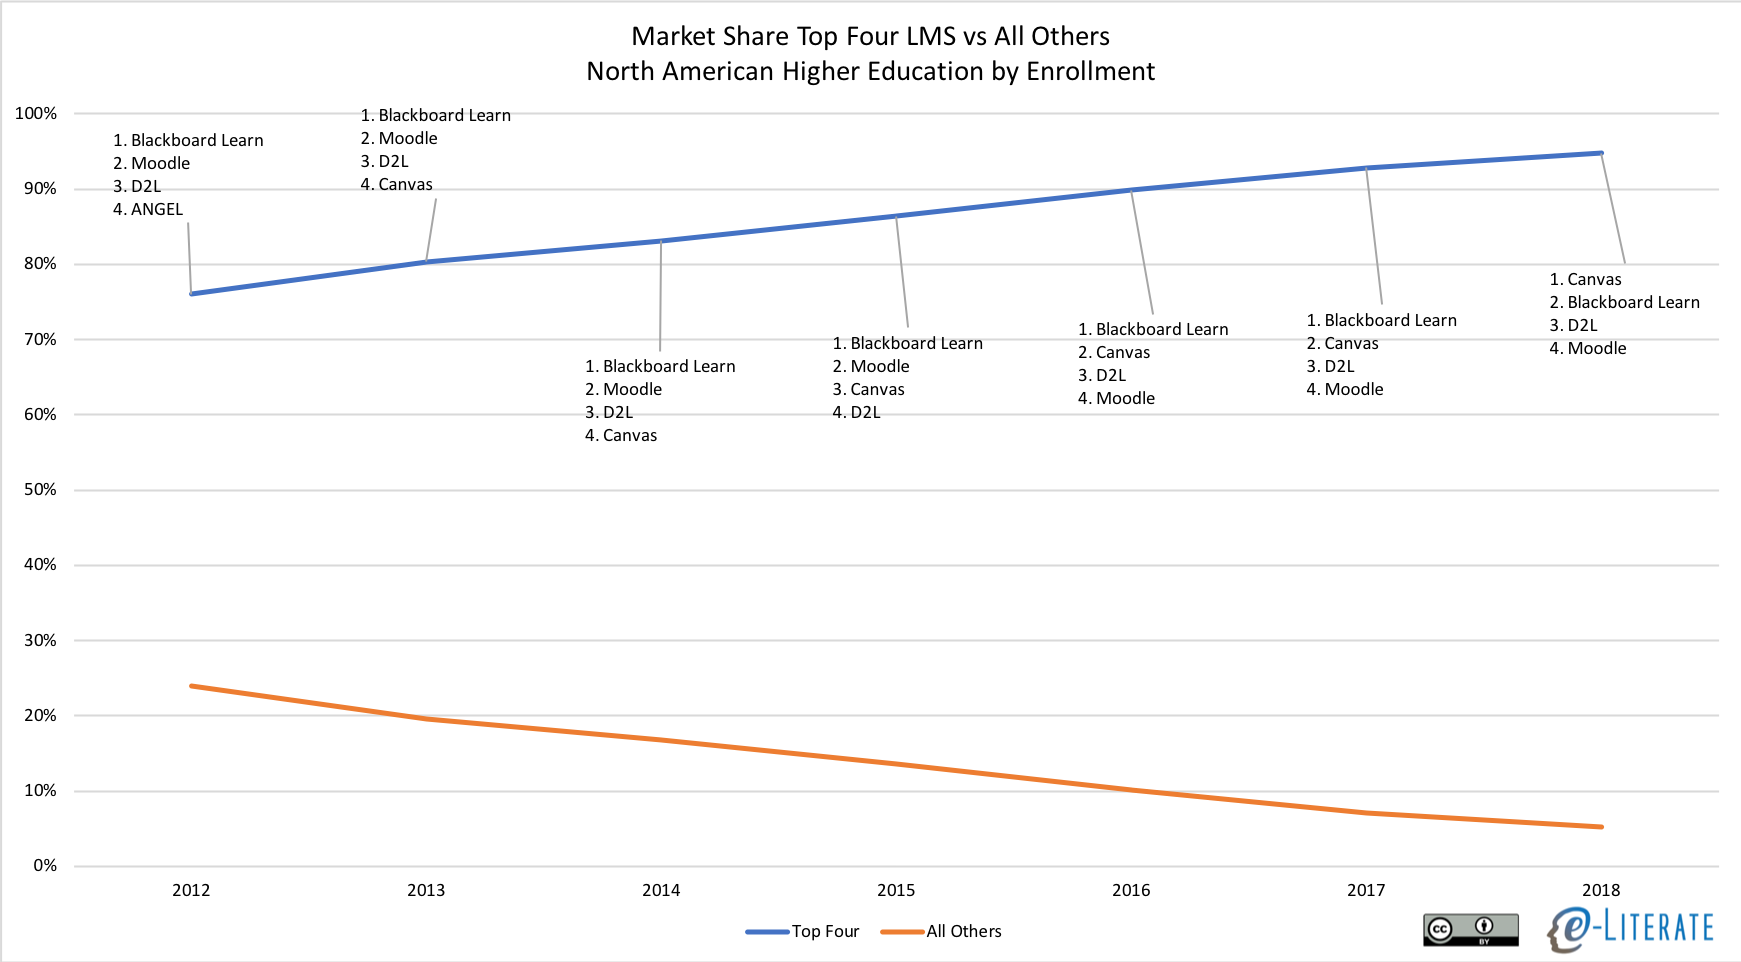
    • In the past five years, the LMS Market for North American higher ed has become increasingly dominated by “the Big Four” (Instructure Canvas, Blackboard Learn, D2L Brightspace, Moodle) for institution-wide adoptions; the aggregate market share of year’s top four systems moving from 80% to 95% in past five years.

    This last point deserves more analysis. There are other systems gaining new institutional clients (think Schoology here, or think CBE-specific platforms like Motivis), but they are mostly picking up either small schools or being adopted for specific programs and not for the entire institution.

    Consolidation of NA HE LMS Market

    Expect more coverage as we enter ed tech fall conference season.

    Update 8/3: Added sentence in third paragraph to clarify usage of total enrollment terminology.

  • Blackboard Learn Ultra in 2018: Is it ready and does it matter?

    Blackboard Learn Ultra in 2018: Is it ready and does it matter?

    One of our longest-running series of posts is on the prospects and status of Blackboard’s Learn Ultra, the user experience redesign and move to the cloud of the world’s second-most-used (behind Moodle) and highest-revenue-producing academic LMS. It is fashionable to claim the LMS is dead or passé, yet this product category remains the centerpiece of educational technology at colleges, universities, and K-12 districts. To understand Learn Ultra is to understand much of the overall LMS market.

    Looking at the timeline of e-Literate coverage, the broad story emerges:

    • 2012: Blackboard acquires Moodlerooms, and one benefit was the see of a cloud-based platform strategy.
    • 2014: Blackboard prematurely announced Learn Ultra (new user experience) and Learn SaaS (move to the cloud).
    • 2015: Learn Ultra is already a year late (more realistically, the BbWorld14 announcement was wildly unrealistic), but the University of Phoenix selects Learn Ultra as its next-generation learning platform.
    • 2016: Blackboard switches CEOs, admits that Learn Ultra is still not ready, and struggles with a major messaging problem around the transition.
    • 2017: No coverage – maybe we got tired of lack of not having customers to talk to.
    • 2018: Blackboard makes Learn Ultra the core of its message at its users conference BbWorld18.

    (Note: It might be easier to view this as a full page timeline instead of the embed within this post.)

    What we have been asked multiple times, by institutions, by investors, by other ed tech companies: is Learn Ultra ready, and does it matter? The unsurprising answer to both questions is a qualified and somewhat confusing it depends. To describe a little further, Learn Ultra’s Base Navigation is ready, but the Course View is not ready for meaningful adoption; furthermore, Learn Ultra is important to Blackboard’s future, but we think SaaS is more important to its present.

    Is It Ready?

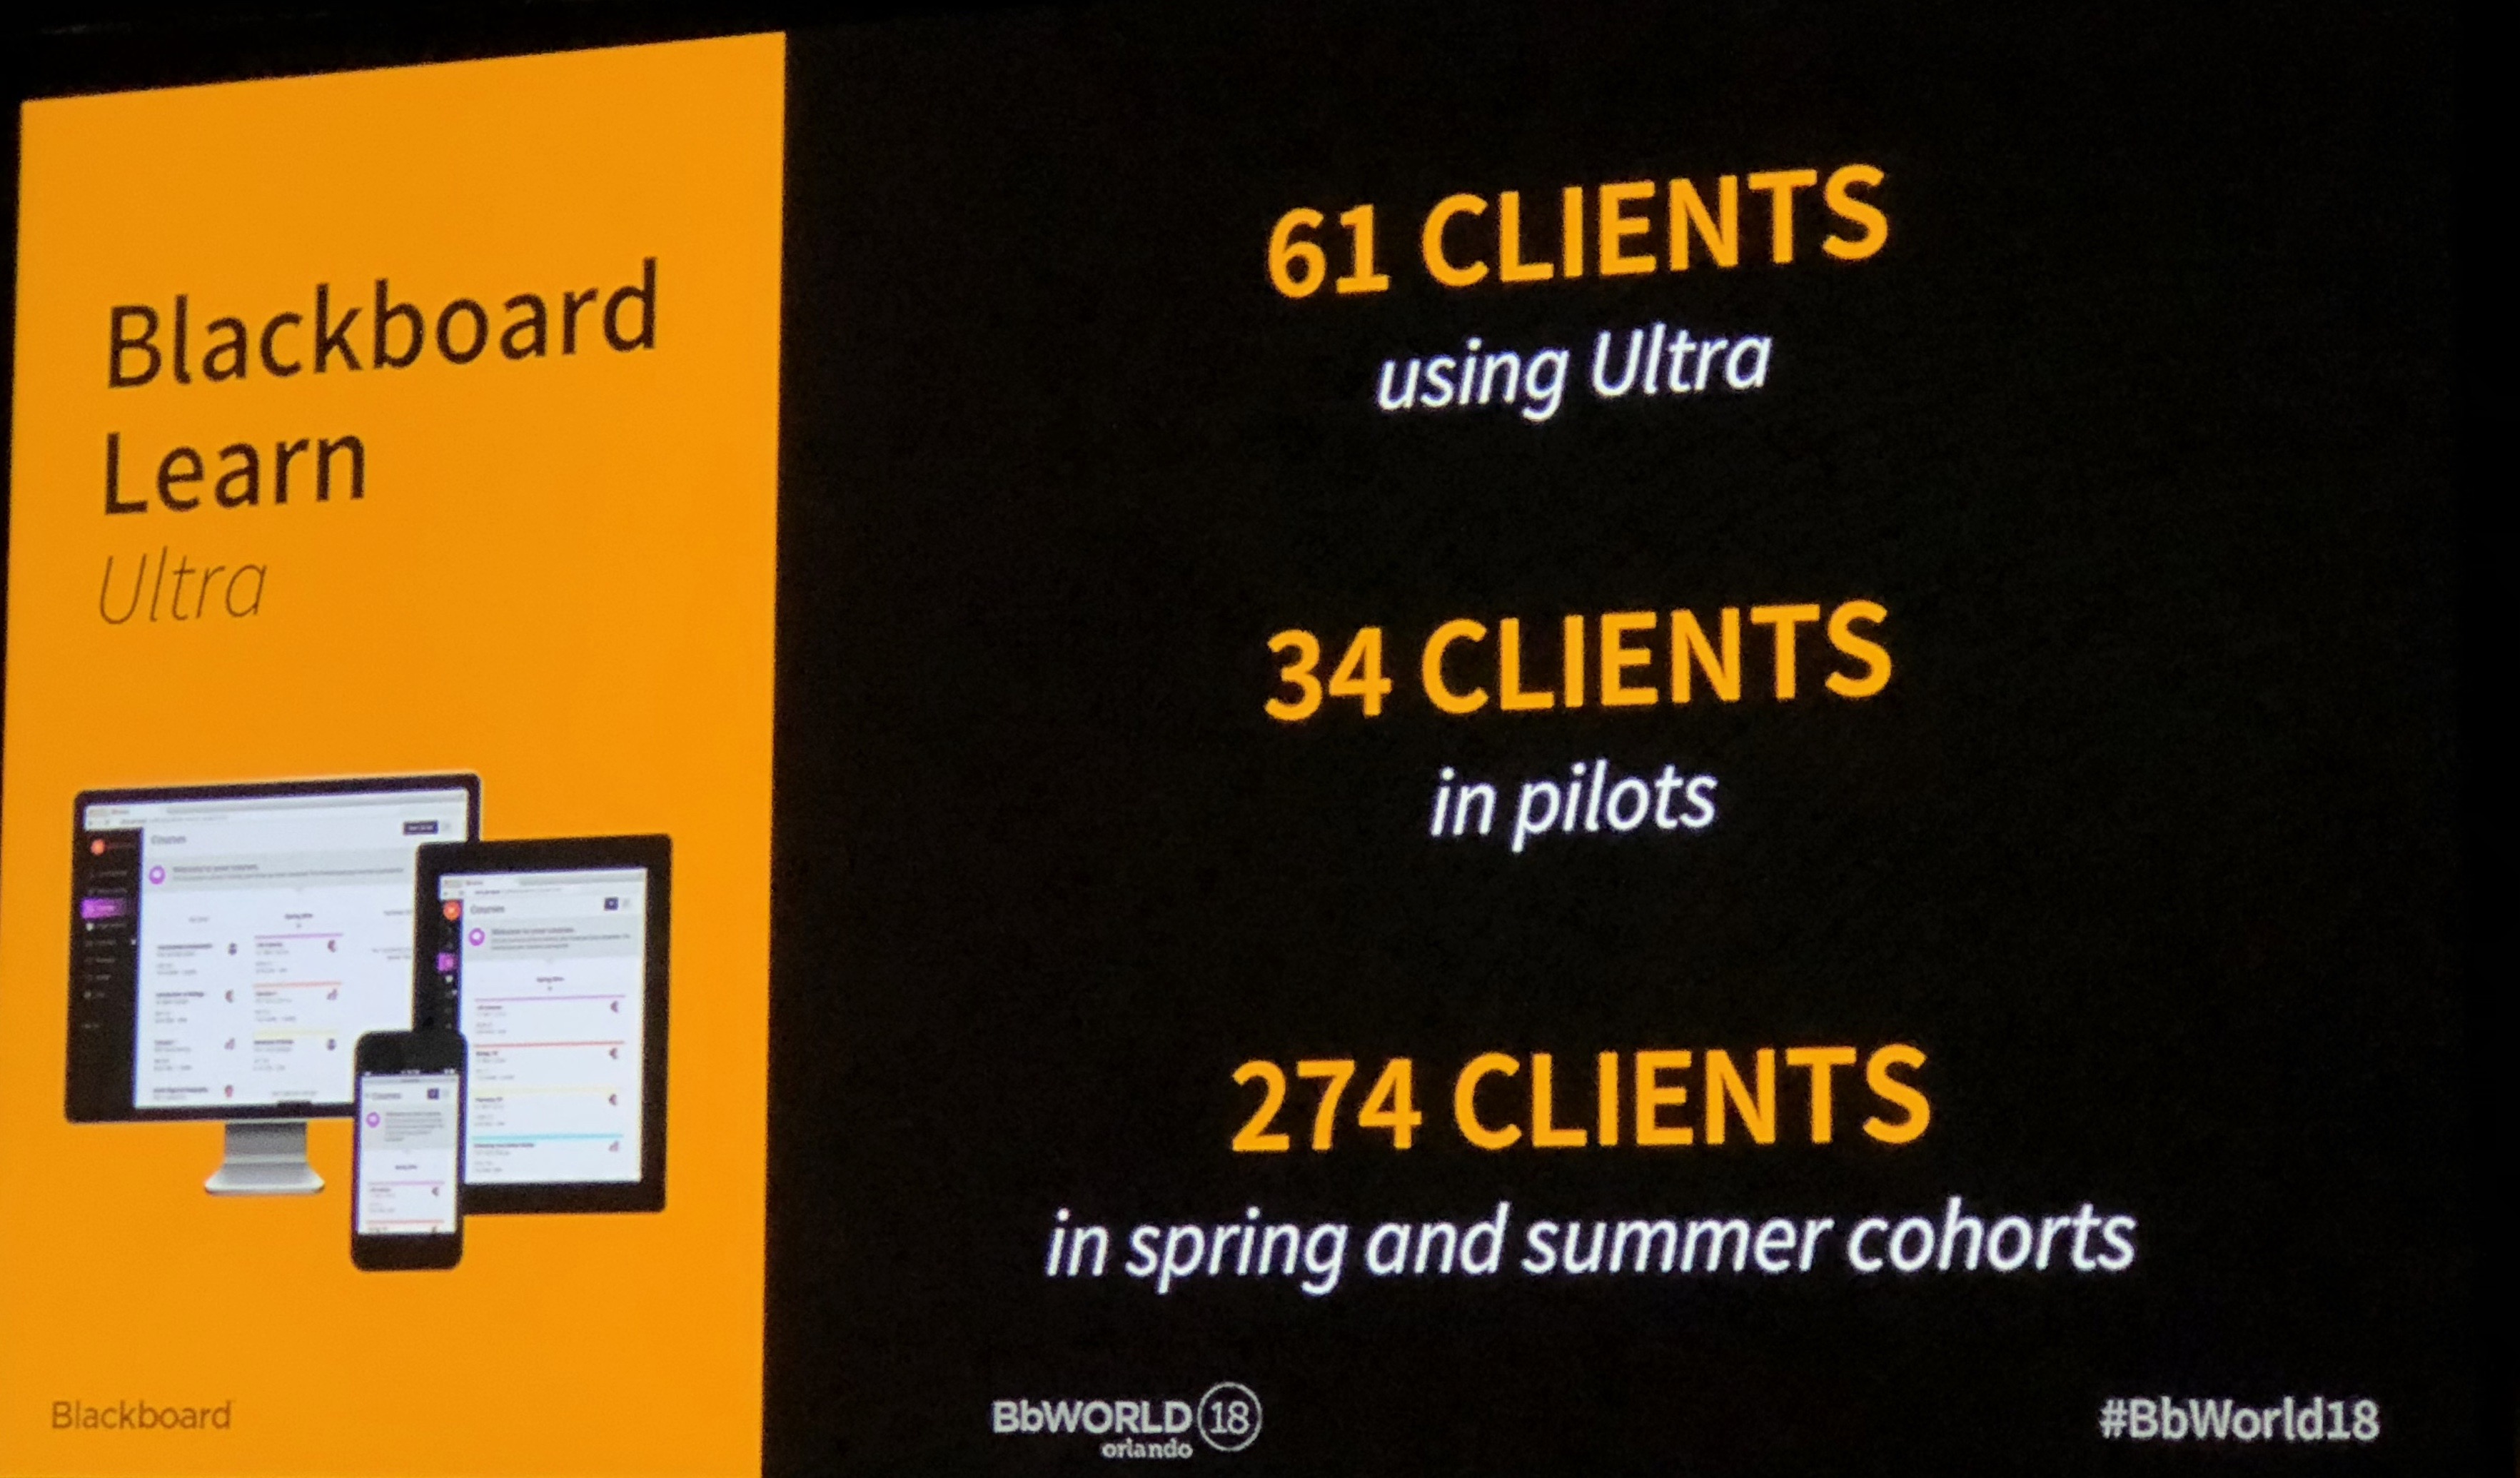
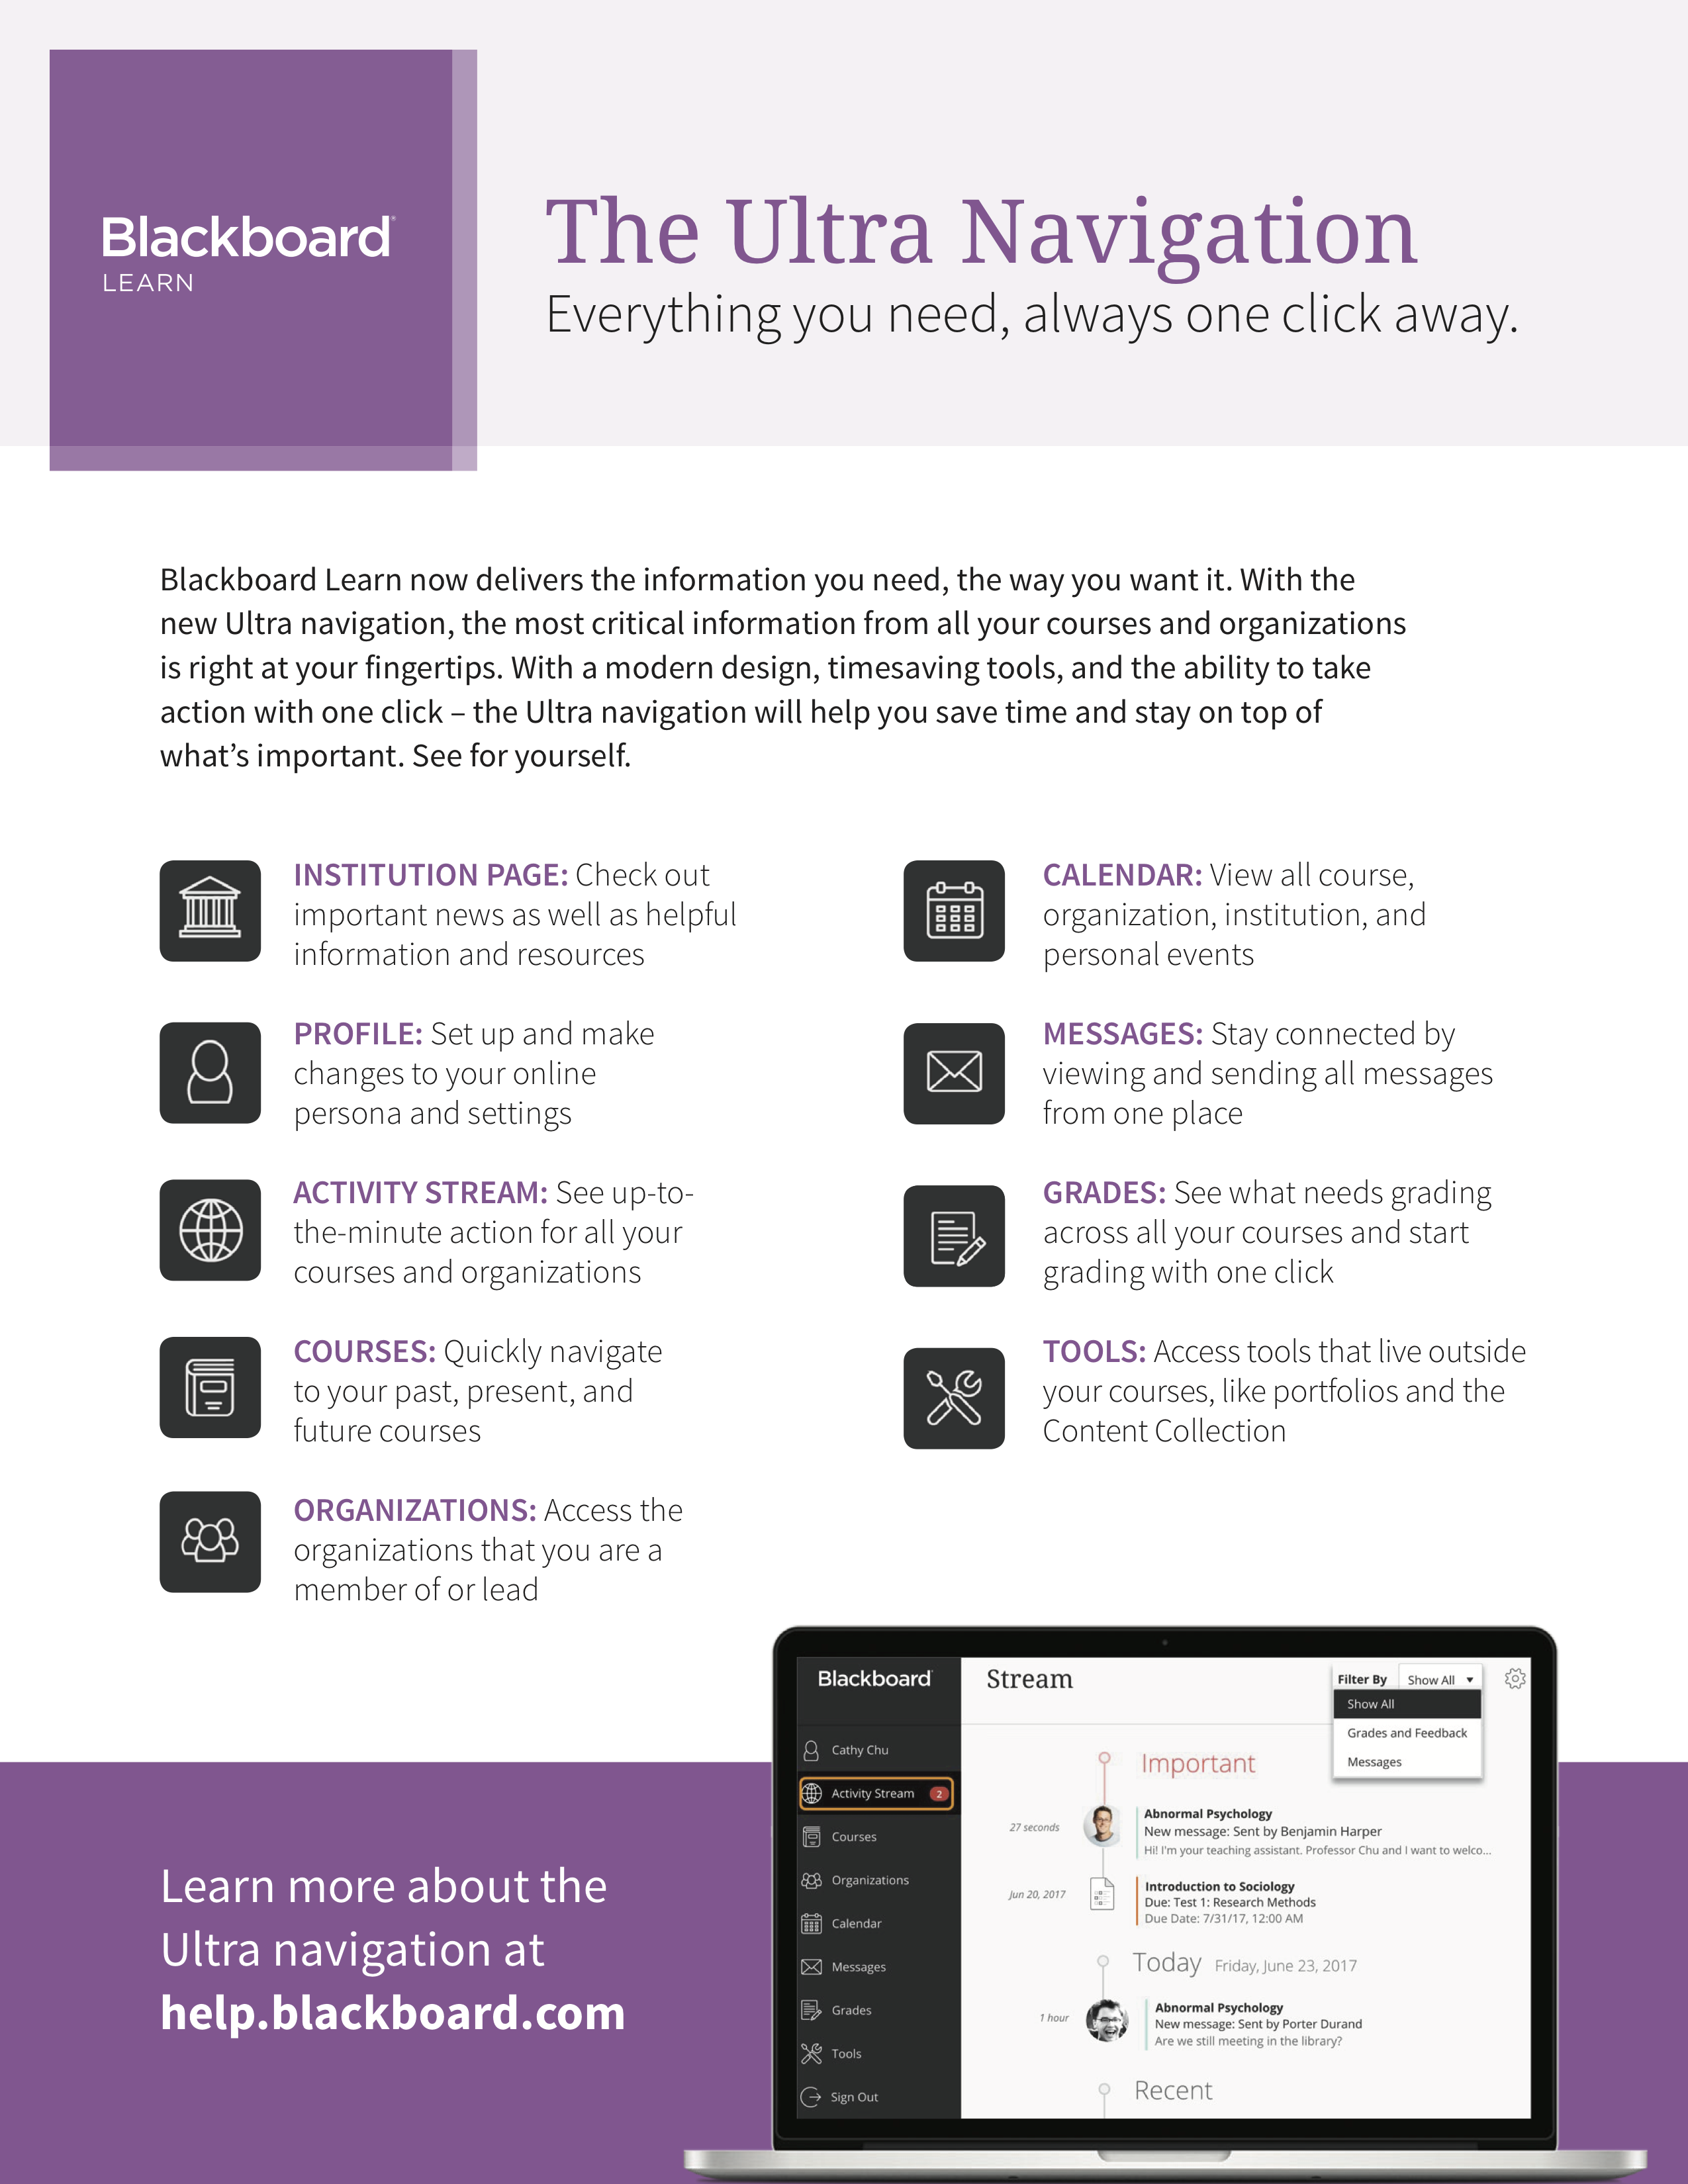
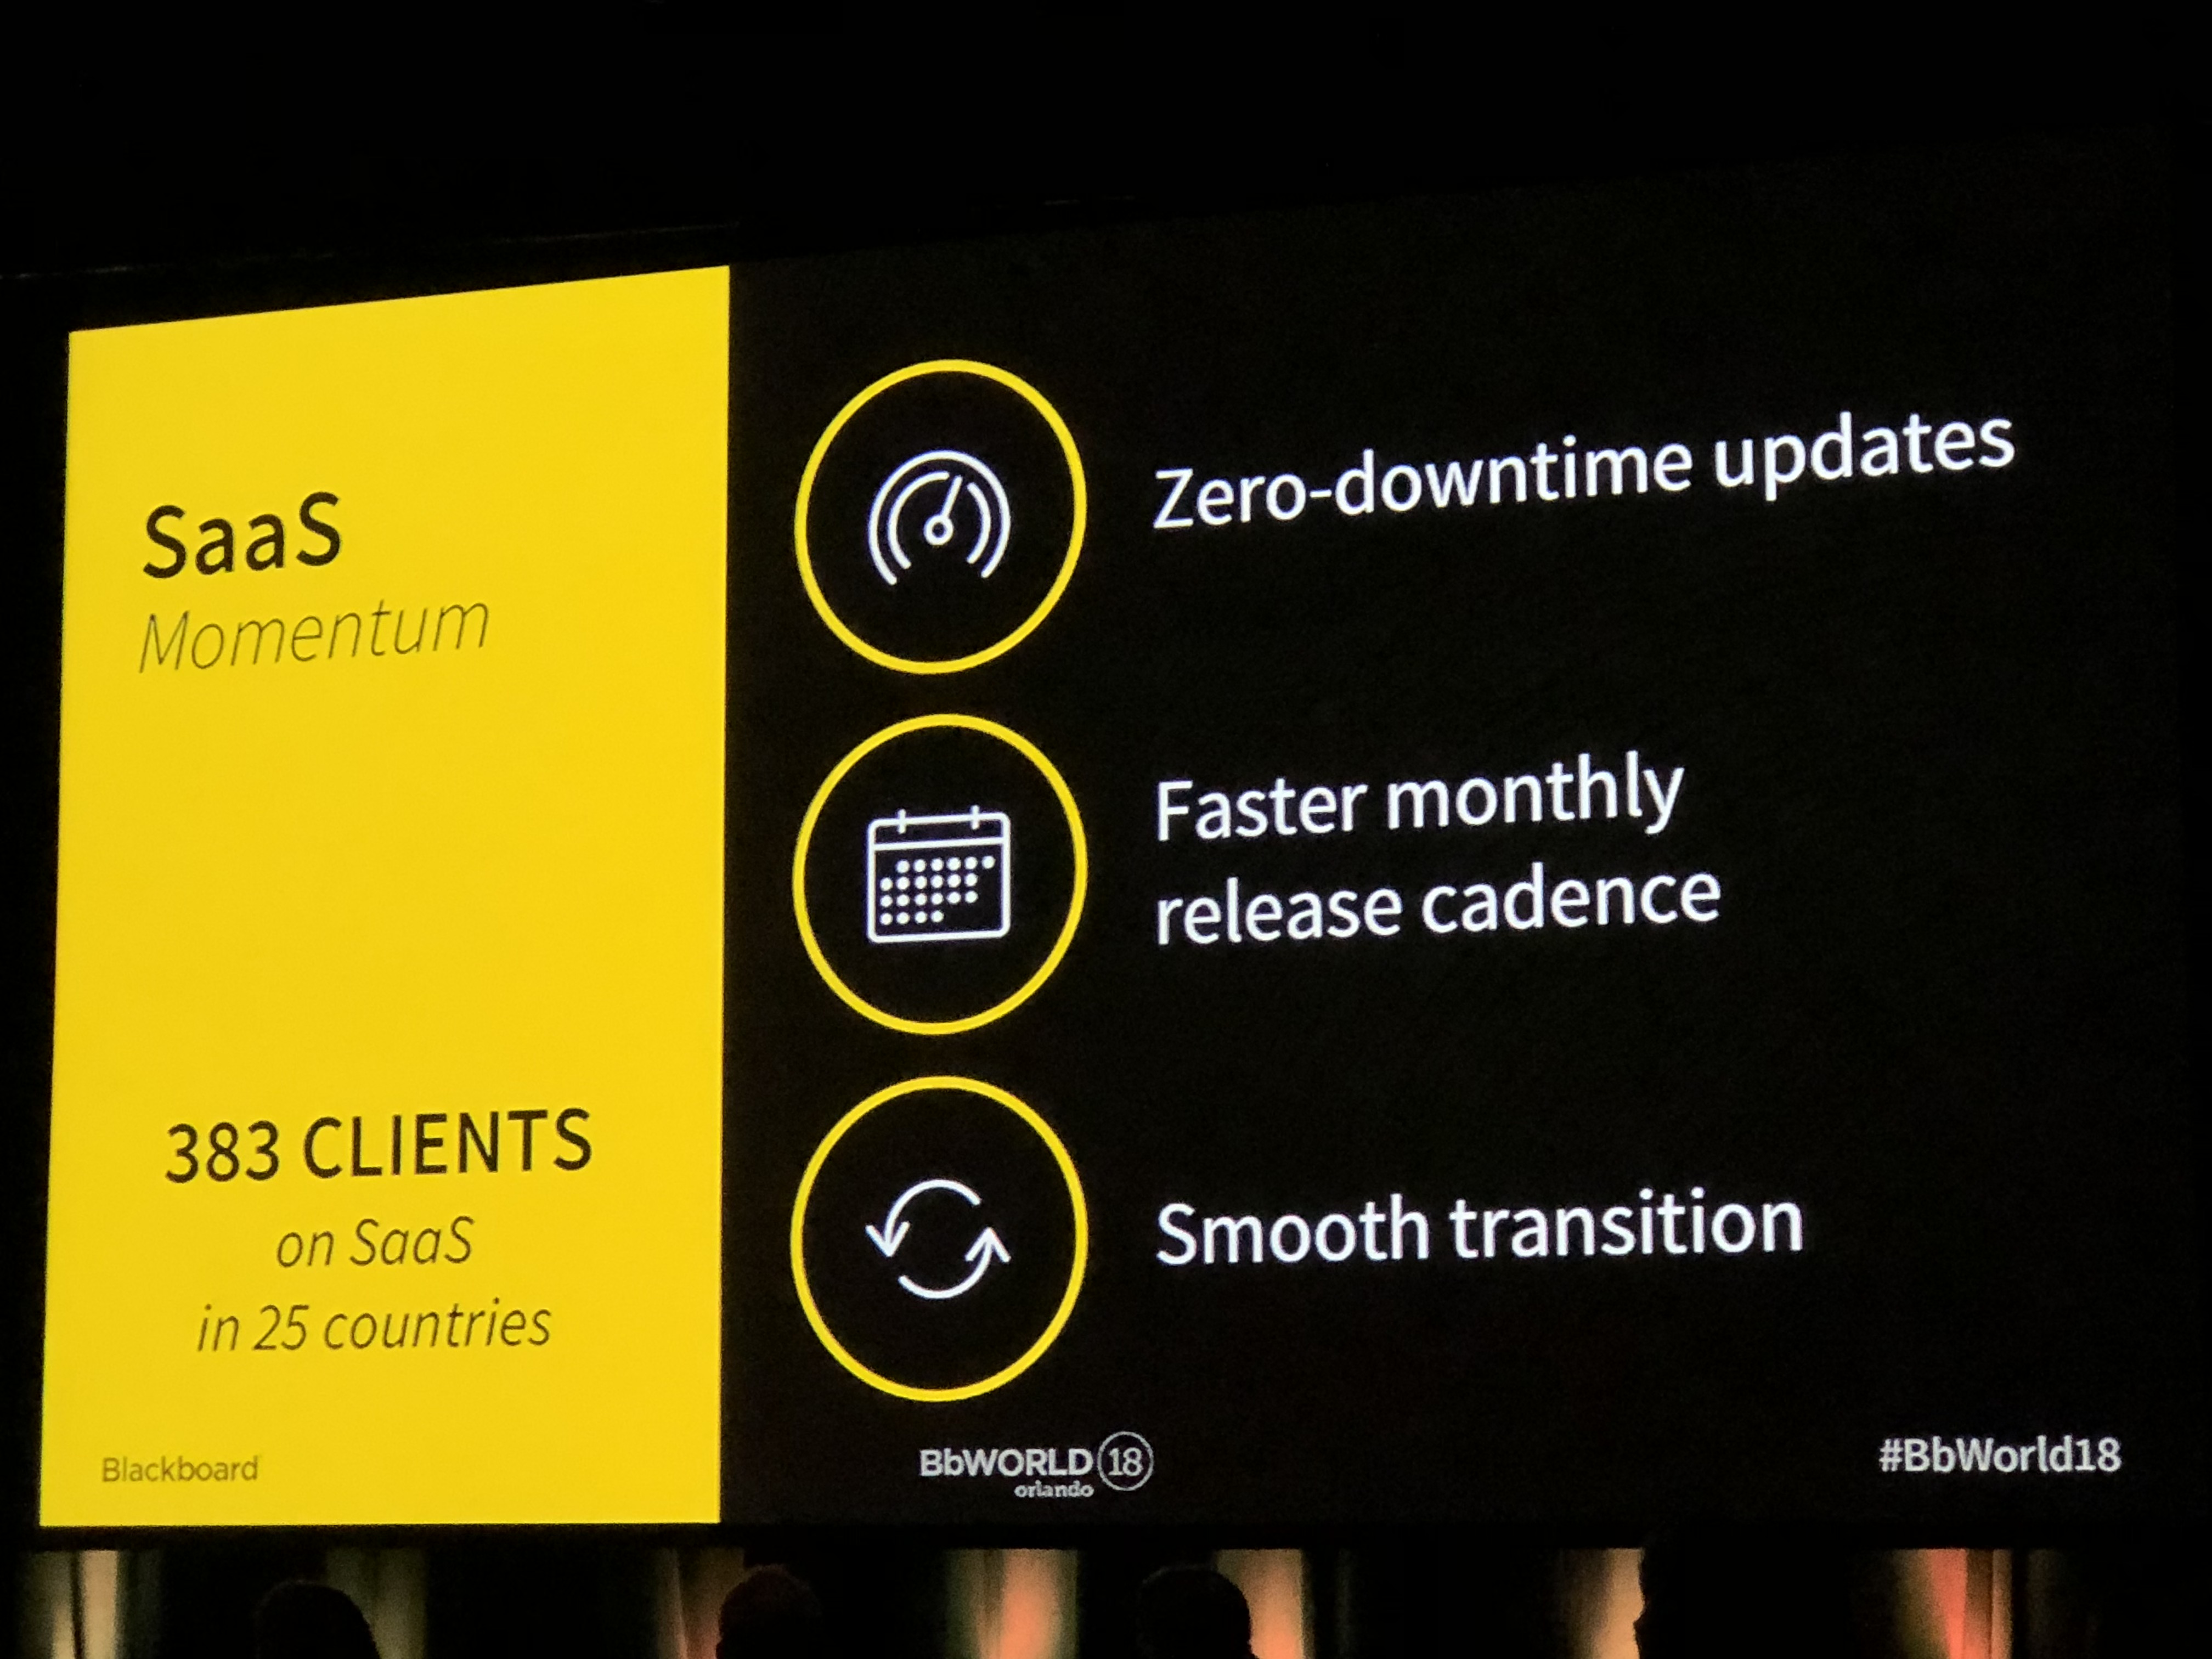
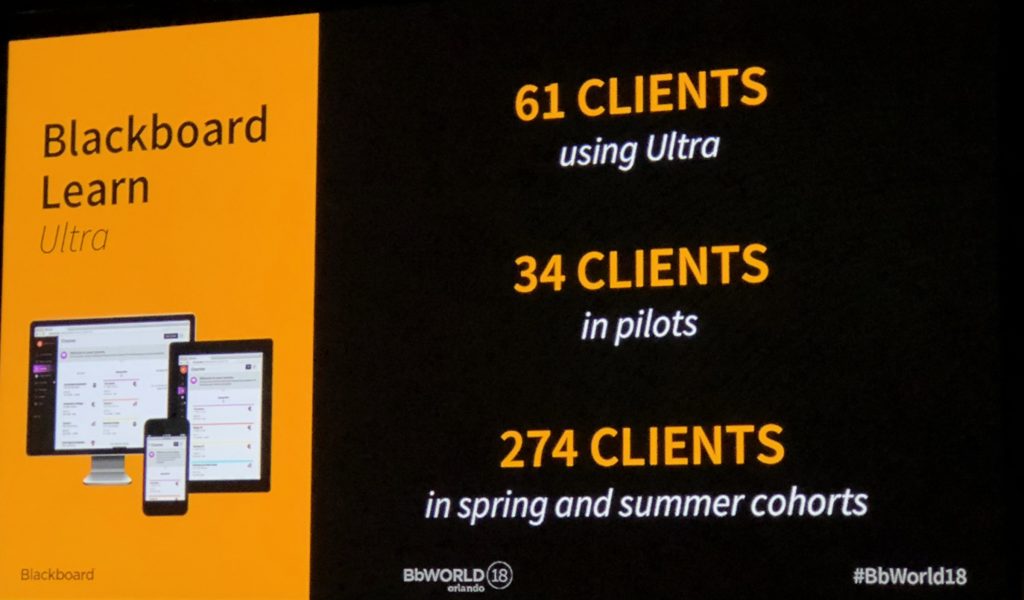
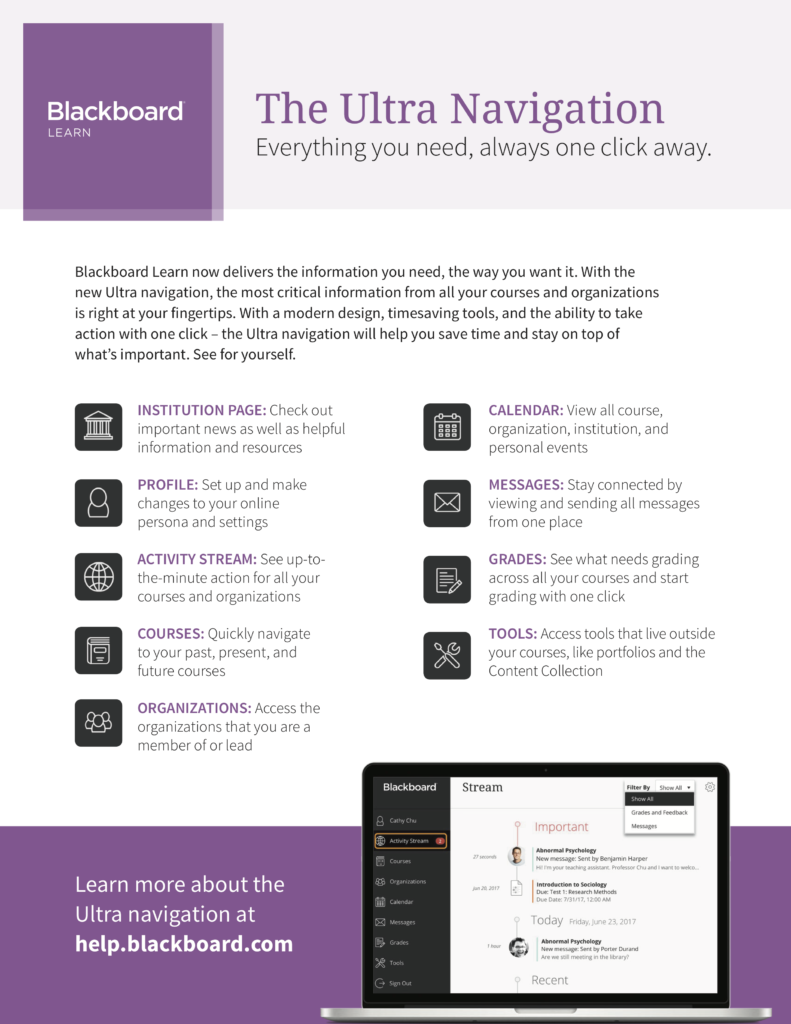
    To ask this question requires an understanding of terminology, as we first described in this post. Blackboard1 is pushing the metric that there are 61 or 62 Learn Ultra customers “in production” or “using Ultra”, yet we have found very few that use, or even plan to use, Learn Ultra as their primary, institution-wide LMS. What gives? What became quite clear at this year’s BbWorld 18 users conference is that when Blackboard says in production, what they mean is that the LMS administrator has enabled the Ultra navigation, which uses the new Ultra user experience framework as the landing page / dashboard with activity feed that users see before entering a specific course. The company calls this Base Navigation, but at this point every course can be configured to be in the Original Experience or the Ultra Experience. Thus, enabling the possibility of running a course in Ultra counts as in production (note that Blackboard now lists 91 clients on Ultra).
    Slide from BbWorld18

    Once a school has enabled Learn Ultra Base Navigation, they could choose to move exclusively to Ultra (e.g. the University of Phoenix, Northwest Florida State College, and a few others), or they could choose to keep all courses in Original (e.g. Northeastern State University), or they could choose to have some courses in Ultra and some in Original (used by the majority of schools investigating Ultra). This last mode is known as Dual Course mode, and even Blackboard executives seemed surprised to find out that the vast majority of schools putting Ultra in production are in fact running in Dual Course. For many of these schools, there are no definitive plans to move exclusively to Ultra.

    Upon re-reading this description, I believe that I should give more credit than just describing a landing page and base navigation. The cross-course functionality is and has been a long-term goal of Ultra, as we described as early as 2016.

    Creating a brand for a set of design goals is inherently fraught. Let’s look at two examples of how it makes communication of Blackboard’s strategy tricky for them. First, there’s mobile. Blackboard came out last year with a mobile app called Bb Student. It provides students with that activity stream view across courses and, of course, it’s mobile-first. (In fact, it’s mobile-only at the moment.) Furthermore, the company has made the product available for both traditional 9.x customers (which at this point is pretty much everybody) and their SaaS customers. People inside the company feel like they should be getting more credit for delivering on two major design goals (mobile first and stream-based activity views) as well as for delivering it to customers on the 9.x platform (which was more significant of a technical achievement than is immediately obvious).

    This is not a matter of Blackboard moving the goal posts, per se, and it is probably more accurate to say that Ultra cross-course functionality enabled by Base Navigation is ready and showing some benefits.
    Learn Ultra Base Navigation Brochure

    The challenge is that this move is not sufficient to make a material change in Blackboard’s company prospects. At best, Learn Ultra Base Navigation without usage of Course View will slightly slow down the rate of customers defecting for another LMS. For Learn Ultra to matter and to make Learn newly competitive, they need customers to also use Course View as the primary choice at their institution, and that usage by-and-large is not ready outside of a handful of schools.As an example from BbWorld18, Belmont University presented their experience moving to Learn SaaS (the important issue in the present, and a predecessor for  adopting Ultra)  and to “the Ultra Experience”. But after we asked a question about faculty adoption of the Ultra Course Experience, the administrator clarified that there are no courses running Ultra – all they have done is enable the Ultra base navigation, and they do not expect to do any course migrations for at least another year. This full adoption of Learn Ultra might become important in the future, but it is not driving decisions today.

    Does It Matter?

    Given that we’ve been asking for three entire years whether Learn Ultra is ready, one obvious follow-up question is whether it matters any longer. I do think the question matters as Blackboard is pinning their corporate turnaround on Learn Ultra as the core piece, and this message was heavily promoted at BbWorld 18.

    This messaging makes some sense in that we consider it unlikely that Blackboard can gain significant numbers of new clients (those moving from another LMS to Blackboard Learn, beyond a dozen or fewer schools) without Learn Ultra. Learn Original Experience has too much baggage and is too dated to compete with Canvas or Brightspace by D2L, at least in North America. The company’s new Learn LMS clients are largely the University of Phoenix and ANGEL contract conversions.

    To be fair, the exceptions include several schools in North Dakota (migrating from Moodle) as well as Northwest Florida State College (migrating from D2L). But even with NW Florida State, they based their decision on Learn Ultra.

    Based on interviews with clients arranged by Blackboard, and based on our own connections at BbWorld, what we consistently heard during dozens of interviews and from listening to panel discussions was that Learn Ultra Course View makes sense primarily for programs or schools that have not been on Blackboard Learn before. Bb Learn clients seem to have too many expectations of needing the same functionality they had before, pushing Ultra to be largely feature-compatible with Original and thus losing some of its simplicity in the process. When the Illinois Institute of Technology migrated from Learn self-hosting to SaaS, which enabled them to explore Ultra, they chose one program and a handful of faculty that were willing to jump into Learn Ultra, but for almost all others they are sticking with the Original Course View for the time being. The soonest they would expect moving primarily to Learn Ultra at the Course View would bet 3-5 years from now. You can hear the same dynamic in a recent Rod’s Pulse Podcast (shared under CC-BY-NC-SA license and also available at Inside Higher Ed), with Rod Murray interviewing Rob McCunney about their school (University of the Sciences) and its migration to SaaS and Ultra. It is a fascinating first-hand description of their experiences. Please note that they use use the terms Traditional and Original interchangeably.

    R Murray: We turned on the SaaS in January, but we really kept the Original Experience until July. In mid-July we flipped the switch to turn on the Ultra Experience. Now again for those of you are not as familiar with the way Blackboard works, that wasn’t changing the course format. They were still traditional courses, but you know all those tabs and modules disappeared, and we ended up with a new base navigation in Blackboard, which they called the Ultra Experience. So that was a major change, and we do have some summer sessions, but we felt this was the least painful way to turn it on. We didn’t want to wait till August just before our fall students came back.

    In terms of turning on the Ultra Experience, what were some of the major issues that you saw, that you were concerned with?

    R McCunney: Besides the fact that we lost the tabs and modules, so we kind of rolled out OneCampus as Rod said, I think one of the major things that that I noticed wasn’t really even on the admin side, it was just getting people used to something that was completely different as soon as they logged in to that institution page. Where’s my stuff, where is my modules? It just looks completely different than what they’re used to, and there’s some stuff missing, and we replaced it. We put stuff in other areas, and we communicated that, but that was probably the biggest hurdle. Just what is this, what is this Blackboard Ultra that you’re changing me to? And at that point, in July we only changed basically the institution page. Your average user, once they get into their course they didn’t notice anything different, but that initial freak out of here I don’t know where my form is. We told them a dozen times where it is, but it’s somewhere else. That was probably one of the major hurdles, and I didn’t anticipate that as being a big as an issue as it was. I thought there was going to be more nuts and bolts issues, which there were very few of those for the most part.

    R Murray: Right now of course we don’t have that many students here in the summer, so the real test will be in another week or so when students come back and really start. We all start kicking the tires, even on the traditional courses within the Ultra Experience.

    [snip]

    R Murray: The next big change that we have to live through has to do with converting courses to the Ultra course view. Now here at our university we certainly didn’t do it en masse, we went to play with it for at least this term and maybe next. But there are some courses that we decided made a lot of sense to convert to the Ultra course view. Those schools that those courses that are brand new, especially online courses that are brand new, it made sense to develop them directly in the [Ultra] course view.

    Schools are trying out the Ultra Experience in terms of the landing page and cross-course functionality, but by-and-large they are very cautious jumping into the Ultra Course View where most of the functionality resides.

    Based on this situation, we believe that the migration to Learn SaaS might be a better indicator – at least in the short run – than Ultra adoption of whether a school plans to stick with Blackboard. When a school moves to Learn SaaS, they all tend to sign contract extensions for 1 – 3 years or at least internally plan no LMS migrations for more than 1 – 3 years. And the migration to Learn SaaS does not suffer from the vague terminology issues – a school either uses Learn deployed on SaaS (through AWS) or they don’t.
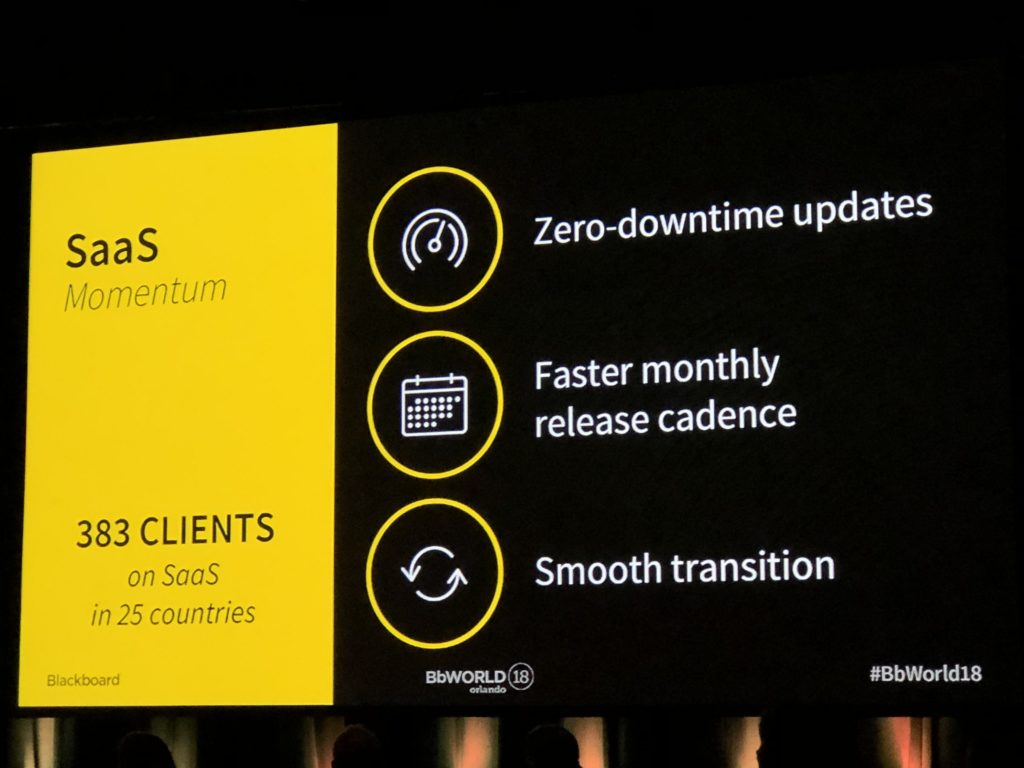
    Learn SaaS progress slide

    383 clients on Learn SaaS as of BbWorld 18 is good progress and easy to understand. This issue is what likely matters more to Blackboard clients today and for the next few years, but in the long run the company needs Learn Ultra to be accepted – including at the course level – in order to become more competitive and pick up new clients.

    In the end, Learn Ultra is partially ready and does matter, more so in the future, but the Learn SaaS migration matters much more today. This answer is a real improvement over the situation a year ago and even from the beginning of this year, but it is still a far cry from a simple yes and yes answer that Blackboard would like to have.

    Update: Fixed name of Rob McCunney

  • Timeline of e-Literate Coverage of Blackboard Learn Ultra

    Timeline of e-Literate Coverage of Blackboard Learn Ultra

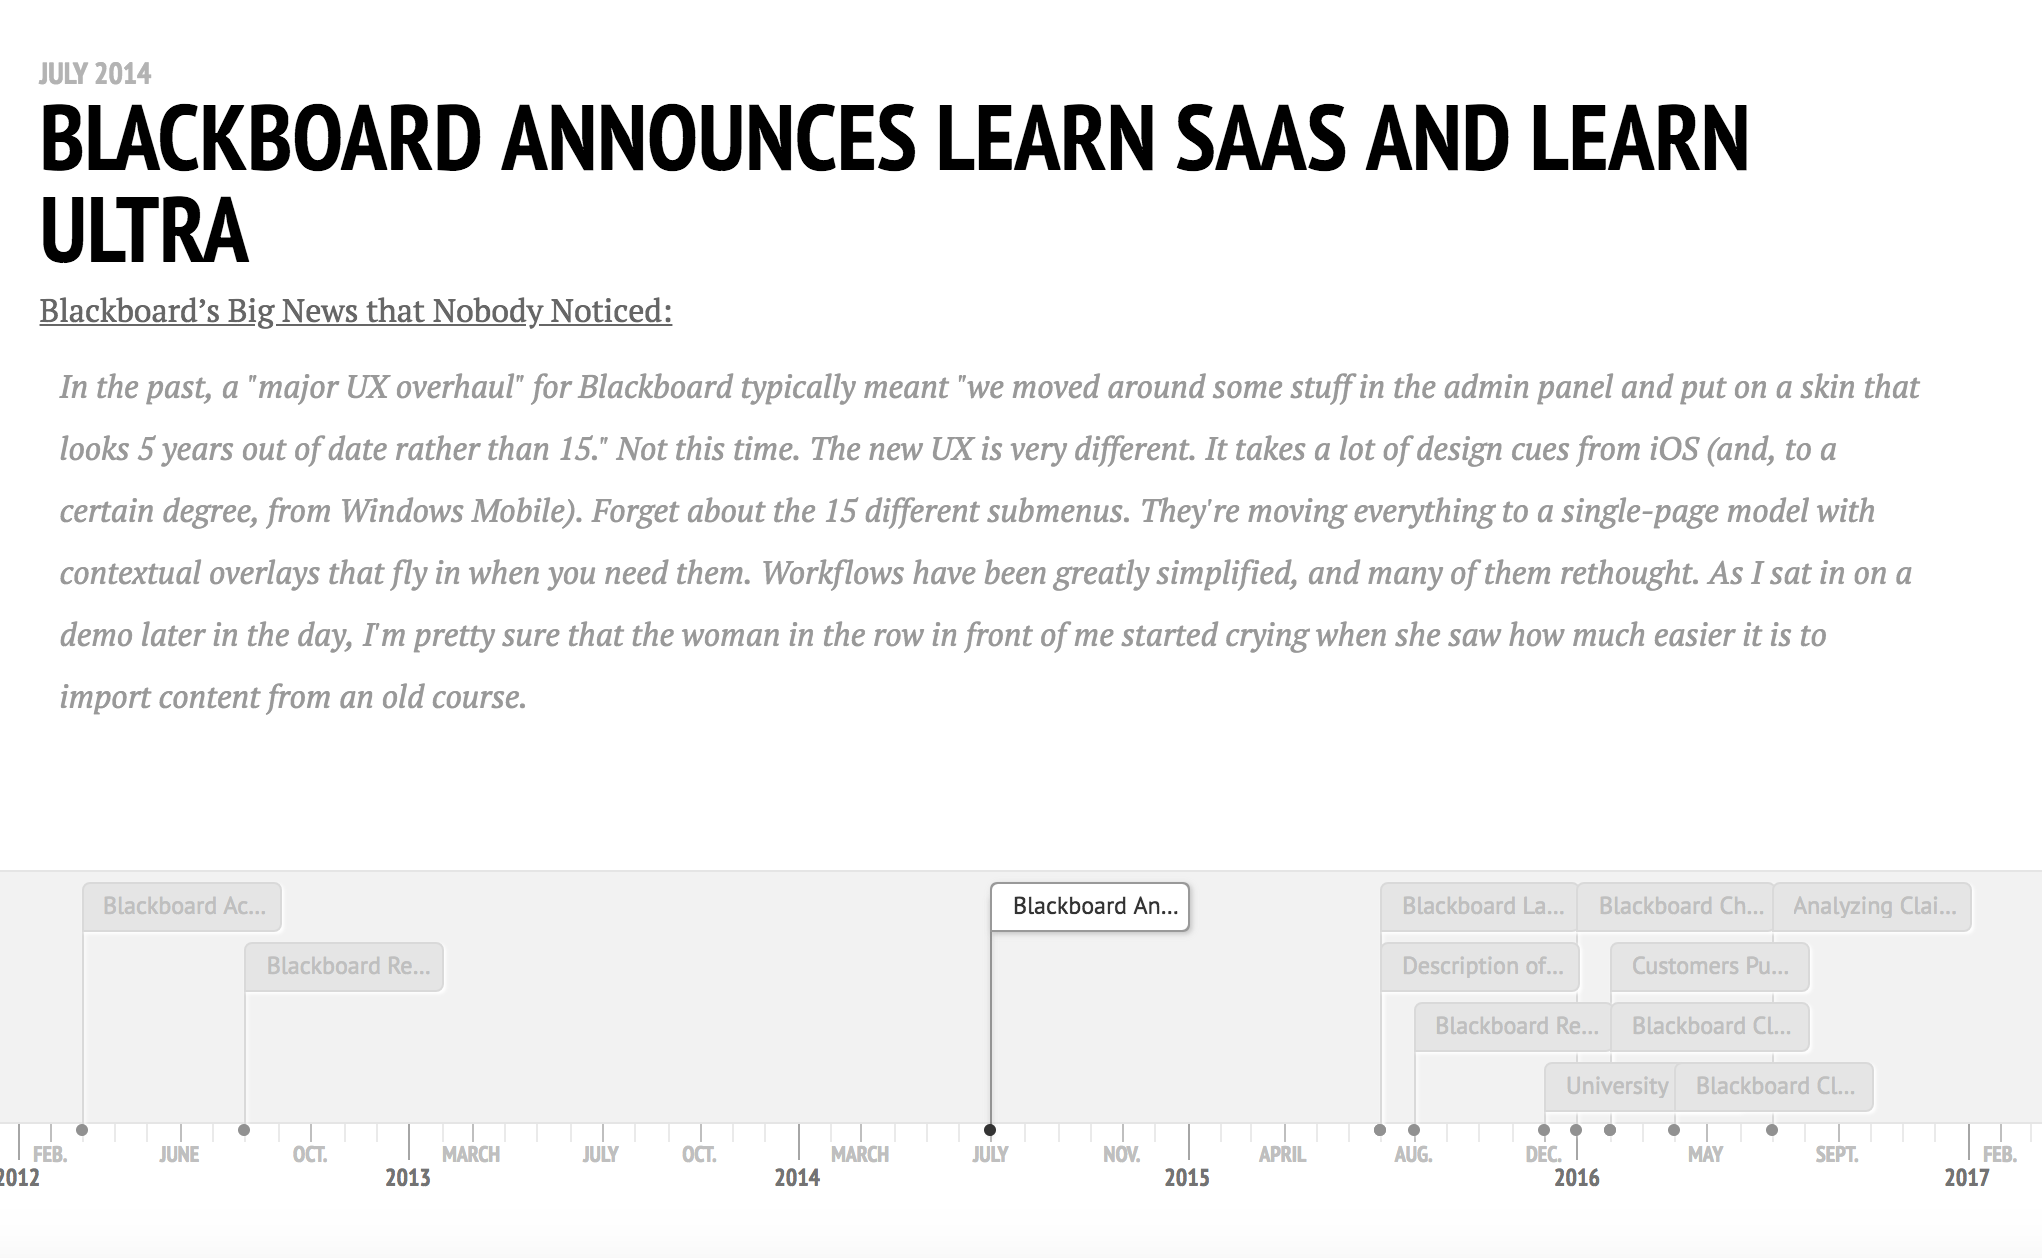
    While doing research for an upcoming analysis post on Blackboard Learn, I found myself wanting to have a coherent timeline of past e-Literate coverage on the development and adoption of Learn Ultra. The most useful timeline tool seems to be TimelineJS by Knight Lab out of Northwestern University, so I gave it a try. The result of combining article data with this tool is an interactive timeline that allows the reader to browse relevant posts since 2012, showing the date of publication, a linked post title, and a snippet of content. You can click on the timeline navigation at the bottom, or you can browse through the overall story by using the arrows by text or swiping left / right on mobile devices. It might be easier to view this as a full page timeline instead of the embed within this post.

    Going through this exercise, I was a little surprised to see the two-year gap in coverage between July 2016 and July 2018.

    Let us know if this timeline view is useful. We may create other versions to help navigate topics like the OPM market.


    One sample page:

    Timeline of coverage of Learn Ultra

  • Response to MoodleNews: Some considerations for critical reading of market sizing claims

    Response to MoodleNews: Some considerations for critical reading of market sizing claims

    There is an interesting post at MoodleNews titled “Open Source LMS Alive And Well: Moodle Breaks World Higher Ed Records, Tops North America, Grows Everywhere” looking at some of our recent LMS market data, focusing primarily on what the data reveal about open source systems such as Moodle, Sakai, Claroline, and Chamilo.

    Open Source LMS Alive And Well Moodle Breaks World Higher Ed Records, Tops North America, Grows Everywhere

    We welcome the usage of our data posted at e-Literate for these purposes, ((That’s why the blog is available for use under a Creative Commons Attribution license.)) but there are some misunderstandings evident in the MoodleNews post that we see too often in critical readings of market sizing reports. Unfortunately the misreadings can cloud otherwise valuable analytical reporting.

    The latest e-Literate report on “active LMS” shows Moodle as the incontrovertible LMS leader in global Higher Ed for primary and secondary systems, including North America.

    Incontrovertible seems quite strong, and we at e-Literate try to be very careful in our language and we rarely use words like incontrovertible or unequivocal. ((For the record, in the 14 year history of e-Literate, the former has been used one time and the latter five times.)) The reason is that for most people reading the data is a translation exercise. There is a need to understand the level of confidence the reader should have and what the limits of the claims are.

    It is useful that MoodleNews called out the global nature of data and measure of primary and secondary systems.

    Assuming it uses data provided by self-reporting service LISTedTECH from the last month, it shows dominance in every region, unsurmountable everywhere but the US, and healthy growth rates. The report mentions the “LMS long tail” as well as “the Big Four” (Moodle, Blackboard, Instructure Canvas and D2L Brightspace) but by their own accounting a more accurate distinction would be “the big one.”

    The data set used from our partners LISTedTECH is not a self-reporting service. Read this post for more information on the multiple channels of data collection used.

    But unsurmountable comes out of the blue. The whole point of doing reports like we do is that we don’t know for certain what the future trends will be, and we gather the data to reduce uncertainty. A while back, many would have said that Blackboard has an insurmountable dominance in North America, but we have seen major changes that would have made those claims invalid.

    I can see the argument for describing Moodle as “the big one” as an alternate description to “the Big Four”.

    LISTedTECH sample (apparently totaling 12,879 active LMS) lists 1,419 active Moodle sites in Higher Ed for North America, self-acknowledged as their most complete dataset. It appears that the advantages in Canada compensate for Instructure Canvas’ growth in the US. In July, it had listed 1,000 sites only for Higher Ed in the US.

    The first sentence is a good example of characterizing the data in a useful way, as it gives the reader a sense of the data set while also clarifying usage in a specific global region.

    Unfortunately the article then jumps into some confusing claims based on misreading the data descriptions. The June 2017 post captured percentage of primary systems at degree-granting institutions for each of four global regions with North America = US and Canada combined, the July 2018 post captured primary LMS in … US colleges and universities, and the August 2018 post captured total counts of both primary and secondary system usage in six global regions. We chose this latter method for the August post due to the frequency of long tail and open source LMS systems being used as secondary systems (i.e. some other LMS is the campus standard, or primary system). There is little basis for concluding that Moodle’s advantages in Canada compensate for Instructure Canvas’ growth in the US.

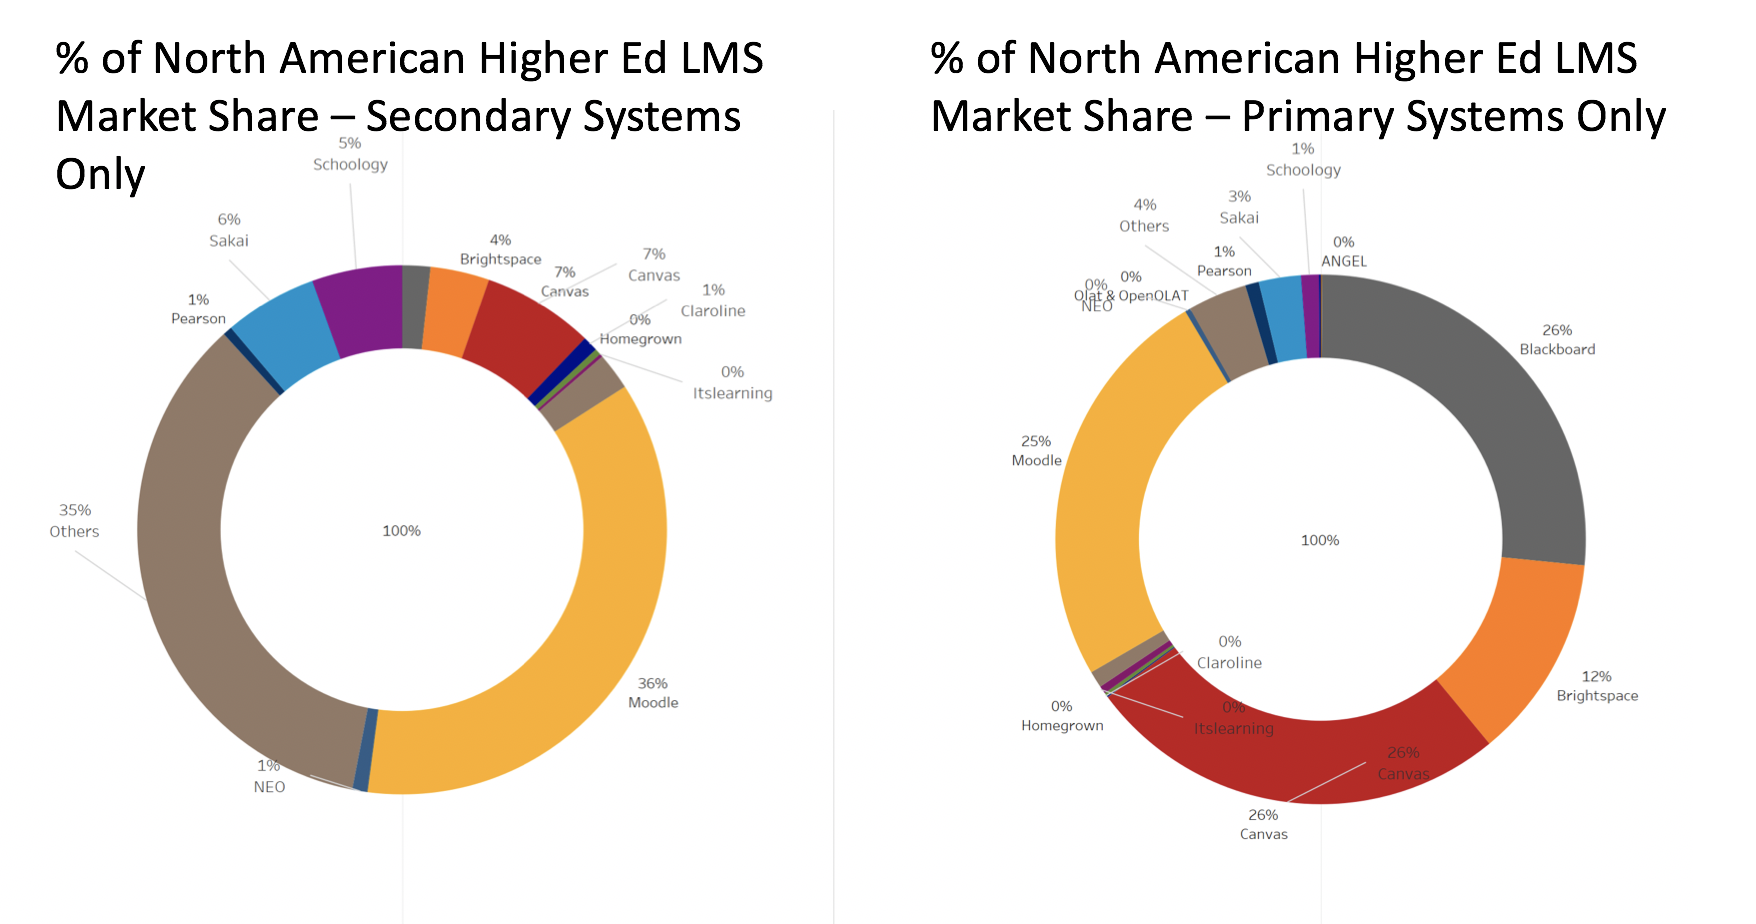
    The larger point here is that there are lots of ways to slice and dice data that end up with similar-lookinggraphs that represent different things – it’s important to read the legends and surrounding text carefully. To give a sense on the issue of primary vs. secondary systems  for North America, consider the difference shown below. ((Graphic shown as clarification, not present in articles referenced by MoodleNews.))

    With MoodleNews’ natural focus on Moodle, it would be accurate to note that Moodle is used quite frequently as a secondary system.

    For comparison, official stats at moodle.net set the total figure at 11,490 as of writing. 9,776 for the US, the biggest Moodle nation; 1,714 for Canada. Moodle does not offer discriminated site data for Higher Ed only.

    This is a helpful comparison and description with a different data set.

    Unfortunately, I need to be careful with further quotations. MoodleNews does not use a creative commons license and clearly limits usage based on the site’s terms of use. So the remainder of this post will have to be limited to short descriptions.

    There is a useful section looking at Moodle’s shares in six different global regions. The main caution I would add comes from our November 2017 post describing the data.

    Market share information provided in percentages and trends are more reliable than absolute counts outside of North America. When we do provide absolute numbers, we advise caution for readers or subscribers to not over-interpret the absolute numbers, at least without us providing additional details to keep the data in context.

    But in this case, MoodleNews also included the percentages for each region, which is helpful.

    The next four paragraphs all focus on market trends (year over year comparisons) that cannot be supported by the data (see above).

    At the end of the MoodleNews post, there is some valuable commentary about other (non-Moodle) open source LMS system and the origins and deployments across various regions.

    Given these clarifications, I would also add the the MoodleNews title has some serious flaws.

    All-in-all, it’s good to see valuable discussions spawned from our CC-BY licensed posts. But readers should be cautios when trying to understand market sizing data and make comparisons and trends analysis carefully.

    Update 8/26: Please see comment from Martin Dougiamas clarifying that MoodleNews “is not associated or affiliated with the Moodle organisation in any way”.

  • D2L Fusion 2018: Product improvements and potential signs of addressing challenges

    D2L Fusion 2018: Product improvements and potential signs of addressing challenges

    This year’s D2L Fusion conference in Houston carved out a space somewhere between the carnival atmosphere of InstructureCon in Keystone and the subdued feel of BbWorld in Orlando (note: we plan another post on each of these conferences to share more details of our observations). This  was the perfect note to hit for where D2L is in its evolution as an educational technology company. A number of things seem to be falling in place for D2L ((Disclosure: Blackboard, Instructure, D2L, and Schoology are subscribers to our LMS Market Analysis service. Blackboard, Instructure, D2L, and Pearson are sponsoring participants in our Empirical Educator Project.)) with its LMS product, but we will have to see if the recently expanded management team will be able to address the ongoing challenges that D2L faces with customer experience and expectations.

    Like Blackboard and Instructure, D2L is in the middle of a transition partially driven by financial considerations. In D2L’s case, the issue is that the two rounds of $165 million aggregate funding in 2012 / 13 lead to expectations of larger market gains. In August of 2017 we shared that “D2L is on a roll, racking up significant client wins in higher education, and the company shows real signs of change in its ability to truly listen to and empathize with customers.” Two months ago we described D2L’s concerted effort to move customers to the cloud and some promising improvements surfacing in the new Daylight user experience. Despite these improvements, however, D2L has lost some marquee customers such as the University of Wisconsin system to offset some of the wins, and the company has remained steady or made slight gains in North America, European and Latin American LMS market share.

    At D2L Fusion, our goal was to get a better read on how actual customers and prospects are reacting to the cloud deployment move and streamlined user experience that we have observed. A second goal we had was to get a better sense of whether D2L will be able to improve its customer service and delivery on promises made to customers.

    Reactions to Cloud and User Experience

    From customers we spoke to at D2L Fusion, the value of the move to the cloud as well as user experience improvements have provided breakthroughs. On the cloud front, D2L now has upwards of 98% of their customer base either hosted through Amazon Web Services (AWS) or in the company’s data centers.  According to a company spokesperson, 55% of what they describe as cloud implementations are hosted by AWS, the remainder by D2L in their leased data centers. All new implementations moving forward will be hosted by AWS and by fall 2019 D2L estimates that nearly all implementations will be on the AWS infrastructure. This will be a significant achievement for a legacy on-premises software provider to make this transition. From our June post:

    D2L has long worked on managed hosting options, but in late 2013 the company introduced Continuous Delivery where software releases are pushed to customers incrementally, such that customers would jointly run the latest versions of Brightspace, their LMS. This move is important, as one primary benefit of cloud deployment is to remove the explosion of software configurations and versions that make it expensive and difficult to diagnose and fix bugs and to release new features.

    Three years later in 2016 D2L announced their move to AWS for cloud deployment.

    At Fusion 2018 we saw a continuation of this strategy, and we heard largely positive reception from customers and prospects, and we are not hearing the grumblings from customers as was evident in late 2016 / early 2017. We should also note that this move to the cloud is more aggressive than that being made by Blackboard and Learn SaaS, but more on that in a future post.

    As for the new user experience and recent changes in product design, it’s useful to first establish context for what’s been happening internally at D2L. About three years ago D2L brought in a new chief operating officer, Cheryl Ainoa, and a new VP of Product, David Koehn. One of their goals was to turn the product development process on its head and, drum roll, put the users first. This means engaging with users, listening to users, understanding their problems and viewing them as partners in the effort to deliver better software. It also means solving the small things that annoy users on a daily basis and shifting away from feature releases as the key metric of progress. For companies that have been engaged in agile methodology and iterative development, this likely sounds basic. For D2L, it was a fundamental cultural shift in how development is done. At this year’s Fusion, we are seeing concrete signs that change has taken root both with the company and with customers.

    Daylight Experience is the name for D2L’s redesign of its streamlined user interface. When it was first announced in early 2017, we were somewhat skeptical as the initial changes were evident in different fonts and cleaner look-and-feel but not significant improvements in the workflow for faculty and students.

    As time goes on and we see more advanced demos, our view is changing. The Daylight Experience does have some real improvements not just in look-and-feel but in fewer and more intuitive clicks to get the same job done. A major focus on the Emerald Release this summer (in time for D2L Fusion users conference) is more fully encouraging usage of the activity stream for higher ed clients (this feature was initially targeted at K-12 market but has been adapted for colleges and universities).

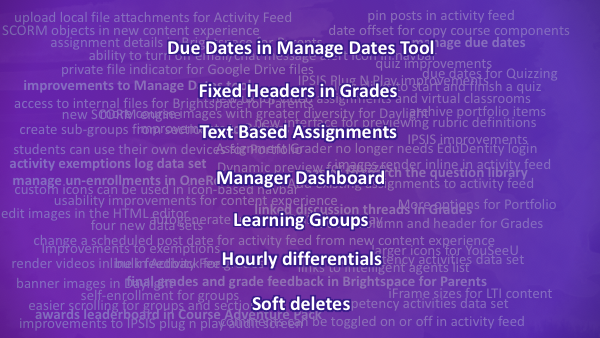
    The product showcase slide that arguably got the most enthusiastic response from the crowd was the one that focused on the small changes that users had been clamoring after for years – things like “Due Dates in Manage Dates Tool”, “Fixed Headers in Grades”, “Learning Groups”.

    New features from D2L Fusion conference

    These are not sexy, headline-making announcements, but they matter to users. D2L has long been viewed as a platform for people and institutions that like to have a lot of control over how to configure and run an LMS; however, the breadth and complexity of options often came at the expense of an intuitive user experience. While D2L has had a solid product for a sub-set of the market for years, they have had difficulty being viewed as ‘intuitive’ or ‘easy to use’, at least since the advent of Canvas and the resultant change in user expectations. The streamlined design afforded by the Daylight Experience, and the progressive disclosure of more advanced features, could change this situation if they’re able to get it in front of potential customers for a serious look.

    Customer Experience and Expectations

    On the second question regarding customer service and delivery on promises there are several reasons to be upbeat, but also reason for concern. Several new customers we spoke with, from Europe, Latin America and North America, all spoke about “partnership” as being a key reason for their choosing D2L over the competition. During lengthy procurement processes, these institutions got the sense that D2L was eager to engage and work with them to achieve their goals with broad service offerings as well as an eagerness to shape product development to suit these new clients.

    That said, D2L has a mixed record on follow through. A number of sources we have spoken with over the past 6-12 months have discussed a pattern of the company over-promising and under-delivering when it comes to implement promised changes. For example, these sources have told us they went into the relationship with this same expectation of a partnership, of having a voice in product direction, only to find out they are having trouble getting D2L staff to respond in a timely manner. It is not clear yet on how prevalent these concerns are, but we do believe they will need to be addressed in order for D2L to make material changes in overall market share.

    D2L has made two key hires in recent months, seemingly in recognition of potential market opportunities as well as persistent internal challenges. One targets growth, the other customer satisfaction. Puneet Arora, a former sales executive with several SaaS companies, has been brought in as chief revenue officer, and April Oman, a veteran customer success executive with a number of enterprise software companies, has been added as as Senior VP of Customer Experience. Arora is new to the education space but seems to be asking a lot of the right questions, and his task is to grow the user base in a meaningful way. Expect to see some changes in how D2L positions itself and who they try to sell to, shifting the balance away from administrators and towards faculty and student end users. Oman’s role is a new one and speaks to the need to develop a stronger relationships and partnerships with customers. This will be critical as D2L tries to establish themselves as much more than a software solution and as they attempt to improve customer experience.

    Better Position but Needing Results

    The center of gravity of D2L’s executive team is more diffuse than it used to be. Much of the longer-tenured leadership of D2L is based out of the Kitchener, Ontario home office: John Baker, CEO; Nick Oddson, CTO; Melissa Howatson, CFO; Jeremy Auger, SVP Strategy; and Ken Chapman, VP of Market Research. Ainoa, Koehn, Arora, and Oman (the new hires), however, are all in the Bay Area in California, and Tracy Strauss, SVP Marketing, is out of Los Angeles. There seems to be a deliberate approach to finding new ways of thinking from a broader field of expertise.

    D2L appears to have largely revamped its approach to product development that is more responsive to customer needs, and is putting resources into building partnerships. Yet they have not made the market gains envisioned after winning the Blackboard patent wars and then raising two large rounds of financing. We still see a two-horse race for new implementations (LMS product switches) in higher education, largely shared between Canvas and D2L, but the second horse that is looking better than it used to still needs to make further adjustments and run faster.

  • Schoology, NEO, Claroline, Chamilo: The beginning of the LMS long tail

    With reporting contributions from Jeanette Wiseman and O’Neal Spicer

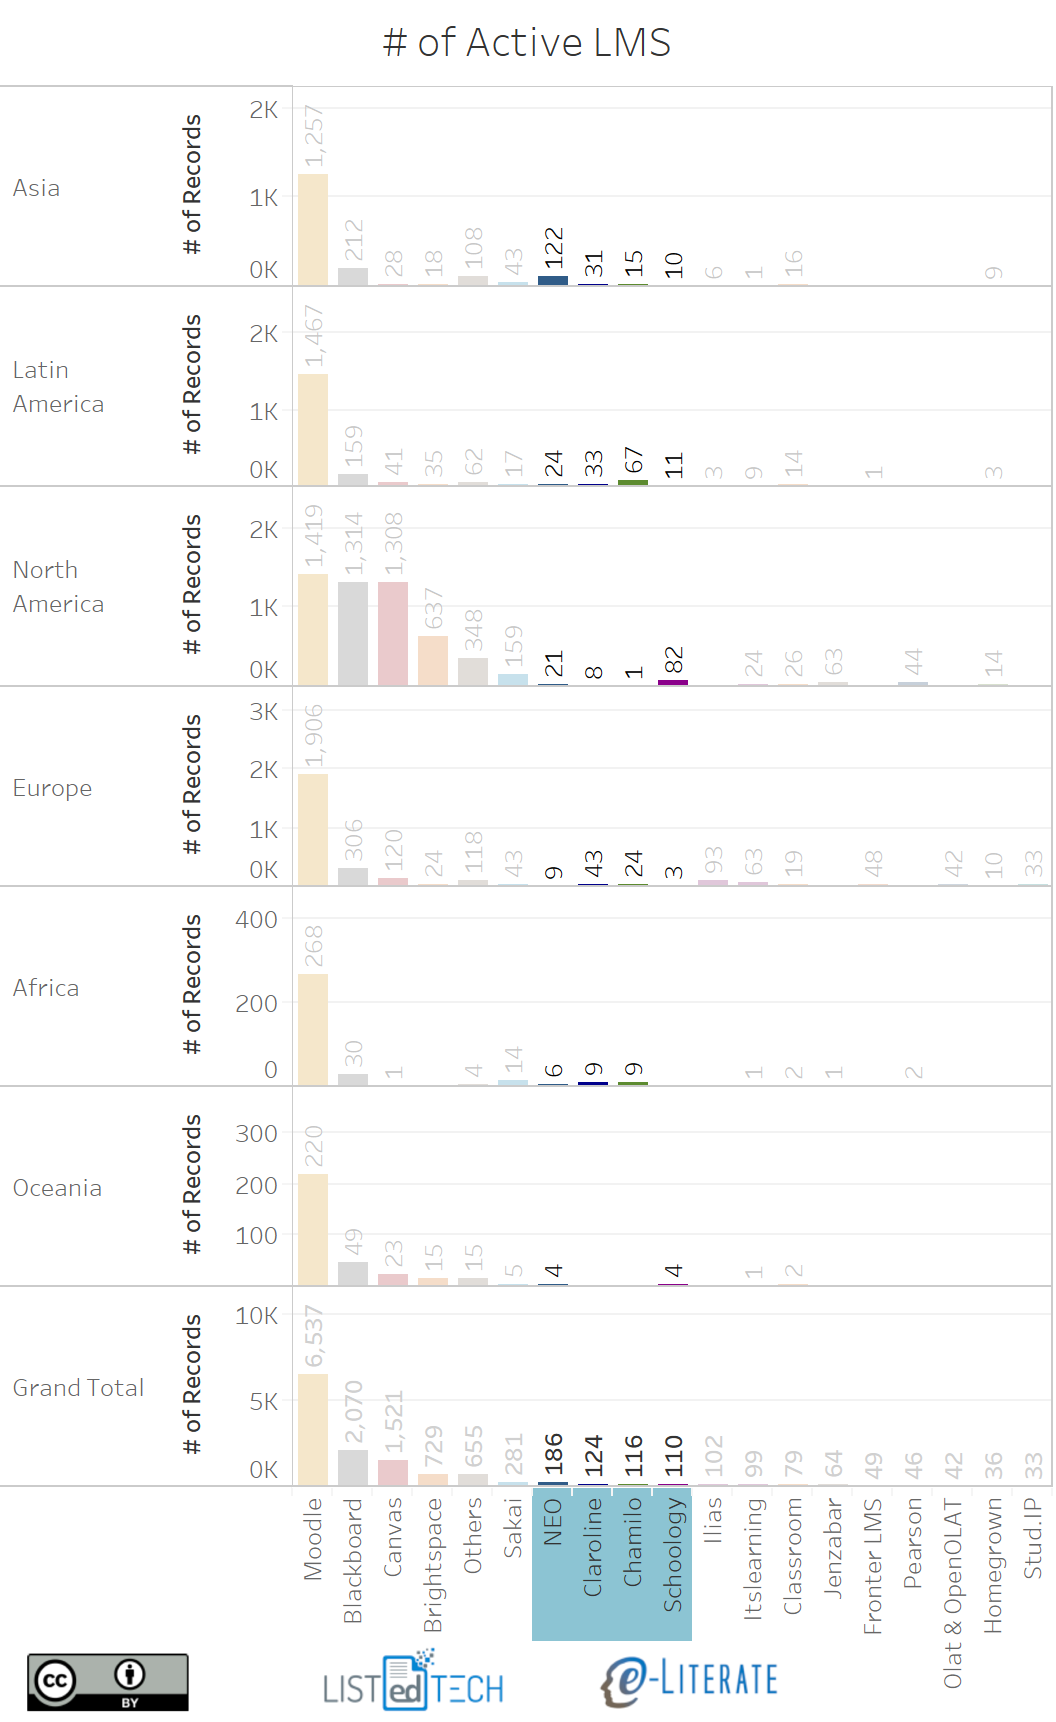
    We have described how the global LMS market is converging in the sense that the Big Four – Moodle, Blackboard, Instructure, and D2L – end up being the primary competitors in more and more global regions, often with similar dynamics. We have also described Sakai and its decline in some detail. But what about the next level down? Let’s consider four LMS solutions that are still quite active but with fewer institutional users than Sakai – Schoology (whom we have described before), NEO, Claroline, and Chamilo. ((Disclosure: Blackboard, Instructure, D2L, and Schoology are subscribers to our LMS Market Analysis service. Blackboard, Instructure, D2L, and Pearson are sponsoring participants in our Empirical Educator Project.)) The following graphic shows both primary and secondary system usage in higher education in six different global regions, and all four systems have more than 100 active implementations.

    LMS higher ed counts by global region


    Schoology NEXT

    • The Schoology NEXT conference occurred at the same time as BbWorld this year. This is a mostly K-12 conference – as that is the primary market for Schoology – with a different attendance demographic than most LMS conferences with the majority of the attendees being actual classroom teachers or instructional designers, not the typical administrators or IT staff that you see at the other user conferences. This audience is more focused on the use of technology to enhance teaching and learning in their classrooms, to assist with assessment, or to fill a requirement of use of technology for professional development. The break-out sessions reflected this academic focus.
    • The only new features or development that were discussed at any length during the keynote presentations involved the vague promise of “Personalized Learning” support. There was little information about what new features would look like, what they would encompass, or if they would entail additional charges like Schoology’s assessment platform. In an interview with CEO Jeremy Friedman and the new President Justin Serrano, they said that the vagueness is by design. The company is still working through their users’ needs and will be completing development on those features once that assessment was complete.
    • When discussing if the company saw Google Classroom’s continued growth in the K-12 market as a threat, Friedman said it is the opposite. They see that in K-12 space Google Classroom fills a need for a classroom, a school or a district that are dipping their toes in the LMS space, and once the school starts actively using the technology they quickly outgrow it. In these cases, Schoology sees Google Classroom as seeding the market for them, and they actively target those Google Classroom schools. In most cases, if responding to an RFP, it will be Canvas they will be up against. Rarely do they see Blackboard or even Moodle in these situations. They feel like, and this was reiterated by their users, that one of the most significant benefits that Schoology users see in the platform is their ease of use. The interface is reminiscent of Facebook; it is familiar to the teachers they quickly can navigate and load announcements and content to their site with very little training or IT support. It may not carry with it the bells and whistles of a Blackboard Learn or even Canvas by Instructure, but for what these K-12 teachers need, it fits the bill. For now.
    • Regarding targeting customers in higher education, the company stayed the course from January 2017 in which they will continue to support their higher education customers and will take easy sales opportunities, but are not planning to aggressively pursue that market. While this strategy only lightly targets higher education, Schoology has over 100 clients at universities and colleges worldwide – mostly small private schools, and often as secondary systems – using their platform. Customers using as a primary system include Wheaton College and Saint Vincent College in the US and the Universidad Metropolitana de Monterrey in Latin America. Schoology is also used as a secondary system at schools including UC San Diego.

    NEO, Claroline, and Chamilo

    The other three systems – NEO, Claroline, and Chamilo – are important in the global market, even if most academic buyers (in the US, at least) likely have not heard of them. All have more than 100 higher education implementations worldwide.

    • NEO is the academic LMS from Cypher Learning: Based on our conversations at the K-12 focused ISTE conference this summer, Cypher Learning has 60 employees and claims 2 million customers worldwide (combining NEO with the Indie and Matrix LMS for corporate markets). In higher ed, their largest implementation is with STI College in the Philippines with a systemwide deal that gives them 77 campus adoptions. The system has been designed native to the cloud and boasts a fairly intuitive user interface that addresses competency-based education and mastery learning.

    • Claroline Connect is an Open Source project run out of France: This system – which has the greatest adoption in Europe, Latin America, and Asia – is a second-generation open source project. In the early 2000s, the University of Lyon and the Université catholique de Louvain created two open source LMSs, and subsequently Claroline Connect combined these projects into the current system based on more modern technology. Get your French ready, or use captions.

    • Chamilo is an Open Source project run out of Spain: This system, used most often in Latin America and Europe, also has origins in the predecessors to Claroline, forking into the Dokeos project and then forking again to Chamilo in 2010. The system is supported by official supporting vendors in the following countries: Belgium, Spain, Italy and Germany. The Belgian company also has offices in Peru. Again, get your French ready.

    While we have only described this second tier of global LMS providers in broad strokes, we hope this post gives a richer view of the broader LMS market and available systems.

  • Terminology is Key to Understanding Blackboard Learn Prospects

    Terminology is Key to Understanding Blackboard Learn Prospects

    There are three observations from Blackboard’s users conference that we feel are important to share before we pull together our thoughts for more comprehensive posts, and all three issues build off of Blackboard’s strong focus at the conference on Learn Ultra as the future of their LMS product line.

    Learn Ultra “In Production” or “Using Ultra”

    The first issue is terminology around Learn Ultra. Blackboard ((Disclosure: Blackboard is a client of the e-Literate LMS Market Analysis service and a participating sponsor in our Empirical Educator Project.)) is pushing the metric that there are 61 or 62 Learn Ultra customers “in production” or “using Ultra”, yet we have found very few that use, or even plan to use, Learn Ultra as their primary, institution-wide LMS. What gives? What became quite clear at the conference is that when Blackboard says in production, what they mean is that the LMS administrator has enabled the Ultra global navigation, which uses the new Ultra user experience framework as the landing page / dashboard with activity feed that users see before entering a specific course. The company calls this Base Navigation, but at this point every course can be configured to be in the Original Experience or the Ultra Experience. Thus, enabling the possibility of running a course in Ultra counts as in production.

    Slide from BbWorld18

    Once a school has enabled Learn Ultra Base Navigation, they could choose to move exclusively to Ultra (e.g. the University of Phoenix, Northwest Florida State College, and a few others), or they could choose to keep all courses in Original (e.g. Northeastern State University), or they could choose to have some courses in Ultra and some in Original (used by the majority of schools investigating Ultra). This last mode is known as Dual Course mode, and even Blackboard executives are surprised to find out that the vast majority of schools putting Ultra in production are in fact running in Dual Course. For many of these schools, there are no definitive plans to ever move exclusively to Ultra.

    This distinction is important, as the majority of functionality for an LMS occurs within a course, even if we did hear a few schools present that they saw some end-user benefits to having the landing page itself. We will add more commentary on this subject in future posts, but for now the takeaway is that Ultra in production numbers from Blackboard do not necessarily mean that any or most courses are in the Ultra Experience.

    Product Variations Resulting in Three Dates for New Features

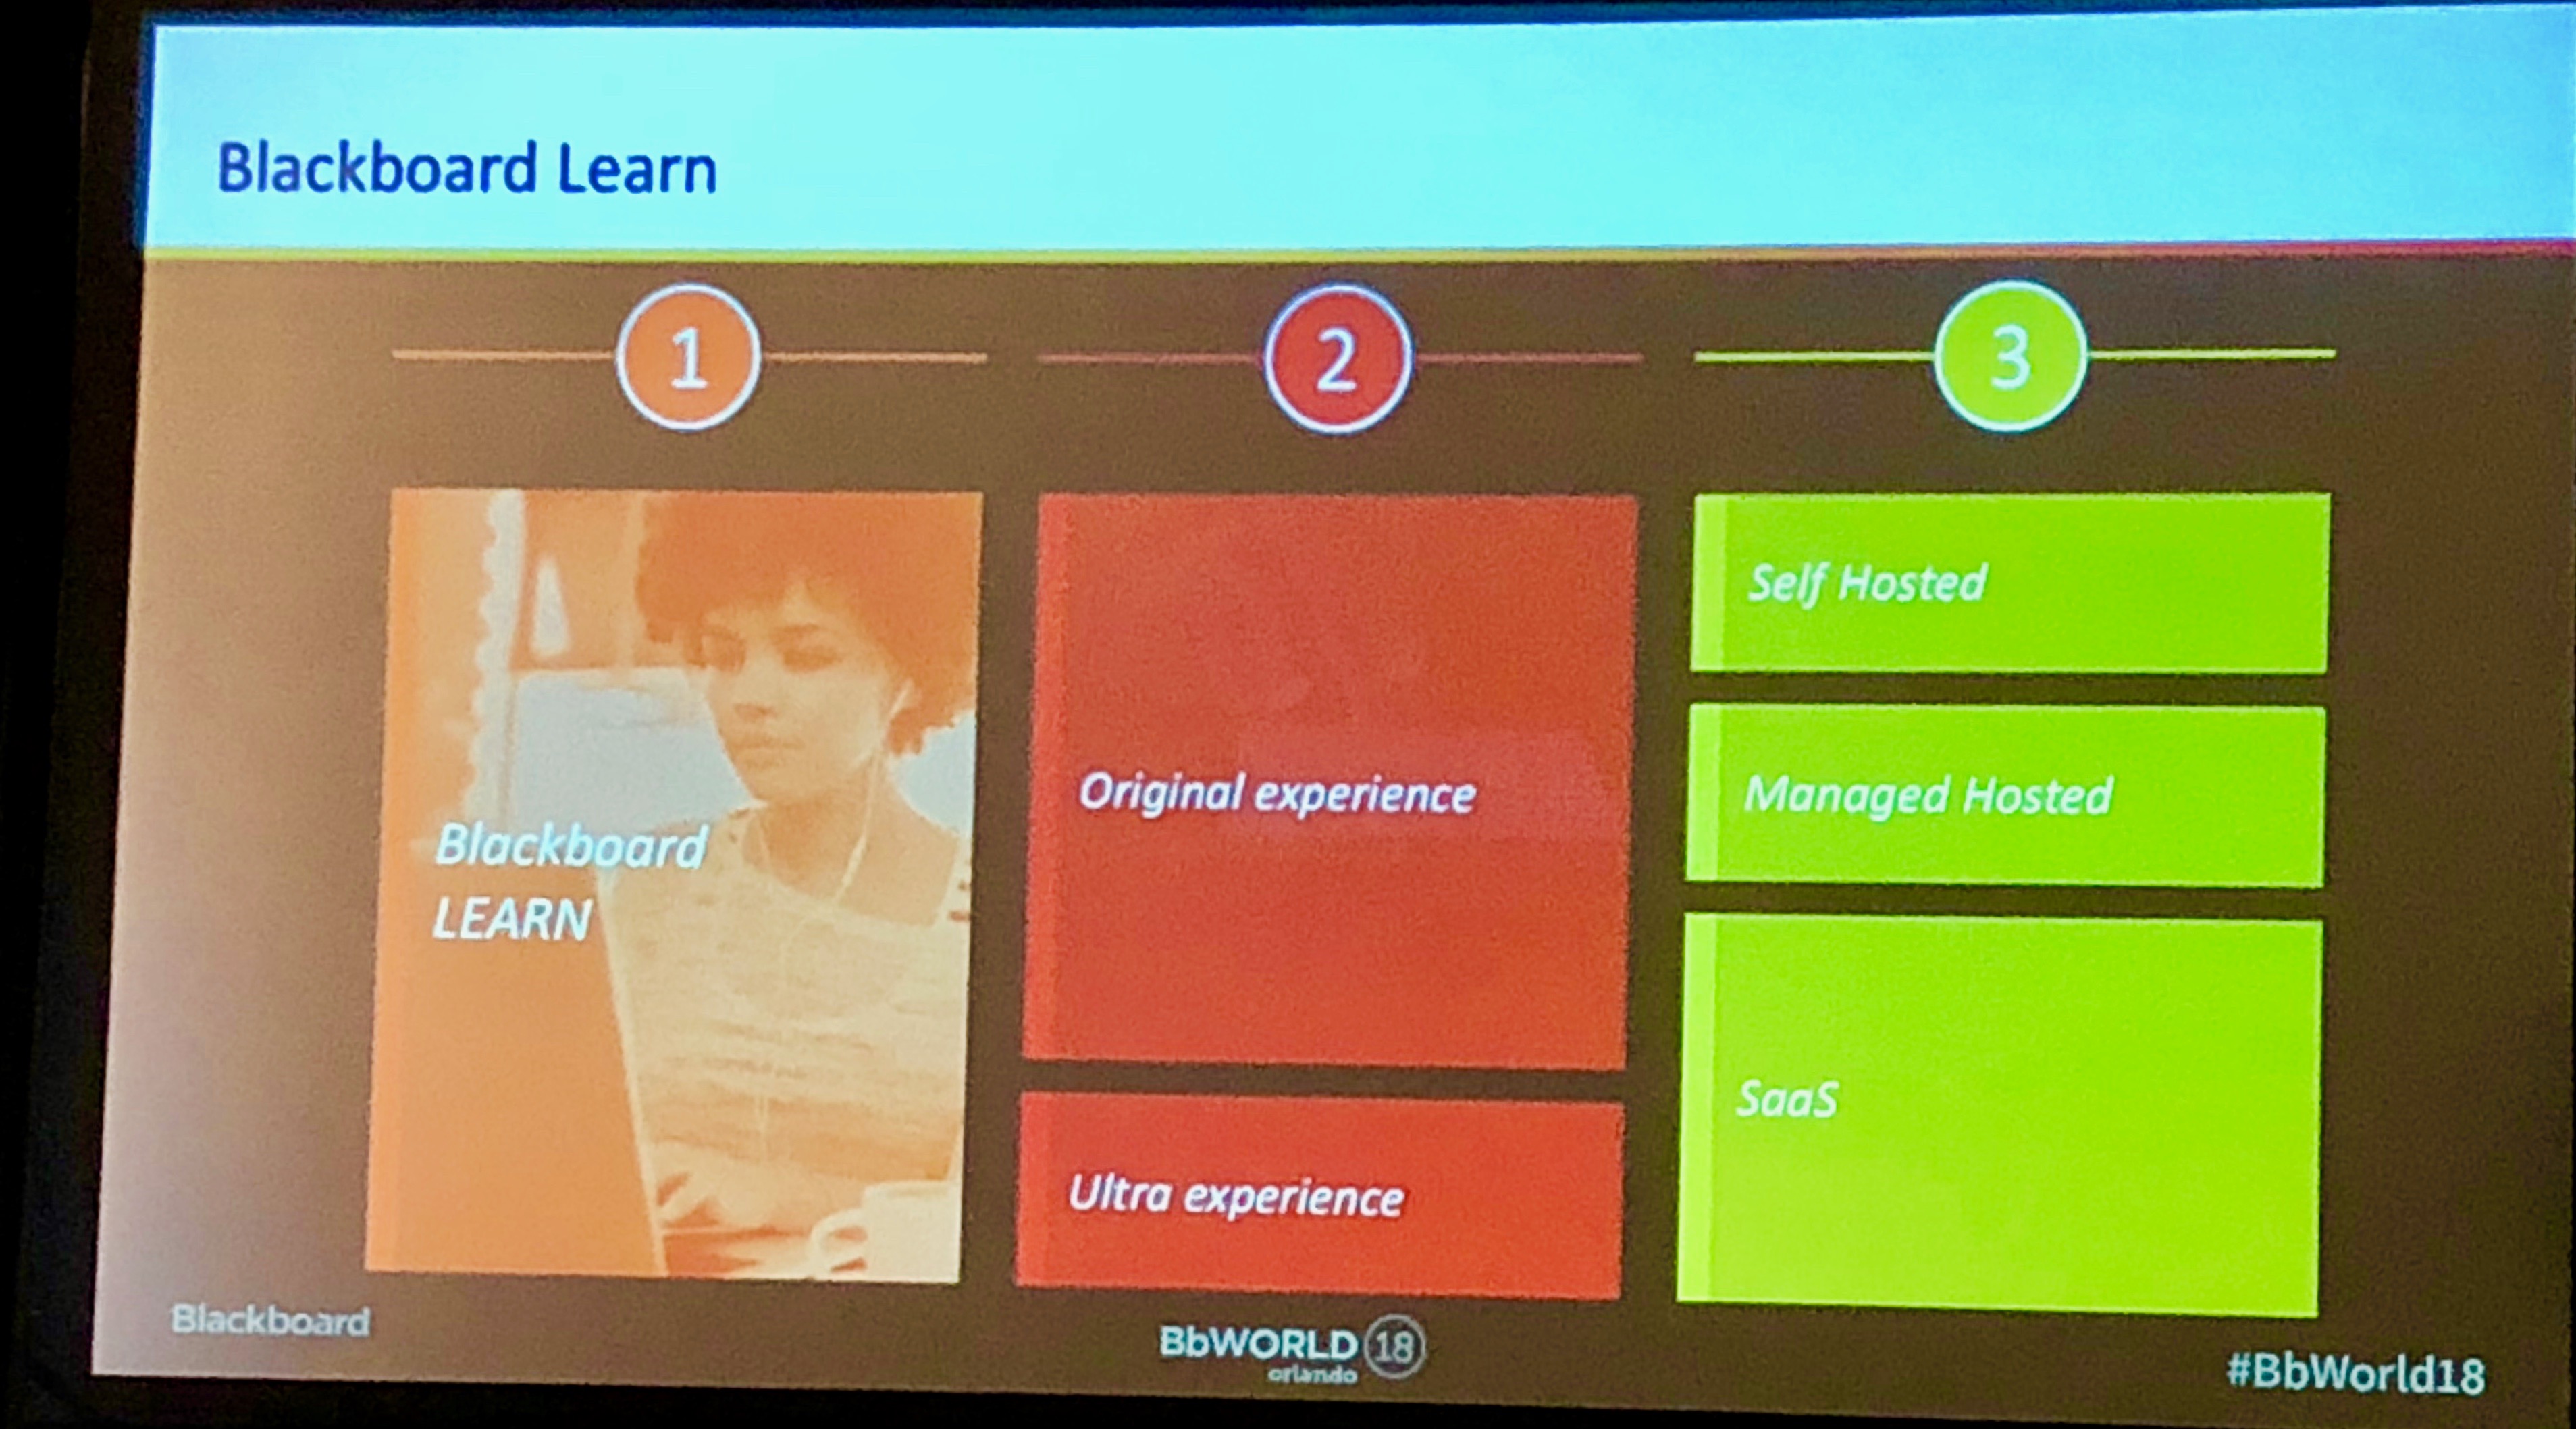
    The second issue is that Blackboard Learn has two experiences (Ultra and Original), three deployments (self-hosting, managed-hosting by Blackboard, and SaaS-hosting at using AWS), often resulting in three different dates for full delivery of new features.

    Slide from BbWorld18

    Keeping in mind that the Original Experience is available on all three deployment models but Ultra is available only in SaaS, here is the view of the final delivery groupings for the courses:

    • Learn Original on self-hosting and Learn Original on managed-hosting, which the bulk of their customers use, is the first case.
    • Learn Original on SaaS-hosting, which represents the bulk of their 383 customers on Learn SaaS announced at the conference, is the second case.
    • Learn Ultra, which represents some subset of the 62 customers announced as “Ultra in production”, is the third case.

    Of course there is significant overlap in terms of common code, such as the micro-services running in the SaaS environment for both experiences, or shared source code between deployment options. But from a feature delivery perspective, the full release often has three different delivery dates – Original SH & MH, Original SaaS, and Ultra.

    This is good news or bad news, depending on your perspective. For Blackboard’s customers, it means more options without forced migrations. Blackboard staff stated several times in presentations and in hallway conversations that none of the deployment options or experiences have any plans to go end-of-life or even into maintenance mode. But on the other hand, Blackboard will not achieve many of the benefits of becoming a cloud product company until they can move the majority of development purely onto SaaS.

    SaaS Better Indicator Than Ultra of Client Retention

    The third issue, which is related to the first two, is that we believe ((OK, OK. I admit that Michael should get credit for seeing this issue more clearly than I did. Not many people read footnotes, so I feel comfortable with this admission.)) that the migration to Learn SaaS might be a better indicator – at least in the short run – than Ultra adoption of whether a school plans to stick with Blackboard. Whether or not the school enables Ultra base navigation or any courses in the Ultra Experience.

    When a school moves to Learn SaaS, they tend to sign contract extensions for 1 – 3 years to cover the new services. And the migration to Learn SaaS does not suffer from the vague terminology issues – a school either uses Learn deployed on SaaS (through AWS) or they don’t.

    For now, just treat this as clarification on the complexities of Blackboard Learn LMS options that became more apparent at the conference.

    Update 7/23: Changed header and some text in second section to focus on dates of feature delivery.