
e-Literate

Present is Prologue

Tag: M&A

  • Winter Is Here: EdTech investments and M&A dropped significantly in 2016

    Winter Is Here: EdTech investments and M&A dropped significantly in 2016

    With the long-term rise in Ed Tech investments – starting in roughly 2007 – many analysts have been predicting a fall for several years. Maybe not a bubble burst like we saw in 2001, but a real drop in activity and volume. Now we also find out that there is also a 70% drop in mergers and acquisition values for the education industry according to a new analysis by the investment bankers Berkery Noyes.

    Throughout 2016 we had plenty of signs that the change was finally here. I got into the act in response to a ludicrous TechCrunch article that concluded that Ed Tech was “2017’s big, untapped and safe investor opportunity”. By the end of the year, there were several reports that investment (venture capital, private equity) had definitely gone down in 2016. Audrey Watters reported “The total dollars invested in 2016 are off by about $2 billion from this time last year”. EdSurge reported a drop of 31%. CB Insights reported a drop of 32% (based on estimates for Q4). (more…)
  • The Massive Decline In Larger Education Company Market Caps

    After our coverage of Blackboard’s CEO change last week, we were both interviewed by the Washington Business Journal, with the following lede:

    Analysts and sources I spoke with Monday, both on and off the record, said the decision to bring on Bill Ballhaus as CEO was a combination of Bhatt failing to make progress building the company’s business and lacking the experience needed to successfully run a company of that scale. And that means at least several years before Providence Equity Partners, which owns a majority of the company after paying $1.64 billion for it in July 2011, begins actively marketing the company for sale, according to industry experts.

    Earlier this week I wrote about Apollo Education Group, parent of the University of Phoenix, putting itself up for sale due to its weakening financial position. I also noted that I doubt that McGraw-Hill Education is going to be able to go public in the near-term. Part of the reason for this latter observation is the dramatic fall of Pearson in the stock market, triggered by its warnings that it would miss earnings estimates. In Audrey’s excellent year-end post on the business of ed tech, she noted:

    Private equity firms sure love buying ed-tech companies. Perhaps because the stock market’s sorta “meh” about them.

    (more…)

  • Blackboard Potential Sale: Market timing, financials, and some thoughts on potential buyers

    With Reuters’ story last week that Blackboard is putting itself up for sale through an auction, one question to ask is ‘why now?’. As Michael has pointed out, Blackboard is in the midst of a significant, but incomplete and late, re-architecture of its product line.

    Bottom line: If you think that Ultra is all about playing catch-up with Instructure on usability, then the company’s late delivery, functionality gaps, and weird restrictions on where the product can and cannot be run look pretty terrible. But that’s probably not the right way to think about Ultra. The best analogy I can come up with is Apple’s Mac OS X. In both cases, we have a company that is trying to bring a large installed base of customers onto a substantially new architecture and new user experience without sending them running for the hills (or the competitors). This is a really hard challenge.

    Market Timing

    On the surface, it seems to be a high-risk move to try and sell a company before the changes are solidly in place and customers have demonstrated that they will move to new architecture rather than “running for the hills”.

    Assuming that the Reuters story is accurate, I believe the answer to the question on ‘why now’ is that this move is about market timing – Blackboard wants to ride the current ed tech investment wave, and Providence Equity Partners (their owners) believe they can get maximum value now. This consideration trumps the otherwise logical strategy of waiting until more of the risk from the new user experience and cloud platform roll-out is removed by getting real products into significant number of customers’ hands. VC investment and M&A activity are at high and potentially unsustainable levels. 2U has shown that ed tech companies can go public and be a success. Lynda.com has shown that relatively mature companies can be acquired for very high valuations. Instructure is likely to go public in early 2016. If you want to get a high price, sometimes it’s worth going on a hot market before addressing most of the re-architecture risk. (more…)

  • Reuters: Blackboard up for sale, seeking up to $3 billion in auction

    As I was writing a post about Blackboard’s key challenges, I get notice from Reuters (anonymous sources, so interpret accordingly) that the company is on the market, seeking up to $3 billion. From Reuters:

    Blackboard Inc, a U.S. software company that provides learning tools for high school and university classrooms, is exploring a sale that it hopes could value it at as much as $3 billion, including debt, according to people familiar with the matter.

    Blackboard’s majority owner, private equity firm Providence Equity Partners LLC, has hired Deutsche Bank AG and Bank of America Corp to run an auction for the company, the people said this week. [snip]

    Providence took Blackboard private in 2011 for $1.64 billion and also assumed $130 million in net debt.

    A pioneer in education management software, Blackboard has seen its growth slow in recent years as cheaper and faster software upstarts such as Instructure Inc have tried to encroach on its turf. Since its launch in 2011, Instructure has signed up 1,200 colleges and school districts, according to its website.

    This news makes the messaging from BbWorld as well as their ability to execute on strategy, particularly delivering the new Ultra user experience across all product lines – including the core LMS – much more important. I’ll get to that subject in the next post. (more…)

  • Why LinkedIn Matters

    A few folks have asked me to elaborate on why I think LinkedIn is the most interesting—and possibly the most consequential—company in ed tech.

    Imagine that you wanted to do a longitudinal study of how students from a particular college do in their careers, or the effect of social media for brick and mortar in a particular local geographical location for strategic placement of services that local market is lacking. In other words, you want to study long-term outcomes. How did going to that college affect their careers? Do some majors do better than others? And how do alumni fare when compared to their peers who went to other schools? Think about how you would get the data. The college could ask alumni, but it would be very hard to get a good response rate, and even then, the data would go stale pretty quickly. There are governmental data sources you could look at, but there are all kinds of thorny privacy and regulatory issues.

    There is only one place in the world I know of where bazillions of people voluntarily enter their longitudinal college and career information, keep it up-to-date, and actually want it to be public.

    LinkedIn. (more…)

  • LinkedIn: I Told You So (Sorta)

    In December 2012, I tweeted:

    https://twitter.com/mfeldstein67/status/276406235564220416

    At the time, Coursera was the darling of online ed startups. Since then, it has lost its way somewhat, while Lynda.com has taken off like a rocket. Which is probably one big reason why LinkedIn chose to acquire Lynda.com (rather than Coursera) for $1.5 billion. I still think it’s possible that they could acquire a MOOC provider as well, but Udacity seems like a better fit than Coursera at this point.

    I’ve said it before and I’ll say it again: LinkedIn is the most interesting company in ed tech.

  • Education M&A Activity in 2013: Still growing, but changing

    Like it or not, education is an industry, and much of the change we see affecting higher ed and K-12 institutions is driven by investment from the private sector. It can be useful to get a high-level view of the trends in private investments to help understand where private companies (edtech vendors, publishers, for-profit institutions, etc) are likely to move in the future.

    According to a new year-end report from Berkerey Noyes, a US-based investment banker, merger and acquisition activity in the education industry continued to grow in 2013, with the 9 of the 10 largest deals occurring outside of the US. As summarized at Education Week:

    A number of recent reports have shown or predicted a strong and growing demand for various educational products and services in markets such as Latin America, and the new, year-end report on transactions published by Berkery Noyes would seem to reinforce that portrait.

    “The big education players are acquiring to help manage the transition from print to digital,” Peter Yoon, managing director of Berkery Noyes’ education group, said in an interview. He said they’re also moving to “strengthen their presence in emerging markets.”

    The most active acquirer was Pearson PLC, with six deals that included the “acquisition of Grupo Multi Holding, an English language training company headquartered in Brazil, for $829 million”.

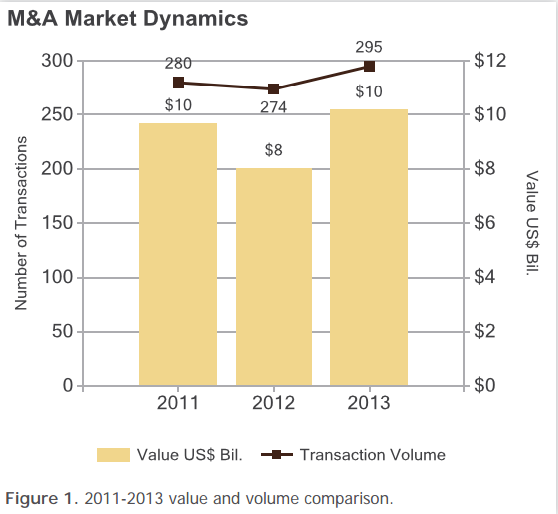
    In total there were 295 transactions for a total of $10.2 billion in value, which represented year-over-year growth of 8 and 27% respectively.

    Summary

    Beyond the international growth, there are two other items that jumped out at me – the shift towards strategic buyers and the strong growth in professional training.

    (more…)