e-Literate

Present is Prologue

Tag: OPM

  • The MOOC-Courseware Convergence

    Now that Coursera for Campus—which I have occasionally erroneously referred to as “Coursera for Schools” in previous blog posts—has been launched, we have some more information about what it’s really about. (I’ll embed the launch video at the bottom of the post, but if you’d rather go straight to it, you can find it here.) I think it’s significant and portends significant trends in the sector.

    Before we get to that, let’s get one item of business out of the way related to my previous posts. As IBL Education notes, Coursera CEO Jeff Maggioncalda said, “Coursera for Campus is not a full-featured LMS. We expect many universities to stay on their LMSs.” IBL News further notes, “According to the company, Coursera for Campus’ LMS is designed to supplement the existing Canvas, Blackboard and Moodle systems.” [Emphasis in original.]

    So Coursera for Campus isn’t LMS play, at least for the foreseeable future. I was pretty harsh on Coursera’s SVP of Enterprise Leah Belsky for her disruption language, but as I’ll get into later in this post, this kind of category mistake is actually quite easy to make and one that other courseware providers have made.

    Because that is exactly what Coursera has explicitly become with their Courseware for Campus offering: a courseware provider. The less obvious part is that MOOC design and courseware design have been converging for some time now. Their increasing similarities in instructional affordances have been masked by the differences in the business models of their parent companies. And even less obvious is that the Venn diagram of courseware companies and OPM companies is starting to overlap significantly.

    “A 21st-Century textbook”

    In the launch presentation, Maggioncalda called Coursera for Campus, in part, a “21st-Century textbook.” Take that seriously. These are MOOCs repurposed as curricular materials. And it’s really not that big of a leap. Remember that the pedagogical model of the xMOOC course generally doesn’t require heavy participation from the instructor. Some instructors do participate heavily, while others, less so. A lot of instructor energy goes into course design and lecture video production. The actual live support could be from the instructor, but it also could be from TAs, or it could be self-study. Or, in the case of Coursera for Campus, it could be a different instructor. From its inception, the design model of xMOOCs began decoupling faculty course design from faculty course delivery.

    There is some messiness, of course. The biggest challenge in terms of textbook-like may be the lecture videos. Faculty may not love having some other personality featured as the star of the show. But there are two mitigating factors to that. First, Coursera’s design staff is likely guiding faculty toward authoring instructionally sound videos, which would tend to reduce the total amount of talking head content in any given course. Second, textbook-provided commercial courseware, which is still often written by star authors in their field, now also features talking heads. Here, for example, is the Cengage MindTap introductory video for Economics, by author Greg Mankiw:

    Greg Mankiw’s head, talking

    “But,” you may be thinking, “MOOCs are not designed like courseware.” One of my Twitter followers made a comment to the effect that at least courseware has an instructional design philosophy, unlike xMOOCs.

    That person is mistaken, and here is the proof:
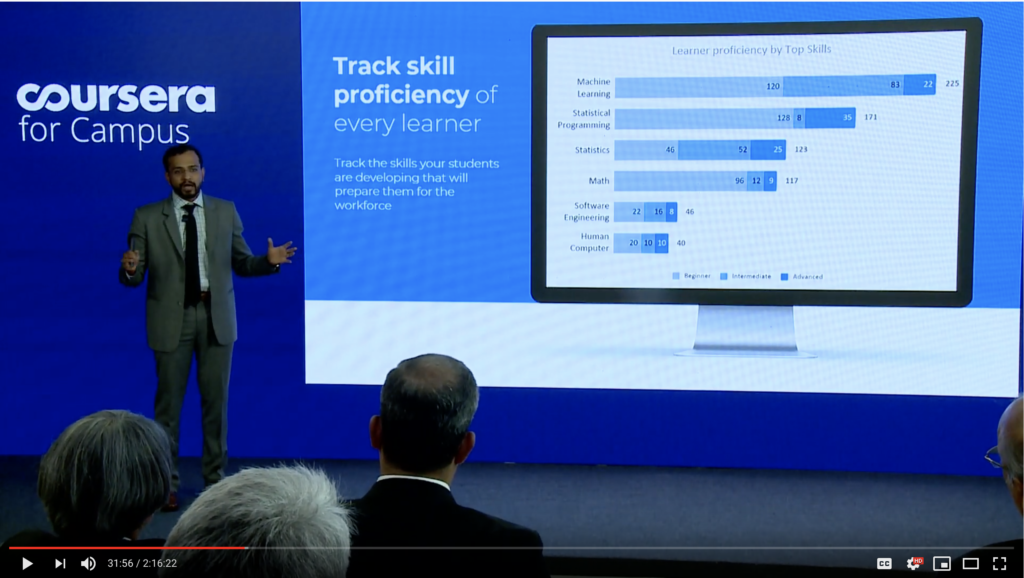
    These analytics are only possible with backward design

    During the launch presentation, a Coursera executive made the statement that “any of the courses that have been authored on Coursera come with an out-of-the-box analytics platform.” If those analytics look anything like the picture above—and I would bet money that they do—then the courses have been built on a backward design philosophy like the one I have been describing in my recent post series on content as infrastructure.

    This shouldn’t be surprising. As I wrote repeatedly throughout that series, almost every professionally designed course uses that design pattern. And Coursera is known for having strong professional course design support.

    (I’m telling you, folks. That content pattern is the revolution of our time.)

    Update: Matthew Rascoff has reminded me to acknowledge that the professional course designers on campuses play large and critical roles in the design of these courses. The larger point is that, on both sides of the fence, there are trained, professional course designers who are applying this design pattern.

    While I haven’t looked at their catalog myself in quite some time, I would not be surprised at all if many of their offerings stack up pretty well against commercial courseware titles. For one thing, while xMOOCs have a bad reputation for anemic social interaction relative to other course models, they probably have more social interaction designed into them than many commercially published courseware titles.

    Courseware platforms vs LMSs

    It’s easy to get confused about the boundary between a courseware platform and an LMS. I know because I have worked on and consulted on both. The LMS companies inevitably start thinking, “Damn, there are so many courses that get delivered through our platform, and so much money made on selling them. And guess what? Everything that faculty build and deliver through our product is a course! The textbook publishers keep rebuilding what we’ve already built. Badly. I mean, have you seen their grade books? Why can’t we be the platform and get a cut of all that money?”

    So they try to displace the publishers. And they fail. Every time.

    The textbook publishers, meanwhile, start thinking, “Damn, our customers really hate their LMSs. We’ve built all these LMS features, and they keep asking for more. I mean, we’ve already built a grade book. Wow, that was painful. Why can’t we be the platform and get a cut of all that money?”

    So they try to displace the LMS companies. And they fail. Every time.

    Here’s the critical difference:

    LMS developers have to optimize for a wide range of faculty preferences, teaching styles, and teaching conditions. They have to accommodate every grading scheme imaginable. They have to handle huge classes and tiny classes. They have to deal with face-to-face, online, and blended. Constructivist, lecture, and whatever else. That’s why they spend so much time adding grade book micro-features and then optimizing the usability to handle all those micro-features without being totally overwhelming.

    Courseware developers, in contrast, have to optimize for the content. If the subject is software development, then you need an interactive code editor and test engine. If it’s accounting, then you need a test engine that looks like a spreadsheet. If it’s chemistry, then you need a molecule visualizer and manipulator.

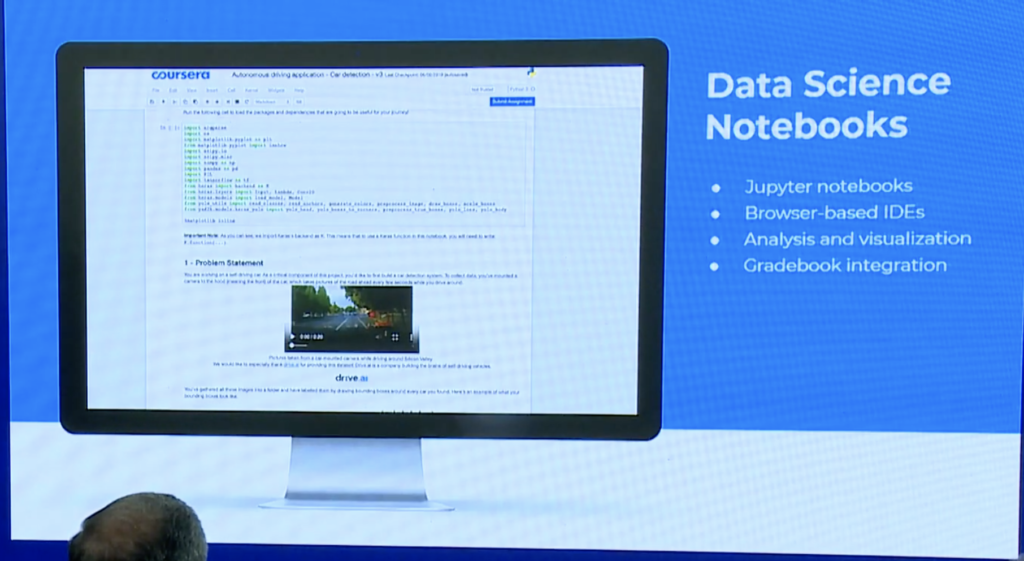
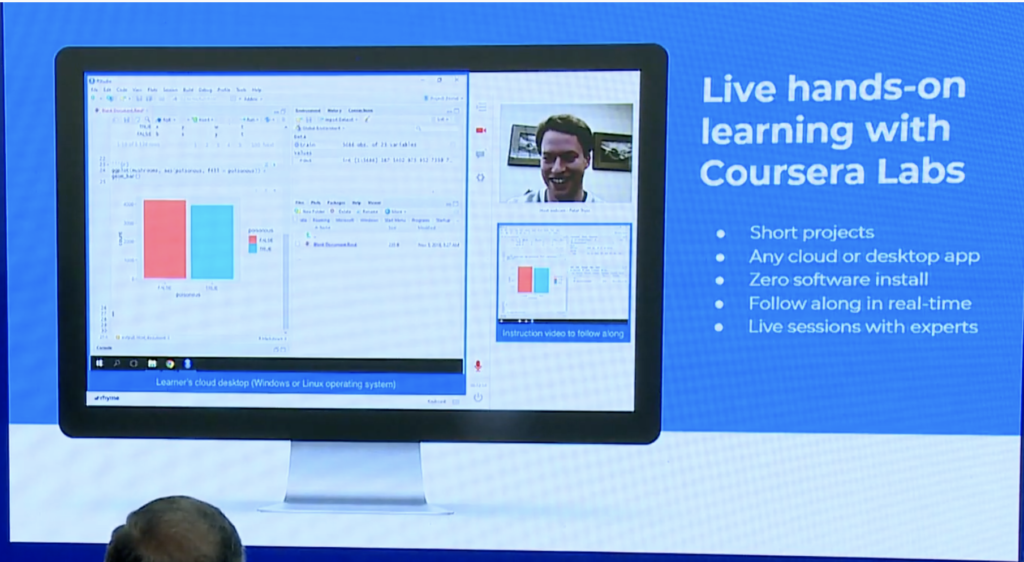
    Which side of the divide do MOOC platforms land on? Here are a couple of slides from the Coursera on Campus launch:
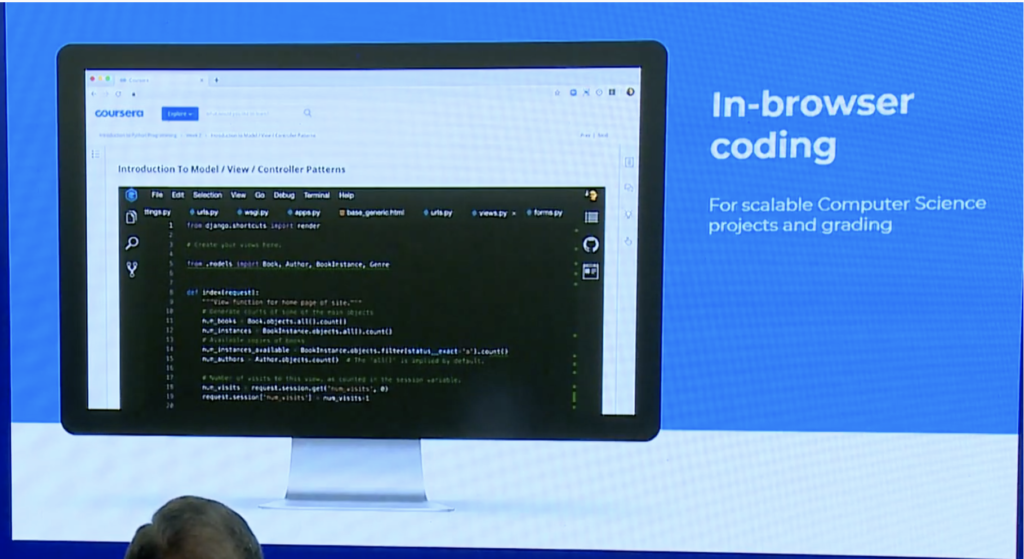
    In-browser coding!
    Virtual labs!
    Data science notebooks!

    These subject-specific affordances, plus competency-based analytics, were the platform highlights of the Coursera for Campus presentation. Not the grade book that can do anything. Not the test engine that can provide any kind of feedback. Not announcements or an event feed. This was all about courseware.

    “But wait,” you say. “Courseware for Campus lets faculty author their own courses. Isn’t that different?”

    Yes. And no.

    Way back the better part of a decade ago, when I was at Cengage working on the MindTap platform, the company debated whether to open it up to customers and license it without content. (“We can disrupt the LMS!”) In the end, there were two major barriers. First, as a print-centric company in the midst of a transition, the authoring tools were not remotely faculty-friendly. And second, as a publisher whose bread and butter came from royalties, there was a fear of cannibalization of the business.

    Coursera has neither of those problems. It was born as a two-sided market, which means that it never owned the content to begin with and always had an incentive to make authoring as easy as possible. It may have taken some time to fully realize that vision, but we were destined to arrive where we are now.

    Further, as textbook publishers increasingly move away from celebrity franchises and toward fee-for-service contracts with their authors, they will have motivation to make similar moves. McGraw-Hill Education doesn’t advertise it widely, but they have been licensing the authoring platform for SmartBooks for several years now. Authoring support can work with a courseware platform as long as the range of course expectations for delivery models can be constrained. And MOOC courseware fits the bill. It’s a genre.

    Coursera for Campus is a harbinger of the future, not for the LMS industry but for the textbook industry. And they are an early mover with certain advantages in their business model.

    The courseware/OPM convergence

    One critical element that I don’t want to lose in all of this is the implications for the OPM market. Let’s not forget that (a) Coursera has been pushing into that market aggressively and successfully and (b) that market has been under massive pressure and upheaval lately. 2U has been the canary in the coal mine, having lost roughly four fifths of its market value since the beginning of the year. ((Disclosure: 2U is a 2019 sponsor of EEP.))

    To be clear, I think there’s some noise obscuring the signal. Two of the reasons why 2U took such a big hit are that the stock got way ahead of itself and some self-interested players have been extraordinarily successful at generating FUD around the market category in general.

    That said, there is no question that the hype around selling an infinite number of $40K masters degrees has met its demise. There are two barriers to OPM growth, which is another way of saying that there are two barriers to conventional online degree growth, and they have both proven formidable barriers to crack. The obvious one is cost. The less obvious one is geography. It turns out that, even in an era when people can take courses from anywhere in the world, they will tend to take them from their local institution or not at all. For all the talk of “national universities” and “mega universities,” it’s not clear that such beasts really exist. For the most part, big universities have proven exceptionally good at soaking up every ounce of demand for education in their local areas. So the next sustainability play is not so much about reaching students far away as it is about serving students you already reach for 40 years rather than for four.

    And interestingly, that is essentially the pitch that the Coursera executives made about Coursera for Campus—even when they were pitching in India. They weren’t making the pitch that the American stereotype would have predicted, of reaching the rural millions. They were talking about lifelong learning. Skilling and reskilling. From an OPM perspective, this pitch gives the company with the large catalog of low-cost and constantly refreshed inventory a competitive advantage.

    That said, there was definitely a bit of hand waving going on regarding completion rate. The Coursera executives talked about University of Illinois’ degree program as having over a 90% completion rate as if that remarkable achievement could be solely attributed to the fact that it was a degree program. I suspect there are some hard-working support staff at the University of Illinois who might quibble with that clean of a causal analysis. I don’t think the Coursera folks are directionally wrong, and I don’t think they were intentionally misleading, either. But I do think that they oversimplified, and that running a highly successful program at scale with a 90%+ degree completion rate entails a lot more than just handing out a piece of sheep skin at the end. The reason I bring this up is not because I want to snark on Coursera but because the part that is being glossed over represents a number of support areas that OPMs compete on (and that more traditional OPMs and OPEs pride themselves on excelling at).

    The gap between “MOOC” the course model and “MOOC” the courseware model is very much an open question in terms of student success. The MOOC courseware model, particularly as implemented into affordable degrees at scale delivery models by pioneers like Georgia Tech and University of Illinois, are creating an alternative delivery model that could start putting pressure on OPMs supporting more traditional models. Coursera on Campus, in addition to creating an additional revenue stream for the company and putting pressure on courseware providers, potentially ups the ante in the OPM market. But we need to look to those universities which are pioneering affordable degrees at scale to understand the service gaps, marketing gaps, and cost differences between MOOC courseware and the totality of what they are doing in order to understand the what it would take to replicate their success.

    In the meantime, consider the implications of the Coursera on Campus model for the future of companies like Pearson and Wiley, which own both courseware and OPM divisions, or McGraw-Hill Education, which has begun experimenting with opening up its platform for content authoring by customers. ((Disclosure: Pearson is a 2019 sponsor of the Empirical Educator Project.)) It’s not necessarily all bad, but it is a potential accelerant to change that is already in the wind.

    It’s a wild, wild, wild, wild world, my friends.

    Here’s the full launch event for your viewing pleasure:

  • I’m Giving a Live-streamed Talk on Thursday at SUNY

    I’ll be giving a talk at the OpenSUNY conference tomorrow (Thursday) at 4:00 PM. The title of the talk is “Everything Old is New Again: What You Taught the OPM Companies.” But it’s about a lot more than that. SUNY was my first gig in higher education, after doing stints in K12 and corporate e-Learning, so it’s going to be a bit of a homecoming for me. I’ll be sharing some lessons learned over the intervening 14 years—for me and for them.

    The streaming URL is at http://opensunysummit2019.edublogs.org/mediasite/. I believe the video will also be available afterward for those who can’t catch the talk live.

  • OPM Readings: New policy briefing from UCT and other useful coverage

    OPM Readings: New policy briefing from UCT and other useful coverage

    Over the past eight days there have been a series of valuable articles covering Online Program Management (OPM) and the broader Online Program Enablement (OPE) markets. ((See this post to better understand the OPE concept.)) All four articles provide useful historical and academic environment context to better understand market dynamics.

    University of Cape Town Policy Briefing

    Laura Czerniewicz and Sukaina Walji from the University of Cape Town’s Centre for Innovation in Learning and Teaching (CILT) released Issues for universities using private companies for online education this week as a policy briefing for “universities who are thinking of using – or already using – private companies to develop or expand their online programmes or courses” ((I’ll stick with the South African English spelling in this section.))

    Rather than just focusing on the OPM market itself, Czerniewicz and Walji place the subject into the broader context of “marketisation, digitisation, unbundling and austerity climates.” This placement is valuable, as it frames the appropriate questions that colleges and universities should address when considering OPM or OPE vendor support.

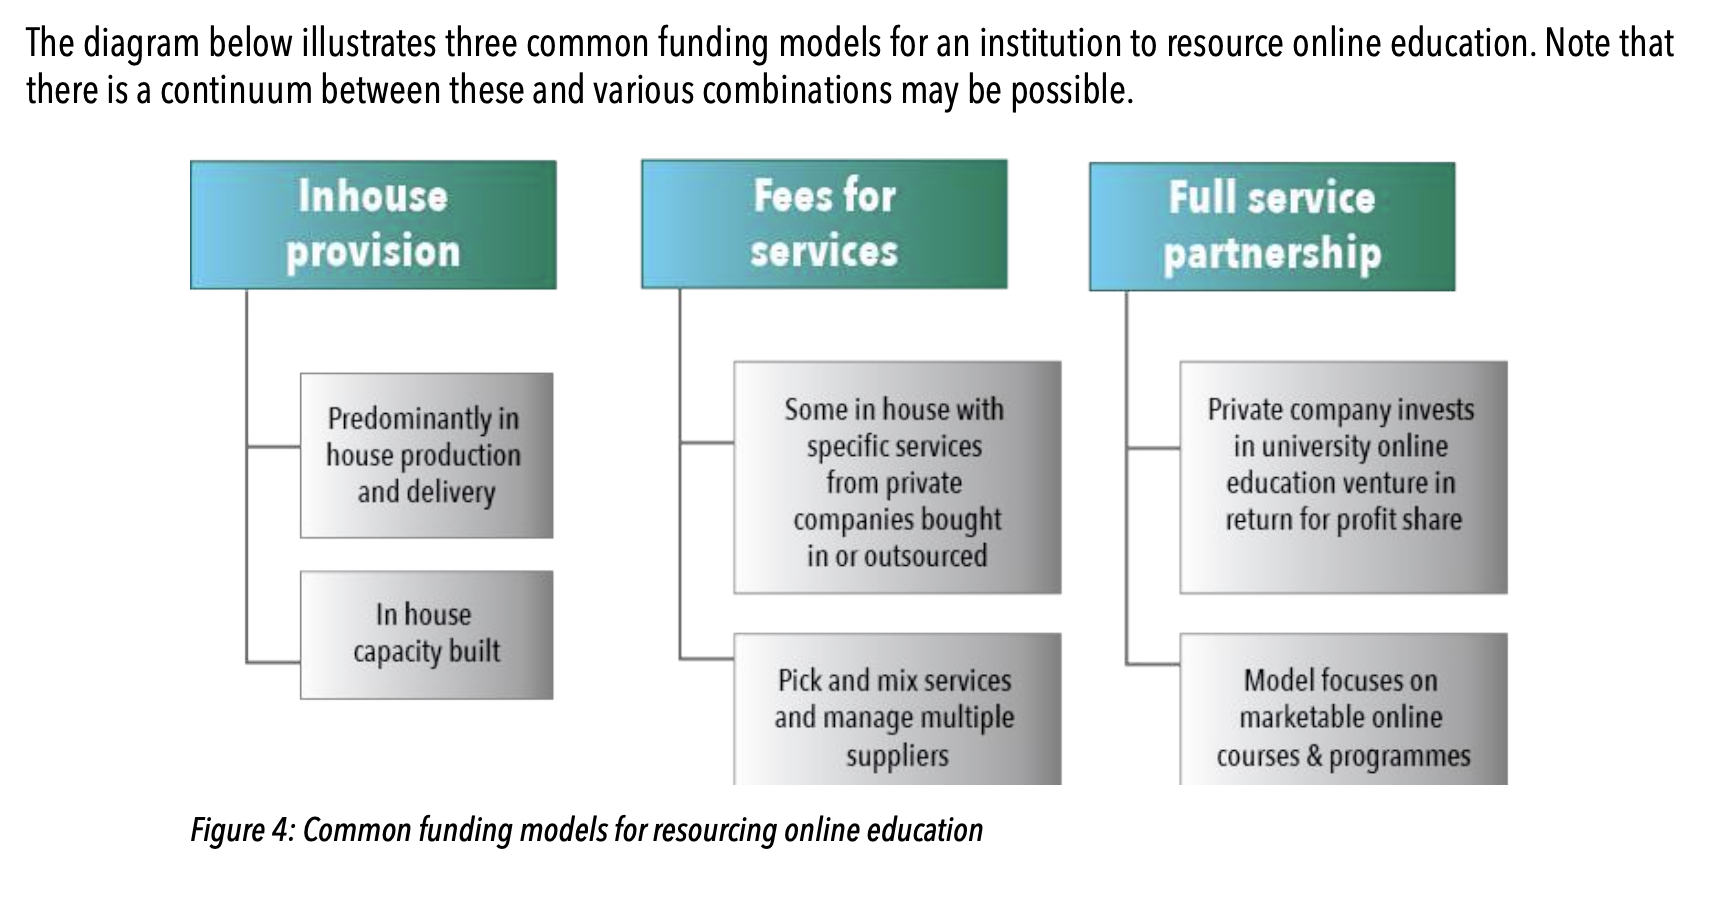
    After addressing why the OPM / OPE movement is becoming so important now – from an international perspective with some global south viewpoitns  – the briefing addresses the various funding models involved. The note in the description about these models being on a continuum with various combinations possible is crucial.

    Three common funding models - inhouse provision, fees for services, and full service partnership

    The briefing including a Strengths, Weaknesses, Opportunities, Threats (SWOT) analysis for the full-service OPM scenario and for an inhouse / fees-for-service scenario as well as use cases for different institution types. It is well-worth reading the whole report.

    EdSurge Debate on OPMs

    Last week EdSurge ran a two-article series on OPMs that missed the SNL’s Point / Counterpoint opportunity and instead tried the nuanced argument method.

    Dan, you pompous ass

    In the first post “How OPMs are the Modern Enrollment Managers”, Randy Best and Harris Pastides from Academic Partnerships described OPMs as a follow-on to the enrollment management companies that emerged in the 1970s, with OPMs partially taking credit for moving away from the for-profit sector.

    These OPMs, like enrollment management consultants decades before, assist universities in providing access to time-pressed, place-bound students for whom online education is the only choice for earning a degree. In doing so, OPMs shifted leadership in the market for online education from for-profit institutions, which dominated the landscape in the early days, to nonprofit institutions.

    After addressing four myths about OPMs, Best and Pastides position full-service revenue-sharing OPMs against the new movement of fee-for-service OPM / OPE providers.

    Given the evolution of OPMs, perhaps the time has come for a new name to describe them. They are not just managers, but partners with universities. They don’t just oversee programs, but perform operations critical to the overall success and reputation of the institution. And their efforts often result in the expansion of overall enrollment. In many ways, they should be called Enrollment Growth Partners.

    Some players in the OPM space who are not traditional comprehensive providers are trying to adopt the mantle of the future with fee-for-service or unbundled offerings. But fee-for-service simply shifts the cost and financial risk to universities. Meanwhile, by unbundling services—say by separating recruitment and retention—outside partners become solely focused on getting students in the door rather than keeping them through graduation.

    Michael wrote the second post “The ‘O’ in ‘OPM’ Could Stand for ‘Outsourcing’”, where instead of taking the simple pro / con approach to the debate, he argued for some nuance in our analysis. In particular, he took issue with the quoted description above.

    Michael’s historical context story differed from Best and Pastides, describing John Sperling’s history creating the University of Phoenix and how the current context for bundling and revenue models.

    The essential OPM characteristics of bundling and revenue sharing, both of which Pastides and Best tout as almost inherently good, contain trade-offs just like any other proposed solution to a complex problem. They balance growth opportunity against a range of risks, including risk that the up-front costs of launching the program would not be repaid, or that the universities could not execute well on essential aspects of the project (like student recruitment), or that they would let down the students by failing to maintain good quality of technology platform support or service at scale.

    There’s nothing inherently bad about managing these trade-offs through a full-service, bundled revenue sharing agreement. But there’s nothing inherently superior about the approach either. For example, universities that are more worried about the risk of failing to grow fast enough than they are about minimizing the expense of using an external vendor are often well served by finding a high-quality OPM partner, while universities with different risk profiles may come to different yet equally appropriate conclusions.

    Both posts are worth reading, and it is interesting to see the same issue described here and in the UCT briefing – about colleges and universities managing trade-offs when deciding which model is appropriate when selecting private partners to help with online programs.

    Education Dive

    Education Dive is running a three-part series on the issues involved with federal rule-making debates, and the first deep dive is “As traditional colleges grow online, OPM relationships shift”, describing the broadening market while traditional schools and systems like SUNY look to develop a strategy for online education.

    The State University of New York (SUNY) is one of several public systems looking to raise its profile online. An early pioneer with its Open SUNY platform, the 64-campus system in July issued a request for information about how it could “take the next step in creating a comprehensive environment” for online learning within and beyond New York state. [snip]

    The document, which Education Dive obtained, mentions a desire to “leapfrog competition” and “challenge current leaders in the field.”

    The article explores several of the OPM-related topics as well as motivations for traditional institutions developing online strategy, based on a series of interviews that included Michael. The key theme of the article described how the OPM market is changing, and the boundaries between online and face-to-face education are blurring.

    Soliciting OPM services for ground-based and hybrid programs can help colleges present a unified face in the market when they offer both on-campus and online versions of a program. Wiley, for example, provides full-service marketing support targeting prospective students for George Mason’s online and campus-based MBAs. That includes SEO, paid search, online advertising and social media.

    “The dialogues (are) more and more moving toward broadening the services to be more than just about the fully online student (but) to be about the student at the university no matter what their modality,” [co-president of Wiley Education Services and Learning House] Hillman said.

    That could lead to an uptick in blended and hybrid experiences, [co-founder and CEO of iDesign] Riter predicts, where learners navigate instruction online and on campus.

    “Over time there’s going to be less difference between online and face-to-face education,” he said. “It’s just going to be education, and even face-to-face residential education that exists today is going to be much more technologically infused.”

    It’s good to see four separate articles all worth reading about the emerging and broadening OPM market, with useful context.

  • MOOCs in Decline: Insights into multi-year data from MIT and Harvard

    MOOCs in Decline: Insights into multi-year data from MIT and Harvard

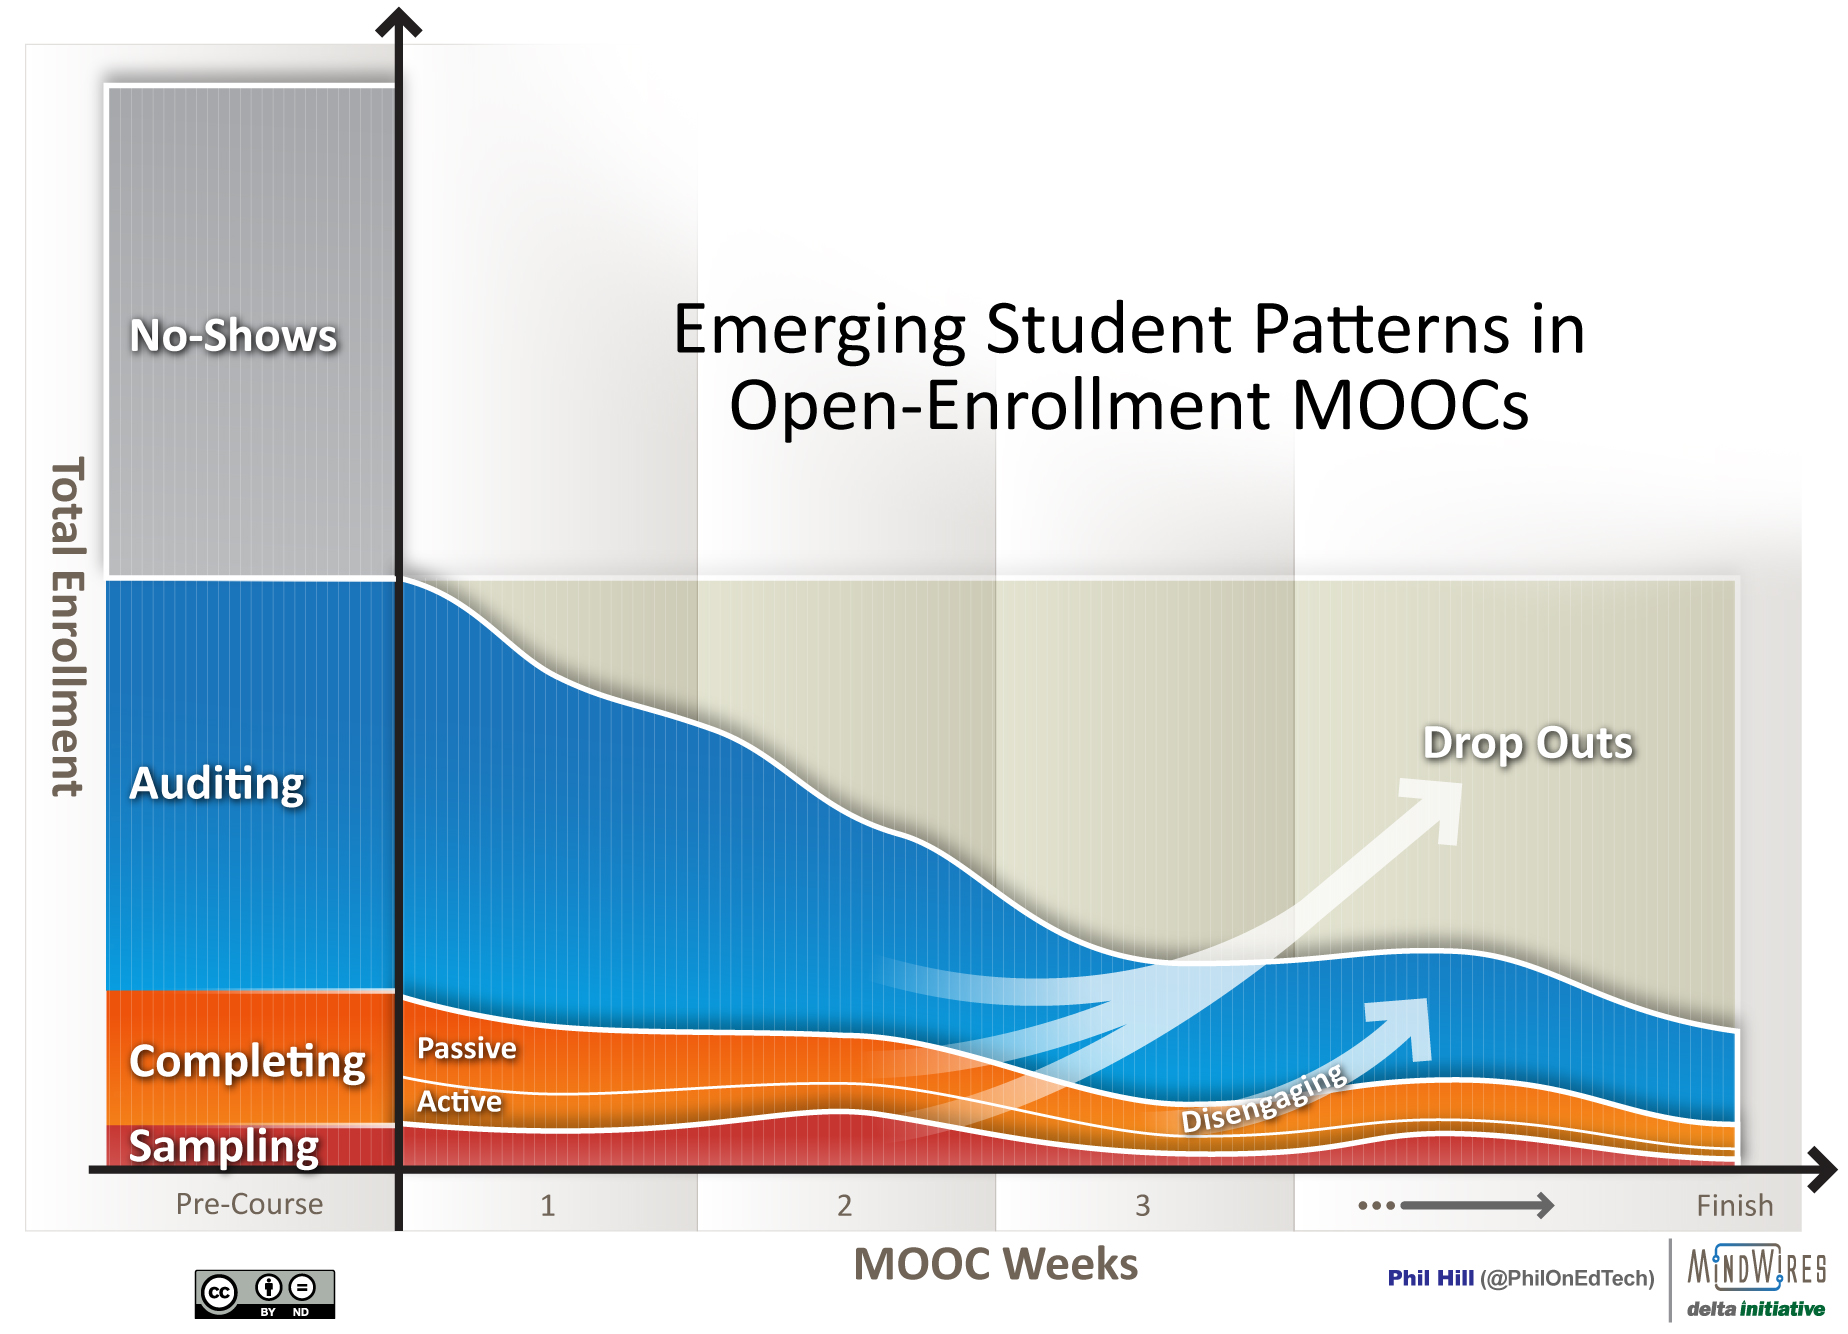
    It is no secret that the commercial Massive Open Online Courses (MOOCs) launched by Coursera, Udacity, and edX in 2011/12 are a different beast from the majority of for-credit online education offerings. One such difference is the pattern of quick drop-off of students within each course, particularly in the first 2 – 3 weeks, which we documented in 2013.

    We also know that the original disruption vision for these large MOOCs has not come to pass, with many MOOC providers moving into Online Program Management (OPM) business models and shutting off many of the free and open access that made MOOCs in the first place.

    Late last week two researchers at MIT, Justin Reich and José A. Ruipérez-Valiente, published an article in Science titled “The MOOC Pivot” that provides new multi-year insight into the trends based on edX usage at MIT and Harvard, the two founding schools for edX. In a nutshell, MOOC activity peaked in 2016 based on new individual learners, based on a dataset of “565 course iterations from 261 different courses, with a combined 12.67 million course registrations from 5.63 million learners”, leading the MOOC providers to look to the OPM market as a more-realistic method of sustainability. The researchers identify three insights from their data [emphasis added].

    To better understand the reasons for this shift, we highlight three patterns emerging from data on MOOCs provided by Harvard University and Massachusetts Institute of Technology (MIT) via the edX platform: The vast majority of MOOC learners never return after their first year, the growth in MOOC participation has been concentrated almost entirely in the world’s most affluent countries, and the bane of MOOCs—low completion rates—has not improved over 6 years.

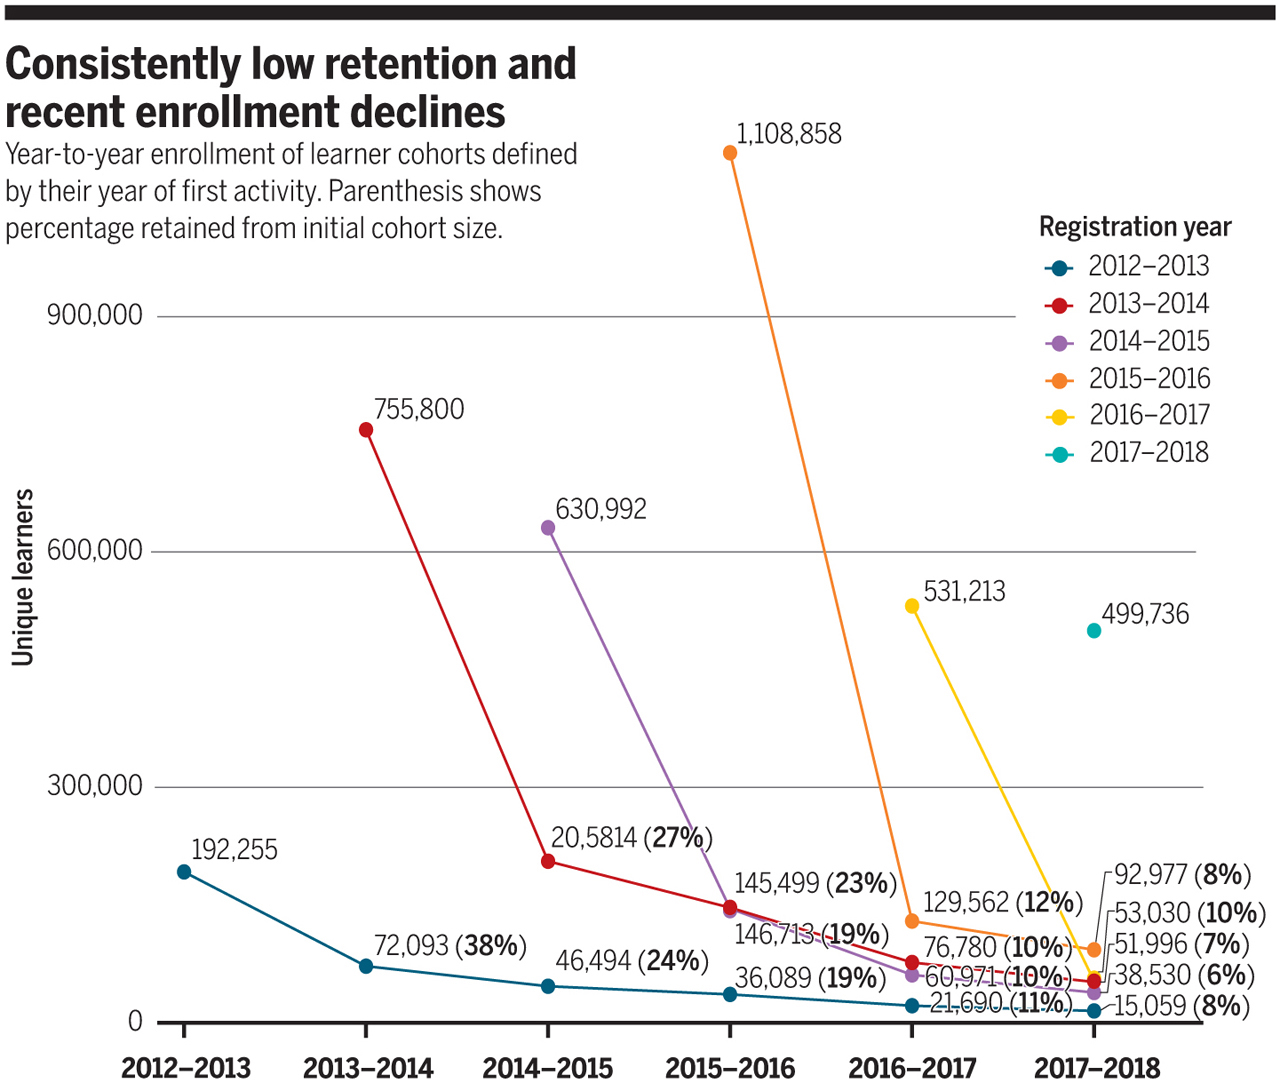
    The highlighted conclusion makes sense, but to my knowledge we have previously not had any solid data to back this point up. The following chart in the article shows annual cohorts of learners and tracks them over time, showing that the decrease per year largely mirrors the course-level situation.

    MIT Harvard multi-year research on MOOCs

    Thus 38% of 2012-13 cohort enrolled in at least one course in year 2, and 24% of 2012-13 cohort enrolled in any course in year 3, etc. Over time, these year 2 / year 3 / year 4 retention numbers reduce significantly. Thankfully, Justin and José provided a GitHub repository of the data, and perhaps a transposition of Table S1 can make these trends more obvious.

    It took nearly six years for 10% or fewer of the 2012-13 cohort to remain active (enrolled in any courses), but just two years for 2016-17. And note that the cohort size has been dropping since 2015-16. Keep in mind that the MOOC providers counteract these institution-level trends by increasing the number of institutions that they partner with over time.

    There is more analysis in the full article at Science – it’s worth reading the whole thing.

  • Grand Canyon Education Acquires Orbis: We have new segment of OPM market

    Grand Canyon Education Acquires Orbis: We have new segment of OPM market

    Nine months ago we wrote about the new movement for the companies formerly know as “for-profits” in the education space to convert the actual schools into non-profit entities and declare their intent for parent companies to become a new form of Online Program Management (OPM) providers. Kaplan University, Grand Canyon University, Ashford University (Bridgepoint Education) all made similar declarations, but the problem was that each one was a single-client OPM – serving only their supposedly independent non-profit schools. That’s not much of a new market segment.

    Today the movement became real as Grand Canyon Education announced their agreement to buy Orbis Education Services for more than $362 million.

    Grand Canyon Education, Inc. (NASDAQ: LOPE), a publicly traded shared services partner dedicated to serving colleges and universities, announced today that it has entered into a definitive agreement to acquire Orbis Education Services, LLC, an education services company that supports healthcare education programs for 17 regionally accredited universities across the United States (“Orbis Education”), for $362.5 million in cash. The transaction is expected to close during the first quarter of 2019, subject to customary closing and regulatory conditions.

    The acquisition combines the strengths of two of the nation’s most innovative service providers in higher education in an effort to align their expertise and better address a nationwide shortage in licensed healthcare professionals.

    “This is a natural extension of what Grand Canyon Education is already doing as an education services partner,” said Brian Mueller, GCE’s CEO. “We are very impressed with the quality of nursing and healthcare education that Orbis Education’s client institutions are providing. GCE can help grow that by providing investment capital and advanced technologies with behind-the-scenes support that will help University partners accomplish their goals and increase the number of licensed healthcare professionals they educate with the same high-quality outcomes.

    While they use the phrase “education services partner” instead of OPM, Grand Canyon in one move became a competitive provider worth watching. This news is significant.

    The large for-profit chains all developed scalable processes for the same functions that OPM vendors provide for non-profit schools – marketing & recruitment, course & curriculum development, technology platform & data analysis, and student support & retention services – and the basic idea of this market change is for the for-profit parent companies to provide these same services for other non-profit schools. With the Orbis acquisition, Grand Canyon will pick up 17 partner institutions.

    Orbis Education is a niche-market full-service OPM provider serving pre-licensure healthcare programs (mostly nursing) and was founded in 2003. Parter institutions include Concordia University, Northeastern University, Marquette University and Mercer University.

    In a broader sense, this acquisition follows the Wiley acquisition of Learning House for $200 million announced this fall. We’ll need to update our graphics, but the OPM market is profitable and growing, but it is also messy and chaotic. OPM vendors are in a battle to have the financial strength and customer scale to survive the chaos and grow in an expensive model.

    For those keeping track, Pearson paid $650 million for EmbanetCompass in 2012, and Wiley paid $220 million for Deltak, also in 2012. Hmm, something about that year . . .

    We’ll follow this story and others like it while sharing information on the likely impacts on the overall OPM market. For now the biggest issue is establishing that this for-profit-turned-OPM segment is real.

  • Coursera CEO Interview: Betting on OPM market and shift to low-cost masters degrees

    Coursera CEO Interview: Betting on OPM market and shift to low-cost masters degrees

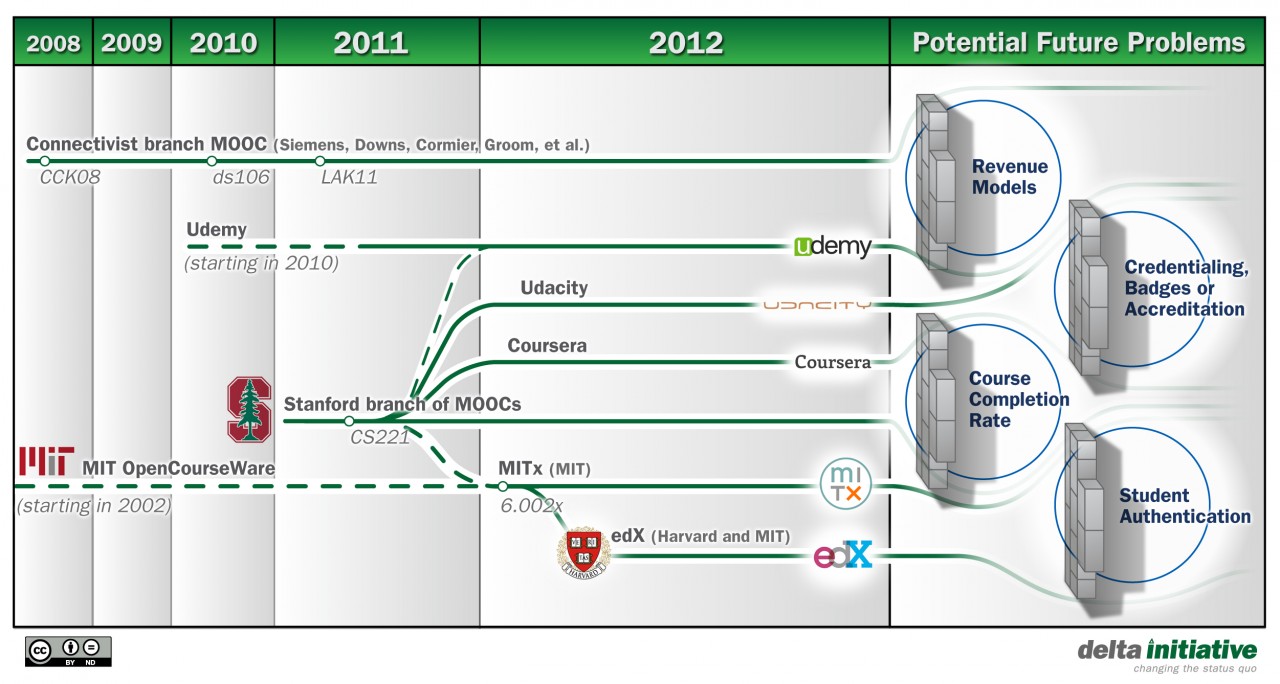
    In mid 2012 during the midst of MOOC mania, I wrote a post noting that we should pay attention to future generations of the concept and that there were four barriers that the MOOC vendors would have to overcome to have any long-lasting impact.

    Given this short timeline and the nature of investment-backed educational experiments, I think the real focus should be on whether and how MOOCs or successor models build on current scalability and openness while overcoming these four barriers.

    Six years later, it is becoming increasingly clear that the next-generation model for MOOCs in higher education is to become a form of Online Program Management (OPM) providers, including the near-term focus on master’s degrees. The OPM market has demonstrated revenue models (tuition revenue sharing mixed with fee-for-service), the end credential is the already-accepted degree, course completion rates are higher for paying and matriculated students, and degree programs have methods for student authentication. In other words, the MOOC-based OPM model is the next-generation designed to address these challenges.

    The shift into the OPM market has been documented in a series of posts in July of 2017, March, April, and May of 2018; and from Dhawal Shah from Class Central . In the May e-Literate post:

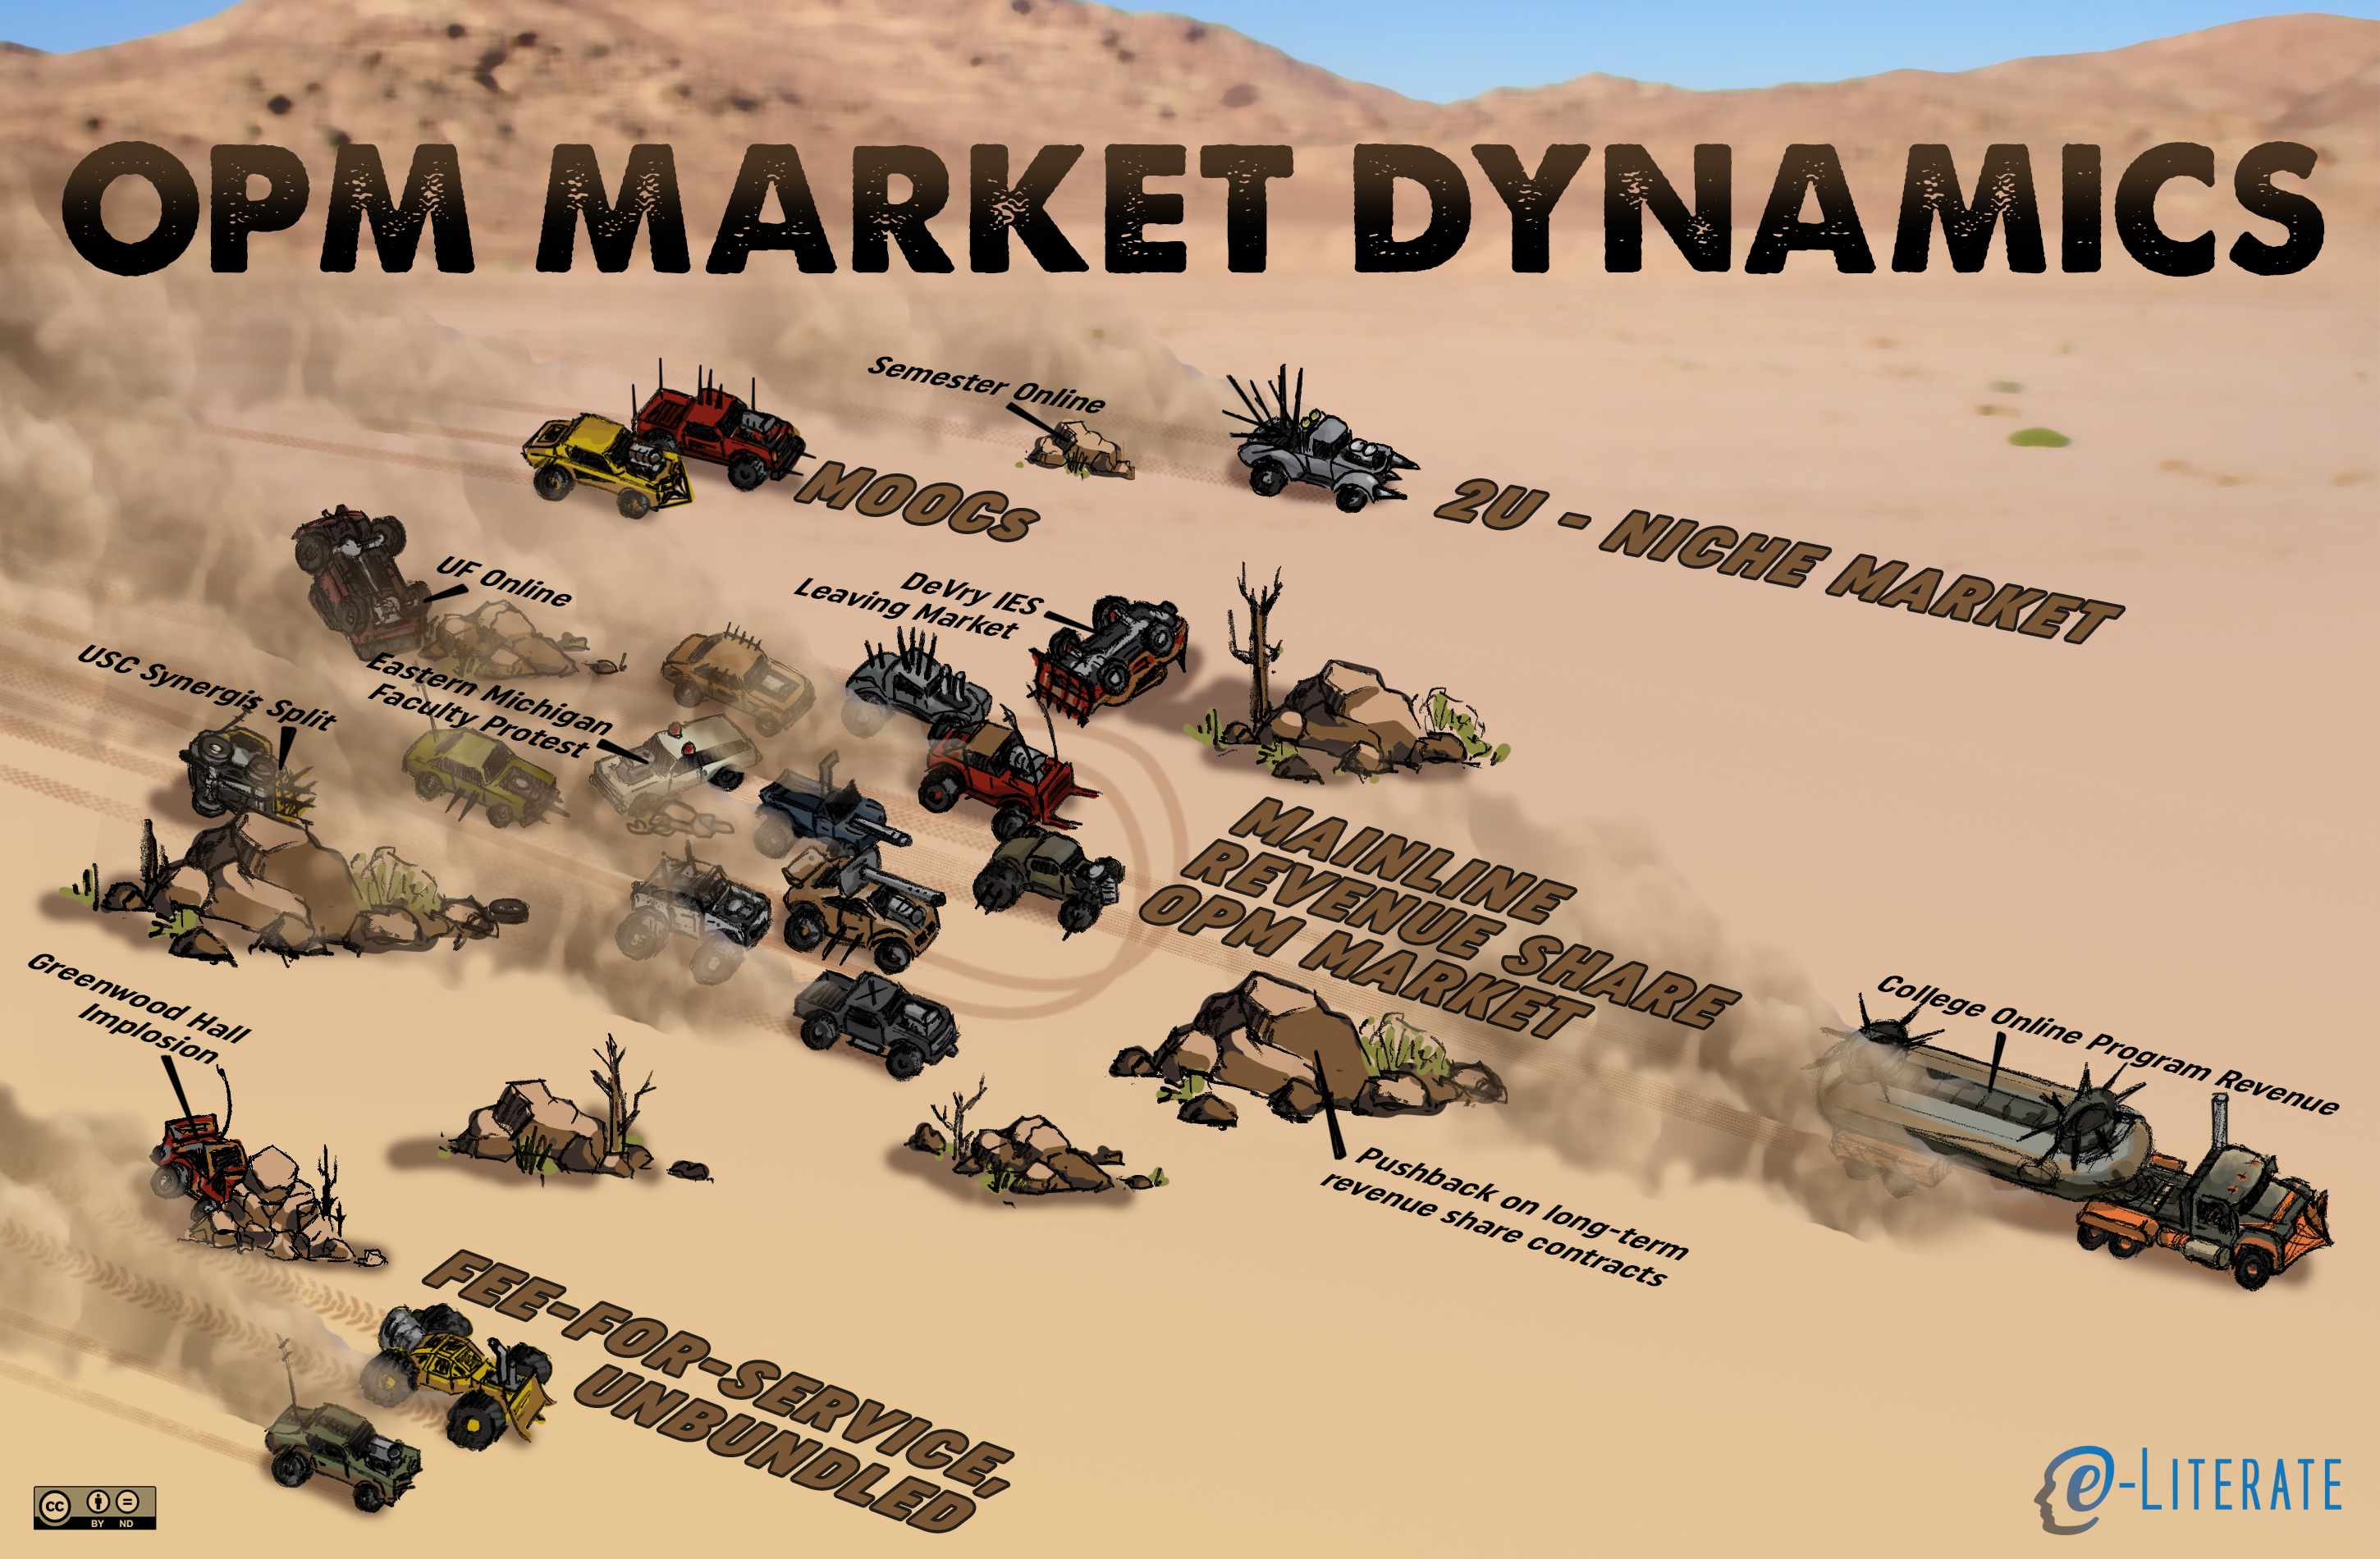
    The picture one gets is of a chaotic market that is not for the faint of heart, and one that will likely see further consolidations and category changes. 2U, for its part, has been successful partially due to a niche strategy where they go after elite master’s programs and mostly avoid direct competition or engagement with the rest of the market. And recently we have started to see the MOOC providers become OPM providers – where the primary revenue for Coursera and FutureLearn are based on revenue sharing with online programs, albeit with lower sharing rates and with very different marketing approaches. In other words, there seems to be several efforts to enter into the same OPM race, but if possible to avoid being in the mainline rev-share OPM market.

    Last week Julia Stiglitz from GSV Advisors, in their first podcast episode, interviewed Coursera CEO Jeff Maggioncalda who joined the company summer 2017. This interview gives the clearest view yet of Coursera’s emerging business model, and by extension it helps explain the new subset of MOOC-based OPM that includes FutureLearn, edX, and Udacity as vendors. ((Outside of Georgia Tech legacy contract, Udacity has moved to corporate professional development market, which is a different approach to same problem.)) I think that the media narrative of tuition revenue-sharing vs. fee-for-service OPM models is overblown, especially since there is a spectrum in that respect more than a binary choice of OPM vendor types. What the MOOC-based OPM entry introduces is a more fundamental characteristic of how traditional institutions develop online programs – namely low-cost vs. full-cost online degrees.

    The first note from the interview is that the Coursera of 2018 is not the Coursera of 2012. While Maggioncalda still shows aspects of that old-time MOOC belief system, his approaches are very much rooted in focusing Coursera on a solid business model. And the difference shows. The second note is that 2U’s success in the OPM market and a successful IPO had a big influence on Coursera’s shift. [Emphasis added in transcript]

    Julia: You know when you first joined. You spent some time looking at Coursera’s strategy, and really digging in and looking at the different businesses that Coursera had, and one of them that you were particularly attracted to, and you have put increased attention on here at Coursera is the online degrees business. What was it about online degrees that excited you?

    Jeff: Yeah. This is sort of I think another good example of what good entrepreneurs have to do, is you have to have feedback loops; you need to get information from multiple sources to understand the nature of a problem so that you can come up with solution. The nature of an opportunity so you can develop a strategy to go after it. It’s really actually pretty simple. I came in – you were on the team, too, we did a lot. We call them deep dives. We went all through the business model, and there’s a great book Business Model Generation that really, to me, gives a nice framework for saying this is what a business model is. It is a target customer. It is a value proposition and offering that solves their needs. It’s a set of channels of how you acquire those customers. It’s a servicing models of how you service the models. Internally it’s the key activities and resources you bring to bear on that. It’s the partners that you work with. It’s the financial revenues and costs, and is your competition. So and that’s the framework. And we stepped through every one of those. I wrote 250 questions across that business model that we as an executive team went through. You know step by step by step, so that everybody learned the nature of our business. And what became very obvious is we had a few things that nobody else really has.

    We had 36 million learners, at the time it was 25 million. 25 million learners from all around the world. That’s a pretty big asset. We had university partners. Now there are competitors out there like LinkedIn Learning, previously Lynda, like PluralSight, like SkillSoft. You know there’s YouTube, there’s Khan Academy – there’s a lot of content out there. You were one of the ones who told me in one of those early meetings, “Hey we’re worried that content, generic content, might become a commodity.” Well, we don’t want to play a commodity game. So what is it about my partners that’s super distinctive? Well our partners are universities, and they’re not just the universities, they’re the best universities in the world, and they’re spread around the world. So you say, well I’ve got a resource that almost no one has, which is this network of universities. Right now they’re publishing MOOCs, and there’s something special about MOOCS, but MOOCs are a little more susceptible to that commoditization just as MOOCs. But what was not very susceptible to commoditization are degrees. So that’s OK. We have an asset nobody else has, and what they do really well is degrees, and they still have market sizing. How big is the market for degrees? 1.5 trillion dollars. Okay, well that’s a pretty big opportunity. And then you say, what’s the likelihood that that industry could be transformed due to technology . . . You know, some industries it’s easier to transform, others, it’s harder. The provision of education is absolutely set up nicely to be enhanced, transformed by technology.

    I think Uber and Lyft were really smart when they said “you know on-demand transportation, called a taxi, it’s a big market, but it’s a broken product. And if we just do some sort of digital view of this kind of redesign what on-demand transportation looks like, it’ll be a much bigger market.” I’m looking at degrees, I’m not saying it’s broken altogether, but if you look at the student debt out there, you look at the the lack of access, and you look at how inconvenient it is for people to have to stop their lives – especially for master’s degrees – quit their job, move their family, pay hundreds of thousands of dollars, forfeit their income. That’s a broken product. So I thought we got partners who are really good, and a massive economic opportunity, and a product that is just ready to be dramatically improved by technology, and so I thought this is pretty good. We should go after this. By the way we also had 2U trading at like a 12 times forward multiple. So clearly Wall Street loved the idea of online degrees, and 2U’s been doing great. They’re growing really rapidly, so there’s a data point out that says, hey this company is doing really, really well; We should be able to do pretty well here, too.

    Julia: Could you share a little bit about what this redesign looks like? Because the online degrees aren’t new. You know 2U is doing them. And before 2U there were a whole set of online degree providers that were out there, so why is what Coursera is doing different?

    Jeff: Yeah I think it’s a few things. The number one, I would say, is quality. When I say quality, I mean the quality of the credential. So a lot of people have spent a lot of money on for-profit college degrees that just don’t have very good credential value, they’re not recognized in the job market. You pay a lot of money, you don’t get much back for it. One of the reasons that people pay so much for the top universities is that those types of degrees means something in the job market. There have been a lot of online degrees out there, from universities, that charge a lot and don’t get you very far. Our partners happen to be the best universities in the world, with the highest credential value in the world. When these degrees come online, and these degrees online are the same degrees as on campus, you’re getting something as a credential that’s extremely valuable. That should have a very high ROI. Because we’re doing it online the cost is often less than half. So it’s a top quality credential at half the price. Same credential you get on campus.

    Different Assumptions on Tuition

    There’s a lot of useful insight in the full interview, but I’d like to call out the fundamental question that gets raised about online education with this market view. Should online degrees from traditional universities cost the same as face-to-face offerings, or should they cost significantly less?

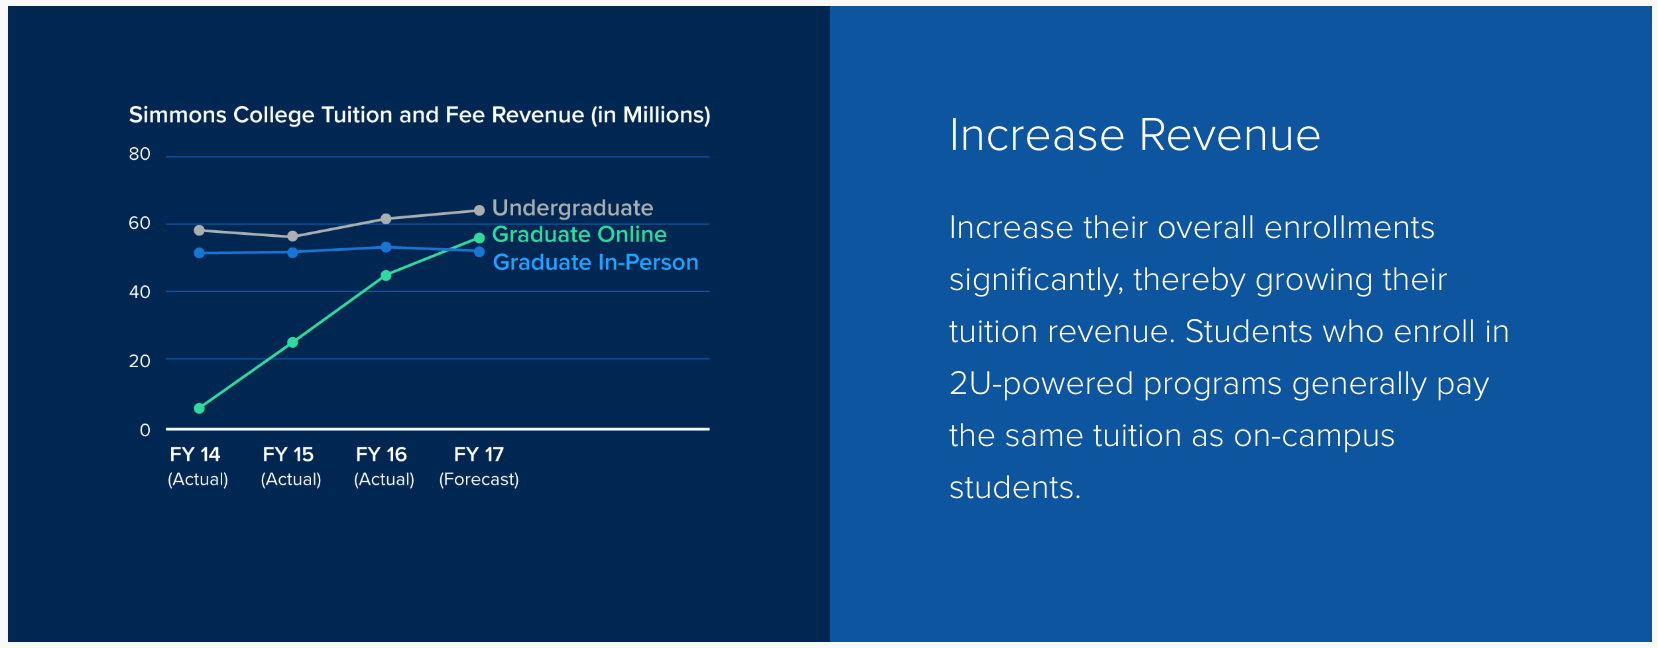
    For full-service revenue-sharing segment of the OPM market, some core assumptions are built on the assumption of high revenue share percentages and full-priced online degrees. 2U is probably the best-known and arguably the most successful OPM company, and like Coursera they target elite institutions as partners. In 2U’s website under “Our Approach” they describe how their online programs typically charge the same as on-campus programs.

    2U's approach for tuition - the same for online as for face-to-face

    Most of the full-service revenue-sharing segment of the OPM market is similar in its view, whether from Pearson, Wiley, Academic Partnerships, or others – relying on consistent tuition as for online programs, and if there are lower prices they tend to be marginally lower. ((Disclosure: 2U and Pearson are sponsoring participants in our Empirical Educator Project.)) The Coursera approach is in direct contrast with this view, based on the interview as well as several of their online degree programs. There are arguments for either approach. With full-cost tuition, the idea is that the online degree gives at least as much value to students as the face-to-face, or on-campus, degree, and therefore students will be willing to pay the same. With low-cost tuition, the idea is that while students get the same value, “because we’re doing it online” the costs should necessarily be lower. Online infrastructure and marginal costs are much lower than investment in physical facilities. The point here is that this is a fundamentally different set of assumptions.

    Writing about the Illinois $22,000 iMBA program, Marc Ethier described this different approach to pricing:

    For most, the initial appeal of the program was certainly the price tag. Illinois’ iMBA costs a fraction of a degree from an elite school, where the median cost is roughly $171,000 and can break the $200,000 mark at the far end of the scale. Illinois’ own residential two-year MBA costs more than $100,000. Arshad Saiyed, executive director of online programs at the Gies College, acknowledges that the low cost brought the program to many prospective students’ attention — but says the iMBA has kept students around through a combination of high-quality instruction and successful community building.

    Different Assumptions on Student Recruiting

    For OPM full-service vendors, the largest expense is typically marketing and sales – i.e. recruiting potential qualified students. The predominant approach to OPM student recruitment has been based on digital marketing – advertising and outreach on social media platforms, search engine placement, digital advertisements in articles. With the MOOC-based OPM subset of the market, there is now an alternative approach based on having a multi-sided platform model. Coursera views their 36 million registered learners as an asset – a natural base of potential students for online degrees that can be reached without external advertising. In addition, the original aim and design of large-scale MOOCs is based on ability to easily sign up new learners for low- or no-cost, with the opportunity to move these students into higher-cost credentials and degrees over time, not requiring full financial commitments from students up front. While a Coursera or FutureLearn might use digital marketing for recruitment, that is not their primary method.

    Different Assumptions on Course Size

    Related to the above assumptions, in 2U’s case the class size is small – typically 10 – 20 students leveraging the platform’s design around small discussion groups, using both synchronous and asynchronous learning. This 2018 article about Washington University’s two programs partnering with 2U partially describes this approach.

    But what is it like for student to pursue a graduate degree in law fully online? How could a pre-recorded lecture support the active teaching that’s integral to discipline? After all, watching a video isn’t the same as participating in a conversation. To support such engagement, 2U created a new tool.

    “Through building an online LLM [master’s of law] program with Washington University in St. Louis, we learned how to design one of the most important tools we provide today: the bidirectional learning tool, or BLT,” said Chip Paucek, co-founder and CEO of 2U. “Socratic-style teaching is fundamental to all law curriculum and coursework. As such, it was imperative for us to design a way to conduct Socratic-style group discussions for Wash U once we signed their online LLM program.

    “What we didn’t realize is that while we were developing a software tool to help solve the challenge of teaching the Socratic method online, we were simultaneously creating a way to facilitate discussion-based learning in an asynchronous environment that would eventually be used in all of our future partner programs.”

    The approach that 2U and Wash U Law conceived relies upon the ingenious integration of asynchronous and synchronous course components. Instead of lecturing from a podium, faculty address small groups of student actors. At key points, the instructor breaks the fourth wall and addresses the online student, who is prompted to answer without the benefit of knowing how his or her peers have responded. In other words, students can’t piggyback like they might in an in-person class.

    After responding, online students can review one another’s answers. They might be prompted to answer follow-up questions, or they might be asked to come to the next live class prepared to defend whatever position they’ve chosen. The preparatory work that might otherwise happen during an in-person class is accomplished in advance through the pre-recorded sessions, enabling faculty to make better use of live, synchronous time.

    In contrast, consider a Class Central interview with Maggioncalda when talking about scaling and its challenges.

    I think about systems. As the system gets bigger, where would the bottlenecks emerge? My sense is that the bottlenecks will emerge in live sessions and in grading. That’s my guess. The grading, I’m actually not so concerned about because I think the ability to automate grading at scale will become pretty good. The live sessions get tricky. From a technology perspective, I’m not that worried about it. It’s the professor’s time and attention. My thought is it’s going to be a little bit like pyramid, where the number of hours that the main professor puts in won’t really change. If you think about how medical systems have worked, a doctor is in the system, but the number of minutes and hours that a doctor spends [with each patient] becomes an increasingly smaller portion of the total time [during which medical treatment is being delivered]. I think it will probably be somewhat similar for education. The size of the classes could be big, let’s say 10,000. But that will be broken into sections of say 50. And each of those sections has an expert who’s probably not the professor. Also, there will be a lot more collaborative learning among the peers in the class. If you think about it, a lot of learning does actually happen among the folks in a class. The expert just dispensing wisdom is not the way most learning happens. I call it “high engagement learning at scale.” A major piece of high engagement learning at scale is utilizing your classmates to provide a highly valuable learning experience.

    Coursera is pursuing a path to enable high enrollments in low-cost programs, and they view their challenge to balance scale and student engagement, with class sections of ~50 students.

    Good Enough vs. Better Enough

    In two posts recently, Michael described a battle in the digital curricular materials market. Focusing on Cengage Unlimited in the first one, he described this dynamic.

    Make no mistake; this is a potential inflection point in the curricular materials market. There is a war raging between curricular materials that are “good enough,” meaning that the lower price has a bigger impact on student outcomes than any differences in the quality of more expensive alternatives, versus “better enough,” meaning both instructors and students believe the product makes a sufficient difference in student outcomes that the more expensive product is worth the premium. Cengage is betting the farm on “good enough” beating out “better enough” and, win or lose, their bet could cause tectonic shifts in how curricular materials are developed, purchased, and used. It will have implications for inclusive access, adaptive courseware, textbook companies, textbook authors, and the landscape of options available to students and teachers.

    Elaborating in the second post:

    The distinction I’m trying to make between two strategies is a little tricky. I’m not arguing that Cengage, for example, thinks that their products aren’t great or that they think all anybody needs is the cheapest PDF possible. And on the other hand, “better enough” no longer means better editing or better production values, which is the way that textbook publishers used to position themselves against OER (and still do sometimes, although that reflex is beginning to fade). Rather, it’s about improving student outcomes.

    What we are seeing in the OPM market, with the introduction of MOOC-based degrees, is a new battle. MOOC providers and its partner institutions, represented by Coursera, betting on “good enough”; and 2U and its partners betting on “better enough”. Like the curricular materials market, the product is based on student outcomes, which wraps in the value of the credential coming from the university along with the academic and administrative experience enabled by the company. Coursera obviously believes in the quality of their experience, and their partners have some programs that are not deeply discounted, but their market position is based on the program price being the compelling feature for students, including free or low-cost on-ramps. 2U understands that students are seeking more cost effective options, which was one driver behind creating the short-course segment with the acquisition of GetSmarter, but their market position is based on quality of experience and value of credential being the compelling feature for students. But the difference in approaches is stark and significant.

    While there is likely room in the market for both approaches, the Coursera of 2018 (and not the Coursera of 2012) deserves careful observation to understand future trends with online degrees. Win or lose, their bet on low-cost online degrees will have big implications in the market.

  • Extension Engine and OPM Market Transparency

    A couple of weeks ago, our response to Open SUNY’s Request for Information (RFI) on Online Program Management services (OPMs), we published an abridged version of our response on our company website and wrote a post about our observations here on e-Literate. Since, then, ExtensionEngine has followed suit. Here’s the introduction to the version that they published on their site:

    The online program management (OPM) landscape is a confusing one, the result of rapid evolution and an ever-greater assortment of businesses keen on winning their share of what has become a very lucrative market. We do not envy the task of any institution of higher learning seeking to upgrade their online learning program, and even less one considering the launch of their first program.

    A few days ago, MindWires — a strategic consultancy and advisory firm — took an unusual step, one that begins to make the task a little easier by increasing transparency among all of these diverse providers: they published their response to a request for information (RFI) from the State University of New York (SUNY).

    The action reflects — and begins to correct — concerns expressed by MindWires’ Michael Feldstein in a series of articles regarding the complicated 2018 OPM market. Greater transparency, as modeled by this move, may be exactly what the marketplace needs to make sense of itself.

    In fact, the SUNY RFI itself has made a contribution to greater clarity. This RFI was more than a request for information on what various providers could do for them; rather, it asked the question: What do we need to know before we move forward? Asking for this guidance before generating a request for proposal, or RFP (which will come later), was a brilliant and insightful move on SUNY’s part.

    The SUNY RFI listed 15 information-gathering objectives. As we formulated our own response, we noticed that we were, in effect, creating a road map through the wilderness of the 2018 OPM market, one that could be valuable to many institutions of higher learning that are thinking of creating or upgrading an online learning program. Some sections are more pertinent to multicampus systems like SUNY’s, but much of the road map applies to any institution, regardless of size.

    For those who are not familiar with ExtensionEngine, we are a professional services organization that designs, builds, launches, and markets custom learning experiences — an integrated, holistic experience designed for learners, pedagogy, vision, and brand. We are a fee-for-service partner — no revenue sharing — and are paid by the hour to provide a full suite of services to help our clients to create successful online learning.

    So, in the spirit of transparency inspired by MindWires’ publication of their response, we are following suit to share portions our response to SUNY’s RFI. Below is a substantial excerpt from the road map through the OPM landscapewe created for SUNY, shared with their permission.

    This is great stuff. In mature product categories like the LMS, this kind of sharing can do more harm than good, because schools tend to just copy and paste requirements without giving a lot of thought about or investigation into which requirements are right for their particular context. But in the still-maturing OPM and broader Digital Enablement Solutions product categories, this kind of sharing helps to surface the differences in needs and contexts that lead to different kinds of optimal solutions. Publishing both the requests and, at least, abridged versions of the responses is very helpful in advancing the conversation. As ExtensionEngine’s Scott Moore noted in the blog post, such responses can “creat[e] a road map through the wilderness of the…OPM market.”

    More transparency in this space would be extremely helpful at this time. We’re giving some thought into different ways to accomplish that aim.

    Stay tuned.