e-Literate

Present is Prologue

Tag: OPM

  • Expansion of OPM-Derivative Model: Disney covers online degrees for hourly employees through Guild Education

    Expansion of OPM-Derivative Model: Disney covers online degrees for hourly employees through Guild Education

    Two weeks ago The Walt Disney Company announced a new educational benefit program called Disney Aspire that goes beyond what other recent benefit programs have offered. As described in a company blog [emphasis added]:

    Disney Aspire is the most comprehensive program of its kind. To make participation easier for eligible employees, The Walt Disney Company will cover 100 percent of tuition upfront and will also reimburse application fees and required books and materials, removing the worry of paying to start or continue school. The program is designed for working adults and offers our Cast Members and employees maximum choice and flexibility with their studies, regardless of whether the program and classes they choose are tied to their current role at Disney. Disney Aspire includes a network of schools that offer a wide array of disciplines and diplomas—including college and master’s degrees, high school equivalency, English-language learning, vocational training and more.

    This program is offered through Guild Education to 80,000 of Disney’s hourly employees in the US (after 90 days of employment), and the ‘regardless’ point is crucial – the options for degrees is not constrained to pre-selected majors or degrees that have to be tied to an employee’s current role.
    Yesterday there were additional details announced by the University of Florida Online (UF Online) about programs that they are offering for Disney Aspire.

    As part of this relationship, Disney employees may apply to one of several fully online bachelor’s degrees – the Bachelor of Arts or Bachelor of Science in business administration from the Warrington College of Business; the Bachelor of Science in sport management from the College of Health and Human Performance; and the Bachelor of Arts in public relations, and the Bachelor of Science in telecommunication from the College of Journalism and Communications. If granted admission by the University of Florida, Disney cast members could begin UF Online classes in January 2019 as part of the University’s spring semester. Once cast members sign up for the Disney Aspire educational benefit, a coach from Guild Education will contact them to determine their eligibility to receive educational benefits, review their academic background, and to provide qualified prospective students with a unique link to the UF Online admissions application.

    One reason this announcement is interesting is the rapid growth of Guild Education, providing a derivative of Online Program Management (OPM) services. Guild describes itself as providing a platform that connects large-employer educational benefit programs with partner schools such as UF Online, Brandman University, Valencia College, etc. As we described in June when Walmart and Discover Financial announced their benefit programs:

    I think these moves are more significant than just individual benefits. What we are seeing is UF Online, along with a handful of others, defining a different approach to marketing and finding potential online students, at least for undergraduate degrees. Historically, there is a common assumption that to enable a scalable online program there is a need for traditional digital marketing as the primary approach – Google AdWords, call centers, social media campaigns – with a partnership or two thrown in on the side. The origin of the OPM market is centered on providing these services in exchange for a percentage of tuition revenue, and for the majority of cases, the OPM’s spending on this marketing and enrollment management category is the most expensive service in the package. The Employer Pathways approach by UF Online has the potential to flip the student acquisition assumptions – primarily driven by employer partnerships with traditional digital marketing channels as a secondary approach.

    Since the June post, Guild Education raised a round of $40 million for a total of $71.5 million since 2015. As EdSurge noted in its article, however:

    One challenge is that few employees who are given education benefits options take advantage of them. The Wall Street Journal recently reported that while nearly 90 percent of mid- and large-size companies offer tuition reimbursement, less than 10 percent of employees at those companies take advantage of the benefits.

    That figure is even lower at Guild’s partner companies, where only 3 to 5 percent of employees take advantage of the educational offerings, says Carlson. “We are optimistic that our companies want to go beyond that.”

    Guild Education works on a tuition revenue share basis, although the details of these agreements are not public information yet. Charging tuition revenue sharing for up-front marketing and acquisition of students for online programs – sounds like a lot of overlap with the OPM market, but for a new or derivative model. This gets to Michael’s point most recently described in a post about Noodle Partners and their evolving model:

    In my last two posts, I talked about OPMs being long-term partners in the ongoing management of online programs. I also argued that unbundling of services opens up a world of possibilities for solving different problems, and that we therefore need an umbrella product category called “Digital Enablement Solutions” with other (emerging) subcategories that could live along side Online Program Management.

    Guild Education does not provide any of the program management services beyond admissions, as they do not help with program design, instructional design, student support, ed tech platforms or analytics. So it would be a mistake to lump them into the OPM category, but there are some interesting overlaps. We referenced this situation in our response to the SUNY Online Education Request for Information.

    Financing models are proliferating in higher education, to the point of creating a great deal of market confusion, in part because one size does not fit all. Universities will likely have to evaluate a wide range of financial models and make sure that their approved portfolio of solutions providers includes a substantial subset of those models.

    As for the educational partners, there is long-term potential but not yet sufficient demand for that flip in student acquisition assumptions. UF Online estimates that within the next two years they might reach 10% of students coming from their Employer Pathways. One motivation for this type of program, according to Associate Provost and Director of UF Online Evie Cummings, is that ideally the  “coach from Guild” will be able to pre-screen applicants, since the cost of marketing to students who do not make it through the admissions process is quite expensive for selective institutions.

    Beyond the online programs, starting in January there are likely to be face-to-face options as well, as described in the Orlando Sentinel.

    Under the education program, Disney employees can take courses toward a high school diploma, a college degree or vocational skill.

    A Disney spokeswoman said the online courses are the first rollout of the tuition program and employees would be eligible for in-person classes — at Valencia College as well as other schools — in the next phase beginning in January.

    Count this news as further evidence of the broader market of Digital Enablement Solutions based on tapping into corporate HR and learning opportunities rather than traditional ad-based student recruitment methods.

  • Noodle Partners and the Boundary of the OPM Product Category

    If you spend some time browsing the Google News search results for ‘OPM “revenue share”‘, you’ll find one industry figure who seems nearly ubiquitous, particularly in pieces by general audience news outlets: John Katzman. Mr. Katzman, currently the founding CEO of OPM company Noodle Partners, is one of those rare individuals who has been extremely successful as a serial entrepreneur in education. He founded both Princeton Review and 2U before going on to start Noodle. In his current incarnation as Noodle Partners CEO, Katzman is waging a publicity war against the OPM revenue share model that companies like his last one—2U—are built on. Josh Kim’s recent interview with him in Inside Higher Ed is quite revealing and tells us a lot about the real debate surrounding OPM revenue sharing.

    Josh starts the interview by quoting a two-year-old opinion piece Katzman wrote for the Hechinger Report:

    In three years, no one will be able to explain why it was that colleges and universities continued to hand more than half of their tuition to companies marketing and supporting their online programs — the online program managers. It will be even more challenging to explain why some agreed to contractually share their tuition for the next 10 or 15 years.

    In that same piece, Katzman referred to traditional OPM revenue sharing agreements as “payday loans” and wrote,

    I’m suggesting the time for the ‘share the bounty’ approach to online education is over. This approach is driving up education costs (and student debt) and fueling a marketing race as schools and online program managers spend more and more to recruit and retain online students.

    That online program managers continue to sell their outdated and misaligned tuition-sharing model fuels the suspicion and mistrust educators have for for-profit education companies.  Those of us who believe for-profit investment and innovation can improve the quality and accessibility of education are obligated to raise our voices when things go off the rails or become ineffective or outdated – as the revenue sharing model has….

    Few, if any, institutions can afford to share their tuition and none can afford the all-out marketing war that outside companies will be all too happy to wage for a cut of the action.

    The good news is that the market knows a change is coming. Tuition-sharing percentages are trending down and contracts are getting shorter. More colleges are investing in in-house solutions to recruit and manage their online offerings. And fee-for-service management options like the one my company offers are also becoming more abundant. That’s progress.

    Pretty harsh words, especially from a guy who founded one of the most successful OPMs in the industry. Has Katzman softened his stance in the last two years?

    Nope.

    Here’s what he says in response to Josh’s question about whether the OPM industry should form an association:

    My job is to decimate the OPM industry, which is driving up higher ed tuition. So … perhaps, but doubt they’d want me in it.

    Clearly, Katzman is on a mission to kill revenue sharing agreements. Here’s what he says in response to Josh’s question about how universities can manage the up-front costs of building an online program without revenue-sharing agreements:

    Some traditional OPMs are trying to position us as fee for service, but Noodle also offers a temporary revenue-share option in which we fund a program and take on all risk. The school pays a share of revenue, but only until we have recouped our out-of-pocket expenses for its programs, after which it pays for actual services. This is the best of both worlds, and about half our schools take advantage of it.

    Wait. What?

    Noodle Partners’ position gets flattened into “revenue sharing bad,” partly because it makes good headlines, partly because Mr. Katzman knows it makes good headlines, and partly because Noodle Partners’ position has evolved. According to the Wayback Machine, Noodle Partners’ 2016 version of their web site said the following about financing:

    Choosing to work with Noodle Partners is the most affordable route to great, quality online programming. While there is an up-front investment necessary to launch your programming, Noodle Partners can work with you to get outside capital from a trusted, low-interest financing partner.

    In the IHE interview—and on the 2018 Noodle Partners web site—the positioning regarding revenue sharing is more nuanced.

    But if revenue sharing isn’t the core problem that Noodle Partners is intended to rectify (anymore?), then what is? Is it the bundling? Here’s what Mr. Katzman says to Josh on that point:

    [U]nbundling isn’t exactly what we’re doing. A program needs instructional design, marketing, recruiting, funding, technology and support services; we’re just comfortable with helping a school build capacity rather than use outside providers exclusively. Any way our competitors follow us, though, they will leave Noodle as the leader in the next-generation OPM space.

    In my last two posts, I talked about OPMs being long-term partners in the ongoing management of online programs. I also argued that unbundling of services opens up a world of possibilities for solving different problems, and that we therefore need an umbrella product category called “Digital Enablement Solutions” with other (emerging) subcategories that could live along side Online Program Management. Noodle Partners isn’t unbundling services but is rejecting the model of the long-term full-service management of online programs by the company.

    So what does that make them?

    I would call the service that Katzman describes “Online Program Enablement (OPE).” In this model, the vendor may offer revenue sharing or some other form of financing designed to cover the up-front costs of full-service support for the program launch, but then unbundles those services to some extent and allows customers to pay for them as needed on a fee-for-service basis. That shift in models after the program launch is what distinguishes an OPE from an OPM.

    Katzman characterizes the shift as “next-generation OPM,” but the resulting service really solves a different problem than an OPM does. If you think your institution is best served by focusing on its current core competencies and outsourcing the lion’s share of online program management work to a specialist on an ongoing basis, then an OPM service is what you want. If, on the other hand, you want full-service support (and financing) to launch your program but want to take over management of significant portions of it once it is up and running, then an OPE service is really what you want.

    How much OPM and OPE services are ultimately going to compete or just co-exist is an open question. At the moment, we don’t see a lot of evidence that OPE growth is coming at the expense of OPM growth. There is likely a Venn diagram of potential customers between the two product categories, but we won’t know the size of the overlap for a while. In fact, we have very little visibility into OPE growth, in part because many service providers are offering multiple pricing options these days. There’s still a lot of improvisation going on without a lot of thought about how tinkering with the pricing model changes the offering enough to put it into a different product category.

    The main point, once again, is that many significantly different offerings are getting crammed into the OPM product category because it’s the only product category that we have. This obscures the fact that some of these services are different enough from each other that they solve different problems from each other. And the differences that tip an offering into a different product category are not always obvious.

  • The Boundaries OPM and What Lies Beyond: The SUNY Example

    In my previous post on OPMs, I wrote,

    There are several factors that are major contributors to the current rush to by vendors to call themselves OPMs:

    1. The variation between kinds of programs that universities are looking to launch is significant and increasing. As a result, different OPM vendors are specializing in different kinds of programs.
    2. More universities are making fine-grained choices about which aspects of their online programs they want to outsource to a specialist, which aspects they want to pay a consultant to help them get started or improve, and which aspects they believe they can do themselves. This broadening out of customer choices is creating further variability in in OPM business models and OPM-like services offered by an increasingly wide range of companies.
    3. As the OPM business disaggregates, universities are increasingly recognizing that certain functions that OPMs perform, like recruiting students who are likely to be successful in a program, redesigning courses to maximize student success, providing early interventions to promote student success, and working with employers to help with career readiness and post-degree employment are all services that might be useful for improving the success of their traditional programs.

    This last point is especially important. Within the three-letter acronym OPM, the “P” and the “M”—”program” and “management”—are defining features of the product category. OPM is a service in which the vendor actively manages at least some substantial subset of a full online program  for some significant period of time. As in multiple years. Once customers start contracting for individual services a la carte on a relatively short-term basis—say, just to get the program up and running—those customers are no longer paying for an OPM service. They are paying for some other digital enablement service which may not yet have a widely used name.

    Because this distinction can be a little fuzzy, it helps to have a case study. Luckily, we have one. Open SUNY recently released a Request for Information (RFI) for vendors that can help them meet a wide range of ambitious goals. While the term “OPM” was never used in the RFI, it’s pretty clear that the request was written specifically to include questions that one might ask of an OPM service provider. MindWires, our consulting company, responded to that RFI. Because we think the answers we provided to SUNY might be useful to a wide range of colleges and universities, we have published a shorter, edited version of our response. Because that response includes fairly detailed descriptions of our consulting services, we have published it on the MindWires site rather than here on e-Literate. But some less commercial discussion of SUNY’s request is also appropriate for the blog because it sheds some light on the challenge defining the product category in a useful way.

    SUNY’s Goals

    In their RFI, Open SUNY enumerates quite a few ambitious and complex goals (even before accounting for the fact that these goals are for a system of 64 diverse and independent colleges and universities):

    • Opportunities to position SUNY as a unique provider of educational opportunities for all learners;
    • Reaching the millions of New York residents currently not enrolled at a SUNY campus, who need higher education to be more effective on their jobs;
    • Significantly expanding SUNY’s online learning experience to serve exclusively online students who are currently not at a SUNY campus;
    • Potential next-generation innovations in online/digital education where SUNY may have a unique opportunity to leapfrog competition;
    • The most appropriate ways to productize SUNY’s vast educational offerings to prospective students;
    • Business and revenue sharing models to incent behaviors, ensure sustainability and provide campus/System revenue growth;
    • Opportunities to capture students SUNY is losing to other online schools generating revenue for investment in our campus operations;
    • Outreach and marketing plans that reach a broad range of key stakeholders, including potential students in-state and out-of-state, internal staff and professors, and other key stakeholders as identified;
    • Platforms and services to expand SUNY’s current online environment and enrollments to challenge current leaders in the field;
    • Insights into the type and structure of programs appropriate for this platform/business model;
    • Requirements to continually align educational opportunities with labor market needs;
    • How to best integrate SUNY’s 64 campuses and their faculty into this improved platform/business model;
    • The impact of the changing demographics in New York, as well as surrounding states and potential global opportunities;
    • Partnering with interested industry leaders, including other university systems;
    • Consideration of prior learning assessment as part of the improvement to this process.

    Much of this sounds like classic OPM work. For example, “[b]usiness and revenue sharing models” and “outreach and marketing plans” are classic elements of an OPM solution.

    The revenue sharing model is both particularly characteristic and widely misunderstood. Revenue sharing is best understood as a service offering. It’s financing. When I bought my last car from the dealer, I got a loan from them to help pay for the car. There were other ways that I could have financed the purchase. I saw the prospect of owing money and paying interest to the car company as a feature rather than a burden because the specific terms they offered were advantageous relative to other options I had at my disposal. In my case, I was buying a new car that cost more than the cash I had on hand. So I needed to take a loan from somewhere. But at 0.9% interest, I might have decided to take the loan even if I had the cash. I might have decided that the interest rate was low enough that I’d prefer to hold onto my cash.

    In SUNY’s RFI, they specifically ask for information about “business and revenue sharing models” because the system wants “to incent behaviors, ensure sustainability and provide campus/System revenue growth.” The revenue sharing model, which is also a risk sharing model, theoretically aligns the vendor’s incentives with the customer’s. Again, theoretically, the vendor makes money only to the extent that the new program is successful. In order for companies to share the risk, they generally want some of the control in addition to some of the revenue. They want some ability to influence decisions that impact the program’s success. This kind of arrangement only makes sense for both parties when the customer wants the vendor to actively manage parts of the program on a long-term basis because they believe their program will have a higher likelihood of success if the vendor does so. Management is a particular kind of enablement where the service provider actively oversees a particular function that the customer doesn’t feel is their core competency (like online marketing) so that the customer can focus more energy on in-house areas of strength (like curriculum).

    So here’s a rule of thumb for defining the shape and boundaries of an OPM service: If a reasonable person could believe that a revenue sharing arrangement is a rational option for paying for the program (regardless of whether the customer chooses that option), then the service may well be an OPM.

    Conversely, if a rational person could not believe that revenue sharing is a rational choice, then it probably isn’t an OPM service. Revenue sharing isn’t definitional for OPM, but it is an indication of the kind of close, ongoing reliance on the vendor to actively manage the program that is the hallmark of an OPM service. One could imagine a customer having one or more of SUNY’s goals and not wanting a full program management service. Take, for example, “[p]latforms and services to expand SUNY’s current online environment and enrollments to challenge current leaders in the field”. This could be as simple as an LMS or a courseware platform. It’s hard to imagine a university or system signing a revenue-sharing contract with their LMS vendor. A learning platform, or even a course registration portal, would be a kind of digital enablement service. But it would not be online program management.

    I’ve been very careful so far to refer to OPM as a service. “Solution” or an “offering” also both work. But I have deliberately avoided talking about OPM companies. Such beasts do exist. 2U and Academic Partnerships are two well-known examples of fairly pure-play companies that are known for offering full-service, revenue-sharing online program management solutions. But once companies start to unbundle their offerings to the point where it no longer makes sense for customers to think about paying for what they are buying via a revenue-sharing agreement, then those companies are offering both OPM and non-OPM digital enablement solutions. Since the sector doesn’t have product category names for those other solutions, they tend to get called OPM services. But prospective customers should think about them quite differently. In one case, the business arrangement should maximize the alignment of incentives between long-term partners. In the other, the customer might well want the opposite, i.e., to minimize long-term dependence on the vendor.

    Generally speaking, true OPM solutions make sense when a college or university is looking to launch a new, differentiated, free cash flow-generating online degree or certificate program. Many of those words can be boiled down to one: Money. The college or university (or system) wants to create an offering that, among other things, pays for itself and generates free cash flow—i.e., leftover money after covering certain core expenses—to spend on fulfilling other aspects of its mission. It’s a new program, and maybe even a completely new kind of offering for the school, so it’s more likely that the institution will need ongoing help with certain aspects of the program. Since there are a million billion MBA programs online already (for example), a new MBA program would need to be differentiated enough to draw students. Otherwise, it won’t generate money. Many colleges and universities know how to create traditional face-to-face programs that are differentiated and will bring in more money than they cost. Fewer know how to launch and run one online. Or, honestly, would want to. There are all kinds of tricks to marketing online programs successfully. Managing seamless registration is hard. Managing, say, live nurse practicums to support an online nursing degree program is hard. Running the registration, LMS, CRM, learning analytics, accounting, and other software, tuned to work together for an online program, is hard. Some schools just don’t feel like they want to put their money and energy into learning how to do these things well enough to run an excellent program. That’s where an OPM offering—which is almost always some flavor of lasting partnership between the school and the vendor, regardless of financing arrangements—can look attractive.

    There is a lot of attention being paid to a-la-carte, fee-for-service models within the OPM product category. We think that much of the activity in a-la-carte falls into one of two situations. First, a lot of OPM service providers tinker with the details to customize their service a bit. “Would you like to hire us for only 80% of our full service portfolio? OK, we can take these things off the service agreement (but not those others).” “Would you like to finance partly with loans rather than revenue sharing? Or use a down payment to reduce the size of your long-term payments to us? You can do those things.” The other situation is that the customer is looking for digital enablement but not online program management. They want help to get up and running. Maybe they’ll continue to contract out a couple of things, like help desk or marketing, but for the most part, they expect to manage the online program themselves. We’re not seeing a lot of activity in the middle ground between these two types of situations. That supports our belief that these are really two distinct product categories. True a-la-carte digital enablement services that do more than tinker around the edges are not OPM services. That doesn’t make them better or worse. It just means that they solve a different problem.

    There’s one more point worth making about the boundaries of “OPM” which is specific to SUNY’s situation. Precisely because online program management requires a very close, ongoing collaboration between the school and the vendor, many OPMs sell first not to universities but to individual schools within a university. First they may develop a relationship with the business school. Maybe they’ll use that to get a referral to the nursing school. And so on. That way of working cuts against the grain of a large, diverse, and decentralized system like SUNY. I used to work at SUNY Systems Administration, and I still know people both in the central offices and out on the campuses. It’s very difficult to get SUNY to do anything in unison as a 64-campus system. Nor is that abnormal for a large, diverse state system. The kind of slow consensus-building and respect for autonomy required to galvanize group action in that kind of environment is hostile, if not outright antithetical, to kind of joined-at-the-hip relationship required for a successful OPM partnership. SUNY can vet and pre-negotiate with OPMs for adoption on a campus-by-campus basis. They can contract for system-wide digital enablement services where campuses can opt-in. They can even build their own sort of system-internal OPM (which would not be entirely different from the function of the original SUNY Learning Network). But we don’t see any evidence that a traditional OPM service could be successfully implemented as the default partnership system-wide in an environment like SUNY. To reach that kind of scale in that kind of environment, the State of New York will have to come up with something truly innovative.

  • OPMs are a Subset of a Bigger Market

    OPMs are a Subset of a Bigger Market

    We are seeing a tremendous surge in interest regarding Online Program Management (OPM) companies. Certainly many of the major higher education news outlets are running stories on them and many analyst firms are publishing white papers. That’s a sign that others who pay attention to this space are hearing…something. But it’s not a strong signal by itself.

    In our own work, we are definitely hearing more interest in OPMs, and we are also hearing from OPM companies (and OPM-like companies) that there is a pick-up in incoming requests from universities. For example, we had an opportunity to facilitate an institution-wide approach at UCLA to vet and pre-qualify OPM vendors as individual colleges determine their online strategy. There was a pretty robust and diverse range of responses. Equally importantly, the pre-qualification approach indicates a sense that different schools and other stakeholder groups within large universities or systems may have different needs.

    You can see this as well in Open SUNY’s system-wide Request for Information (RFI). Here is one of the largest university systems in the country, and they are essentially casting a wide net, asking, “What do you think we should know about this space in order to serve our 64 very different campuses with a wide range of needs, while also serving the needs of the system as a whole?”

    That wide open RFI from SUNY really speaks to the good news/bad news of the current state of the OPM market. The good news is that there is an increasingly broad range of options for colleges—or schools within those colleges—with different needs. The bad news is that the market is such a mess right now that it’s hard for colleges to find the right vendors to talk to and hard for vendors to find potential customers who need what they’re offering.

    A lot of the analysis we’ve seen so far has been variations on a theme: “There’s a lot of [mostly unspecified] innovation in the the OPM market. For example, revenue sharing isn’t the only financial model anymore!”

    While there is indeed increasing variation in the OPM space—only some of which we would call genuine “innovation”—we believe the expanding range of financing options is the tip of the iceberg. The deeper cause of the current chaos in the market is largely the result of a more profound broadening out of demand. This, in turn, is driven by a tectonic shift in how universities go about fulfilling their core mission of enabling student success. As new change management needs emerge, we don’t yet have names for the solution categories that meet those needs. But since the new solutions share elements with solutions to online program management problems, everything is getting lumped under the heading of “OPM.”

    There are several factors that are major contributors to the current rush to by vendors to call themselves OPMs:

    1. The variation between kinds of programs that universities are looking to launch is significant and increasing. As a result, different OPM vendors are specializing in different kinds of programs.
    2. More universities are making fine-grained choices about which aspects of their online programs they want to outsource to a specialist, which aspects they want to pay a consultant to help them get started or improve, and which aspects they believe they can do themselves. This broadening out of customer choices is creating further variability in in OPM business models and OPM-like services offered by an increasingly wide range of companies.
    3. As the OPM business disaggregates, universities are increasingly recognizing that certain functions that OPMs perform, like recruiting students who are likely to be successful in a program, redesigning courses to maximize student success, providing early interventions to promote student success, and working with employers to help with career readiness and post-degree employment are all services that might be useful for improving the success of their traditional programs.

    The common theme with all three factors is that customers who think they are all looking for “OPMs” are, in fact, trying to solve a wide range of different problems. So wide a range, in fact, that the term “OPM” is on the verge of becoming meaningless.

    We believe that all of these needs belong under a larger umbrella that we call “Digital Enablement Services.” In general, colleges and universities are beginning to move from having a philosophical commitment to student success toward operational excellence at enabling student success. The idea here is to use modern tools—and more importantly, the educational practices and organizational processes enabled by those tools—to do a better job of making sure that students don’t fall through the cracks.

    It’s easiest for universities to see the need to improve their operational excellence when they are launching a new, (hopefully) revenue-generating and net cashflow-positive degree or certificate programs. They are making a substantial upfront financial investment in the hope that future tuition will make that investment pay off for the university as well as for the students. To do this, they need to keep students happy enough that they stay in the program, even as the university loses the traditional face-to-face touchpoints that they have relied on to engage with their students and have to figure out how to build digital equivalents. It can feel like a scary (and potentially career-ending) undertaking. This is why 2U—a publicly traded OPM with a $3.9 billion valuation—made a smart branding choice with their tag line, “No back row.” ((Disclosure: 2U is one of the sponsors of the Empirical Educator Project.)) It is also why universities have been willing to accept revenue share arrangements. They reduce the up-front cost of the program—sometimes to the point of making an otherwise unaffordable program possible—and shift some of the risk to the vendor in return for a share of new revenues and some sharing of control over certain aspects of the program design and management.

    There is increasing interest from universities to step away from revenue sharing agreements and be more selective in how they use external vendors to plan, launch, and manage new online programs. That’s a real trend, though it is being somewhat hyped by shallow market coverage and some industry players who are looking to differentiate themselves against more established competitors. As far as we can tell, there is growth across the different models, particularly since the range of program types universities are looking to offer increasingly have different kinds of risk profiles.

    Think about the differences in launching and running the following different types of programs: (1) a largely synchronous online nursing degree, including a required face-to-face practicum at a hospital, (2) a mostly self-paced, competency-based MBA, (3) a “micro-masters” degree in cyber-security, and (4) a code academy. Think about what it would take to design and launch each type of program, how much new expertise each would require of the university, how much support the students would need in each case, how hard it would be to recruit students, to track them in the existing ERP system, and so on.

    Given the differences in these challenges, there should be demand for significant variety in OPM services with different sweet spots. OPMs with different models do end up competing head-to-head in the market sometimes, but that’s partly because customers don’t yet have a good way of sorting out what kinds of characteristics are most important to support their specific goals. In its current state, the market isn’t efficient at enabling customers and vendors to determine if there’s a good fit.

    The chaos we are seeing now is nothing compared to what’s coming. Universities are beginning to see needs for OPM-like services elsewhere. As budgets continue to tighten and pressure to improve outcomes continues to rise on public colleges and universities, academic leaders are increasingly realizing that improving degree completion and decreasing time to degree are good for both the student and the financial health of the institution. At the same time, changing student expectations are putting pressure on high-end private colleges and universities to recognize that the formula which has made them successful for the past century is not guaranteed to bring them top students and generous alumni in the next one. This has the potential to be a Pandora’s box. Where is the line for defining an OPM? And how can universities find vendors with the kinds of OPM-like services and business models that are appropriate for helping solve their particular problem?

    Over the next months, we at e-Literate are going to try to put some definition around this market, first by defining the boundaries of the OPM solution category—and the variation within those boundaries—and then by naming and defining other, similar-looking solution categories that solve different problems. We will be blogging about it and releasing at least one report about it as well.

    Stay tuned.

  • UF Online’s New Corporate Partner: Discover Financial joins Walmart with Online Education benefit

    UF Online’s New Corporate Partner: Discover Financial joins Walmart with Online Education benefit

    Last week Walmart announced a new education benefit for its employers, subsidizing undergraduate college degrees at select online programs at the University of Florida (through UF Online), Brandman University, or Bellevue University.

    The company said it estimates as many as 68,000 of its employees initially could sign up for the new college program. Walmart employs 1.5 million in the U.S. The company declined to comment on how much this initiative will cost it.

    Employees will contribute $1 per day, for 365 days every year, toward their education, so long as they’re enrolled. Walmart will cover the rest of the tab. Workers will be able to choose from the three nonprofit schools and have the option of taking classes online with the flexibility to study during the evenings or on weekends.

    Today UF Online announced another partner: Discover Financial Services, issuers of the Discover Card and Diners Club International, with its 14,000 employees.

    Discover announced a significant new education assistance benefit that provides all eligible U.S.-based employees the opportunity to earn a bachelor’s degree online from an accredited public or non-profit private university at no cost.

    Known as The Discover College Commitment, the benefit covers tuition and required fees, books and supplies needed to complete select online degrees at one of three schools – the University of Florida (via UF Online), Wilmington University and Brandman University. The benefit has no tenure requirement so employees can start participating as soon as they want regardless of how long they have been with the company, including new employees on their first day.

    The two partnerships are part of what UF Online calls their Employer Pathways, and in the process seem to be defining an alternate method of marketing and enrollment management, in contrast with most Online Program Management (OPM) assumptions.

    Employees from Walmart and Discover Financial Services have expanded opportunities to earn a bachelor’s degree from the University of Florida (UF) thanks to a new and significant investment in their education from their employers. This remarkable step by these and other large employers demonstrates the value of a UF degree and the accessibility of UF Online, UF’s online undergraduate experience. Employers will provide a robust support package covering tuition, fees, plus access to life coaching and college readiness programs.

    Discover is offering this new benefit to select programs at UF Online, Wilmington University, and Brandman University.

    Discover is covering 100% of cost for select bachelor’s degrees. Discover is proud to offer “The Discover College Commitment” program – an innovative full-ride college education benefit, providing US-based employees the opportunity to participate in one of several select high-quality, fully paid, online bachelor’s degrees.

    Both packages of education benefits is managed by Guild Education, “a tuition reimbursement and education platform that helps large employers extend education benefits, including tuition reimbursement, to workers”.

    I think these moves are more significant than just individual benefits. What we are seeing is UF Online, along with a handful of others, defining a different approach to marketing and finding potential online students, at least for undergraduate degrees. Historically, there is a common assumption that to enable a scalable online program there is a need for traditional digital marketing as the primary approach – Google AdWords, call centers, social media campaigns – with a partnership or two thrown in on the side. The origin of the OPM market is centered on providing these services in exchange for a percentage of tuition revenue, and for the majority of cases, the OPM’s spending on this marketing and enrollment management category is the most expensive service in the package. The Employer Pathways approach by UF Online has the potential to flip the student acquisition assumptions – primarily driven by employer partnerships with traditional digital marketing channels as a secondary approach.

    Walmart and Discover already have potential students identified, and the companies have the incentive to internally market these education benefits to employees. UF Online needs to support that internal marketing and feed applicants into the same application process, but they have a reduced need for general-purpose marketing. UF Online started out with Pearson Online Learning Services (formerly known as Embanet) to be their OPM partner, but in late 2015 they pushed Pearson out and decided to take over this management internally.

    I talked to Evangeline (Evie) Cummings, Associate Provost and Director of UF Online, at WCET’s Leadership Summit last week, and she described how UF Online is trying to reduce their marketing spend and instead invest more in faculty and course development. Part of that move is to spend less trying to get out-of-state students, which may pay higher tuition but still cost much more per student in acquisition costs. But the other move is to decrease the need to spend on traditional marketing channels.

    We can think of Guild Education in this case as a derivative of the unbundling version of OPM, enabling the front-end services with an alternative approach and what appears to be a lower revenue share.

    Rather than charge a transaction fee per student to the employer, Guild takes a cut of the tuition revenue from the universities it works with. This revenue-share model is an “elegant” solution for institutions that want to grow their enrollment online but don’t want to spend more on marketing, said Carlson. It’s also an attractive proposition for employers, who don’t have to pay any additional charges on top of the contribution they make to their employees’ tuition. The tuition fees are not discounted for the employers and will be charged at in-state or out-of-state rates depending on the location of the student. Neither Guild nor the three universities involved in the Walmart offer would disclose what percentage of tuition revenue Guild will take.

    The bulk of the OPM market serves master’s programs, and UF Online is centered on bachelor’s degrees with a handful of master’s, so this approach might not work across the board. But I’ll bet that there will be plenty of undergraduate online initiatives that will be looking to UF Online and wondering if they should develop similar degree pathway partnerships as the centerpiece of their student acquisition plans. The online education space is maturing and becoming a lot more interesting.

  • The ASU + GSV Conference was More GSV than Ever—And That’s Good

    The ASU + GSV Conference was More GSV than Ever—And That’s Good

    I’ve been struggling with how to characterize this year’s ASU + GSV Summit. Part of the problem is that it’s just become harder to sum up, for three reasons. First, the conference has gotten so big that it’s hard to see enough of it to get a representative sample. Second, as it has become a “must attend” conference for certain circles, it becomes harder for me to clear time away from meetings with people I know—both planned and unplanned—to be a fly on the wall. I can partly deal with that problem by bringing e-Literate colleagues who can be extra pairs of eyes and ears.

    But the third problem is harder. As the conference and the culture around it mature, the trends become harder to identify because they’re no longer fashion. We’re past the Year of the MOOC and the Year of Personalized Learning and all of that. Some of the less patient money has left, and some of it has refocused on corporate talent management. (Good luck with that; I don’t think it’s any easier than edtech.) A lot of the hype has faded into the background. The conversations seem more real and more focused on tackling important educational problems in realistic ways.

    Don’t get me wrong; there are still 12-year-olds in $300 jeans talking to 22-year-olds in $3,000 suits about how their math app is going disrupt education, and a few random dudes—and they are still often dudes, despite a sincere and concerted effort to make the conference more diverse—walking around wearing tinfoil headbands and loudly declaring, “I CAN READ STUDENTS’ MINDS!”

    But it’s easy to get distracted by the spectacle and miss the big picture. One way to look at the summit is as a giant peer review machine. Yes, with so many submissions, the quality will be uneven. And yes, sometimes a bad product will make it through the peer review process. And yes, you may find the process and the culture to be alien and unsettling if you’re not from that world. But from what I can see, the peer review machine is getting better in the sense that the pitches from startups to investors increasingly seem to focus on things that actually make sense in terms of developing products that are educationally useful.

    Coincidentally, I was reviewing some of the videos of the lightning talks from our Empirical Educator Project (EEP) summit this morning as I was thinking about this post. I was struck by how the presentation from RealizeIT, which is the type and size of company that would typically pitch at ASU + GSV, was not hugely different from the best of the pitches at that summit:

    The main difference is that, for the EEP crowd, the presentation focused on the collaborative research with University of Central Florida and others to improve student impact, while a good GSV pitch might pivot off the impact visualizations to talk about how their evidence of impact has led to increased sales. Having the latter conversation between companies and funders is an important piece in the ecosystem that was missing before the ASU + GSV conference. Trying to have the former type of conversation doesn’t work easily in the same forum with the latter type, partly for reasons of cultural differences. In the early years of ASU + GSV, the conference organizers—again, with the best intentions—worked very hard to try to host both conversations, with the result often being strong negative reviews from the academics. In more recent years at the summit, the academic needs seem to be coming in more organically via the companies as intermediaries and self-selecting academics who are, for lack of a better term, bi-cultural.

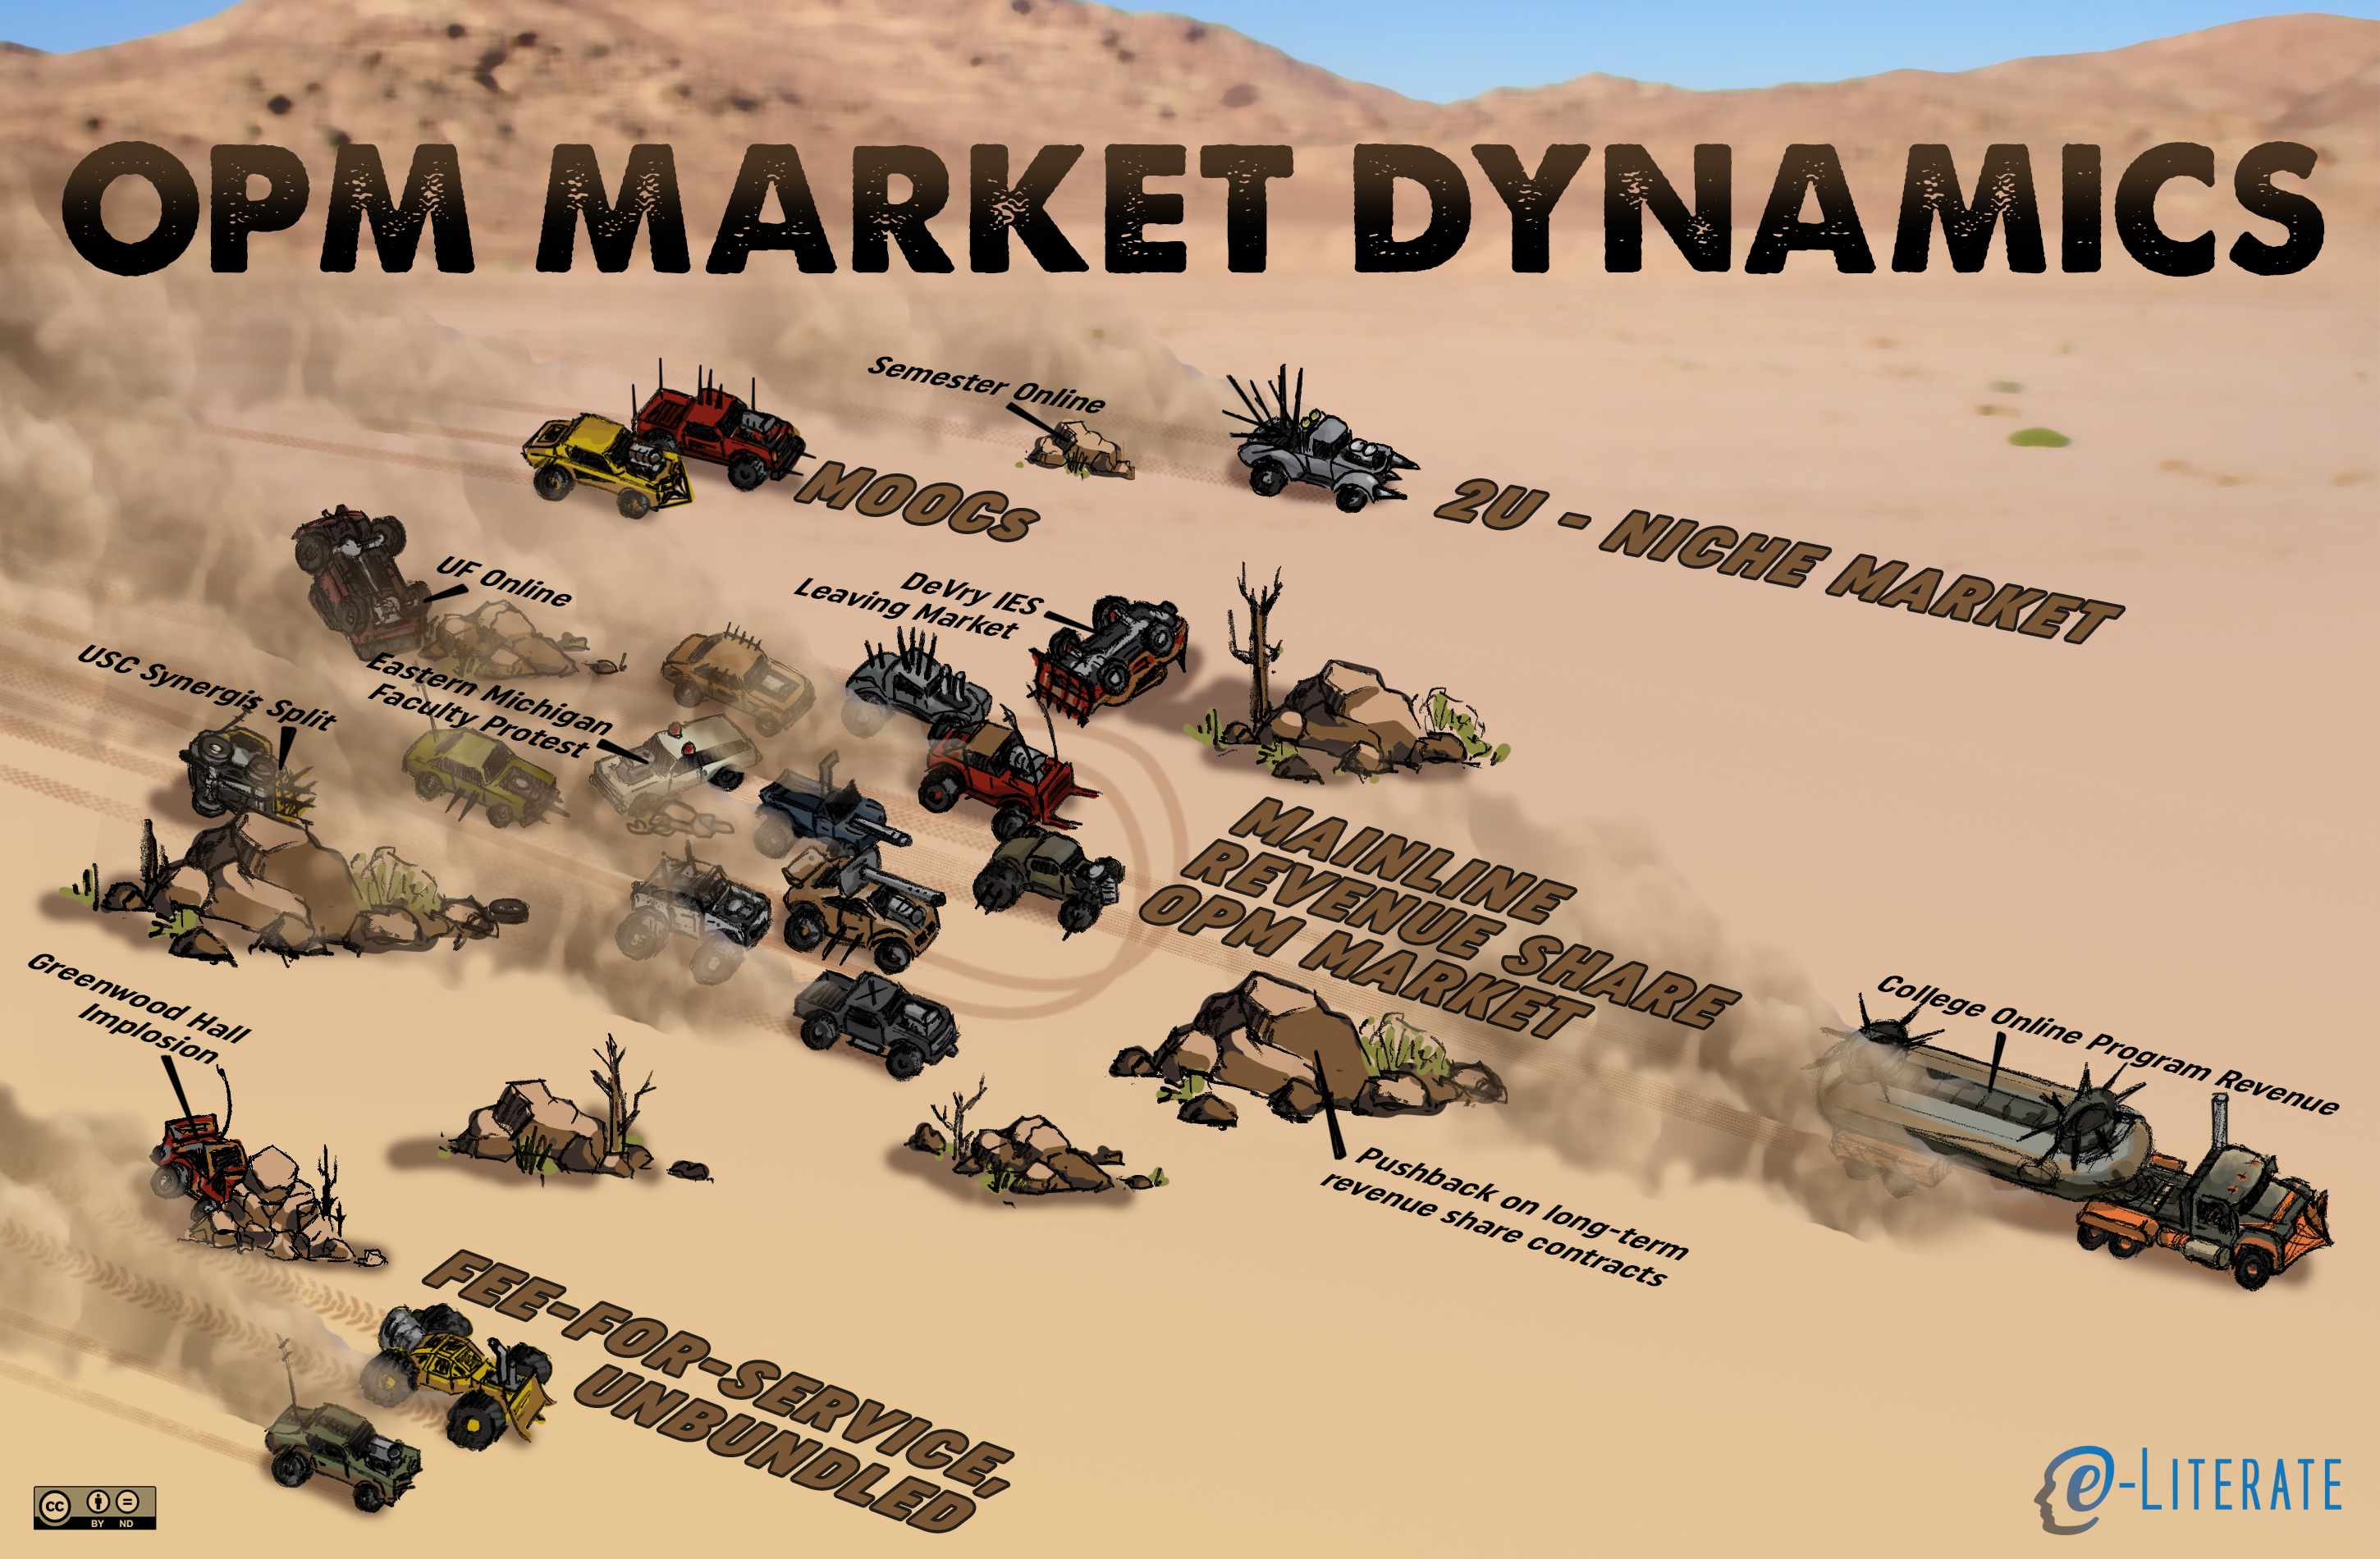
    The one trend that did stand out at ASU + GSV, which I think is related to the above, is a lot of activity around Online Program Management (OPM) companies. Something fairly deep is happening in this space. Right now, most of the buzz is around the debate over whether the future of OPM business models is in revenue share or fee-for-service. I think that’s a red herring, created in part by the bad blood between some individuals at Noodle Partners—one of the leading proponents of the fee-for-service model—and 2U—the darling of the revenue share crowd. The truth is that, while there is some overlap in competition, what we are seeing increasingly is a range of different companies, many but not all of which are currently labeled as “OPMs,” that offer different bundles of services and different financing models that are best suited for solving different kinds of problems. The common thread is that there is a growing range of service businesses that help colleges and universities develop strong, student-centered degree and certificate programs, either by creating new ones or strengthening existing ones. We don’t have a good term or set of subcategories for this class of businesses, of which traditional OPM is one subcategory. (And some of these business are pretending that they are not service businesses for a variety of reasons, but that’s another story.)

    To me, this squishiness in the OPM market is a sign that more and more schools are serious enough about learning to be systematically better at supporting student success that they are increasingly willing to pay for help. And that change in prioritization is potentially good for everyone. And ASU + GSV has become a good vantage point for spotting that kind of change—if you look hard enough.

  • If At First You Don’t Succeed, Try To Be An OPM: Conversion of for-profits and MOOCs

    If At First You Don’t Succeed, Try To Be An OPM: Conversion of for-profits and MOOCs

    Two weeks into March, this has already been a busy month already for the transformation of for-profits and MOOCs. For-profit universities are in a race to become nonprofit by separating academic programs from behind-the-scenes services, and MOOCs are focused primarily on monetization and moving beyond free and open courses. The common thread tying these messy transitions together is the move to become new forms of Online Program Management (OPM) providers.

    Best Way to Make Money? Go Nonprofit

    Arguably the biggest news was March 5th when the Higher Learning Commission (HLC), the regional accreditor, approved the Kaplan University / Purdue University deal to create Purdue Global. This was the final approval step as Purdue acquires Kaplan, leaving Kaplan University, leaving Graham Holdings (Kaplan’s parent company) to serve as a single-client OPM provider.

    The following day Grand Canyon University announced that it had received approval from HLC to convert into a nonprofit institution. As described in their press release, the remaining for-profit company will become an OPM, even if they choose not to use that name [emphasis added]:

    As part of the transition, GCE will sell certain academic-related assets to a non-profit entity that will carry the Grand Canyon University name. Following the sale, GCE will operate as a third-party provider of educational and related services to GCU and potentially, in the future, to other universities. The structure is similar to that at hundreds of non-profit universities in the country that outsource services to third-party providers.

    And yesterday, Bridgepoint Education announced that they were formally seeking to convert Ashford University into a nonprofit in a similar deal as Grand Canyon. At least they are more direct about the OPM tie-in as described at Inside Higher Ed yesterday.

    Bridgepoint will continue on as an online program management (OPM) provider — a booming space in higher education. The company will negotiate with Ashford to enter into a shared services agreement, with Bridgepoint likely handling data management, course management software and services, technology, and financial aid processing for the nonprofit university.

    “As an OPM, Bridgepoint Education will bring years of technological and academic innovation and intellectual property development to other colleges and universities that desire to serve students through online education programs,” Schray said in a written statement.

    In an interview here at e-Literate when Purdue and Kaplan announced their acquisition plans last April, Trace Urdan (now at Tyton Partners) described the market forces involved in some of these moves.

    • Non-profit entities – both public institutions and private non-profit institutions – “wanting to get into the adult market and the online market”. This is the big push behind the Online Program Management (OPM) market, kick-starting these non-profits into online programs targeting adult education.
    • For-profit entities “feel like they are being burdened by being for-profit”. One part of this is the regulatory burden from the Department of Education and even accreditors. But there is also a marketplace burden as non-profits like Southern New Hampshire University keep growing enrollments while for-profits are dropping.
    • There is a “the investor enthusiasm for the services model” with OPMS, “and this is a model that investors love – it gives you access to the growth in online education, affiliation with strong brands, and it’s more or less free from the regulatory hostility” of the for-profit sector.

    Beyond the market forces, however, there is another underlying factor affecting these moves. As described by legal team at Cooley Education:

    So, why did this happen? First, and most obviously, we are in a different regulatory environment – at least as far as the federal Department of Education is concerned. In late 2017, the Department of Education dropped its opposition to for-profit conversions vehemently articulated by then-Secretary John King, most recently approving the sale of South and Argosy Universities and the Art Institutes owned by Education Management Corporation to a nonprofit created by the Dream Center Foundation. This change in federal policy shifted the emphasis on approvals back to the accreditors and the states.

    At the accreditor level, the politics may be less important in understanding the outcome than the process. At about the same time that Kaplan-Purdue was first announced, HLC began working on revising its policies and procedures to establish new benchmarks by which such transactions would be measured. HLC made two significant changes: it updated its procedures for review of Change of Control transactions and, in a politically astute move, also established a policy that Department of Education approval must be obtained before HLC acts on a change of control application, thus insulating itself from second-guessing in Washington. (HLC’s change was telegraphed in late 2016 when it deferred acting on the sale of the parent of the University of Phoenix to a private equity group pending prior ED approval.)

    Significantly, HLC now has relatively clear guidance governing what is needed for OPM relationships and for-profit conversions.

    How Do We Make Money? The Answer Is Simple – Volume

    Meanwhile Coursera announced their plans to further focus on the monetization of supporting online degrees, as described at EdSurge on March 5th.

    These days, though, many MOOC platforms are courting the traditional higher-ed market they once rebuked, often by hosting fully-online masters degrees for colleges and universities. And today, one of the largest MOOC providers, Coursera, announced it’s going one step further in that direction, with its first fully online bachelor’s degree.

    Coursera is not alone here – most notably Georgia Tech and Udacity launched an online master’s of computer science in 2013. In a related move, edX has begun its work supporting online master’s degrees through its MicroMasters program, and FutureLearn – spun out of the Open University of the UK – supports multiple degree programs.

    While the Coursera news focused on the new bachelor’s program, the bigger news was the expansion its graduate programs as described at Inside Higher Ed.

    Online education platform Coursera has set a goal of offering 15 to 20 degree programs by the end of 2019. The company took another step toward that goal Wednesday, announcing new degree offerings from the University of Illinois at Urbana-Champaign and France’s HEC Paris.

    “This is our coming-out party for online degrees on Coursera,” Nikhil Sinha, Coursera’s chief business officer, said in an interview.

    FutureLearn announced their own expansion of online degrees last month.

    For the MOOC providers, their move into the OPM space seems to be driven by their leverage of current registered learners as a marketing channel, as described in a separate IHE article.

    Roughly half of the students in Coursera’s current degree programs took one of the open online courses first, essentially enabling students to “try these degrees before they buy them,” Maggioncalda says. So not only do students have a chance to see how they like a professor, or how well they perform, before enrolling in the for-credit program, but Coursera also asserts that it can drive down the cost of acquisition of students by tapping into its 31 million users.

    Coursera’s institutional partners “share a certain percentage of the learner fee with us in exchange for distribution to our world of learners, and the whole delivery of the system on our platform,” Maggioncalda says.

    New OPM Models

    Two years ago we described how the OPM market has evolved beyond its full-service tuition revenue-sharing origins to add unbundled service offerings – not to replace the previous model but to augment it. What we are now seeing are two new models within the OPM market becoming much more clear: the remnants of for-profit conversions into nonprofit status, and MOOCs supporting online degree programs. Both of these models are driven by markets that need to move beyond their origins as well. A lot of changes happening in the education space.