e-Literate

Present is Prologue

Category: Business & Economics

The “Business & Economics” category covers the business aspects of ed tech, including the financial health and business models of individual companies, economic aspects of selling in education that shape the available offerings, and coverage of markets and investment.

  • Instructure’s Better Possible Future

    Having reluctantly weighed in on Instructure’s proposed acquisition by Thoma Bravo, I would like to turn back toward positive rather than negative possible futures by describing a different potential vector for the company. Despite the criticisms of my previous post, I do not believe that Instructure is in a deep hole, inevitably heading deeper, with no way out in the foreseeable future. If there are two takeaways from that post, they are these: First, it is easy for an EdTech company to have a sudden and dramatic reversal of fortunes and of customer perceptions, especially in the downward direction. Instructure is at an inflection point where the risk of such a turn is particularly high. (I warned about this over a year ago, after Instructurecon 2018.) Second, the seemingly obvious or proximal causes of a company’s success can be misleading. When we misunderstand causality in this way, it heightens the risk. Instructure has not been a well-understood company in general, and my concern is that the current board of directors and executive management may not have a good understanding of the causes of the company’s historic success. So that post wasn’t about what will happen. It was about what could happen.

    In this post, I want to explore the company’s actual current competitive strengths as the basis for the kind of growth in value generation that both customers and shareholders would like to see. In the process, I’m going to have to spend a little more time analyzing their missteps. But beating up on Instructure’s management is not my goal. Rather, I want to offer up a case study for how value can be created in EdTech in the 2020s. In the process, I am going to spend some time on the promise and perils of data-driven affordances.

    Reminder: D2L, one of Instructure’s major competitors, recently became the first foundational sponsor of e-Literate’s Empirical Educator Project (EEP). Given that big decisions are in the process of being made about Instructure’s future right now, I am obliged to call special attention to the appearance of a conflict of interest.

    Instructure’s remaining competitive strengths

    As I highlighted in my previous post, Instructure entered the market with competitive strengths that were difficult and time-consuming for their competitors to duplicate. One was that Canvas was built from the ground up to be cloud-native. From their customers’ perspective, that’s a critical ingredient to the product’s reliability. From their competitors’ perspective, it is a very hard technical task to retrofit a cloud architecture onto a mature product that was designed to run on individual customers’ own servers. Another competitive advantage was that Canvas was built from the beginning to delight end-users, whereas older platforms were at least partly built to delight the IT managers who had made purchasing decisions in the early years of LMS sales, and who often had different concerns than the end users. This too is very hard to retrofit onto an older application. Arguably, Blackboard’s biggest mistake with Ultra has been to set customer expectations too high regarding the pace of progress. The rearchitecture and redesign they have undertaken are genuinely, seriously hard.

    But given time and motivation, these challenges can be overcome. And sure enough, Instructure’s competitors have been steadily narrowing these gaps over the years. The race is now competitive in these areas where Instructure had the field to itself for a long time. Likewise, their competitors have improved their customer service and focus on improving the end-users’ interactions with the companies.

    So what’s left?

    First, while Instructure’s brand has taken a couple of hits lately, it’s still strong enough, and customer memory of their positive experiences with the company is long enough, that lost ground can be regained. There are some customers who have had bad experiences, or growing concerns. The CEO has said potentially alarming things in public and failed to correct his mistakes. Nevertheless, I get the sense that the customer base is still rooting for the company to find its footing again.

    Second, there’s the culture. Most of the front-line people and important mid-level to senior managers who grew up in Instructure’s culture of excellence are still there. They still have the same knowledge, skills, experience, and convictions. And they have a collective muscle memory of how to work together in ways that were successful for customers in the past. Until we start seeing either talent flight or layoffs that cut deeply into the wrong parts of the company, then the heart of the original company is still beating.

    As for the core platform, while it’s no longer dramatically differentiated, it’s still solid. All things considered, nobody enjoys migrating to a new LMS. Instructure is still on a glide path to at least maintain its market share in the US and grow abroad. They would have to actively screw that up for the situation to change. And while that is easier than it may seem, it would take a while.

    Finally, while the market has caught on to the value of Canvas being designed as a cloud-based application with a focus on end-users, there is one other novel decision the company made early on that is still underappreciated. Canvas was designed to be a platform, not an application. To grasp the difference, think about the difference between a Blackberry (if you are old enough to remember those) and an iPhone. The Blackberry was a good phone that had a great keyboard. So, in a world where texting and email were becoming at least as important as voice communications, adding text communication features to a phone was a good idea. Yes, there were a few “apps,” for Blackberry. But there weren’t many, and most of them were bad. The iPhone, in contrast, was built for apps. Instead of making the primary interface a great physical keyboard, Apple made it a pane of glass. The interface was anything that could be created for a touch screen. Including interfaces and applications that Apple hadn’t even dreamed of. The iPhone is a platform. It is infrastructure that is designed for other people to write applications that run on it and through it.

    Instructure made a series of principled decisions not to develop certain capabilities in Canvas. Instead, they built both the technical infrastructure in Canvas and the relationships with integration partners to have a very strong ecosystem of EdTech companies that have deep relationships with the company and deep integrations with the platform. Rather than building a great keyboard and email app, they built a metaphorical pane of glass and app store. They created a technology platform and ecosystem that attracted other people to extend Canvas with new capabilities.

    This too was a pioneering strategy. Before Instructure, the model for LMS partner relationships had been set by Blackboard in the Chasen/Small era. They recognized that the vast majority of digital education products would have to integrate with the LMS. So they decided to monetize that by charging every integration partner a (significant) fee. In those early days, there was some business justification for that strategy. After all, Blackboard had invested in developing integration APIs—Blackboard Building Blocks—and, since they were by far the largest player in the market, integration with their platform offered substantial business opportunities in the form of access to Blackboard’s customer base. This became a significant revenue source for Blackboard that its competitors envied and, to varying degrees, tried to emulate.

    But just as Instructure was lucky to come along right when the nature of the LMS customer was shifting, and right when cloud-based development had matured enough to make building a cloud-based LMS feasible, they were also lucky to come to market right when the IMS LTI interoperability standard was starting to take off and EdTech venture funding was really taking off. The LTI technical integration standard made charging a toll harder to justify, while the proliferation of EdTech startups transformed the locus of value for an LMS from a Swiss army knife into the hub of an ecosystem. Or, as my friend Kelvin Thompson from UCF has memorably characterized it, the potato part of Mr. Potato Head. On the one hand, there is no Mr. Potato Head without the potato. On the other, the potato itself is not where the personality (and personalization) come from. Instructure was less focused on charging partners and more interested in enticing them into adding character to Canvas in new and imaginative ways.

    Dalek Mr. Potato Head
    Homer Simpson Mr. Potato Head

    Their platform differentiator is subtle in the LMS world, but one that is critical to their current situation.

    In fact, it is essential to the first of two paths Instructure has for developing a product portfolio that I’m going to describe in the remainder of this post.

    Acquisitions

    There is now a whole galaxy of small EdTech companies that have developed new products or services that touch the LMS in one way or another. Instructure arguably is in the best position of any of the players in the market to identify good companies with products that already integrate well with Canvas and snatch them up. It’s not an exceptionally strong or durable advantage, but it’s one that they could be utilizing aggressively right now.

    Former Instructure CEO Josh Coates had a philosophy about acquisitions. Specifically, he was against them most of the time. I heard him give a talk about it once. His strategy was thoughtful and well-reasoned. And it would have been justified had the company succeeded in organically developing a portfolio of compelling offerings. But that didn’t happen. So, at least for the short term, the company is going to need to be more acquisitive in order to become financially healthy. But for that strategy to work, Instructure will need to rely on the knowledge of its employees who have worked on the platform aspects of Instructure’s business to identify truly good companies. What I mean by “truly good companies” is ones that have earned customer loyalty by solving some important problem well. Instructure needs to find compelling products, which is not easy in EdTech. The company leaders will also need to clearly and consistently articulate the reasons why they are proud to have acquired those products and how the acquisitions will better serve their Canvas customers.

    Instructure has made one high-profile acquisition under CEO Dan Goldsmith: Portfolium. Here’s the relevant bit from Instructure’s press release announcing the acquisition:

    Portfolium was created to help every person realize their full potential by connecting their learning with opportunity. The company helps institutions inspire, assess, and showcase student achievements via its powerful ePortfolio network, student-centered assessment, job matching capabilities, and academic and co-curricular pathways.

    “Working with Portfolium advances our mission since it enables us to help people move from the classroom to the workplace,” said Dan Goldsmith, CEO of Instructure. “Portfolium has been a great partner of ours. With their team, and by adding their student success capabilities built on the leading learner network, we will, together, provide more value to both current and new customers.”

    Instructure Enters Into Agreement to Acquire Student Success Network Portfolium

    Honestly, I don’t know what that means. Portfolium is an ePortfolio. That blurb mostly describes what an ePortfolio does, but adding some pleasant adjectives. Shorter version:

    Instructure is acquiring Portfolium, which is an ePortfolio company. Portfolium does things that ePortfolios do. We like it and think you will too.

    Honest press release

    The only bit in there that isn’t completely generic is the sentence fragment about job matching. But they don’t do anything with it.

    In fairness, most people who haven’t written a press release don’t appreciate how hard it is to write a meaningful one. I’m a pretty good writer, but I will readily admit to having struggled with that particular genre at times. That’s exactly why smart companies don’t rely on the press release to carry all the weight. They go out and repeat and elaborate on the message. Relentlessly.

    I haven’t heard any such message about Portfolium.

    Again, in fairness, I have not been following the LMS market as closely as I used to. But the thing is, if Instructure were really doing this right, it shouldn’t have been possible for me to miss this. I should have read it in the articles in outlets like EdSurge, Inside Higher Ed, and The Chronicle. In preparing to write this post, I did a search to see if I missed anything in the coverage by these or any other outlets.

    Nope.

    No quote from the CEO beyond what was in the press release. In fact, no quote that I could find from anyone that wasn’t already in the press release. There was an interview with the Portfolium founder in the San Diego Tribune. But it was clearly a local business story, in a local outlet—Portfolium was San Diego-based—and not anything aimed at Instructure’s customers. There’s nothing. Nada. Zip.

    When I ask Instructure customers about the deal, they tell me they haven’t heard anything either. And when I have run into Instructure employees at conferences—specifically, ones who are in a position to know about Portfolium—none of them have brought it up with me. In the old days, they would have. These are the same humans. There has been no invasion of the body snatchers. So it appears that the corporate communication strategy has changed. Where it used to be the case that you could get any random Instructure employee driving a golf cart at Instructurecon ((Golf carts driven by employees at Instructurecon is an actual thing. Or at least, it used to be.)) to talk about just about anything, it is now difficult to get even senior Instructure managers to talk about…well…just about anything.

    So there is at least one and possibly two serious but very fixable problems here. First, there is definitely a communication problem. Specifically, it would be good to have meaningful communication directly from the people within the company who understand why acquisitions are being made. Instructure employees have been some of the best brand ambassadors in the sector. Circumstantial evidence strongly suggests that they are no longer empowered to speak for the company. By muzzling them, Instructure is voluntarily throwing one of its remaining competitive strengths in the garbage can. And the only senior manager who has been allowed to speak on the record about the Goldsmith era’s first important, high-profile acquisition—to anybody, apparently—is the CEO. The one who has the most to prove about actually knowing the sector and caring about it. And his only statement that I can find amounts to a spoonful of bland pap in a press release.

    I don’t know much about sports, but I know what an unforced error is.

    While it would be easy to lay much of this at the feet of the marketing department, there has been a pattern of communication in the Goldsmith era that started immediately after he became CEO and has been consistent despite some churn in marketing department senior personnel. In fact, that churn may be an indicator in itself. The leader sets the tone.

    The second possible problem is harder to assess precisely because of the effects of the first one. I can’t tell if Portfolium is a good acquisition or not. A lot depends on what problems Instructure’s managers think it solves for customers and how they intend to make it more useful. Which they’re not really talking about. I can’t tell if this acquisition was a paint-by-numbers decision or if there is a real effort to increase value for the customers in a mindful, meaningful way. Instructure has people who know which partners are good potential acquisitions and why. They know their partners and customers really well. I can name a handful of them off the top of my head. In general, they are not being heard externally, which is unfortunate. If they are also not being heard internally—and again, I can’t tell one way or another—that would be a lot worse.

    I am confident that Instructure has the right ingredients and the right chefs to cook up an effective acquisition strategy. But the proof of the pudding is in the eating. If Instructure doesn’t both prioritize the acquisition of companies that will serve their customers well and communicate the reasoning and intentions behind the acquisitions, that could easily mean the difference between customers who are hungry for more and ones who are left with a bad taste in their mouths.

    Insights

    The other area for growth is in providing educators and students with better insights that support student success. It is impossible to overstate both how important and how fraught a topic this is.

    On the one hand, colleges and universities fail huge swathes of students all too often. There are students who want to go to college, get admitted to college, but haven’t had anybody to teach them how to succeed in college. Students who never make it to the first day of class. Or who get partway to a degree and drop out, due to lack of skills and support or tough personal circumstances. Students who need to come back to school and reskill while they are holding down full-time jobs and raising families.

    Many colleges and universities are not very good at serving some or all of these groups and routinely fail them. This used to be “only” a moral failing. Now it is an existential one, because the most obvious path to long-term sustainability for an increasing number of colleges and universities is to serve more students in their area more effectively for 20 or 40 years rather than for two or four. Institutions of higher education need to learn to perform better. And they need to learn it urgently. To do that, they need new insights. To get new insights, they need better information—that is, better data—and better ways of analyzing it.

    On the other hand, we live in an era when people have good reason to be concerned about the misuse of data in a seemingly ever-increasing variety of deeply troubling ways. Educators are responsible for their students. Many of them take this responsibility very seriously indeed. And particularly when it comes to the experimental use of data—even for the best of purposes—that responsibility is hard-wired into institutional processes in very particular ways.

    In academia, educational research falls into a larger bucket of “human subjects research.” That category also includes research on topics like how to perform open-heart surgery, how to deal with intractable clinical depression, and how people can be manipulated or fooled by social media. Think about the possible unintended consequences of poorly designed experiments in any of those three areas. We have canonical examples from bygone eras. The Milgram experiment. The Stanford Prison Experiment. Today, any academic research conducted in the United States that involves human subjects must submit its experimental design and protocols for experimental subjects’ informed consent to a rigorous peer review and approval process before the experiment can be undertaken. Educational research must be submitted to the same approval process by the same oversight board that would approve life-and-death surgery or psychological experiments.

    But unlike in medicine, an EdTech company that wants to conduct research using student data for product development purposes is required to do…nothing at all. They don’t even have to inform the students that they are being experimented on.

    In fact, EdTech companies conduct experiments on a weekly basis that would require a lengthy approval process in some universities. ((Different universities interpret the rules around such approvals differently, in part because a university that has a world-class medical school will likely understand their responsibilities differently than one with no medical school at all but a significant psychology research program, for example.)) Suppose, for example, that product developers want to test which design of a button is more likely to raise user awareness of a feature. They conduct what is known in the industry as an “A/B” test. They show some users one design, other users the other design, and track which design gets the most clicks. This is an absolutely routine software development practice. It is a foundational strategy that developers use to learn how to make their software more useful and usable.

    But let’s also suppose that the feature the button activates has a significant impact on improving student outcomes. Using the feature helps to improve learning. The developers, with the best of intentions, are trying to figure out which version of the button will get more students to use the feature that will help them. But in this experiment, the button that turns out to be worse may negatively impact the learning outcomes of students using that version of the software.

    This is exactly the kind of contingency that might trigger a requirement for an experimental design review process inside a university.

    Imagine that you’re an academic who feels responsible for your students and who lives in that kind of a culture surrounding anything that remotely looks like it could be human experimentation. Imagine that you read the following statement by the CEO of a company whose EdTech product you, personally, require your students to use extensively every single day:

    We’ve been working on the scaffolding for [DIG] for well over a year now. I mentioned in our remarks that we already have product validation towards out there in the market. We have instructors and students consuming output from some of the initial experiments with DIG. And we anticipate later this year obviously to make more announcements around specific products and offerings and how we bring them into the market. DIG ultimately is a platform first and foremost based upon machine learning and artificial intelligence. I believe that any multi tenant SaaS company born in the cloud has the opportunity once they hit a certain market share. And in fact, it may even be incumbent upon those organizations to partner with the industry and evolve that industry with new insights and predictive modeling using AI and ML. That’s what DIG is at its heart.

    We already have analytical capabilities in our Canvas platform. I want to be really clear and delineate the difference between an analytics and reporting capability, and a machine learning and AI platform. [snip]

    We have the most comprehensive database on the educational experience in the globe. So given that information that we have, no one else has those data assets at their fingertips to be able to develop those algorithms and predictive models.

    Instructure CEO Dan Goldsmith

    Heads would explode. Heads did explode. Heads are still exploding.

    Even so, as I said in my previous post, that was a very fixable problem. Dan was still new. He easily could have played the “new guy” card. A mea culpa, a couple of comments to reporters, and a brief but earnest listening tour likely would have blunted the worst of it. The company could have reset and been in a position to have productive conversations with customers about this thorny set of challenges that they need to face together. Instead, Goldsmith said nothing, and the problem festered.

    In July, Instructure VP of Higher Education Jared Stein wrote a blog post on DIG trying to settle things down and dispell some of the concerns. I trust Jared and, more importantly, Instructure customers trust Jared. He did a decent job in that post, as far as it went. But one blog post by a senior employee, three months later, is not going to undo the damage of such a bad faux pas by the CEO. A CEO trumps a VP. Therefore, a CEO’s misstatement can only be credibly corrected by the CEO. Furthermore, Pandora’s Box had been opened. Because Instructure didn’t jump on the lid the moment they saw it crack open, all the deeply difficult questions about uses of student data in EdTech have come flooding out. The company didn’t lose everybody’s trust, but they lost the trust of enough vocal customers that now they have a persistent problem.

    This too is fixable, but it must be fixed. Some damage has been done to Instructure’s reputation. Enough that a more concerted and sustained effort must now be made which includes actions and not just gestures. But the imbroglio has not yet permanently damaged the company. People have long memories of their experiences with Instructure and personal relationships with employees who still work there.

    Update: Jeff Young just published a piece out about the data concerns in EdSurge. It includes quotes from Instructure’s chief spokesperson Cory Edwards, who I don’t know well but have found so far to be a good actor, and Melissa Loble, a long-time Instructure vet and current SVP for Customer Success, who is exactly the kind of person we should be hearing from directly more often. There’s even a quote from a Thoma Bravo representative. All were responding directly to the data use uproar. So this is progress. But still nothing from CEO Dan Goldsmith. Why EdSurge was able to get Instructure’s prospective PE owner on record but not its CEO, about a problem that was set off by a comment made by that CEO…it’s just mystifying.

    Education needs insight-providing, data-driven tools to help educators better serve a wider range of students who could succeed if only we were offering them the right kind of help. Furthermore, educational institutions need productive partnerships with the private sector to get these solutions out to as many students as possible as quickly as is possible and responsible. But this partnership can only take place in a high-trust environment. Instructure has had the necessary level of trust from their clients to do this kind of work. They have damaged that trust in this particular area. But not beyond repair. There is still a sound foundation, and any cracks still can be repointed.

    This brings me to Instructure’s most compelling product. It is not Canvas. Canvas has only been Instructure’s second-most compelling product.

    Brand, brand, brand

    Most people interpret “brand” as shorthand for a banal series of tactics employed by marketing departments. Academics, in particular, are inclined to load the word with distasteful connotations of shallow window dressing at best and obnoxious disingenuousness at worst.

    Nothing could be further from the truth. “Brand” is another word for reputation. It is who people think you are. It’s how much they trust that you are who you say you are. How much they trust you, period. Brand isn’t a series of tactics. It is the outward manifestation of the character of an organization or individual, as understood by people who have come to know them based on their actions over an extended period of time. Far from being a small set of eye-rolling marketing gimmicks executed by a small set of individuals, an organization’s brand is the gestalt impression that people get from every single interaction they have with every single member of that organization and every single product, website, or other touchpoint. That gestalt is “monetizable” to the extent that people trust the organization to understand their needs and have their interests at heart. They will give you their money if and when they believe they can trust you with it.

    Instructure’s brand has, until now, been its primary and best product. It is still one of the best in the sector, even if it is getting a little ragged around the edges. Because the brand is still good, the company can still build the relationships it needs to make good acquisitions, evangelize those acquisitions to its customers, and work with its customers on even the most sensitive (and important) product research and development efforts.

    That is what I hope for Instructure and why I have expended so much energy writing these last two blog posts. I want to live in a world where EdTech vendors are successful because their customers and partners believe in them. Instructure has been that kind of company. And it still could be.

    But back to the proof of the pudding. In this 21st-Century economy, as the saying now goes, if you’re not at the table, you’re on the menu. Instructure can recover, succeed, and thrive to the degree that the company’s leadership can reignite their customers’ faith that they have a seat at the table. Every decision they make, including financial transactions, should be judged by how it helps or hinders them from doing so.

  • Christensen Scorecard: Data visualization of US postsecondary institution closures and mergers

    Christensen Scorecard: Data visualization of US postsecondary institution closures and mergers

    In 2013, Harvard Business professor Clayton Christensen made a bold prediction based on his ubiquitous innovation theory that maybe half of all postsecondary institutions could close within 10-15 years.

    (source: https://youtu.be/KYVdf5xyD8I, starting at 6:25)

    The scary thing is that 15 years from now, maybe half of the universities will be in bankruptcy, including the state schools. But in the end, I’m excited to see that happen.

    Christensen then doubled down on his predictions in 2017, humorously saying it might take nine years instead of ten.

    (source: https://youtu.be/4ljlUOV-Uj4, starting at 1:04:42)

    Q. Do you still believe, as you’ve said before, that as many as half of colleges and universities will be bankrupt or closed within a decade?

    A. Um, yes. [snip] Whether the providers get disrupted within a decade — I might bet that it takes nine years rather than 10. Maybe I’m too scared about the Harvard Business School to be rational about it. But we should worry.

    There have been plenty of articles written about these claims, but it has been frustrating that very few back up their analysis with data. One exception is Derek Newton’s article critiquing the claims in Forbes, titled “No, Half Of All Colleges Will Not Go Bankrupt”.

    Look at the numbers. In the 2013-14 year, there were 3,122 four-year colleges according to the Department of Education. In 2017-18, the most recent data, there were 2,902 – a drop of about 7% over four years. That could be disruptive. But numerically, all of school closures since Christensen made his 2013 forecast were four-year, for-profit schools, which fell from 769 in 2013 to 499 in 2017 – a drop of 270. Of all the colleges, at all levels, that have closed since 2013, 95.5% of them were for-profit institutions.

    Another exception is Michael Horn’s explanation of the predictions (he co-authored the New York Times op-ed from 2013, titled “Innovation Imperative: Change Everything”, that included the initial prediction). This 2018 post “Will half of all colleges really close in the next decade?” also sought to go back to original, more nuanced claims of 25% closures and mergers at the Christensen Institute.

    Translation? Our predictions may be off, but they are directionally correct.

    To that I emphasize one more piece of nuance. Ultimately we are really predicting a failure rate, made up of a combination of closures, mergers or acquisitions, and bankruptcies in which a college or university has the opportunity to restructure itself. Not all universities that “fail” will disappear. [snip]

    From 2004–2014, “Closures among four-year public and private not-for-profit colleges averaged five per year from 2004-14, while mergers averaged two to three,” according to Moody’s. Moody’s predicted in 2015 that that closure rate—out of 2,300 institutions—would triple by 2017, and the merger rate would double.

    Assuming that were true, and say that the rate held steady for 15 years, that would take out roughly 13% of existing higher education institutions right there.

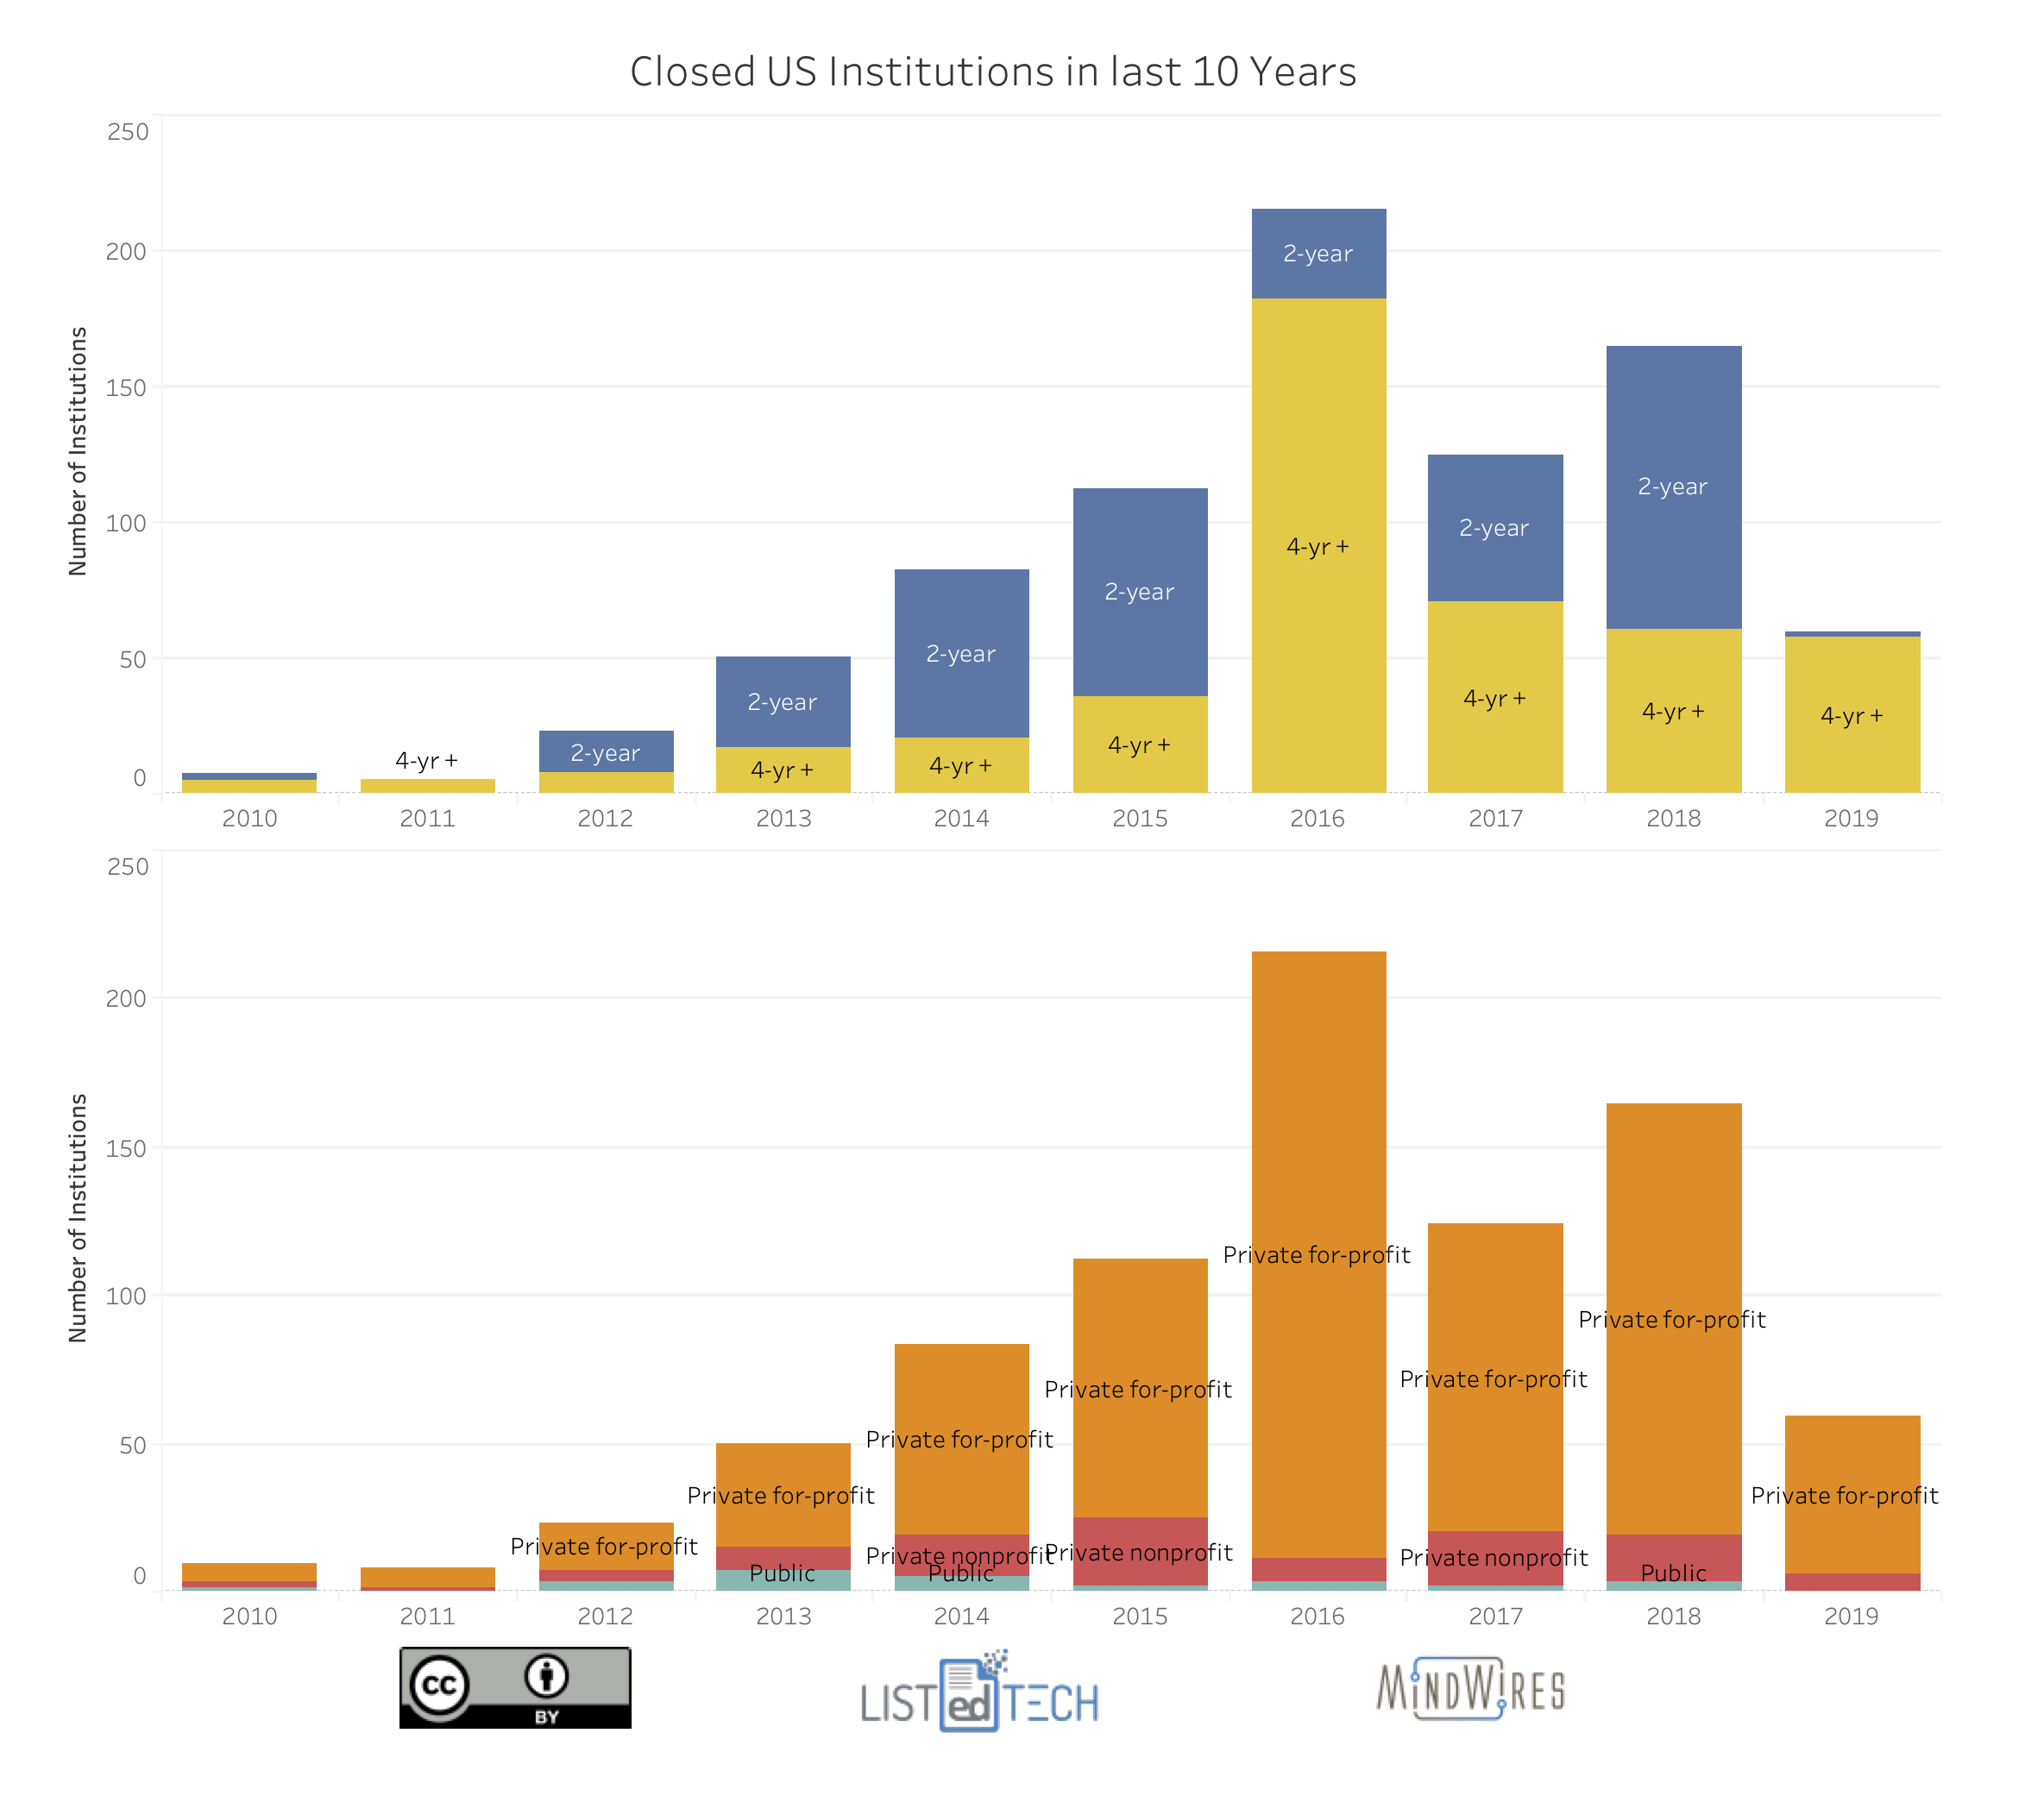
    Thanks to our partners with our LMS Market Analysis service, LISTedTECH, we can now provide data visualizations to better evaluate the validity or likelihood of these claims. For the first time that I’m aware of, we have visualizations showing combined closures and mergers over time, broken down by sector and degree-type, and showing data 2-3 years in advance of IPEDS publications.

    The LISTedTECH data shown below tracks known closures and mergers, which have then been checked against both IPEDS and Federal Student Aid data sets. There are translation issues in all three data sets, so the data will not match 100% – probably more at the 80 – 90% confidence level. The first view shows combined closures and mergers per year, broken out by control and whether they are classified as 2-year or 4-year degree-granting institutions.

    Closed US higher ed schools over past decade

    As Derek Newton and Michael Horn pointed out, the vast majority of closures were from the for-profit sectors. Part of the dynamic at play is that when a large for-profit chain meets its demise (e.g. Corinthian Colleges, ITT, Westwood Colleges) or has a massive downturn (e.g. University of Phoenix) literally dozens of individual institutions close, whereas when a small private nonprofit college in New England closes, it is one school. Add to the that the massive drop in for-profit enrollments since 2012.

    The public sector data in 2013 and 2014 is largely driven by reorganizations in the University System of Georgia.

    Also note that the 2019 data only includes the first quarter.

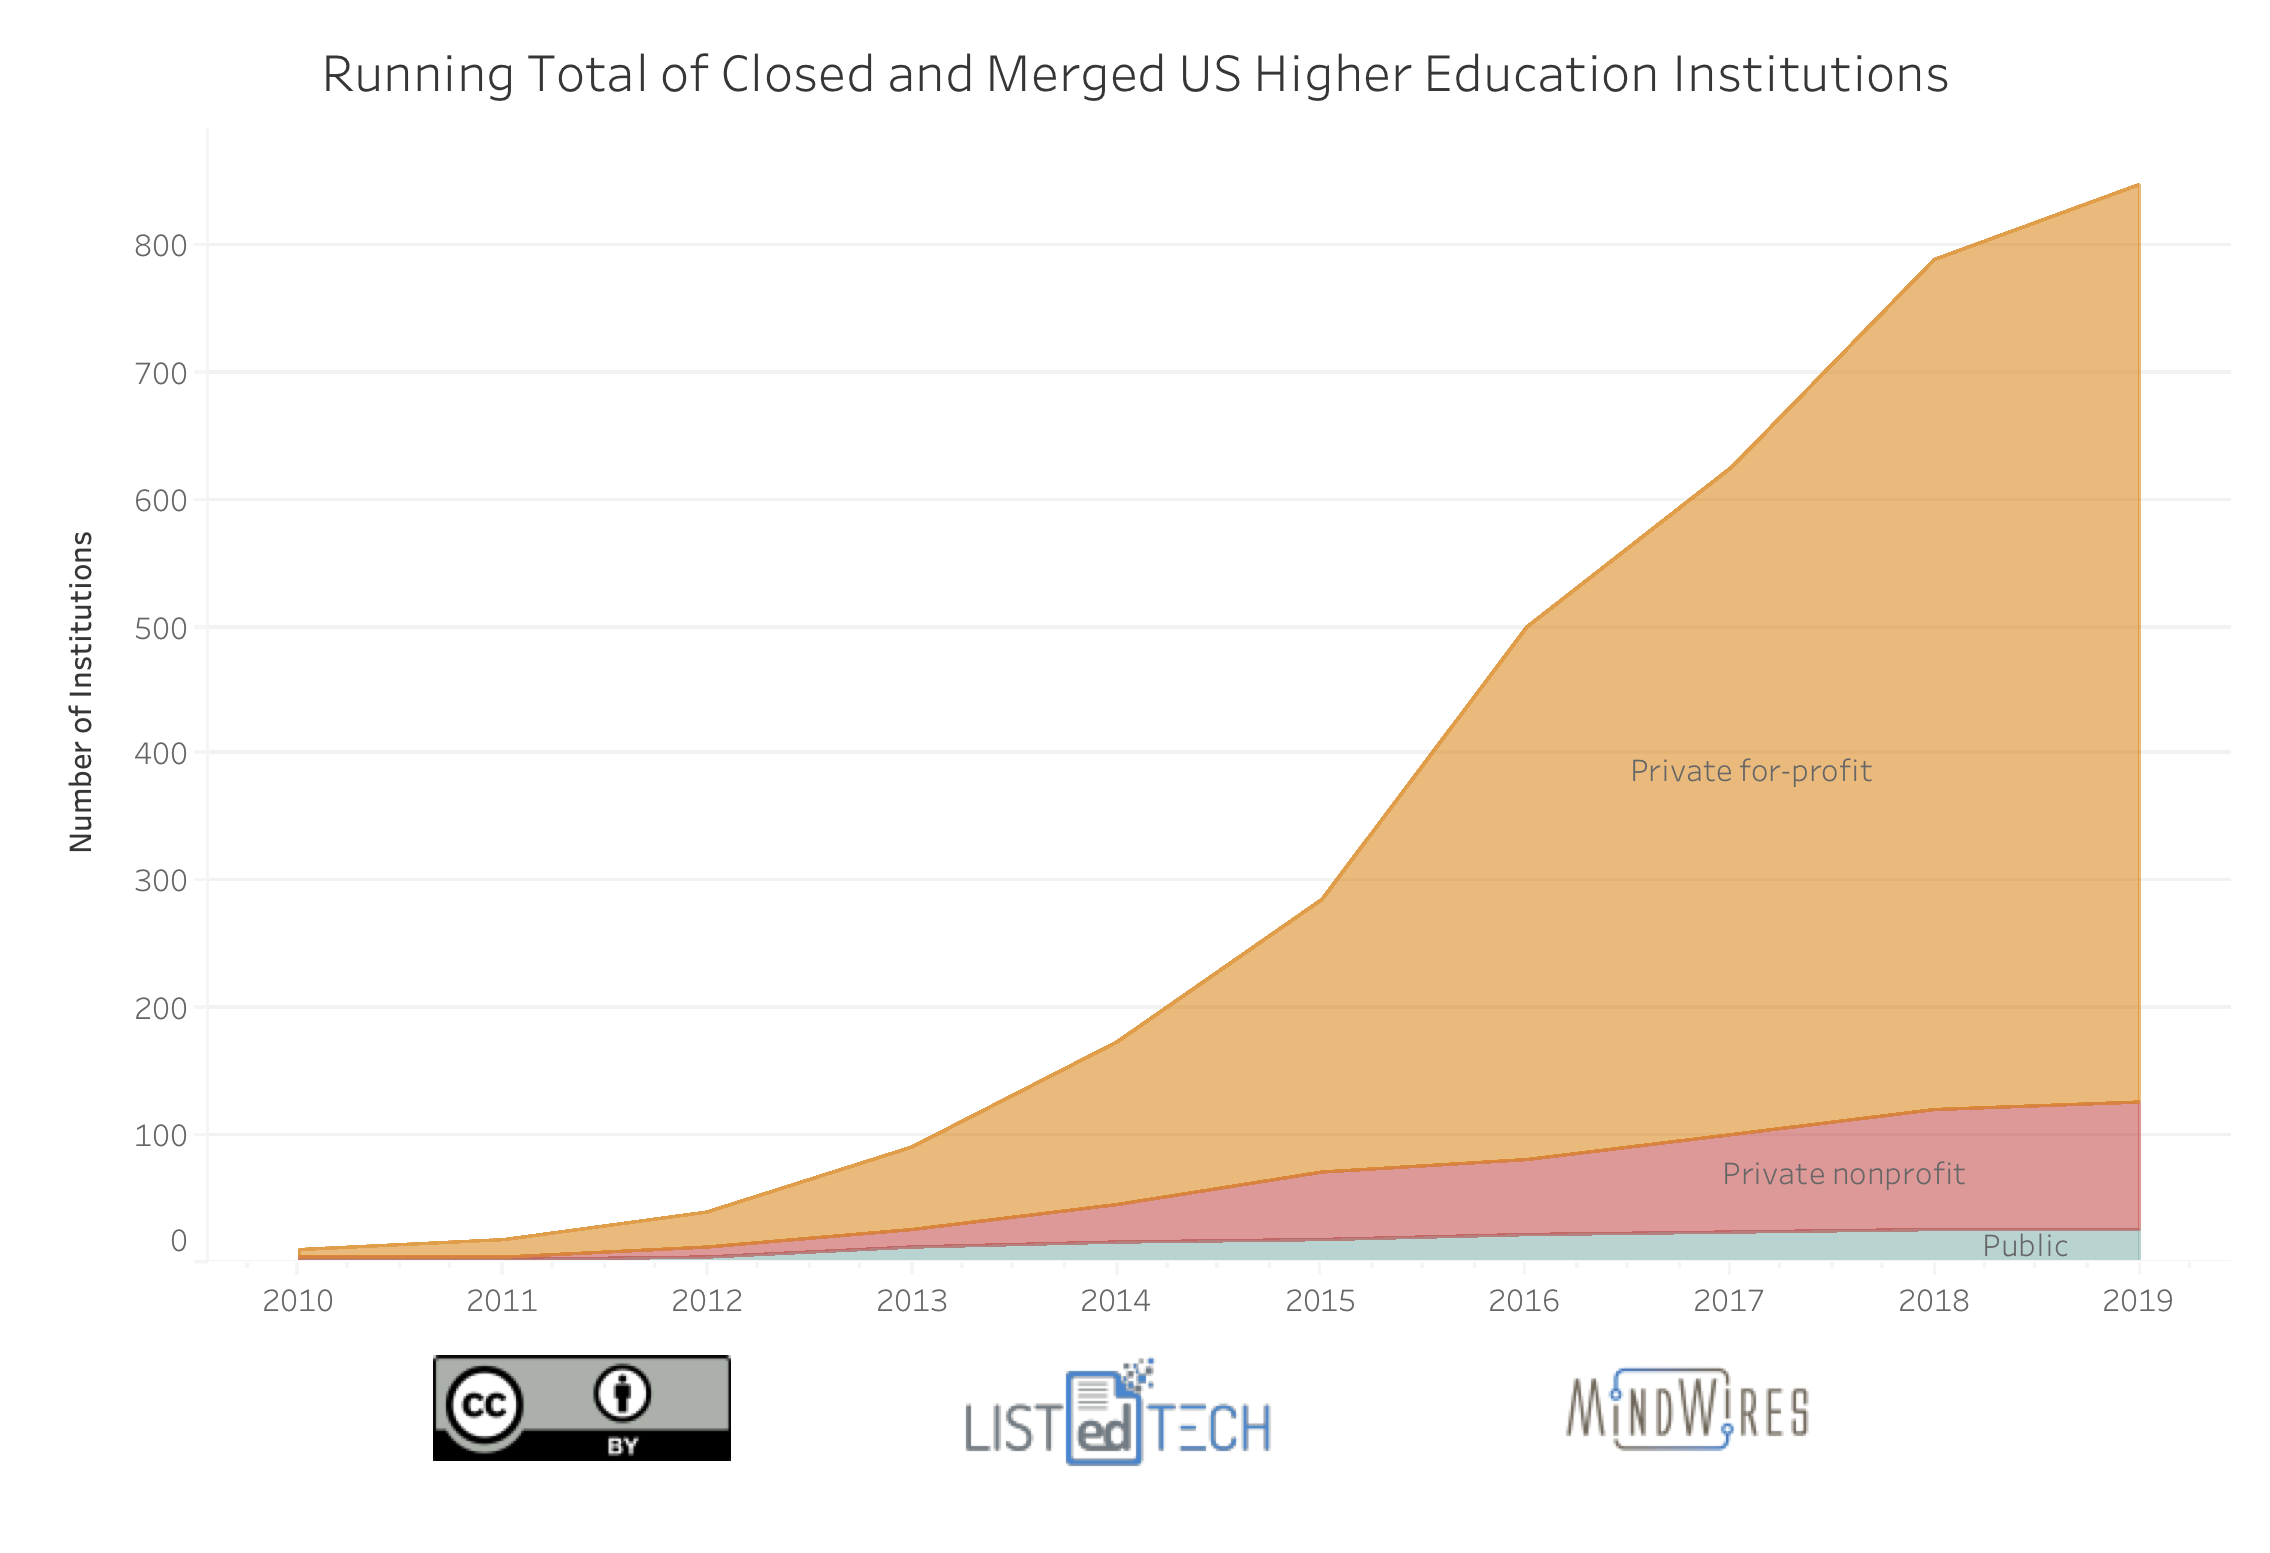
    If we want to track the Christensen (and Horn) predictions, however, we need to view this data as a running total.

    Running total of closed and merged US higher ed institutions

    Let’s zoom out to capture the timeline of the most recent predictions of a decade from 2017, and let’s add the rough levels indicated (using bold row from this IPEDS table to define number of institutions).

    Running total of closed US institutions with trend lines

    If you include all degree-granting institutions (i.e. for-profits as well as private nonprofits and publics), then the current trends lines show that the 50% closure prediction by 2027 certainly seems feasible. Note, however, is that there are less than 1,000 for-profit institutions remaining as of Fall 2017 IPEDS data, and the rate of for-profit closures cannot continue more than another 8-10 years (best case / worst case, take your pick).

    There are quite a few stories recently about private nonprofit small-school closures, but the data thus far don’t show a rapid acceleration of closures. Some perspective is useful here.

    If you ignore the for-profit sectors, then the trend line for private nonprofit and public institution closures + mergers remains far below that needed to hit the 25% level described by Horn or the 50% level described by Christensen. None of this is to say that the trends moving forward will be linear, however. The rate of private nonprofit and public closures and mergers would need to at least triple to hit the more conservative level of 25% within a decade, a possibility that I would not reject out of hand. And it turns out that Moody’s was wrong – the rate of closures and mergers in this group did not triple from 2015 – 2017. Nevertheless, the data could get worse.

    We’ll share more information on this new data, but hopefully these visualizations provide a better sense of the trends on college closures and mergers.

  • A Blackboard Debt Update, and a Lesson on Public Relations

    The short version of this story is that Blackboard has sold off their Transact business and moved their corporate headquarters out of Washington, DC. Both of these are sensible moves that give them an opportunity to reduce their debt load and get on better financial footing. Not being a debt expert with access to the information to the information that credit rating agencies have, I can’t comment at this point on how much this improves their outlook.

    That should be the sum total of this post. Unfortunately, because Blackboard handled some of our previous coverage poorly, the news also provides evidence that they weren’t entirely forthright with us in previous conversations about the tools they had at their disposal for handling their debt. So I’m obliged to complicate the news with an accountability story. Since I am weary of writing accountability stories after 14 years of writing them, I prefer to turn this story into a lesson about how ed tech companies can handle difficult PR situations better, in the hopes that I will have to write fewer of these stories in the future.

    If what you mainly care about is Blackboard’s financial health, then you can stop here. If you’re interested in learning more about how ed tech companies accidentally get themselves into unnecessary trouble, and how they can minimize their chances of doing so, then read on.

    Asking for Trouble

    Back in the summer of last year, I got into two consecutive spats with Blackboard, neither of which I saw coming. The first was about our data showing that Instructure Canvas had surpassed Blackboard in US market share. Now, everybody, including Blackboard, knew that those market share lines where moving closer together. Counting methodologies being complex and legitimately debatable, it’s possible to have honest disagreements about how close they are or whether they have crossed at any given moment. But we considered this more of a milestone that summed up a long-term trend than a big story in and of itself.

    There were a couple of ways that Blackboard could have handled this. One was to play it to the hilt. Being branded—pun intended—as the corporate juggernaut has been a problem for Blackboard for a long time. They could have finally turned the tables on Instructure and portrayed themselves as the scrappy underdog. Or they could have just kept quiet and let the story pass. It would have disappeared down the memory hole in about three days. Instead, they engaged in a strong public pushback against our numbers. That doesn’t make them bad people; they have a right to defend themselves as they see fit. But from a purely strategic perspective, their choice had the effect of both prolonging their bad news cycle and provoking responses from us.

    In one of those responses, I tried to explain—again—that the market share lines crossing really wasn’t news but rather a symbol of the ongoing trend. If you want real potential bad news for Blackboard, I argued—and this is where the danger of prolonging the bad news cycle caused further complications for them—you should look at their debt situation:

    The real issue of concern is the potential behavior of their debt and equity owners. I’ll come back to the point about Blackboard’s total product portfolio in that context….

    The second “Blackboard alert” article worth reading is the one by Katherine Doherty and Eliza Ronalds-Hannon at Bloomberg News. This one wasn’t a reaction to our piece but rather coincidental timing triggered by the same underlying concerns. I spoke with Doherty, whose beat includes companies with distressed debt.

    The debt is the real existential issue. Without it, Blackboard would just be a company that continues to struggle with its flagship product but which would have enough runway to turn itself around over time, one way or another. In the Bloomberg article, Blackboard CEO Bill Ballhaus repeats Miller’s reminder that the company sells other products and services. And as we have pointed out repeatedly here on e-Literate, the international markets are an increasingly large percentage of Blackboard’s financial picture. The fundamentals of the company may not be great, but they’re not dire either. Given time, good leadership, and low debt, a company in this position should be able to right itself.

    But because Blackboard has high debt, their situation potentially a lot more volatile. One major reason why the market share milestone matters is that it’s an apt metaphor for Blackboard’s financial waterline. At their current debt levels, the company can’t afford for their market share to continue to drop.

    Contract losses have sent Blackboard’s revenue and earnings sliding, according to people with knowledge of the matter, making it harder to carry more than $1.3 billion of rated debt. With some of Blackboard’s bonds selling at deeply distressed levels, Ballhaus is crafting a comeback, and possible options include the sale of its payment processing division, said the people, who asked not to be identified because the discussions are private.

    So, I wrote that Bloomberg news reported that Blackboard has debt levels that are high enough to cause potential problems for its business. Elsewhere, we reported that Moody’s had made some negative comments about their debt as well. Reporting these things is a little like reporting that the Weather Channel is predicting a high likelihood of heavy snow. It’s not something you argue about.

    I went on to say that, while the debt situation was serious for Blackboard, it was far from certain doom:

    Even in this situation, the results for Blackboard Learn customers won’t necessarily be bad, or even noticeable—depending on how the finances are resolved. If Blackboard sells off Transact, gets a good price for it, pays down some debt, and otherwise sticks with the current management’s plan, that could buy them some time and some ability to survive further erosion of market share around Learn. If the company’s owner, Providence Equity, decides to take more drastic steps, then the potential impact on customers is unpredictable. And Providence’s calculations regarding how much drastic action is required must be at least partly driven by their assessment of how close Blackboard is to bottoming out in LMS market share loss.

    This story was harder for the company to ignore, but they still had some options. I had said some good things about the company in that post, and some critical things about their competition. Their CEO, Bill Ballhaus, is a turnaround specialist. The Private Equity owners of Blackboard have signaled their trust in him by making him both Chairman and CEO. They had a good story line there. And they were going to have an option to engage with us in person very soon at BbWorld.

    So what strategy did they choose?

    Keep digging

    They pushed back hard. We had two meetings with Blackboard executives, including our meeting with Bill Ballhaus, in which they brought up the debt issue immediately and completely dismissed it as illegitimate. This was what poker players call a “tell.” It was so far out of the norm for this sort of analyst/executive meeting that it sent a clear signal of how concerned they were about the coverage. Now, some of that is simply due to the fact that people read what we write and react to it, and they don’t always read it carefully. So we know that Blackboard got inbound calls that were triggered by that post. But the tone of the pushback, coupled with the implausibility of the arguments, were highly inconsistent from our experience with this management team.

    This instantly changed the story line of BbWorld for us, and not in a way that Blackboard had intended. Here’s what I wrote in my follow-up post, entitled “Blackboard’s Defenses of Its Finances Are Not Persuasive,” about that meeting:

    When we were at BbWorld the week before last, Blackboard’s executive management pushed back vehemently on our analysis of how their high levels of debt could impact their business decisions. We heard their strong disagreement expressed in our very first meeting of the conference from Chief Learning and Innovation Officer Phill Miller and in our very last meeting from CEO Bill Ballhaus.

    We stand by our analysis. In fact, Blackboard’s pushback had the opposite of its intended effect. We left BbWorld more convinced that we are right rather than less….

    Ballhaus argued to us that the amount of debt that Blackboard is carrying is a strategic choice that he and the private equity investors—he used the pronoun “we”—make together. In particular, he argued, “we” could choose at any time to invest more money in the company, paying down debt in exchange for equity. Further, he argued, it’s logical to assume that Providence would do so if needed because “they only make their money if we improve.”…

    Paying down debt in exchange for equity, called “recapitalization,” is a strong vote of confidence by a private equity (PE) owner. First, since debt holders get paid before equity holders in the event of bankruptcy, it increases risk for the PE firm. Second, it would mean a substantial investment of cash, which is partly what PE firms typically try to minimize by requiring the companies that they own to take on substantial debt in the first place. When PE-owned companies find that they are in danger of being unable to make their debt payments—which both Moody’s and S&P Global Ratings have said is currently the case with Blackboard—the PE owners can and do employ a number of different strategies that are financially less risky to them in order to address the problem, either instead of or in addition to recapitalizing.

    For example, when Cengage Learning found itself with unmanageable debt levels after its acquisition by private equity, they filed for bankruptcy:

    “The decisive actions we are taking today will reduce our debt and improve our capital structure to support our long-term business strategy of transitioning from traditional print models to digital educational and research materials,” Michael Hansen, Cengage Learning’s chief executive, said in a statement.

    To be crystal clear, I am not suggesting that Blackboard is likely to file for bankruptcy. Providence Equity has other options at its disposal, some of which I will write about in the next section.

    Rather, the point is that Ballhaus’ claim that we should just assume Providence will see it as being in their interest to recapitalize Blackboard is not credible on its face to anybody with even passing knowledge of how private equity companies work. For example, the tone of the Washington Business Journal article I referenced above, which (obviously) was written by a business reporter, suggests significant skepticism that Providence will not let the company’s debt challenges impact their business decisions. The industry experts we typically consult with when writing financial or business stories like this one were even harsher in their evaluations of Blackboard’s position. Two literally laughed out loud at it.

    I’m pretty sure that wasn’t the coverage Blackboard was hoping for.

    And it was destined to get worse. Because they were now stuck in a trap of their own making.

    The Trap

    What do you do as an analyst when you believe a company has been making misleading statements to you and that there will be evidence supporting your theory of the case in the future? You lay down a marker and wait.

    Here’s what I wrote:

    [I]n fairness, there is an empirical fact of the matter here, and we do not yet have conclusive public evidence that the company’s high levels of debt will, in fact, affect their business strategy. So here’s what we’re going to do:

    1. I will summarize their position as objectively as I can.
    2. I will explain why we don’t find their position persuasive.
    3. I will lay out the signs that concrete evidence we will be looking for going forward that will either support or undermine our thesis.
    4. Phil and I will publish updates as we monitor these signs and, if there is no additional public evidence of our thesis by BbWorld 2019 (or strong evidence emerges that we are wrong before then), then we will publish a mea culpa post….

    Here are a few actions Blackboard could take in the future that would indicate Providence Equity has chosen to push Blackboard to solve its own debt problem rather than making it go away with more of Providence’s money:

    • Sell off one or more parts of the business: A Bloomberg piece written by journalists from their distressed debt desk reports, “With some of Blackboard’s bonds selling at deeply distressed levels, Ballhaus is crafting a comeback, and possible options include the sale of its payment processing division, said the people, who asked not to be identified because the discussions are private.” Said payment processing division, Blackboard Transact, is a cash cow for the company. If Blackboard sells off one of its more profitable business units at a time when the company is having trouble making debt payments, that would indicate a choice by Providence Equity to find a way to reduce debt pressure that is less risky for them in terms of cash investment but more risky for Blackboard in terms of long-term health. Particularly since Providence already tried to sell Blackboard once and has now owned the company for well past the normal sell-by date that PE companies like to follow, the sale of Transact might suggest further moves to follow.
    • Unload expenses (like office space): The Washington Business Journal article notes, “Blackboard is also interested in unloading its 70,000 square feet of office space at 1111 19th street, with 12,000 square feet already sublet, according to an April post on Tech Office Spaces. It’s unclear where Blackboard will go if it succeeds in leasing out its entire footprint. Blackboard stood to benefit from a tax rebate program for companies that agree to sign 50,000 square feet for at least a dozen years, valued at half the company’s tenant improvement costs, or a maximum of $5 million over five years.” Of course, companies take cost-cutting measures all the time, regardless of their financial health. The business reporter’s phrasing suggests that he may be detecting a whiff of desperation in the specifics of this transaction. Since that’s his expertise more than ours, we’ll be looking for additional confirmation of our thesis, such as if Blackboard were to…
    • Significantly restructure with major layoffs: If Blackboard were to move to a smaller office while also laying off employees—beyond those that might leave in a sale of a business division or the slow leak of headcount that the company has been having for a while now—that would certainly be an indicator that Providence is not ready to just give Blackboard the money the company needs to complete a turn-around and is instead pushing them to solve their own financial problems.

    I wrote that post on July 31st, 2018. Where are we seven and a half months later?

    Trap Sprung

    Last week, Blackboard announced the sale of Transact.

    Boom.

    Note that this is not an objectively bad thing for Blackboard. To the contrary, it helps them with their debt problem in a way that has little to no impact on their core customers. The problem is that it also runs against the grain of the story line that Blackboard executives pushed to us aggressively last summer. They turned what should have been a good story for them into a more complicated story.

    Also, last January, Blackboard announced they would be moving their headquarters out of Washington, DC to a new space in Reston, VA.

    Boom.

    Note that this is also not an objectively bad thing for Blackboard, also a way for them to manage their debt problem without impacting customers, and also in tension with the story they told us last year.

    The layoff evidence is less clear. There are plenty of comments on Glassdoor about ongoing layoffs (as well as voluntary talent drain) at the company, but that sort of evidence needs to be taken with a heaping teaspoon of salt. And honestly, I am hoping that I don’t see evidence of a major restructuring going forward. I never want to root for people to lose their jobs.

    So overall, there is pretty clear evidence that (a) all the debt agencies were not wrong when they said Blackboard had debt issues, (b) we were not wrong when we said that Blackboard could not expect Providence Equity to solve their problems by simply showering them with more money, and (c) Blackboard is taking necessary and reasonable steps to reduce their debt load. In other breaking news, gravity still exists.

    I let Blackboard know I would be writing an update to my previous post and gave Mr. Ballhaus an opportunity to revise and extend his previous remarks. Here’s what I got back:

    Our decision to divest in Transact is consistent with our strategic efforts to simplify our business as we move to a purely SaaS model and enhance focus on our core teaching and learning portfolio. The fact that we have tightened our strategic focus toward our current education clients and are accelerating innovation to benefit them is a stark contrast from our competitors who are looking to grow their business in areas outside of education.

    Proceeds of the sale will go toward deleveraging the company and also present potential opportunities to reinvest in the business.

    OK. This isn’t a bad statement as far as it goes. The last sentence is most directly relevant. The rest is stuff that he wants to get in, which is fine and expected. The truth is that he’s heavily constrained in what he can say about the debt management for legal and other reasons. As I said at the top, regarding the substance of the situation, I’m not a financial expert and do not have access to the information that debt agencies do, so I will wait for them to weigh in on how all of this affects Blackboard’s financial prognosis. It can’t be bad, but I’m not qualified to judge how much they’ve improved without the benefit of expert input.

    Regarding the PR situation, as far as I’m concerned, this was a fairly normal corporate answer. We’re back on terra firma. The more interesting question is how companies can avoid getting themselves into this situation in the first place. Blackboard is far from the only company that has gone through this sort of thing with us. And while we occasionally run into CEOs who are simply bad humans, usually these situations arise out of missteps that happen while the people at these companies are under enormous pressure because the companies are working their way through a rough patch. I have been on the inside of a company as an employee in that sort of a situation. It is not easy. External-facing leaders in particular need to cultivate reflexes to deal with these sorts of crisis situations. And make no mistake; an analyst or reporter raising uncomfortable questions about something your company is struggling with definitely feels like a crisis situation.

    So what’s the right reflex to cultivate?

    Honesty Works

    Executives need to understand the power of honesty as an offensive weapon. Set aside ethics for a moment. I’m talking about it from a purely strategic perspective. Let’s look at a couple of examples of how to play this card, starting with Blackboard.

    I made the analogy earlier between the debt agencies and the Weather Channel. Let’s extend that analogy a bit. I live in Massachusetts. It snows a lot up here. (Or at least, it used to.) But we have very professional road crews who know what they are doing. Most of the time, we can get a dumping of 18 inches at night and still drive on safe roads the next morning. We check the weather, but we don’t freak out about it. One way Mr. Ballhaus could have handled the debt conversation would have been to wait for us to bring the topic up—which we would have—and then say something analogous to the following:

    It’s true; the Weather Channel is predicting snow. I lived for ten years in rural Minnesota. In a house with a very long driveway. I have a truck with a snow plow on it. Here is my shovel. Any questions?

    Here’s how that looks in business terms:

    It’s true; the debt agencies are concerned about our debt load. That’s one reason why Providence Equity brought me in. I’m a Private Equity turn-around guy. This is pretty much what I do. You guys have been around the block enough to know that I can’t talk about the details of how we’re going to manage it, but we have strategies in place for strengthening the company’s balance sheet while protecting our customers.

    Every word of this is either undeniably true or reasonably plausible, and there’s not much we could have said in response. It also doesn’t make for much of a story. It becomes a “this is one of a number of factors that we’re watching” kind of thing. It doesn’t become the dominant story line coming out of BbWorld. And it softens the analysts up just a little bit. With a story like debt risk, there’s always a lot that we don’t know. The flavor of our coverage is influenced by our trust in management to be reasonably honest and open with us. In this context, a little bit of good will goes a long way.

    For another example, take the case where Pearson was trying to manage a story I was chasing of their CIO’s penchant for repeatedly talking about the company’s supposed ambition to build, in his words, the Netflix of education. I was (and still am) pretty sure that isn’t what Pearson is trying to do. But because this very high-level person continues to be allowed to publicly declare that they are trying to do this, and because Pearson is a big place where the right hand sometimes doesn’t know what the left hand is doing, only somebody who outranks the CIO can definitively put the question to rest. And there is only one person who outranks him: CEO John Fallon. After much discussion with Pearson’s PR team and some interviews with a couple of the CIO’s peers in other relevant parts of the organization, and very much to my surprise, I was given direct access to Pearson’s CEO. So here we go, I thought. This was going to be easy. He could put this story to bed, and I could spend my time writing a story about something good rather than something dumb.

    That’s not what happened. 

    But it so easily could have.

    Yeah, Pearson doesn’t want to be the Netflix of education, and Albert shouldn’t have said that we do. We do think that we need to become an internet-scale digital company, and we do think that the trend toward renting digital assets is one that is relevant to the educational market. That said, we understand that analogies are fraught in education and we don’t wish to oversimplify. In fact, we sold off our consumer businesses in part because we want supporting educators in managing those complexities to be the core of what we do. When we talk about efficacy, that’s what we mean.

    That answer not only would have spiked the “Pearson can’t stop talking about being the Netflix of education” story; it also would have turned me toward writing an update to my original efficacy story, complete with reporting on the genuinely good work the company’s efficacy team has been doing since then. The Netflix thing would have ended up getting mostly buried as a side note about how difficult and fraught it is for companies to talk about their work.

    It wouldn’t have mattered if I knew the answer was a strategic attempt to kill or divert the story. As long as it was honest, it would have been fair game. Beyond that, I would much rather write a story about a company that’s trying to do the right thing and does it imperfectly than play a game of gotcha with a company because the management is giving answers that I feel I have an obligation to police. When leadership chooses not to play the honesty card, they often accidentally trigger a gotcha game that generally doesn’t end well for them and puts them in a worse light than they actually deserve. I wanted to say definitively that Pearson isn’t trying to be the Netflix of education because I believe it to be true. I know they are doing good work because I have seen it with my own eyes. I could have written a story about that. But because Mr. Fallon chose not to play the honesty card, the story ended up being about Pearson failing to clearly disavow the Netflix analogy, and I couldn’t definitively write what I believe to be true about the company because Mr. Fallon didn’t give me the proof that I needed for the story.

    I could go on; I have many more examples like these. A positive one is when Instructure’s former CEO Josh Coates completely transformed a negative story about the company charging customers for access to their own data. Not only did he admit that the company screwed up in very blunt terms; he changed the policy, encouraged us to call customers and verify that they were satisfied with the changes, and thanked Phil for calling his attention to the problem. There are reasons why we wrote very little negative coverage of Instructure during the Coates years. One is that the leadership team really understood the power of honesty.

    The bottom line is that honesty is disarming. Good analysts always try to maintain healthy skepticism, but they also try to be good judges of character. Because good analysis is partly based on knowing how much you trust the particular version of events that a company’s management is giving you. In contrast, when leaders give in to the (understandable) temptation to deflect, they look dishonest. I want to be very clear about separating a moment of failing to be honest, which we all have had under pressure from time to time, from being a fundamentally dishonest person, of which I have met relatively few in my life. Analysts (and reporters) have to distinguish between the two based on very little information, and they have the obligation to be skeptical. Also, good analysts have instincts that lead them to poke where it hurts. The reflex of the person being poked will be to protect the sore spot. Effective leaders learn to fight that reflex in the moment. They acknowledge problems that the analyst may have uncovered (to the degree that they can) and turn that moment of vulnerability into an opportunity.

  • Instructure: Plans to expand beyond Canvas LMS into machine learning and AI

    Instructure: Plans to expand beyond Canvas LMS into machine learning and AI

    It’s common knowledge that Instructure has shifted its focus to place more emphasis on its growth in corporate learning markets than in the educational markets that have fueled the company growth to date. We covered the initial news about their introduction of the corporate learning LMS, Bridge, four years ago.

    While Instructure has excelled on maintaining product focus and simplicity of user experience, this move outside of education raises the question about whether they can maintain company focus. The corporate market is very different than the education market – different product needs, fragmented vendor market, different buying patterns. Many companies have tried to cross over between education and corporate learning, but most have failed. Blackboard, D2L and Moodle have made a footprint in the corporate space using one product for both markets. Instructure’s approach is different.

    As noted, the other Big Four LMS vendors are also targeting corporate learning (or professional ed, or workplace, pick your name). D2L and Blackboard are using the same platforms in both markets (Brightspace for D2L, Learn and Open LMS for Blackboard), while Moodle released Workplace, a set of plugins on top of core Moodle. Instructure, however, has different products for educational and corporate markets.

    That is old news. What is more interesting is to understand Instructure’s emerging strategy given the new executive team. Thanks to the nature of Instructure being a publicly-traded company, we are getting more insight that should set expectations for educational customers. As CEO Dan Goldsmith said during an investor conference a week ago:

    We really changed the company, as I came in nine months ago and then took over as CEO January 1st of this year. We’re initiating the second chapter in the journey of Instructure.

    I should first note that the audience for these calls is the investment community, so naturally Instructure executives focused more on financial performance and projections that they would in academic meetings. But there is a lot to learn here.

    In some ways, the changes to operations of Instructure are welcome and are already helping them manage corporate finances. In other ways, however, that second chapter reads a lot like Blackboard. Moving beyond the LMS, willing to bet on corporate acquisition, expecting big focus on data and analytics, and continuing challenges in completing products.

    Operational Improvements

    One of the ongoing criticisms of Instructure, particularly by their competitors, is that they continue to lose money and are buying growth. While these observations are accurate, as long as Instructure keeps growing, they have never been at risk of running out of money or having their losses significantly impact their operations. Under the new leadership, Instructure has been much more aggressive in managing expenses, with a big milestone described on the conference call by CFO Steve Kaminsky [emphasis added].

    Turning to the expense side. With our focus on operational excellence during the second half of 2018, we’ve changed the mindset of our leadership team and the entire organization about how we approach the business and fund investment. We focused on disciplined investments for balancing profitable growth has been put in place and is reflected in the outlook we provided today. On the cash side, we have a strong cash position to support our important strategic objectives for both Canvas and Bridge. And looking forward to 2019, we anticipate being approximately free cash flow neutral for the full year.

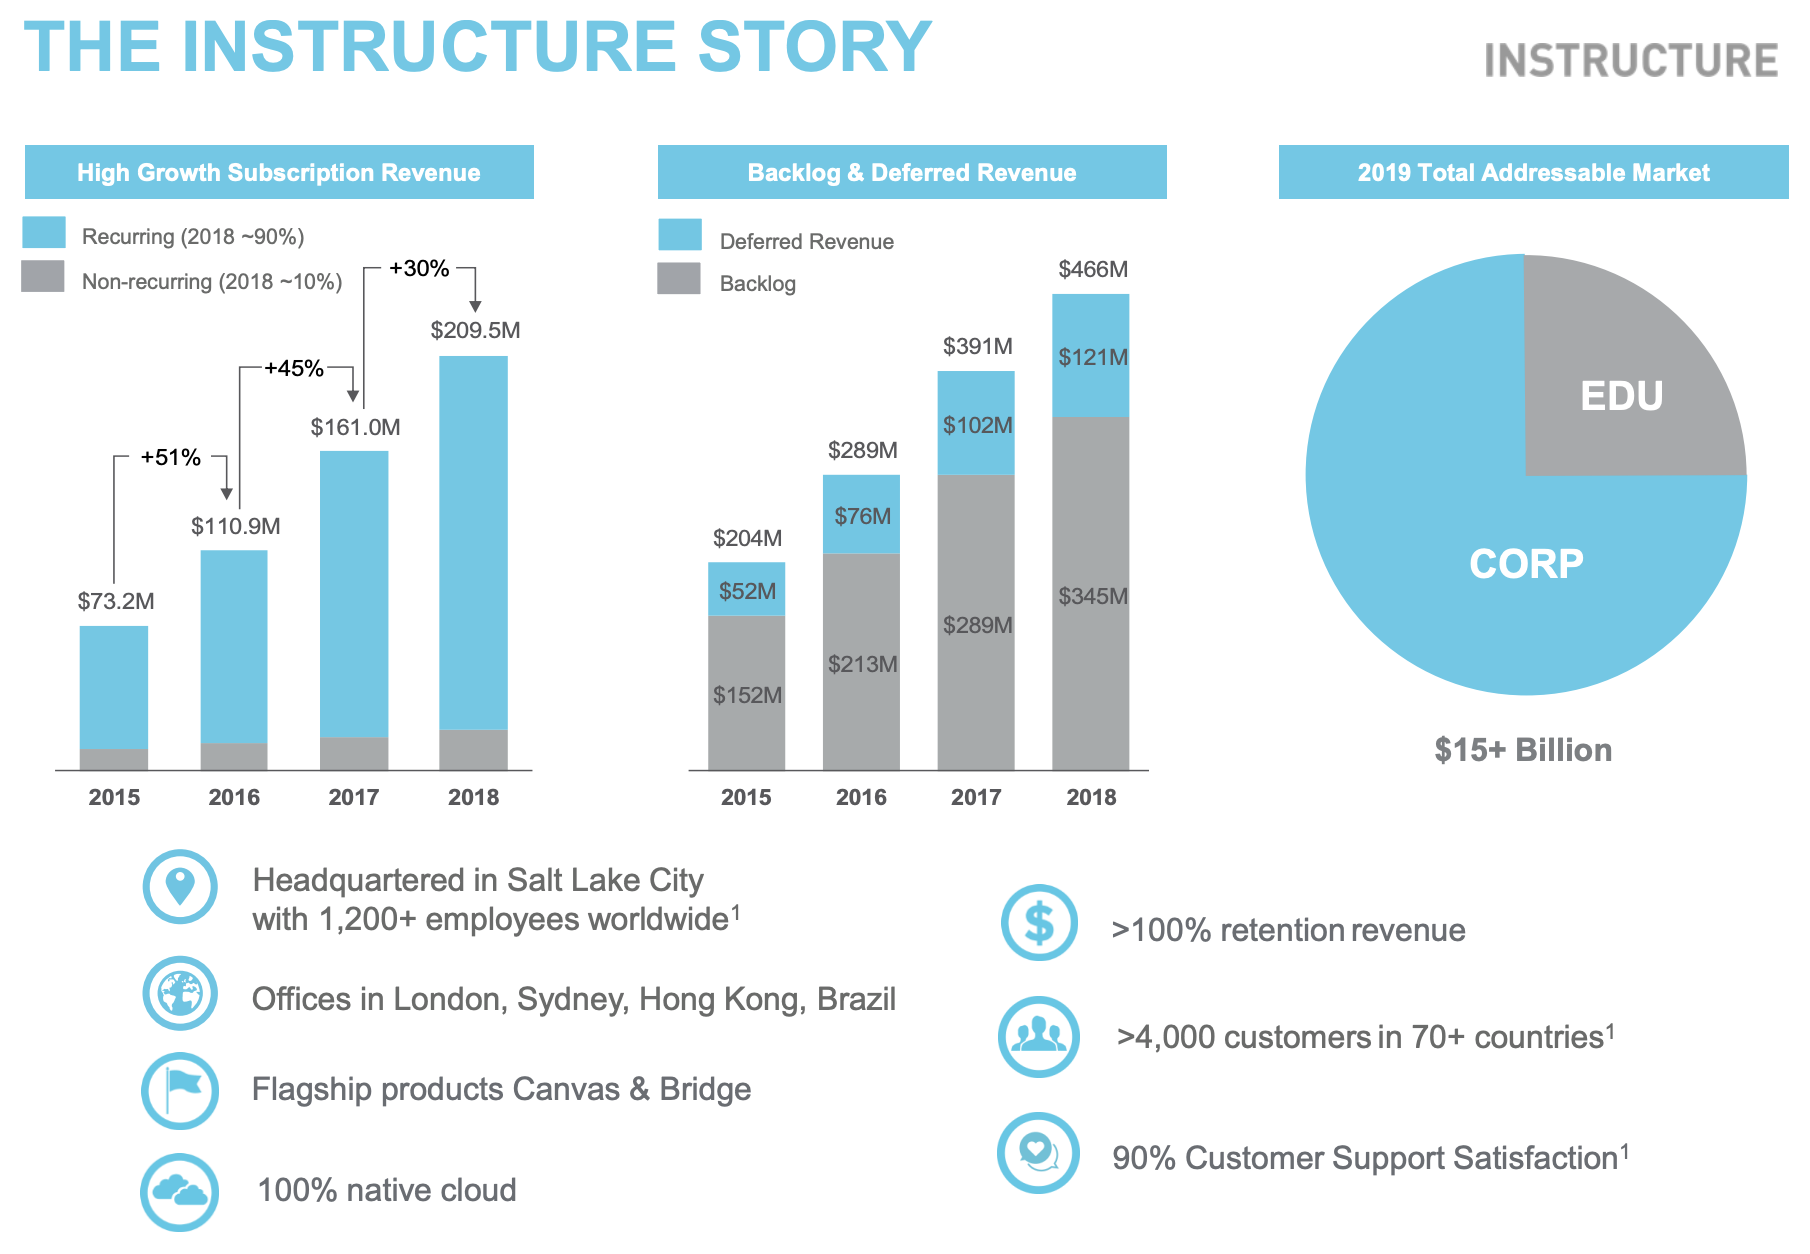
    Beyond simple finances, we have seen some operational changes for international operations as well. The global regions (EMEA, Latin America, APAC) all have more autonomy now, including control over country-specific marketing and product management. The non-US operations have moved beyond being regional sales and support offices into more aggressive engines of growth. In Europe and other regions, the management team has more autonomy is deciding which countries are worth investment for expanding markets, and when. From the Feb 25th investor presentation:

    The Instructure Story

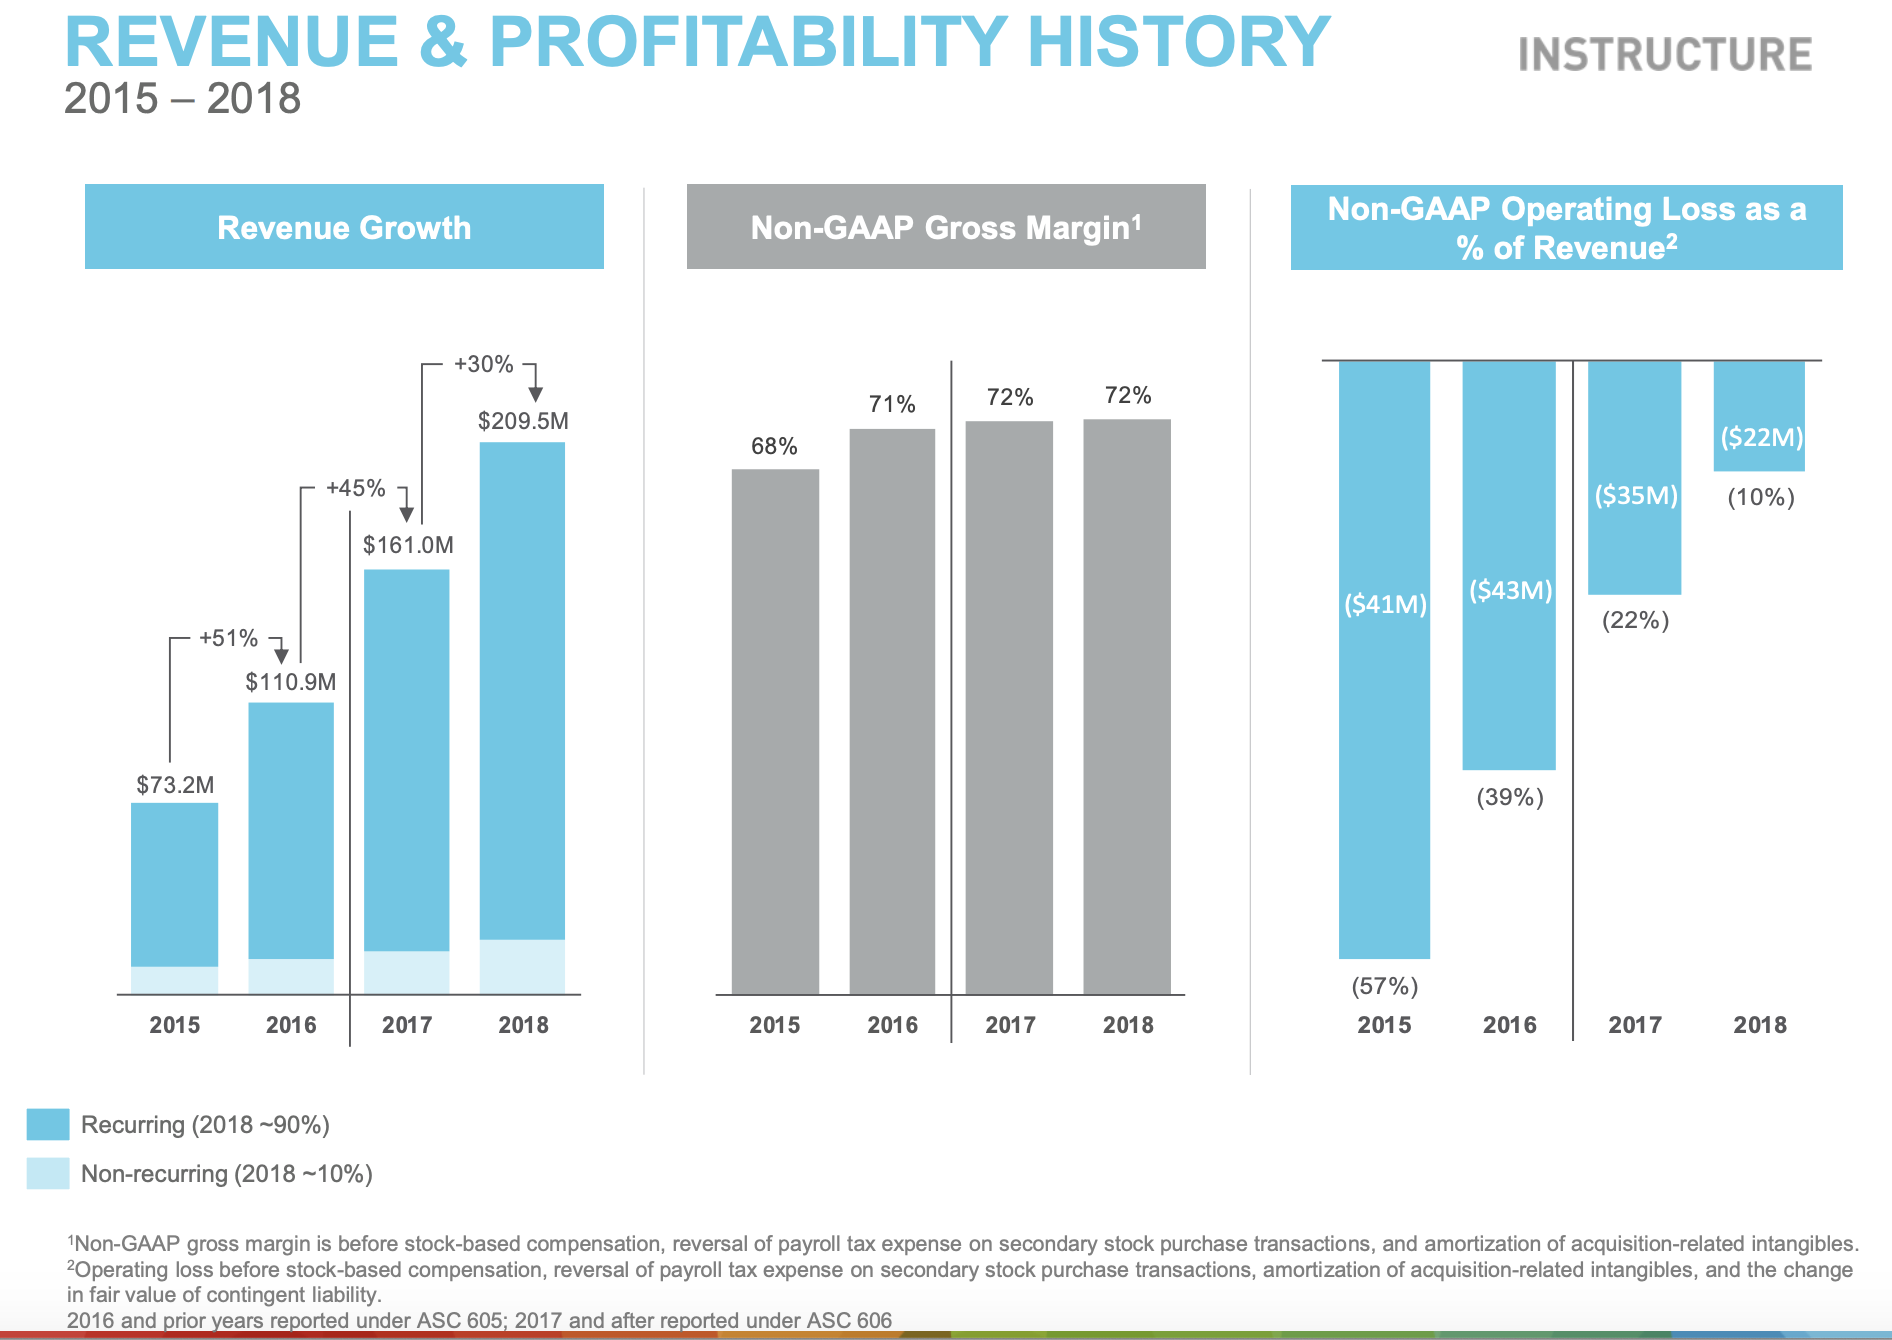
    With the improving operations, Instructure has reduced their operating losses from 57% of revenue to 10% of revenue in the past three years.

    Investor conference slide

    Moving Beyond the LMS

    On the same day as Instructure’s earnings call and release of FY2018 financial results, the company announced the acquisition of Portfolium for $43 million, a small startup focusing on “ePortfolio network, student-centered assessment, job matching capabilities, and academic and co-curricular pathways”. We interviewed Instructure staff the same day as the earnings call and noted a different message. In our initial call, the Portfolium acquisition was positioned primarily as a way to improve how Instructure can handle structured assessments in the education market – think CBE, mastery learning, with ePortfolios not as the goal but as the necessary infrastructure. During the earnings call, however, the positioning was more about bridging educational and corporate markets and expanding total addressable market (TAM).

    Today, we’ve taken a great stride towards enabling that transition with our expected acquisition of Portfolium, a successful long time Canvas partner. Portfolium vision is to help each person realize their full potential by connecting learning with opportunity, through e-portfolios, program and course level assessments, career pathways and by matching students to job opportunities. Portfolium will join Instructure with a wealth of shared customers, such as Virginia Tech, Santa Clara University and Swinburne University in Australia. This acquisition is a great match in vision and culture and represents our first major step into the Student Success market. And while Portfolium’s current offerings provide an excellent solution, more importantly, they establish the first Bridge between academia and the corporate world that aligns precisely with Instructure’s vision.

    Instructure now views itself as a company with a suite of products, and they are much more open to using corporate M&A to build this portfolio.

    Emphasis on Data & Analytics

    The second initiative announced on the earnings call was DIG, a strategic move with data and analytics.

    I am also pleased to share with you an early insight into our second growth initiative focused on analytics, data science and artificial intelligence. The code name for this initiative is DIG. And this technology platform combined with the most comprehensive SaaS database on the educational experience uniquely positions us to deliver meaningful value to our customers. And from a growth perspective, DIG has the potential to double our TAM in education.

    Instructure started ramping up their data and analytics efforts (again) about a year ago, although the focus was described at the time as being about internal analytics – that is, making Canvas a better and more valuable LMS product. From what I have heard the product validation for DIG are consistent with this message – dashboards, surfacing useful data within a workflow, etc. But that was not how DIG is being sold during the conference call [emphasis added].

    We’ve been working on the scaffolding for [DIG] for well over a year now. I mentioned in our remarks that we already have product validation towards out there in the market. We have instructors and students consuming output from some of the initial experiments with DIG. And we anticipate later this year obviously to make more announcements around specific products and offerings and how we bring them into the market. DIG ultimately is a platform first and foremost based upon machine learning and artificial intelligence. I believe that any multi tenant SaaS company born in the cloud has the opportunity once they hit a certain market share. And in fact, it may even be incumbent upon those organizations to partner with the industry and evolve that industry with new insights and predictive modeling using AI and ML. That’s what DIG is at its heart.

    This is brand new behavior for Instructure as a company. Previously the company was reticent to talk much about non-released products, but now they are talking not just about a new initiative, they are touting buzzwordy machine learning and artificial intelligence and predictive modeling well before any of those capabilities exist or are in customer hands. Goldsmith further clarified the DIG plans during the investor conference discussion [starting at 9:00, emphasis added].

    We already have analytical capabilities in our Canvas platform. I want to be really clear and delineate the difference between an analytics and reporting capability, and a machine learning and AI platform. [snip]

    We have the most comprehensive database on the educational experience in the globe. So given that information that we have, no one else has those data assets at their fingertips to be able to develop those algorithms and predictive models.

    Goldsmith then described an example of predicting a student’s expected performance in a class and how that prediction reliability goes up over time. Then we get the vision.

    What’s even more interesting and compelling is that we can take that information, correlate it across all sorts of universities, curricula, etc, and we can start making recommendations and suggestions to the student or instructor in how they can be more successful. Watch this video, read this passage, do problems 17-34 in this textbook, spend an extra two hours on this or that. When we drive student success, we impact things like retention, we impact the productivity of the teachers, and it’s a huge opportunity. That’s just one small example.

    Our DIG initiative, it is first and foremost a platform for ML and AI, and we will deliver and monetize it by offering different functional domains of predictive algorithms and insights. Maybe things like student success, retention, coaching and advising, career pathing, as well as a number of the other metrics that will help improve the value of an institution or connectivity across institutions. [snip]

    We’ve gone through enough cycles thus far to have demonstrable results around improving outcomes with students and improving student success. [snip] I hope to have something at least in beta by the end of this year.

    Wow. Robot tutor in the sky – meet the new kid on the block.

    The most generous interpretation I have is that they are being sloppy in their terminology and casually throwing out machine learning and AI to eager investors, while the reality could be more mundane but useful sharing of useful data to help instructors or administrators.

    If I had to guess, however, I would suggest that Instructure has its sights set on additional corporate acquisitions over the next year or two to try and back up these expectations. I hope they realize they are not the first company to believe that AI on top of their best-in-world data will deliver success for all.

    The message is also clear that Portfolium and DIG are intended to increase TAM. This means separate product categories with separate pricing in addition to Canvas. Either that or offering Canvas at different pricing levels to include add-on product bundles.

    Challenges in Completing Products

    We noted the modernization efforts behind Quizzes.Next, the next generation quizzing and test engine for Canvas, as well as the big schedule miss. In short, Quizzes.Next was announced at InstructureCon 2016 as being available within a few months. 12 months later at InstructureCon 2017 it entered limited beta, and at InstructureCon 2018 it entered general availability. But the story is not over. Quizzes.Next is still not at feature parity with the original quiz engine, as noted by Indiana University.

    Instructure has released a new quizzing tool for Canvas called Quizzes.Next. Quizzes.Next offers several new features and question types, but is missing many features from the current Quizzes tool on which many instructors depend. Both tools will continue to be available until Quizzes.Next has achieved feature parity with Canvas Quizzes. The original Canvas Quizzes tool will eventually be retired, but Instructure has not yet announced the timeline.

    If you read the Canvas Community page comparing features, it is clear that feature parity is not imminent. The transparency is impressive, however, and from what we are hearing customers are still giving Instructure some leeway because of trust. But Quizzes.Next and its delivery is a continuing problem, not least of which is the reduction in R&D spending growth for Canvas, described by CFO Steve Kaminsky on the call.

    Regarding the R&D investment, we don’t really break that out. But what we can tell you qualitatively is while we are doing some incremental investments on the Canvas side and DIG is a good example of that, the lion share of the growth in R&D is going into Bridge.

    What to Expect

    Instructure is at a crossroads. While they continue to grow, especially in education markets, and while they report improving financial performance, Instructure is entering uncharted territory (for them) in this second chapter. It is remarkable that they have not lost a major educational LMS customer in the 8+ years since Canvas was first selected by the Utah Education Network, but there are some warning signs that should not be ignored and some risky expectations being set.

  • Moodle Workplace: A new product and change in open source deployment

    Moodle Workplace: A new product and change in open source deployment

    Moodle unveiled its new product, Moodle Workplace, at the the Learning Technologies conference in London three weeks ago. While the open source Moodle LMS has been used by companies and organizations for employee training for years (approximately 40% of Moodle implementations worldwide according to this 2015 interview), Workplace represents a new approach for Moodle’s usage of open source deployment.

    Moodle Workplace

    Based on an email interview with Moodle Pty Ltd (aka Moodle HQ) CEO and founder Martin Dougiamas, Moodle Workplace is a “a series of well-written plugins that sit cleanly on top of the standard core distribution” and is being released under an open source GPL license. The plugins add functionality to:

    • Create training paths;
    • Create departmental structures and reporting;
    • Automate enrollment, certificates and other back end processes; and
    • Customize reporting and report delivery.

    From first reading, the Workplace functionality is a subset of the features available in other products, notably Totara Learning. That solution is also based on Moodle core, although Totara forked its code base more than three years ago. ((At the time of the fork, Totara management also predicted Moodle was planning to offer the market ‘Moodle for Workplace’.)) Workplace appears to be a solid, if somewhat unremarkable platform for organizational training delivery which can provide compliance tracking, learning pathways, and other business-focused features. For organizations looking to add training features to existing stock Moodle, Workplace should offer an easier migration path than Totara.

    The bigger news is the change in the distribution and business model as described by Dougiamas.

    We are restricting distribution to Moodle Partners for now so that we can give more value back to our Moodle Partners who invested time and money into it.

    Similar to Totara’s business model, there are limitations put on the Moodle Partners to prevent modification or distribution of the code. By providing Workplace only as a SaaS solution, Moodle is using the same distribution loophole in the GPL. ((For those unfamiliar with the peculiarities of open source licensing, Moodle and Workplace are released under the General Public License (GPL). The GPL requirement to release the source code ONLY applies if you are providing someone a copy of the binary. Providing software as a service does not constitute “distribution” under the GPL. This is how Google, Amazon, Facebook and all the other major internet players can build on open source, but not release their source code.)) The upshot is that if a company or organization wants to use Moodle Workplace, they have to work through a Moodle Partner and cannot download and install the software for free.

    The business model around Moodle Workplace is clearly a departure from the norm for Moodle, where the core GPL code is available to anyone, anytime, for free. But it is not clear whether this change in model for Workplace is a limited play or has broader applications that may impact education markets. In our interview, Dougiamas directly addressed our question on whether we should expect similar changes to Moodle core:

    No, we remain intensely committed to developing and improving Moodle core as a GPL product with the same license, open source practices and active community as now.

    He further stated:

    Our team developing Workplace have been contributing features (the more general ones) into core at the same time, and the plan is that any Workplace features that also supports sectors like Higher Ed or schools will always be migrated into core this way.

    So, what are educational institutions to make of the new business model around Moodle Workplace? We’re not entirely sure at this point. At a minimum, it would appear to be an attempt to better monetize the large installed base – a move to satisfy investors and to replace the Blackboard revenue after cancellation of their Moodle Partner agreement. At a more strategic level, it could be an attempt to stay competitive with peers, particularly SumTotal and Totara, who are going after the corporate learning space.

    If Workplace is successful, it will create a new revenue stream for Moodle HQ, potentially accelerating the development of the core educational product. A Moodle Partner we interviewed for this piece claimed they were already seeing increased lead generation from the announcement. The small and medium business (SMB) market is larger and generally has faster sales cycles than the education market, which could drive partner revenue and cash flows. The partners who are able to create sales momentum in both spaces and find their product / market niche are likely to see some accelerated growth. If this is successful, Moodle HQ should capture additional revenue and accelerate the product and service roadmap. This move directly addresses the issue Michael raised in the Fall about the termination of the Blackboard contract and revenue stream.

    For Moodle, everything rides on their ability to grow alternative sources of revenue. The company has been touting newer offerings such as MoodleCloud, MoodleNet, LearnMoodle, and MoodleServices. Since we don’t have any external evidence that these are material sources of revenue for the company, and since the company itself has not shared numbers that we can independently evaluate, it’s very hard to tell what their chances are. Moodle has a huge installed base, which gives the project a lot of momentum. But the company that drives most of the core platform development has a business model that has not aged well and is in the process of diversifying into business models that are as yet unproven. I remember enough physics to know that momentum and acceleration are not the same thing. I think the risks are probably greater for Moodle Pty. than they are for Blackboard. But both sides of the equation bear watching.

    Moodle Workplace as a monetization strategy seems to be a stronger bet than the previous offerings.

    The risk for education institutions, however, is that the Workplace development roadmap pulls resources from making investments in core Moodle necessary to keep pace with better-funded rivals. At worst case, Workplace fails to find a market niche and position itself in a crowded field. The opportunity cost of investing in Workplace vs other potential investments in the core education product and cloud services could end up having larger knock on effects downstream.

    What we have observed over the past 6 – 9 months is an increased customer focus by Moodle HQ, acknowledging the importance of market messaging (e.g. first-time presence at EDUCAUSE, announcing Workplace at London conference) and better understanding and satisfying business needs of revenue-generating Moodle Partners. The jury is still out on how these changes will impact financial sustainability and competitiveness of Moodle in education markets, but there is little doubt that there are changes in behavior.

    In the end, this is another example of corporate financial health issues having an outsized impact on the LMS market in 2018 – 2019. And one that bears watching, coming from the LMS provider with the world’s largest installed base.

    Update 3/6: Changed naming throughout to Moodle HQ instead of Moodle Pty to reflect more accurate and common usage. Also edited footnote about ‘Moodle for Workplace’ prediction to remove the implication of Moodle Workplace being a copy of Totara code.

  • Blackboard Updates: Learn SaaS progress and LMS market news

    Blackboard Updates: Learn SaaS progress and LMS market news

    Blackboard had a lot of news to share two weeks ago when we spoke with CEO Bill Ballhaus and senior teaching and learning executives. The updates addressed efforts to streamline the business, customer retention, and customer acquisition. Blackboard ((Disclosure: Blackboard is a subscriber to our LMS Market Analysis service.)) was upbeat about their current position and prospects going forward, but we see a mixed picture.

    Ballhaus said that Blackboard’s efforts to simplify the business were paying off and leading to greater focus on their core teaching and learning businesses. While the company was built as an enterprise software amalgamation based on 20+ corporate acquisitions, Ballhaus described how management is looking forward to becoming a Software as a Service (SaaS) business with a simpler focus. While the executives declined to comment on current M&A activity, Blackboard appears to be trying to sell its CashNet and Transact products that are part of the same business line focused on campus ID and payment processing, for up to $800 million and $720 million respectively ((Although it is possible that both of these reports are referring to the same combined transaction – CashNet and Transact together. This explanation makes more sense to me.)). Remembering that Blackboard reportedly tried but failed to sell the entire company for ~$3 billion in 2015, there is no guarantee that they will actually sell either unit or get the desired prices. [Update 3/7: Blackboard did end up selling entire Transact business unit , including CashNet, to PE firm Reverence Capital for a reported $720m.] But if they do succeed, the profits from either sale will help the company pay down and manage its debt. And it will back up the claims of focusing the company on core teaching and learning business.

    The claim of the company looking forward to being a pure-SaaS business is largely based on their ability to migrate the flagship Learn LMS client base over to the AWS-enabled Learn SaaS offering. Blackboard leadership believes that the ongoing migrating effort has been a critical factor in improving their customer retention numbers, an argument that we made last summer.

    The third issue, which is related to the first two, is that we believe that the migration to Learn SaaS might be a better indicator – at least in the short run – than Ultra adoption of whether a school plans to stick with Blackboard. Whether or not the school enables Ultra base navigation or any courses in the Ultra Experience.

    When a school moves to Learn SaaS, they tend to sign contract extensions for 1 – 3 years to cover the new services. And the migration to Learn SaaS does not suffer from the vague terminology issues – a school either uses Learn deployed on SaaS (through AWS) or they don’t.

    Ballhaus went so far as to say that Blackboard’s improvements in client retention was the primary factor in the overall market slowdown last year. While we certainly feel that Blackboard has benefited from the slowdown and has improved client retention lately, we are not convinced on the cause and effect dynamics. By tracking the public proclamations of Learn SaaS adoptions, we see an interesting linear trend leading to the current ~25% of Learn clients being on SaaS.

    Learn SaaS Adoptions Over Time

    Blackboard continued to present the importance of their broad product portfolio combined with their experience. Ballhaus stressed that the LMS is necessary but not sufficient as a strategy for the company. Blackboard management sees Blackboard at an inflection point in 2019 in a good way, and they stressed that their big focus will now be on data and analytics offerings. Remember this paragraph when we get to the Instructure update post.

    Early in February Blackboard announced what could be their biggest LMS win since we broke the news of University of Phoenix selecting Blackboard Learn Ultra in late 2015 (a migration that is scheduled to be complete by this summer). From the press release about Galileo Global and their 100,000+ student system:

    Blackboard today announced that Galileo Global Education, a leading international provider of higher education and Europe’s largest higher education group, will roll out Blackboard Learn with the Ultra experience as the common Learning Management System (LMS) for its network of 37 schools with 80 campuses across 10 countries. Blackboard Learn Ultra was selected over other cloud-based solutions for the ease of use, the powerful features, and the unparalleled level of support provided by Blackboard.

    On the surface, this is a big win for Blackboard, but the story comes with a caveat regarding its relevance to the LMS market. What was not shared during our call with Blackboard executives is that they share their private equity owner (Providence) with Galileo as described in late 2017.

    Laureate Education, Inc. (NASDAQ:LAUR), the world’s largest global network of higher education institutions, and Galileo Global Education, a company under the umbrella of Providence Equity, a leading global asset management firm, have signed an agreement for the sale of Laureate’s institutions in Italy and Cyprus for a total transaction value of Euro 225 million (USD 263 million at the current exchange rate).

    Two or three schools within Galileo were already on Blackboard Learn, a few on Moodle, and the majority on Homegrown or not really using an LMS previously. Unless we can get independent confirmation about the nature of the selection (was it truly competitive or was it earmarked for Blackboard as long as they met minimum requirements), I would not extrapolate this news to show broader movements in the market.

    Blackboard also presented some data around roughly 200 new LMS customer acquisitions in 2018 (“new logos”) for both Open LMS (the rebranded Moodlerooms) and Learn.

    • The majority of the reported wins, roughly 120 based on interview, are for Open LMS, showing continued growth for this under-the-radar Blackboard product. These numbers are impressive, but we note that last year the company reported 223 Moodlerooms “new logos” in 2017. It will be interesting to track over time if this deceleration is primarily driven by the general market slowdown vs. fallout from the cancelled Moodle Partner agreement.
    • For the Learn LMS, Blackboard is reporting ~80 new logos in 2018, of which 52% are in higher education. If accurate, this would be a significant turnaround for the company; however, our data do not show this level of new wins for Blackboard unless you include Galileo as roughly 30 “new logos”. We asked Blackboard to back up that number with specifics such as sample listings to see if we have holes in our data, but Blackboard declined to provide further information due to “privacy reasons”. During the same time period, according to our data, Blackboard has lost more than 100 institutions, more than three fourths moving to Canvas and the remainder moving to D2L Brightspace.

    In the end, Blackboard is making steady progress with Learn SaaS deployments and contract extensions, benefiting from the LMS market slowdown, and winning their biggest new LMS account since 2015. We are not convinced that Blackboard is causing the slowdown or that their new Learn momentum goes beyond Galileo Global, but there are signs of progress worth sharing.

    Update 2/27: Fixed description of CashNet and Transact, which are part of the same business line, and added footnote.

  • State of Higher Ed LMS Market for US and Canada: 2018 Year-End Edition

    State of Higher Ed LMS Market for US and Canada: 2018 Year-End Edition

    This is the eleventh year I have shared the LMS market share graphic, commonly known as the squid graphic, for US and Canadian higher education. This past year we at e-Literate shifted our LMS Market Analysis reports from Spring / Fall to Mid-Year / End-of-Year to better allow analysis of entire years. With the release of our end-of-2018 report last week to subscribers, it’s time for us to look at updates on the institutional LMS market for North America (US and Canada) higher education. Note that our coverage for the market analysis includes Europe, Latin America, Oceania (Australia, New Zealand, and surrounding island countries) as well as emerging coverage of the Middle East.

    We present the following data “by institutions”, with market share as a percentage of the total number of institutions using each LMS as a primary system, and “by enrollments”, where we scale the institutions by its total enrollment. The latter better captures the business of the LMS market, since most licensing deals are based the number of students.

    But first, let’s look at an updated LMS market share graphic, commonly known as the squid graphic, for US and Canadian higher education. The original idea remains – to give a picture of the LMS market in one page, highlighting the story of the market over time. The key to the graphic is that the width of each band represents the percentage of institutions using a particular LMS as its primary system.

    Higher ed LMS market share for US and Canada, January 2019

    This year there are two inter-related trends that deserve a broader explanation -the LMS market slowed down with less activity overall, and Canvas and Blackboard continue to be neck-and-neck in the top spot of this market.

    We recently described the overall market activity slowdown in that there are fewer LMS formal evaluations taking place since mid 2018, with initial data pointing to a 20 – 25% drop from a year earlier. This slowdown seems to be a type of plateau rather than a continuing trend, and we are watching to see if it is temporary or not.

    Last summer we shared the symbolic passing of the torch where Canvas surpassed Blackboard in US market share, which was the first time Blackboard was not the top system since the market emerged two decades ago. What is interesting is that half a year later, the two systems are still neck-and-neck. In the US Canvas is still slightly ahead, and in North America (adding in Canada), Blackboard remains in the top spot by 0.4% (26.8% to 26.4%). Why is Canvas not continuing to extend its lead? Looking at the underlying data, there seems to be three reasons to consider:

    • The overall market slowdown means that there are fewer deals for Canvas to win lately.
    • Blackboard continues its University of Phoenix implementation, which still includes dozens of campuses despite its enrollment drop.
    • The shutdown in December of the for-profit Education Corporation of America (Virginia College and Brightwood College systems) meant that Canvas lost several dozen campuses.

    The latter two points should fully play out in the next three months, possibly making this a one-time change in trends, but it is important to call this situation out.

    Some other notes:

    • The market continues to consolidate around the Big Four – Blackboard, Canvas, D2L Brightspace, and Moodle.
    • The Homegrown option for LMS usage is going away, at least in a statistical sense. Only a handful of schools even consider this option.
    • D2L shares the challenge of having picked up several large for-profit systems that are closing campuses and therefore hurting market share. In D2L’s case, the biggest one is the former EDMC schools – the Art Institutes, Argosy University, and South University – that were sold out of bankruptcy to a non-profit entity and have closed dozens of campuses over the past year. These losses offset many of D2L’s wins in 2018.
    • Moodle had a few new wins in North America.

    Sticking with North America, we can also show LMS market share scaled by the enrollment of each institution, giving a different measure worth considering.

    NA LMS Market Share by Enrollment

    We’ll share more information on other global regions in the coming months.