e-Literate

Present is Prologue

Category: LMS & Learning Platforms

Everything you want to know about Learning Management Systems and whatever comes after them.


  • Moodle’s Sanctimony on Openness is Moot

    Moodle’s Sanctimony on Openness is Moot

    Phil Hill has a great post up on the latest chapter in the Moodle partner soap opera. You should read the whole thing if you care about the LMS world, but the gist is this:

    • Moodle, in addition to being open-source software, is also an Australian for-profit company called Moodle Pty. Said company exerts a great deal of control over the development of the software and whose business model is licensing the Moodle trademark to partners who provide Moodle-related services in exchange for a percentage of their Moodle-related revenue.
    • Moodle creator and company owner Martin Dougiamas was very unhappy when Blackboard bought some of the biggest Moodle Partners some years back. After a lot of drama and tension, Blackboard left or was ejected from the Moodle Partner program. (Details vary depending on which party is telling the story.) Since Moodle Pty owns the trademark to the Moodle name, it revoked Blackboard’s permission to call its Moodle-based product “Moodle” or to use the Moodle logo.
    • Blackboard renamed their Moodle-based product OpenLMS, which it eventually sold to a company called Learning Technologies Group (LTG).
    • Somehow LTG or one of its subsidiaries was apparently a Moodle Partner at this time. It’s a little hard to follow because Moodle Pty has had some ongoing drama with LTG in their Moodle Partner program as well. At any rate, LTG continued Blackboard’s strategy of buying up Moodle Partners.
    • This week, after a lot of drama and tension, Moodle Pty ejected LTG from the Moodle Partners program, accusing LTG of creating lock-in with proprietary extensions in violation of the principle of “Openness” (which probably has some truth to it, but…well…more on that in a bit).
    • In parallel, OpenLMS announced its own policyabout what it will release as open-source and what it will keep as proprietary.
    • Recriminations between the two companies have been flying back and forth about a variety of topics, including whether OpenLMS’s openness policy is open enough.

    When e-Literate changed editorial focus in 2019, it largely stepped away from (a) providing coverage of the LMS market as an end in itself and (b) taking on one of its primary missions as policing vendor behavior. I have been very happy with both of those decisions. I’m going to make an exception to both here mainly because I want to make a point about “Openness” (where, as you will see, the choice of capitalization is not mine).

    Moodle is a vendor for which openness is a tool

    Over the years, I’ve tended to go easy on Moodle because it, and Martin, have accomplished enormous good in the world. Whatever one thinks about the LMS as a product category, it has enabled online education at scale, a development whose value has been spotlighted by the global pandemic. Moodle, by virtue of its design, license, and community, has brought these capabilities to communities and regions that no other vendor has deemed profitable enough to serve. Moodle has genuinely made the world a better place. And although I am pointedly and repeatedly going to emphasize Moodle Pty’s nature as a for-profit company, I fully believe it is a mission-oriented company that has prioritized impact.

    Corporate structures, business models, trademark laws, and software licenses are all inventions. They are artificial constructs we design in order to have specific effects on the world. Many of these constructs are specific kinds that we collectively refer to as “intellectual property” or “IP.” IP is simply an idea that somebody legally owns. That ownership can be legally expressed in a variety of ways, such as a patent for an invention, copyright for content, or a trademark for a company or product name or logo.

    (Update: IP is a little more complicated than that, as a couple of early critics of this post have pointed out. The degree to which the ownership is of the idea itself or the particular expression of it varies by type of IP. A process patent is different than copyright. This is a nuance that is beside the points I’m making here, but I’m noting it in the interest of precision.)

    IP in all its forms is a tool. In the United States, our Constitution specifically framed it this way. Here in the US, IP is a temporary monopoly that Congress can grant in order to provide financial motivation for the creation of new ideas and works. For example, you may be granted a copyright so that the years of your life writing the Great American Novel will pay off in the form of royalties, thus enabling you to contribute art to the world and, perhaps, to even be able to afford to start working on your next novel.

    Open licenses along the lines of open-source and Creative Commons are hacks of this system but do not depart from its essential purpose. Thir underlying insight is that sometimes existing IP licenses are hindrances to the desirable activities they are intended to encourage. For example, I publish this blog for free because I want to share knowledge. I want people to create new works using mine as building blocks. All I want in return is credit for my contribution. If I made every person who wanted to quote e-Literate explicitly ask my permission—as copyright law requires—then that extra effort might discourage some from adding to our educational knowledge. So I publish the blog under a Creative Commons license that lets people use my content without having to ask me as long as they properly attribute it.

    Some people who use open licenses view this kind of sharing as an inherent value. I personally tend toward the utilitarian. I have an affinity for openness and believe that, all else being equal, open is better than not. But I view openness as subordinate to other values such as educational impact. This is a matter of personal philosophy; other folks legitimately feel differently. But even as an end in itself, those who are immersed in topics like open-source or Creative Commons licenses know that the definition of “openness” and the value that it represents are very much contested territory among advocates.

    One way to divide the territory is into open licenses, which are specific legal contracts with well-defined terms, and “openness,” which is a squishy concept with a mix of utilitarian and moral connotations that vary from person to person. Well-written open licenses are clear-cut in their requirements and limitations. They often support, but do not necessarily define, commitments to a specific definition of openness as a value.

    Let’s focus on the utilitarian part for a moment. Martin created Moodle Pty with a particular revenue model, a particular open-source license, and a particular approach to using the Moodle Trademark as intellectual property. These pieces all fit together into a machine for growing “Moodle,” by which I mean both the adoption of the software and the company that Martin owns. It’s a model that served the Moodle mission and sustainability goals well at the time it was created. Many small schools, colleges, and other organizations all over the world had no access to any tool for centrally supporting online and technology-enabled learning. The Moodle software is free and easy to run (up to a point). Moodle Pty created a network of small, local businesses supporting support schools that did not have the capability to run Moodle on their own. Moodle Pty collected (and still collects) a percentage of revenues from these local vendors. This money went toward the development of the Moodle software, promotion of Moodle and its partners, paying salaries, and so on. At the time, the model worked incredibly well, making Moodle far and away the most popular LMS around the globe outside of the US and Canada.

    But the world has changed. Moodle was created before cloud computing and before online learning became mission-critical at scale across large swathes of the globe. These changes broke Moodle’s business model. It has been broken for quite some time. It arguably broke when a Moodle Partner called MoodleRooms, before it was eventually acquired by Blackboard, demonstrated that it could support one million simultaneous users on a single multi-tenant instance. This was a cloud version of Moodle, even if that term wasn’t popular at the time. Once a cloud version of Moodle existed, the power balance between Moodle Pty and its customers…er…partners shifted, and the number of customers from which it could collect revenues was destined to shrink. Rather than being a supplier to many small businesses, Moodle increasingly became the supplier for a few large businesses, each of which became increasingly important for its revenues. Again, read Phil’s post if you want a detailed breakdown of the Moodle model’s…um…breakdown.

    Open is as Open does

    Back to the present. Remember, LTG’s OpenLMS (which it purchased from Blackboard) made an announcement this week about which parts of their code they would release under an open-source license and which parts they would keep as proprietary. Phil Hill asked Martin to comment on OpenLMS’s announcement about their openness policy as part of the reporting for Phil’s blog post. Here is Martin’s reponse:

    Our actions have obviously been a factor in causing this, which I count as a good thing for everyone.   Please note, though, that their stated direction is to sell the integration of the full suite of LTG products – and none of those other things are open or planned to be.  Clients will still have the same lock-in to LTG as before (as desired by LTG).    https://www.youtube.com/watch?v=mBFShI8OYe4

    Not even all the “Open LMS” SaaS product will be actually open either.   I don’t know exact figures, so I’m estimating, but the OpenLMS service is probably 90% Moodle, with perhaps 10% other stuff, and they’re going to make only perhaps half of that other stuff available under GPL, so 5%.   It’s not a big deal and honestly, the least they could do.

    Moodle’s Dispute with LTG and its Growing Suite of Former Moodle Partners 

    Meh.

    News flash: All vendors try to make their customers want to stay by adding features or services they can’t get anywhere else. Some strategies are more ethical than others. Moodle Pty., like many vendors, uses its proprietary intellectual property to create what could arguably be called lock-in. Moodle Pty’s customers are Moodle Partners. Its intellectual property is its trademark. Martin has, on multiple occasions, exercised the threat of withholding that valuable IP when its customers have left or when they have behaved in ways that he believes are contrary to the interests of Moodle.

    There is nothing inherently wrong with this. Moodle has a mission that depends on revenues to sustain. Moodle Pty gets revenues from mostly smaller Moodle vendors. It uses its IP in the form of its trademark as kind of a soft lock-in to its customers (or “Partners”). If the customers walk away, they can still use the Moodle code. They just can’t use the Moodle trademark, which has value because it is recognized and trusted.

    LTG and its subsidiaries, eThink Education and OpenLMS, also provide value-added intellectual property to differentiate themselves, attract prospective customers, and hold onto existing customers. Moodle had earlier ejected eThink from the partner program for not being sufficiently “Open”:

    The Learning Technologies Group (LTG) announcement of the acquisition of eThink Education represents LTG’s intention to move customers into the Open LMS platform, which is not truly Open at all. Their extensions to Moodle are not downloadable, and not available from other service providers. Once on their platform, it is harder for institutions or organisations to move to a different provider, or to their own servers. This goes directly against Moodle’s values of openness. Consequently, as of 18 December 2020, eThink Education is no longer a Moodle Certified Partner or otherwise associated with or recommended by us at Moodle.

    Moodle’s Dispute with LTG and its Growing Suite of Former Moodle Partners 

    Martin’s definition here of “Open” has always been problematic. A lot of software is designed to integrate with or even run on other software. If somebody runs Moodle on a Windows server, does Moodle cease to be “Open” because Windows is not? If a school integrates Zoom—which is not downloadable and is not available from other service providers—as an “extension” to Moodle, does Moodle cease to be open source?

    Of course not. Heck, I would bet money that he personally has written code in Moodle that enables proprietary vendors to integrate their products deeply into Moodle. Further, the cloud has made this situation vastly more prevalent. How many of the software products you integrate as “extensions” to your LMS are downloadable to run on your institution’s servers? How much do you care? Instructure, whose source code to Canvas is largely (though not completely) open-source, has had vanishingly few institutions choose to download and run Canvas on their own servers or seek out an alternative provider. That’s because the virtue that drove customers to Canvas was its nature as cloud software, which means it is designed precisely so that nobody would have to download the software and run it on their own servers. It turns out that schools are not typically great at running mission-critical software applications with no hiccups and no downtime. The cloud has diminished the utility of “openness” (with a lower-case “o”) for many institutions.

    Now, it’s perfectly fine for Moodle Pty to hold that as a requirement for its partners and assert that their version of openness a value. Certainly, if its mission is to prioritize those parts of the world where affordability dictates either self-hosting or a small operation that can’t write its own cloud harness for Moodle, then the company certainly is within its rights to make a decision about that. If so, they should say that.

    By the way, Moodle Pty does have a cloud version of Moodle called, aptly enough, MoodleCloud. If their cloud-enabled version of Moodle has been released as open-source, I have not been able to find it. Again, I take a utilitarian view of any decisions that Moodle Pty makes in this regard. In my view, it’s a good decision to the degree that produces desirable results for educational equity and effectiveness. My concern is with Martin’s apparent hypocrisy, which is underlined by a tone that I read as sanctimonious.

    Likewise, if LTG is alleged to have violated Moodle’s open-source license or infringed on its trademark—in other words, if LTG stands accused of stealing Moodle Pty’s IP—then Moodle Pty should be clear about that accusation. The fact that they have not done so is suggestive. If LTG’s extensions legally violated Moodle’s open-source license’s “openness” requirements, then Moodle Pty would (and should) sue. They have not sued, which suggests to me that LTG’s code is cleanly separable. It may not be as clear-cut as Zoom or Windows, but it appears to be clear-cut enough that Moodle Pty has not pursued legal recourse.

    This is not to say that LTG couldn’t be playing games with features that (a) customers do not know are proprietary and (b) would have a hard time leaving behind if they migrated. I don’t know LTG’s offerings well enough to have an opinion on the matter. Martin could conceivably make a specific argument along these lines. Not a legal one, mind you. Moodle Pty’s trademark lock-in is relatively weak and circumscribed. But he could try to make an ethical argument that LTG’s extensions trick customers into lock-in. He seems to insinuate that.

    But he has not actually made the case. In fact, his waving away of OpenLMS’s statement about what they are opening as “the least they could do,” speculating about the percentage of code that remains proprietary rather than pointing to explicit features that concern him, suggests that he is not particularly interested in making that argument. He wants to make an argument about Openness in some pure and absolute sense.

    I have two problems with that. First, it comes across as hypocritical. Again, I don’t have any problem with Moodle Pty setting terms for its resellers, kicking out resellers that violate those terms, and enforcing the terms by withholding use of the Moodle trademark. But let’s not pretend that Moodle Pty has eschewed all IP, like some sort of corporate Buddhist, or that it has declined to assert that IP to protect its interests. I assume that Martin has a set of principles regarding openness that he is following. They must be more nuanced than “Openness is judged by the percentage of code is downloadable and available from other vendors.” He should state his principles clearly, not as the Proper definition of Openness but as Moodle Pty’s objective and concrete commitments and rationale. In fact, the OpenLMS statement that he dismissed so blithely does exactly this. Martin has enjoyed a position of assumed moral privilege for too long. If he wants to serve “Openness,” however he defines it, he should start by defining it in serious, testable, and internally consistent terms.

    Second, I reject the notion that Openness is a well-defined and absolute virtue by which others are Judged. ((Two can play the Capitalization Game.)) I always have and always will. Martin is far from the only person to wield an “opener than thou” attitude as a weapon in educational communities. He’s also far from the worst offender. But the way in which he’s choosing to communicate his decisions about the Moodle Partner program is particularly harmful because of his global stature. People who are deep into any of the various open communities—open-source, OER, open access—have inevitably been exposed to the complex and nuanced debates about the pros and cons of different licenses. These debates are fundamentally about the values and affordances of different definitions of openness, as expressed in those licenses. I understand that participants in these debates have passionate views on the subject. I don’t doubt Martin’s own passion. But by presenting the matter as cut-and-dried, he flattens this useful debate instead of taking the opportunity to raise awareness and literacy regarding its nuances. In the process, he risks coming across as naive at best and manipulative at worst.

    Martin could also take another (simpler) approach, which is to explicitly require Moodle Partners to adhere to Moodle Pty’s limitations around permitted extensions and reserve the right, without sanctimony or high dudgeon, to eject Partners that don’t adhere to the Terms and Conditions. I have no problem with that.

    Ironically, I have never been able to see a copy of the Moodle Partner Terms and Conditions, even though I explicitly asked to see them at one point. Apparently, they are (or were) considered to be proprietary IP of Moodle Pty and are (or were) not to be shared.

    I hate this crap

    Ugh.

    As I write these words, I am 50/50 on whether I will hit the “publish” button. If you are reading this post, it means I decided the discussion of the larger principle justifies wading into a topic that I largely don’t care about to criticize a person and organization whose accomplishments I respect. I don’t care about the LMS market per se. I have no real opinion about the dispute between Moodle Pty and LTG. Nor do I care enough to put in the work required to form one, at least based on what I’ve heard so far. I harbor no ill will toward Moodle Pty or Martin Dougiamas. Truly, I have a long list of topics that I would relish writing about instead of this one.

    All that said, I find the way that Martin is publicly characterizing the nature of the dispute to be disturbing and harmful, just as I found it to be disturbingly simplistic when he used the same rhetoric with Blackboard. If he truly believes that there is a clear moral definition of “Openness” (which he chose to turn into a proper noun through capitalization) then he should define it and articulate his argument for it. Alternatively, he could simply state that these are the conditions for Moodle Partnership without the air of moral superiority. Either option would be fine with me.

    We should be able to have thoughtful and productive discussions about how different definitions of openness can support or hinder different aspirations and values. My desire to do so is my motivation to write this piece and characterize the rhetoric coming from Martin and Moodle Pty in such strong terms. I am writing because I believe that Martin’s language is doing more to obscure the values and goals of “Openness” than it is to support and illuminate them. I find that to be particularly upsetting because I believe that Moodle has historically advanced goals and values that I cherish. In my view, Martin’s current rhetoric risks damaging that good work while diminishing the value of openness as a tool for future good work.

  • What’s Next for Instructure?

    So, Instructure CEO Dan Goldsmith is “stepping down.” Going to “spend more time with his family.” “Hiking the Appalachian Trail.” Choose your euphemism. He has been forced out. Don’t shed too many tears for him; he made about $12 million during his roughly 14-month tenure as CEO. That’s enough to pay maybe 25 decent software engineers for 5 years in the Salt Lake City area.

    The truth is that nobody would have paid much attention to how much Goldsmith was getting paid had he been doing a good job. But in the education market, people tend to pay attention to who is getting a big payout if they worry that their vendor is not putting the students first. I hope that is a lesson that Thoma Bravo is taking note of. (More on that in a bit.)

    That said, the Goldsmith era is now water under the bridge. The more important question is what happens at Instructure going forward and how it impacts the students and educators who depend on the company.

    Short-term

    The acquisition of Instructure by Thoma Bravo is not dead. If anything, it is considerably more likely now, for a variety of reasons, including but not limited to a higher bid by the private equity company. As usual, Phil has a terrific breakdown of the financial drama. The short version is that there is likely to be a bit more drama that will take a bit more time, but the acquisition looks close to a done deal at this point.

    In the meantime, there is no CEO. Instead, the company is being run by a team of its senior executives, some of whom are the veterans that I’ve been complaining have been stifled. Within hours of the announcements of Dan’s departure, I began seeing private signs of aggressively renewed outreach from this team. The bunker mentality is gone. We’ll see how well this team coordinates that outreach, but the horse is out of the barn on this one. I think it will be hard for the next CEO to go back to a classic corporate command-and-control customer interaction style. That is one good outcome from the interregnum (though it is possible to go too far in the other direction if they don’t all pull together).

    The bigger question for customers, assuming that the deal does go through, is what happens afterward.

    Medium-term

    My position has always been neutral-positive on Instructure being acquired by a private equity company in general and neutral on being acquired by Thoma Bravo in particular. Instructure needs some time to move past its current growth plateau. There is a reasonable argument to be made that they could focus on doing that with fewer distractions that could harm their core work for customers if they were under private ownership rather than under the quarter-by-quarter performance pressures of the public stock market. Instructure’s acquisition could be good or bad for education, depending on two major factors.

    The first factor is Thoma Bravo’s plan. I am quite confident that they already have one. And as Phil wrote in the aforementioned post, it is likely an ambitious one:

    One other note – with these aggressive moves, I have to believe that Thoma Bravo has much bigger plans than simply buying a few more Portfoliums while divesting Bridge. Bravo is sitting on a pile of cash ($12+ billion in their latest round), and there are likely bigger plans that depend upon this Instructure acquisition.

    The post by that other guy

    The danger is that the typical private equity merger and acquisition playbooks have a decidedly mixed record in EdTech. At best. Education is a weird market. Combinations that look good based on the spreadsheets are often terrible ideas IRL. I can think of one or two possible big combinations that might work—Coursera comes to mind—but by and large, the impulse to combine two EdTech giants more frequently results in the destruction of value than in the creation of it.

    Private equity folks are rarely stupid. On the contrary, the ones that I’ve met have generally been incredibly smart. They simply lack education market domain knowledge. They apply their disciplinary skills in an area where those skills don’t translate straightforwardly. That can work out if they have a partner in the form of an excellent CEO who does understand education (or can learn it quickly) and is a strong advocate for customers. Dan Goldsmith wasn’t that person, which meant that private equity ownership under him was virtually guaranteed to be disastrous. Assuming the Thoma Bravo acquisition does go through, then the CEO that Thoma Bravo brings in to replace him will be critical.

    They almost certainly have somebody already lined up. Private equity companies tend to keep stables of CEOs that they rotate from company to company. That is probably just fine in the short term. While I have a lot of respect for Instructure’s management team, managing a company of that size through a committee will only work for so long. So bringing in a caretaker CEO quickly is a good idea. But that person may or may not be a good long-term solution. I would argue, for example, that somebody who comes from running an enterprise software company, like Goldsmith did, is not likely to be a good long-term fit. The market dynamics are very different, which is one reason why Goldsmith was completely blindsided and seemed slow to learn.

    There are major opportunities in EdTech. The education sector is entering a period of massive and uncharacteristically rapid evolution. That represents opportunities for a company that can identify new, unmet needs, engage in innovative, user-informed product development, and keep good relations with a particularly demanding customer base. Leadership matters in this kind of situation.

    I see two possible candidate profiles. The first is somebody from EdTech. There is now a generation of executives who have grown up in the space, seen all the many mistakes that have been made, know the customers, and have an eye for the market shifts as they happen. The ideal candidate in this mold is one who is old enough to be seasoned but young enough or unorthodox enough not to be stuck in the first-generation mindset from the established product categories like LMS or textbook publishers (which is where they will likely have earned their stripes). The second possibility is somebody more like Josh Coates, by which I mean a strong product-oriented CEO from the consumer software space who knows how to listen to—and speak to—customers. This person would have more of a learning curve, but since Instructure has a seasoned management team, it could work. But it would take more time before such a person could provide good guidance on acquisitions.

    Those awkward teenage years

    In the summer of 2018, I wrote that Instructure was entering its awkward teenage years. We just survived eighth grade. After a year of monosyllabic responses and long periods in the bedroom with the door closed, the pale young thing has emerged into the sunshine.

    But now comes high school. There will be new friends and new temptations. There will be strange ideas of what it means to be cool and how to get to the top of the ladder. Instructure didn’t become popular by being the cool kid that everyone had to be with. They became popular by being the kid that was fun to be with. That was good at making friends. That listened to you, cared about your problems, and laughed at your jokes.

    It’s that kind of popularity that makes the company valuable and that will enable the right leadership team to build value going forward. Whatever clever plans Thoma Bravo may have, they need a CEO who can provide them with ground truth, push back when necessary based on an education-informed perspective, and keep faith with the customers.

  • Instructure’s Better Possible Future

    Having reluctantly weighed in on Instructure’s proposed acquisition by Thoma Bravo, I would like to turn back toward positive rather than negative possible futures by describing a different potential vector for the company. Despite the criticisms of my previous post, I do not believe that Instructure is in a deep hole, inevitably heading deeper, with no way out in the foreseeable future. If there are two takeaways from that post, they are these: First, it is easy for an EdTech company to have a sudden and dramatic reversal of fortunes and of customer perceptions, especially in the downward direction. Instructure is at an inflection point where the risk of such a turn is particularly high. (I warned about this over a year ago, after Instructurecon 2018.) Second, the seemingly obvious or proximal causes of a company’s success can be misleading. When we misunderstand causality in this way, it heightens the risk. Instructure has not been a well-understood company in general, and my concern is that the current board of directors and executive management may not have a good understanding of the causes of the company’s historic success. So that post wasn’t about what will happen. It was about what could happen.

    In this post, I want to explore the company’s actual current competitive strengths as the basis for the kind of growth in value generation that both customers and shareholders would like to see. In the process, I’m going to have to spend a little more time analyzing their missteps. But beating up on Instructure’s management is not my goal. Rather, I want to offer up a case study for how value can be created in EdTech in the 2020s. In the process, I am going to spend some time on the promise and perils of data-driven affordances.

    Reminder: D2L, one of Instructure’s major competitors, recently became the first foundational sponsor of e-Literate’s Empirical Educator Project (EEP). Given that big decisions are in the process of being made about Instructure’s future right now, I am obliged to call special attention to the appearance of a conflict of interest.

    Instructure’s remaining competitive strengths

    As I highlighted in my previous post, Instructure entered the market with competitive strengths that were difficult and time-consuming for their competitors to duplicate. One was that Canvas was built from the ground up to be cloud-native. From their customers’ perspective, that’s a critical ingredient to the product’s reliability. From their competitors’ perspective, it is a very hard technical task to retrofit a cloud architecture onto a mature product that was designed to run on individual customers’ own servers. Another competitive advantage was that Canvas was built from the beginning to delight end-users, whereas older platforms were at least partly built to delight the IT managers who had made purchasing decisions in the early years of LMS sales, and who often had different concerns than the end users. This too is very hard to retrofit onto an older application. Arguably, Blackboard’s biggest mistake with Ultra has been to set customer expectations too high regarding the pace of progress. The rearchitecture and redesign they have undertaken are genuinely, seriously hard.

    But given time and motivation, these challenges can be overcome. And sure enough, Instructure’s competitors have been steadily narrowing these gaps over the years. The race is now competitive in these areas where Instructure had the field to itself for a long time. Likewise, their competitors have improved their customer service and focus on improving the end-users’ interactions with the companies.

    So what’s left?

    First, while Instructure’s brand has taken a couple of hits lately, it’s still strong enough, and customer memory of their positive experiences with the company is long enough, that lost ground can be regained. There are some customers who have had bad experiences, or growing concerns. The CEO has said potentially alarming things in public and failed to correct his mistakes. Nevertheless, I get the sense that the customer base is still rooting for the company to find its footing again.

    Second, there’s the culture. Most of the front-line people and important mid-level to senior managers who grew up in Instructure’s culture of excellence are still there. They still have the same knowledge, skills, experience, and convictions. And they have a collective muscle memory of how to work together in ways that were successful for customers in the past. Until we start seeing either talent flight or layoffs that cut deeply into the wrong parts of the company, then the heart of the original company is still beating.

    As for the core platform, while it’s no longer dramatically differentiated, it’s still solid. All things considered, nobody enjoys migrating to a new LMS. Instructure is still on a glide path to at least maintain its market share in the US and grow abroad. They would have to actively screw that up for the situation to change. And while that is easier than it may seem, it would take a while.

    Finally, while the market has caught on to the value of Canvas being designed as a cloud-based application with a focus on end-users, there is one other novel decision the company made early on that is still underappreciated. Canvas was designed to be a platform, not an application. To grasp the difference, think about the difference between a Blackberry (if you are old enough to remember those) and an iPhone. The Blackberry was a good phone that had a great keyboard. So, in a world where texting and email were becoming at least as important as voice communications, adding text communication features to a phone was a good idea. Yes, there were a few “apps,” for Blackberry. But there weren’t many, and most of them were bad. The iPhone, in contrast, was built for apps. Instead of making the primary interface a great physical keyboard, Apple made it a pane of glass. The interface was anything that could be created for a touch screen. Including interfaces and applications that Apple hadn’t even dreamed of. The iPhone is a platform. It is infrastructure that is designed for other people to write applications that run on it and through it.

    Instructure made a series of principled decisions not to develop certain capabilities in Canvas. Instead, they built both the technical infrastructure in Canvas and the relationships with integration partners to have a very strong ecosystem of EdTech companies that have deep relationships with the company and deep integrations with the platform. Rather than building a great keyboard and email app, they built a metaphorical pane of glass and app store. They created a technology platform and ecosystem that attracted other people to extend Canvas with new capabilities.

    This too was a pioneering strategy. Before Instructure, the model for LMS partner relationships had been set by Blackboard in the Chasen/Small era. They recognized that the vast majority of digital education products would have to integrate with the LMS. So they decided to monetize that by charging every integration partner a (significant) fee. In those early days, there was some business justification for that strategy. After all, Blackboard had invested in developing integration APIs—Blackboard Building Blocks—and, since they were by far the largest player in the market, integration with their platform offered substantial business opportunities in the form of access to Blackboard’s customer base. This became a significant revenue source for Blackboard that its competitors envied and, to varying degrees, tried to emulate.

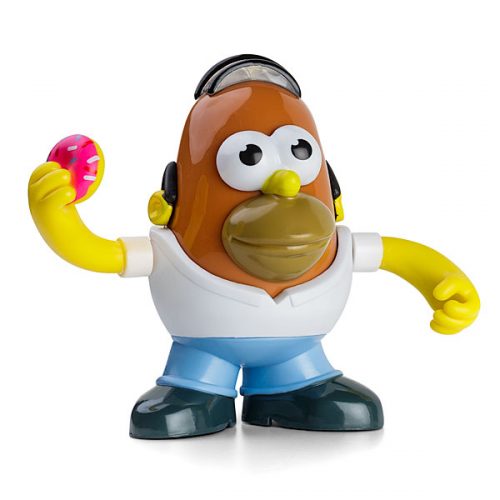
    But just as Instructure was lucky to come along right when the nature of the LMS customer was shifting, and right when cloud-based development had matured enough to make building a cloud-based LMS feasible, they were also lucky to come to market right when the IMS LTI interoperability standard was starting to take off and EdTech venture funding was really taking off. The LTI technical integration standard made charging a toll harder to justify, while the proliferation of EdTech startups transformed the locus of value for an LMS from a Swiss army knife into the hub of an ecosystem. Or, as my friend Kelvin Thompson from UCF has memorably characterized it, the potato part of Mr. Potato Head. On the one hand, there is no Mr. Potato Head without the potato. On the other, the potato itself is not where the personality (and personalization) come from. Instructure was less focused on charging partners and more interested in enticing them into adding character to Canvas in new and imaginative ways.

    Dalek Mr. Potato Head
    Homer Simpson Mr. Potato Head

    Their platform differentiator is subtle in the LMS world, but one that is critical to their current situation.

    In fact, it is essential to the first of two paths Instructure has for developing a product portfolio that I’m going to describe in the remainder of this post.

    Acquisitions

    There is now a whole galaxy of small EdTech companies that have developed new products or services that touch the LMS in one way or another. Instructure arguably is in the best position of any of the players in the market to identify good companies with products that already integrate well with Canvas and snatch them up. It’s not an exceptionally strong or durable advantage, but it’s one that they could be utilizing aggressively right now.

    Former Instructure CEO Josh Coates had a philosophy about acquisitions. Specifically, he was against them most of the time. I heard him give a talk about it once. His strategy was thoughtful and well-reasoned. And it would have been justified had the company succeeded in organically developing a portfolio of compelling offerings. But that didn’t happen. So, at least for the short term, the company is going to need to be more acquisitive in order to become financially healthy. But for that strategy to work, Instructure will need to rely on the knowledge of its employees who have worked on the platform aspects of Instructure’s business to identify truly good companies. What I mean by “truly good companies” is ones that have earned customer loyalty by solving some important problem well. Instructure needs to find compelling products, which is not easy in EdTech. The company leaders will also need to clearly and consistently articulate the reasons why they are proud to have acquired those products and how the acquisitions will better serve their Canvas customers.

    Instructure has made one high-profile acquisition under CEO Dan Goldsmith: Portfolium. Here’s the relevant bit from Instructure’s press release announcing the acquisition:

    Portfolium was created to help every person realize their full potential by connecting their learning with opportunity. The company helps institutions inspire, assess, and showcase student achievements via its powerful ePortfolio network, student-centered assessment, job matching capabilities, and academic and co-curricular pathways.

    “Working with Portfolium advances our mission since it enables us to help people move from the classroom to the workplace,” said Dan Goldsmith, CEO of Instructure. “Portfolium has been a great partner of ours. With their team, and by adding their student success capabilities built on the leading learner network, we will, together, provide more value to both current and new customers.”

    Instructure Enters Into Agreement to Acquire Student Success Network Portfolium

    Honestly, I don’t know what that means. Portfolium is an ePortfolio. That blurb mostly describes what an ePortfolio does, but adding some pleasant adjectives. Shorter version:

    Instructure is acquiring Portfolium, which is an ePortfolio company. Portfolium does things that ePortfolios do. We like it and think you will too.

    Honest press release

    The only bit in there that isn’t completely generic is the sentence fragment about job matching. But they don’t do anything with it.

    In fairness, most people who haven’t written a press release don’t appreciate how hard it is to write a meaningful one. I’m a pretty good writer, but I will readily admit to having struggled with that particular genre at times. That’s exactly why smart companies don’t rely on the press release to carry all the weight. They go out and repeat and elaborate on the message. Relentlessly.

    I haven’t heard any such message about Portfolium.

    Again, in fairness, I have not been following the LMS market as closely as I used to. But the thing is, if Instructure were really doing this right, it shouldn’t have been possible for me to miss this. I should have read it in the articles in outlets like EdSurge, Inside Higher Ed, and The Chronicle. In preparing to write this post, I did a search to see if I missed anything in the coverage by these or any other outlets.

    Nope.

    No quote from the CEO beyond what was in the press release. In fact, no quote that I could find from anyone that wasn’t already in the press release. There was an interview with the Portfolium founder in the San Diego Tribune. But it was clearly a local business story, in a local outlet—Portfolium was San Diego-based—and not anything aimed at Instructure’s customers. There’s nothing. Nada. Zip.

    When I ask Instructure customers about the deal, they tell me they haven’t heard anything either. And when I have run into Instructure employees at conferences—specifically, ones who are in a position to know about Portfolium—none of them have brought it up with me. In the old days, they would have. These are the same humans. There has been no invasion of the body snatchers. So it appears that the corporate communication strategy has changed. Where it used to be the case that you could get any random Instructure employee driving a golf cart at Instructurecon ((Golf carts driven by employees at Instructurecon is an actual thing. Or at least, it used to be.)) to talk about just about anything, it is now difficult to get even senior Instructure managers to talk about…well…just about anything.

    So there is at least one and possibly two serious but very fixable problems here. First, there is definitely a communication problem. Specifically, it would be good to have meaningful communication directly from the people within the company who understand why acquisitions are being made. Instructure employees have been some of the best brand ambassadors in the sector. Circumstantial evidence strongly suggests that they are no longer empowered to speak for the company. By muzzling them, Instructure is voluntarily throwing one of its remaining competitive strengths in the garbage can. And the only senior manager who has been allowed to speak on the record about the Goldsmith era’s first important, high-profile acquisition—to anybody, apparently—is the CEO. The one who has the most to prove about actually knowing the sector and caring about it. And his only statement that I can find amounts to a spoonful of bland pap in a press release.

    I don’t know much about sports, but I know what an unforced error is.

    While it would be easy to lay much of this at the feet of the marketing department, there has been a pattern of communication in the Goldsmith era that started immediately after he became CEO and has been consistent despite some churn in marketing department senior personnel. In fact, that churn may be an indicator in itself. The leader sets the tone.

    The second possible problem is harder to assess precisely because of the effects of the first one. I can’t tell if Portfolium is a good acquisition or not. A lot depends on what problems Instructure’s managers think it solves for customers and how they intend to make it more useful. Which they’re not really talking about. I can’t tell if this acquisition was a paint-by-numbers decision or if there is a real effort to increase value for the customers in a mindful, meaningful way. Instructure has people who know which partners are good potential acquisitions and why. They know their partners and customers really well. I can name a handful of them off the top of my head. In general, they are not being heard externally, which is unfortunate. If they are also not being heard internally—and again, I can’t tell one way or another—that would be a lot worse.

    I am confident that Instructure has the right ingredients and the right chefs to cook up an effective acquisition strategy. But the proof of the pudding is in the eating. If Instructure doesn’t both prioritize the acquisition of companies that will serve their customers well and communicate the reasoning and intentions behind the acquisitions, that could easily mean the difference between customers who are hungry for more and ones who are left with a bad taste in their mouths.

    Insights

    The other area for growth is in providing educators and students with better insights that support student success. It is impossible to overstate both how important and how fraught a topic this is.

    On the one hand, colleges and universities fail huge swathes of students all too often. There are students who want to go to college, get admitted to college, but haven’t had anybody to teach them how to succeed in college. Students who never make it to the first day of class. Or who get partway to a degree and drop out, due to lack of skills and support or tough personal circumstances. Students who need to come back to school and reskill while they are holding down full-time jobs and raising families.

    Many colleges and universities are not very good at serving some or all of these groups and routinely fail them. This used to be “only” a moral failing. Now it is an existential one, because the most obvious path to long-term sustainability for an increasing number of colleges and universities is to serve more students in their area more effectively for 20 or 40 years rather than for two or four. Institutions of higher education need to learn to perform better. And they need to learn it urgently. To do that, they need new insights. To get new insights, they need better information—that is, better data—and better ways of analyzing it.

    On the other hand, we live in an era when people have good reason to be concerned about the misuse of data in a seemingly ever-increasing variety of deeply troubling ways. Educators are responsible for their students. Many of them take this responsibility very seriously indeed. And particularly when it comes to the experimental use of data—even for the best of purposes—that responsibility is hard-wired into institutional processes in very particular ways.

    In academia, educational research falls into a larger bucket of “human subjects research.” That category also includes research on topics like how to perform open-heart surgery, how to deal with intractable clinical depression, and how people can be manipulated or fooled by social media. Think about the possible unintended consequences of poorly designed experiments in any of those three areas. We have canonical examples from bygone eras. The Milgram experiment. The Stanford Prison Experiment. Today, any academic research conducted in the United States that involves human subjects must submit its experimental design and protocols for experimental subjects’ informed consent to a rigorous peer review and approval process before the experiment can be undertaken. Educational research must be submitted to the same approval process by the same oversight board that would approve life-and-death surgery or psychological experiments.

    But unlike in medicine, an EdTech company that wants to conduct research using student data for product development purposes is required to do…nothing at all. They don’t even have to inform the students that they are being experimented on.

    In fact, EdTech companies conduct experiments on a weekly basis that would require a lengthy approval process in some universities. ((Different universities interpret the rules around such approvals differently, in part because a university that has a world-class medical school will likely understand their responsibilities differently than one with no medical school at all but a significant psychology research program, for example.)) Suppose, for example, that product developers want to test which design of a button is more likely to raise user awareness of a feature. They conduct what is known in the industry as an “A/B” test. They show some users one design, other users the other design, and track which design gets the most clicks. This is an absolutely routine software development practice. It is a foundational strategy that developers use to learn how to make their software more useful and usable.

    But let’s also suppose that the feature the button activates has a significant impact on improving student outcomes. Using the feature helps to improve learning. The developers, with the best of intentions, are trying to figure out which version of the button will get more students to use the feature that will help them. But in this experiment, the button that turns out to be worse may negatively impact the learning outcomes of students using that version of the software.

    This is exactly the kind of contingency that might trigger a requirement for an experimental design review process inside a university.

    Imagine that you’re an academic who feels responsible for your students and who lives in that kind of a culture surrounding anything that remotely looks like it could be human experimentation. Imagine that you read the following statement by the CEO of a company whose EdTech product you, personally, require your students to use extensively every single day:

    We’ve been working on the scaffolding for [DIG] for well over a year now. I mentioned in our remarks that we already have product validation towards out there in the market. We have instructors and students consuming output from some of the initial experiments with DIG. And we anticipate later this year obviously to make more announcements around specific products and offerings and how we bring them into the market. DIG ultimately is a platform first and foremost based upon machine learning and artificial intelligence. I believe that any multi tenant SaaS company born in the cloud has the opportunity once they hit a certain market share. And in fact, it may even be incumbent upon those organizations to partner with the industry and evolve that industry with new insights and predictive modeling using AI and ML. That’s what DIG is at its heart.

    We already have analytical capabilities in our Canvas platform. I want to be really clear and delineate the difference between an analytics and reporting capability, and a machine learning and AI platform. [snip]

    We have the most comprehensive database on the educational experience in the globe. So given that information that we have, no one else has those data assets at their fingertips to be able to develop those algorithms and predictive models.

    Instructure CEO Dan Goldsmith

    Heads would explode. Heads did explode. Heads are still exploding.

    Even so, as I said in my previous post, that was a very fixable problem. Dan was still new. He easily could have played the “new guy” card. A mea culpa, a couple of comments to reporters, and a brief but earnest listening tour likely would have blunted the worst of it. The company could have reset and been in a position to have productive conversations with customers about this thorny set of challenges that they need to face together. Instead, Goldsmith said nothing, and the problem festered.

    In July, Instructure VP of Higher Education Jared Stein wrote a blog post on DIG trying to settle things down and dispell some of the concerns. I trust Jared and, more importantly, Instructure customers trust Jared. He did a decent job in that post, as far as it went. But one blog post by a senior employee, three months later, is not going to undo the damage of such a bad faux pas by the CEO. A CEO trumps a VP. Therefore, a CEO’s misstatement can only be credibly corrected by the CEO. Furthermore, Pandora’s Box had been opened. Because Instructure didn’t jump on the lid the moment they saw it crack open, all the deeply difficult questions about uses of student data in EdTech have come flooding out. The company didn’t lose everybody’s trust, but they lost the trust of enough vocal customers that now they have a persistent problem.

    This too is fixable, but it must be fixed. Some damage has been done to Instructure’s reputation. Enough that a more concerted and sustained effort must now be made which includes actions and not just gestures. But the imbroglio has not yet permanently damaged the company. People have long memories of their experiences with Instructure and personal relationships with employees who still work there.

    Update: Jeff Young just published a piece out about the data concerns in EdSurge. It includes quotes from Instructure’s chief spokesperson Cory Edwards, who I don’t know well but have found so far to be a good actor, and Melissa Loble, a long-time Instructure vet and current SVP for Customer Success, who is exactly the kind of person we should be hearing from directly more often. There’s even a quote from a Thoma Bravo representative. All were responding directly to the data use uproar. So this is progress. But still nothing from CEO Dan Goldsmith. Why EdSurge was able to get Instructure’s prospective PE owner on record but not its CEO, about a problem that was set off by a comment made by that CEO…it’s just mystifying.

    Education needs insight-providing, data-driven tools to help educators better serve a wider range of students who could succeed if only we were offering them the right kind of help. Furthermore, educational institutions need productive partnerships with the private sector to get these solutions out to as many students as possible as quickly as is possible and responsible. But this partnership can only take place in a high-trust environment. Instructure has had the necessary level of trust from their clients to do this kind of work. They have damaged that trust in this particular area. But not beyond repair. There is still a sound foundation, and any cracks still can be repointed.

    This brings me to Instructure’s most compelling product. It is not Canvas. Canvas has only been Instructure’s second-most compelling product.

    Brand, brand, brand

    Most people interpret “brand” as shorthand for a banal series of tactics employed by marketing departments. Academics, in particular, are inclined to load the word with distasteful connotations of shallow window dressing at best and obnoxious disingenuousness at worst.

    Nothing could be further from the truth. “Brand” is another word for reputation. It is who people think you are. It’s how much they trust that you are who you say you are. How much they trust you, period. Brand isn’t a series of tactics. It is the outward manifestation of the character of an organization or individual, as understood by people who have come to know them based on their actions over an extended period of time. Far from being a small set of eye-rolling marketing gimmicks executed by a small set of individuals, an organization’s brand is the gestalt impression that people get from every single interaction they have with every single member of that organization and every single product, website, or other touchpoint. That gestalt is “monetizable” to the extent that people trust the organization to understand their needs and have their interests at heart. They will give you their money if and when they believe they can trust you with it.

    Instructure’s brand has, until now, been its primary and best product. It is still one of the best in the sector, even if it is getting a little ragged around the edges. Because the brand is still good, the company can still build the relationships it needs to make good acquisitions, evangelize those acquisitions to its customers, and work with its customers on even the most sensitive (and important) product research and development efforts.

    That is what I hope for Instructure and why I have expended so much energy writing these last two blog posts. I want to live in a world where EdTech vendors are successful because their customers and partners believe in them. Instructure has been that kind of company. And it still could be.

    But back to the proof of the pudding. In this 21st-Century economy, as the saying now goes, if you’re not at the table, you’re on the menu. Instructure can recover, succeed, and thrive to the degree that the company’s leadership can reignite their customers’ faith that they have a seat at the table. Every decision they make, including financial transactions, should be judged by how it helps or hinders them from doing so.

  • Instructure’s Proposed Acquisition is a Bad Risk for Everyone

    I did not want to write this post. I really didn’t.

    For starters, I’ve been delighted to get away from this sort of corporate analysis and accountability writing, knowing that Phil has it well covered on his blog. That goes doubly for LMS inside baseball. Second, having recently announced a major sponsorship from one of Instructure’s competitors, there’s no way I can write about this topic without the appearance of a conflict of interest, particularly when my assessment is negative. Third, After watching the fights about what the acquisition means breaking out on social media, I have about as much desire to insert myself in the middle of that as I do to stick my index finger into my garbage disposal.

    But people keep asking me to write about Instructure’s prospective acquisition by Private Equity (PE) company Thoma Bravo. And it’s a consequential moment. One of only a very few mainstream LMS providers is at an inflection point. Perhaps more than customers realize. I have become increasingly worried that, by going through with this particular sale at this particular time, there is a very high risk of destroying the company’s value to customers and shareholders alike.

    So here I go. Stickin’ my finger in the garbage disposal.

    In this post, I’m going to explain why I worry the current deal on offer to take Instructure private runs a high risk of being bad for everyone.

    Instructure probably needs to do this at some point

    Let’s start with a basic reality: The reason that Instructure is moving toward a sale to private equity is that the company is at an inflection point and, despite its history of success, could very easily fall apart. Most Instructure customers don’t see this; what they see is a company that keeps growing and, on the surface, doesn’t seem to have changed dramatically. But major shareholders and board members have a different perspective. They see financial problems down the road, and they also see that life under private equity could buy the company the time it needs to address these challenges in ways that staying publicly-traded might not. There is some debate among shareholders about how quickly this move must be made and how to best accomplish it. But I haven’t heard objections from these stakeholders that taking the company private is a bad idea in general. I agree with them on that point. I personally believe that a sale to the right PE firm is probably a good idea in principle, both for shareholders and for customers.

    Instructure’s competitors have made a big deal out of the fact that the company still isn’t profitable after all these years. That’s a bit of a red herring. Instructure has chosen to reinvest profits in the company. When you do that, the “extra” money the company has made from a sale is no longer called “profit.” But that is a choice.

    The real problem is that selling Learning Management Systems is, in and of itself, not a very good business. Yes, Instructure could have been profitable sooner. But not very profitable. The way that LMS companies become financially healthy in the long run—to the extent that they do—is by selling other products and services to their existing LMS customer base. They increase the number of dollars per customer that they earn by selling those customers other things. (We’re going to return to that last sentence later in this post, because even though it is true, it is framed in a way that often leads EdTech Private Equity acquirers to make very bad decisions.)

    Instructure has a strong and growing customer base (even if the rate of growth has slowed recently). That’s why investors are attracted to them. What the company lacks is a portfolio of other products and services to sell. They have a good foundation, but they need to build on it. So there are a few critical questions that I am going to address in this post which are relevant to everyone who wants to see Instructure become more valuable rather than less:

    1. How did the company manage to grow so dramatically for so long?
    2. What does the company need to do in order to avoid breaking the engine that enabled them to acquire and retain customers?
    3. What would a credible plan for increasing Instructure’s future value to customers look like?
    4. What is the gap between a credible plan and what Instructure has presented so far?
    5. Why is that gap bad for current shareholders and dangerous for customers in the context of a potential acquisition?

    Before I get to these questions, though, I want to address a source of anxiety that I am seeing on social media that I think is misplaced. There is a narrow and outdated notion of what PE does that is leading to some unrealistic fears among some concerned academics. While there are real risks to worry about here, it’s important to focus on the fears that are realistic.

    Private equity is…equity that is private

    From a definitional standpoint, a private equity (PE) company purchases equity—stock shares—of the companies it invests in, but it does so outside of the publicly traded stock markets. For many years, private equity companies tended to follow one of only a couple of well-defined playbooks. Sometimes they would be house flippers, fixing up an undervalued house and then turning it over (relatively) quickly for a profit. Sometimes they would be junk dealers, stripping a car with a broken engine for the parts that still had value. Sometimes they would be slumlords, extracting as much “rent” from the asset as they could while putting as little investment in maintenance as they could. While the word “slumlord” is (intentionally) pejorative, some of these models could work out fine for the customers and employees, depending very much on the specifics. More on that in a bit.

    Now that the private equity markets have reached over three trillion dollars (and growing rapidly), there is a lot more diversity in the kinds of investors buying equity privately. Their goals, risk tolerance, and strategies vary pretty widely. There are, for example, family offices where rich people invest their money in individual companies rather than on the public markets. Depending on the goals of the family, the behavior of these funds can be quite long-term-minded and benign. Or not. You just can’t conclude much from the label “private equity” by itself anymore.

    Here’s another way to think about it: Academics tend to be suspicious of venture capital, private equity, and IPOs. Basically, any funding is anxiety-provoking because of the potential strings attached. In Instructure’s case, they earned a spectacular reputation with customers while being venture-backed. They’ve done less well, but not horribly, since their IPO. What can we conclude, then, about the relative badness of VC-backed companies versus publicly traded ones?

    Uh…not much. It comes down to the alignment of incentives between the investors and the customers. Understanding that will help to clarify which fears about this particular acquisition are realistic and which are not.

    Instructure has no parts to fleece

    One concern I’ve read is that the new private equity (PE) owners will sell off parts of the company. To which I reply, Which parts are you worried about them selling off?

    Canvas?

    No. There would be no company without Canvas.

    Arc?

    Are people massively freaked out about the potential sale of Arc? I’m guessing not.

    Portfolium?

    I’m not saying anything bad about the product itself (or any of Instructure’s products), but is all of this hand-wringing about the possible sale of Portfolium? Doubtful.

    Bridge?

    Hmm. Let’s set Bridge aside for a moment, look at a situation with an LMS company where selling off parts actually was a viable business strategy, and then return to it.

    Blackboard’s PE owners sold off CashNet less than a year ago. It was an absolute nightmare for the company’s bread-and-butter education customers.

    Oh, wait. No, it wasn’t.

    Blackboard Learn customers, by and large, didn’t even notice that CashNet was gone. It was an asset that had more value to those customers in the form of the cash that Blackboard got for it than in the actual ownership of the product. This was a case in which selling off a part of the company was both a good strategy from a financial perspective and inconsequential at worst to customers.

    In fact, Instructure is struggling now largely because it doesn’t have enough valuable parts to sell. To anyone, including current customers. The company failed to develop a strong portfolio of products they could “cross-sell.” Going back to Blackboard for a moment, however much people may grumble about them (rightly and/or wrongly), when the conversation shifts to the topic of their Ally accessibility product, eyes light up. It solves a real and important problem. People want it. Current Learn customers want it. Prospective Learn customers want it. Customers who wouldn’t touch Learn with a 10-foot pole want it. Therefore, it has financial value.

    Instructure needs a portfolio of offerings that are compelling as Blackboard’s Ally in order to be financially viable in the long term. Because the company has thus far failed to develop such a portfolio, it developed an alternative growth strategy to sell an LMS into the corporate market instead. And not its existing LMS. No, a new one. Bridge.

    This, frankly, was a dumb idea that was never going to work. Where the LMS is a mission-critical application that inspires passion—positive or negative—from users in the education markets, it is the polar opposite in the corporate markets. Whenever corporate budgets get slashed, Training and Development is the first departmental budget to get hit. And unlike the academic LMS market, there are somewhere in the neighborhood of 173,000 corporate LMS products. OK, I’m exaggerating. A little. But it’s a large enough list that whole companies have been built on writing up catalogs that describe the different LMSs in that market. Not even reviewing them, really. Mostly just listing them all in one place.

    Ask yourself how detrimental it would be for you if Instructure sold off or killed off Bridge. If your answer is “not very,” then you don’t have much to worry about in terms of new owners selling off pieces of the company.

    It’s important to understand that a profit motive and a motive to serve students and educators well are not inherently opposed to each other. They can be. They are almost always in tension with each other. But if the best way to make money is to serve students and educators well, then good results for education can be driven by a profit motive. Money will be more likely to be invested in the right things. I say “more likely” because the other challenge is knowing how to invest that money such that it will be likely to have the net effect of serving students and educators well. My father likes to say, “Never attribute to malice that which simple incompetence can explain.” More on this later in the post.

    The PE acquisition would be to support a return to a focus on education

    One way to read the PE acquisition is as an admission of failure of the Bridge strategy. That is certainly, explicitly, the line that Instructure’s activist investors have been pushing. If you’re worried about the impact of the short-sighted view of PE, then you should also be worried about the quarter-to-quarter pressures of the public markets. Instructure’s Bridge strategy failed to produce the financial results that were promised. One argument for PE acquisition in this situation is that the public markets would not be patient with Instructure as it attempts to recover from this misstep and build the product portfolio that it should have started working on five or more years ago. The right PE firm would give Instructure time to ditch Bridge and refocus on its core market. (That’s you.)

    I don’t know much about Instructure’s PE acquirer, Thoma Bravo. Phil describes their investment style thusly:

    Thoma Bravo is widely known for the “buy and build” acquisition strategy, where a platform company with solid customer base is purchased (often for high price), enabling subsequent acquisitions of smaller companies that have lower price multiples. This is not the same as buying company A and B and combining them; rather, this strategy is based on multiple acquisitions tied to the platform company.

    That fits with what Instructure needs to do to become more sustainable in its core education markets. It needs more educational products to sell. So at first blush, Instructure being owned by Thoma Bravo could be better for customers than Instructure being publicly traded has been.

    Interestingly, though, the current Instructure shareholders who oppose this acquisition also argue that Instructure should return its focus to its core market of education. They just don’t think this particular deal is the best way to do it and are suspicious that there are other, more venal reasons for this particular merger at this particular time. Here, for example, is what Instructure investor Rivulet argued in its SEC filing protesting the merger:

    We invested in Instructure because we admire the company, and we see plenty of opportunity for continued growth and success. With Canvas, Instructure has developed the market-leading learning management software product for the higher education market. The Canvas story has provided an incredible lesson about the success that comes from a focus on innovation, putting students first, and offering a compelling alternative to a greedy incumbent that was run for the enrichment of management and shareholders. Unfortunately, with the announced sale of the company to Thoma Bravo, Instructure is providing a different sort of lesson to its customers and shareholders. Here, it appears that the company has run a rushed strategic review process that was designed to result in a sale to management’s chosen buyer at a low price…in order for management to save their jobs and enrich themselves in the years ahead. It is outrageous.

    Rivulet SEC filing

    In other words, investors both in favor of the merger and opposed to it agree that Instructure is a growth company that has stalled because it has lost focus on its core education markets. They believe the company can continue to serve its shareholders well by serving its education customers well. The debate among them is over whether this deal was really designed to serve those customers (and thus generate profit for shareholders), or whether it was corrupted by an agreement that exchanged preferential treatment of Thoma Bravo in the bidding process for particularly rich compensation for Instructure CEO Dan Goldsmith and his sister, who Goldsmith hired as a senior executive of the company.

    I will not write about the details or the merits of those accusations in this post. That’s not e-Literate‘s beat anymore, and I have no insights to offer about them that would add any value. If you want to read more insightful and in-depth coverage of that fight than I could offer, then go read Phil Hill’s coverage.

    Rather than speculating about motives or analyzing the finances, I am going to write about strategy and execution. Does Instructure’s current executive team have a credible strategy and a strong track record of execution that is consistent with its previous, incredibly successful strategy for growing and retaining its installed base? And does it have a credible, market-validated strategy for increasing the value that it provides to its customers such that customers will likely be willing to pay more for that value? If the answer to these questions is “yes,” then current shareholders can have increased confidence that they will receive a good price for their shares while the end users of Instructure’s products and services can have increased confidence that they can continue to count on the company to serve them well.

    Unfortunately, it looks to me like the answers to these questions are “no.”

    Why Instructure has succeeded—and failed—to date

    We have long argued at e-Literate that Instructure came to market with three critical advantages that incumbent competitors were slow to see and which were difficult, time-consuming, and/or expensive for them to replicate. Those advantages are as follows:

    1. Reliability (implemented as cloud-native infrastructure)
    2. Ease of use (implemented as a rethink and redesign of existing LMS functionality)
    3. Customer rapport (implemented through a variety of formal and informal ways and tied together by a strong company culture)

    These three advantages can be collected under one unifying strategic insight of the original executive management team: They brought a consumer software sensibility to what had been treated by incumbent vendors as an enterprise software business.

    Instructure understood who their customer really was in a changing market

    For readers who are not software industry aficionados, one way to get at this difference is to ask yourself a few questions about software products being used at your institution that are generally treated as enterprise software products. How involved were you in selecting your registrar software? How broadly and intensively were different stakeholder groups involved in the selection process? Who made the final decision? Do you even know the answers to any of these questions? Do you know how the decision was made?

    Generally speaking, registrar software is part of a larger package of software that includes modules for things like payroll and expense tracking. There is usually a very small group of people who both make the decisions on the procurement of such software and who also decide who else will have input on the process. This is typical with enterprise software selection—even for critical enterprise software that has many end-users who depend on it and use it daily. For enterprise software companies, their customers are those few decision-makers. They only have to care about reliability, ease of use, and end-user happiness to the degree that the decision-makers do. And often, those decision-makers have other priorities, like cost, or arcane but important support for regulatory requirements, or making their bosses happy in some way.

    In the early years, LMSs were procured like enterprise software. CIOs generally selected the LMS vendor and decided on whose input they would take when making their selection. But by the time Instructure came on the scene, that was changing. Faculty were much more intensively involved with LMS selection, and it was not unheard of for a university to form a student advisory committee or conduct focus groups as part of the selection process. Instructure made and kept three promises to these stakeholder groups. First, they would build and run the LMS such that it would be extremely unlikely to go out for two weeks at the beginning of the semester or in the run-up to finals week. Second, it would be less painful and time-consuming to use than the alternatives which existed at the time. And finally, end-users would be treated as human beings, with good customer service and both visibility and input into the product roadmap.

    Given the pedigree of the executive team at that time, these changes should not be surprising. CEO Josh Coates’ previous gig was running Mozy, a startup that was essentially the precursor to Dropbox. Think about what life was like trying to back up or share locally stored files across multiple devices before Dropbox. There was FTP. There were email attachments. And there was Sharepoint. But in order for a Dropbox product to replace those well-entrenched incumbents, it had to be rock-solid reliable, be dead simple to use, and feel completely approachable and safe.

    Instructure has been spectacularly successful not because it has been a great education company but because it has been a great consumer software company. And the early management team was very clear about this distinction. Here’s what I wrote in a 2012 post:

    The founders of Instructure aren’t educators, and they think that’s a good thing. The way they see it, educators tend to build software that solves their own problems from their own perspective, and the results are often idiosyncratic. As technologists coming in with no strong opinions about how teaching “should” be done, the Instructure leadership feel they have an advantage of humility and open-mindedness when considering solutions. As CEO Josh Coates put it, educators “are experts in their context. But their context is one or two classes in a specific university in a specific part of the country. Software developers don’t even pretend to know the domain.” So they have to go out and do the research. Instructure co-founder Brian Whitmer added, “And we know that we have to do it. We know that we have to validate it against a bunch of different people.” And they do. Instructure, as a company, is extremely attentive to the conversations among educators, to the point where they have Twitter feeds from various ed tech folks sucked right into the IRC channel that all their developers use for internal communications. They do their homework.

    Educators tend to get hung up on the profit motive and, ironically, miss the disciplinarity of starting a company. Co-founder Devlin Daley talked about a “new style of development” that was “not true in the ’90’s,” and all three of them talked a lot about Agile development. As they see it, a lot of companies that implement Agile miss the fundamental aspect of the methodology that is about getting closer to customer needs.

    e-Literate, “What Are Ed Tech Entrpreneurs Good For?

    Instructure lost its way after solving the obvious problems

    In a lot of ways, Instructure got a big leg up by being late to the market. The product category was well defined through the experiences of the early incumbents. Does an LMS need a gradebook? Definitely. A test engine? For sure. A blogging system? Ehh…. Instructure’s product team could go to a lot of people who were already using LMSs and ask them, “What do you hate about this thing and what are you really trying to accomplish that is possible but painful in it?”

    And, in fact, that is exactly what Instructure did. They figured out what problems people were trying to solve when they used an LMS and then, rather than building yet another, more feature-packed version of the same tool, they set out to build solutions to those problems. For example, they figured out that instructors who were entering grades wanted to do so as quickly as possible and focus their energy on adding educationally useful comments. So rather than cramming more features into the same spreadsheet-style gradebook that every other LMS had implemented, they built SpeedGrader, a novel user experience that helped instructors focus on the aspects of grading that they cared about while moving other functions out of the way. Why should instructors have a grade curve-setting widget taking up screen space when they’re trying to comment on a student’s paper?

    But once Canvas had caught up functionally with the other LMSs, Instructure seemed to run out of ideas. Internal to the LMS, we haven’t seen many truly major customer-facing improvements in the past four years. In fairness, Instructure claims to have been doing a lot of under-the-hood work that will yield future benefits. But I’m still fairly unclear on what those future benefits will be.

    Meanwhile, what new customer problems have they solved outside of the LMS? What new products have they given us?

    Arc. They gave us Arc. A lecture capture tool. Another lecture capture tool. Is it good? Yeah, it’s pretty good. Did it set the world on fire? No, it did not.

    I don’t want to overplay the we-don’t-need-another-one-of-those card, because Canvas itself could have been dismissed on those grounds when it first came out. In fact, it was dismissed on those grounds. I, personally, dismissed it on those grounds.

    Nor is it the only example of such a product. Not by a long shot. Consider Zoom. It dominates the webconference market, both in education and elsewhere. How did that happen? Cisco already had a very mature and very widely adopted product in Webex. Google had Hangouts. Adobe had Connect. Blackboard had the education-specific Collaborate solution. There are multiple open source options, like Big Blue Button. There are other options like GoToMeeting and Bluejeans. There was no good reason to believe that a startup with yet another webconferencing solution would survive, nevermind thrive.

    And yet, it did.

    Why? This is the critical question for Instructure to both maintain its current strength and build new ones. Maybe Instructure just got lucky by coming in when they did. Maybe they weren’t nearly as talented as they seemed to be. Humans tend to over-credit skill and under-credit timing and luck.

    Even so, I don’t believe that luck and good timing were the primary reasons for Instructure’s success. Permit me to repeat a snippet from the quote above of my 2012 post:

    Co-founder Devlin Daley talked about a “new style of development” that was “not true in the ’90’s,” and all three of them talked a lot about Agile development. As they see it, a lot of companies that implement Agile miss the fundamental aspect of the methodology that is about getting closer to customer needs.

    I believe Instructure had an approach to building their business that worked. They lost some mojo because, among other reasons, the pressure for them to grow pushed them into flattening what had been a philosophy and corporate culture into something closer to a paint-by-numbers formula. This is one reason why sales have slowed. Instructure is no longer performing as a truly great company. And if they don’t find their mojo again before they enter into an acquisition, then things are far more likely to get worse—possibly catastrophically worse—than they are to get better, because building a culture of product development excellence is not one of the things that PE knows how to do well. Whatever patterns are there when the company is purchased are likely to stay. Whatever direction the CEO has set will stay. And without the bulwark of leadership protecting a strong culture of excellence, the tendency to paint by numbers is likely to get worse rather than better. PE firms may or may not understand education, but they all understand numbers and find a high level of comfort in them.

    Product-led Growth

    Back when Instructure was being started, the software product development buzzwords were “Agile” and “Lean.” Today, a new buzz-phrase that also fits with that quote above is “product-led growth.”

    “Product-driven company” can be defined narrowly or broadly. The narrower version involves some fremium model where people adopt a free version of the product through a self-service process, use it a lot and, once again through self-service with no human salesperson involved, upgrade to a paid version. Zoom works like this. So does Dropbox. I had a free Dropbox account for a long time. To borrow a phrase from Apple, it “just worked.” I used it to the point where I needed more space. So I paid for an upgrade. At peak Dropbox for me, I had a personal paid account as well as a larger one for my company.

    Spreadsheet jockeys like product-driven companies because they have low sales and marketing costs. People adopt the product because it’s easy to do so. It spreads because people tell their friends and colleagues about how good it is. It makes money because people love and use the product so much that they will pay for an upgrade. The customers do much of the sales and marketing work and pay for the privilege.

    But as with Agile, people who implement a product-driven company design miss the fundamental aspect of the methodology that is about getting closer to customer needs. And again, Josh Coates’ last gig before becoming Instructure’s (previous) CEO was building the precursor to Dropbox. There wasn’t a big self-service component to Canvas sales, but the core philosophy of creating a customer experience that carries a lot of the sales and marketing load by inspiring fanatical loyalty was there.

    At least, it was there in the beginning, and for quite a while. It has been less evident in recent years. When a company is under pressure to grow, either financially or just to scale up to meet the needs of new customers that are walking in the door, it is easy to slip from a focus on finding new problems to solve toward one of finding new things to sell. In EdTech, there aren’t many obvious things to sell, particularly “at scale.” Painting by numbers under these circumstances is a weak strategy that fails often.

    But education has many, many problems to solve. If you have a strong rapport with your customers, a really solid team of education specialists who understand the complex nuances of educational problems, and a leadership team that is absolutely committed to growing by understanding their customers’ needs better than anyone else does, then you can find ways to make money by solving new problems. Product-driven companies are problem-driven companies.

    A good example of solving new problems is Blackboard’s decision to acquire Ally. Was there a healthy, established product category for an educational content accessibility checking platform that would be sold to colleges and universities? Absolutely not. Could anyone calculate the total addressable market (TAM) for such a product without wildly guessing? Not in any way that I can think of. Were Blackboard’s customers begging them to build and sell such a product? I very much doubt it, since there really wasn’t any such thing on the market.

    But Blackboard saw that the little startup that had found this problem to solve. I’m sure they talked to Ally’s customers—and their own—about it to make sure that it was a real and large problem, solved by the product in a useful way. And they made a bet. It’s turning out to be a good one.

    In retrospect, you could argue that the product is adjacent to Blackboard’s LMS business. But almost everything in EdTech is adjacent to the LMS because almost everything has to connect with it or work with it. If you had grabbed a random EdTech mid-level manager off the street and asked them for their top suggestions for hot product categories that are adjacent to the LMS, I doubt that learning content accessibility would have shown up on anybody’s list. This is the kind of thinking that made Instructure, and it’s the kind of thing it needs to be doing again if it wants to find its next leg of growth while holding off its newly resurgent competitors.

    So who did Instructure’s board hire to lead the charge at this critical moment to reinvigorate that deep culture of devotion to solving the problems of the end-users? A guy whose last job was running a company that sold enterprise software to life sciences companies.

    Now, Dan Goldsmith is not his résumé. He’s a multidimensional person who is capable of learning. (And to be fair, Josh Coates was not an obvious candidate for the job either.) But Dan has been in his current job for less than two years. In order for him to establish that he is up to this challenge in this industry within that length of time, he would have had to perform extraordinarily well. This is vital right now because the very same shareholder ballot they are voting on to accept Thoma Bravo’s offer would also change Dan’s compensation package to one that would attempt to lock him in with a very generous amount of stock that vests over time. If Instructure’s board and shareholders have decided that now is the time to go private, with this CEO, then they need to be very confident that he will deliver. If they are not, then the customers are under increased risk, the new owner is under increased risk, and the current shareholders are less likely to get attractive competing bids for their shares.

    Has Dan Goldsmith met this high bar in the brief 20-month period that he has been on the job?

    In my opinion?

    No.

    A case study in the opposite of what Instructure needs to do

    Instructure hasn’t made a lot of significant moves in the education space since Dan took the helm. Off-hand, I can think of two. The first was the acquisition of Portfolium. In and of itself, that’s not an obviously genius move. The ePortfolio product category has been around almost as long as the LMS product category and has been a hot seller since…uh…never.

    It could turn out to be an interesting move. Instructure has to bet that (a) potential trends like comprehensive learner records or stackable credentials will turn into something more substantial and that (b) an ePortfolio in general and this ePortfolio, in particular, provides a good infrastructure from which to start supporting those trends. I’m troubled by the fact that I’ve not heard an articulation from the company about their vision for the product. Dan made some comments about the potential for cross-selling. But those comments characterize Portfolium as a thing to sell, not as a solution to a customer problem. I simply don’t know what they’re thinking with Portfolium.

    The other move was Dan’s announcement about their DIG learning analytics initiative in the spring of 2019, which Phil covered in his own inimitable way:

    The second initiative announced on the earnings call was DIG, a strategic move with data and analytics.

    “I am also pleased to share with you an early insight into our second growth initiative focused on analytics, data science and artificial intelligence. The code name for this initiative is DIG. And this technology platform combined with the most comprehensive SaaS database on the educational experience uniquely positions us to deliver meaningful value to our customers. And from a growth perspective, DIG has the potential to double our TAM in education.”

    Instructure started ramping up their data and analytics efforts (again) about a year ago, although the focus was described at the time as being about internal analytics – that is, making Canvas a better and more valuable LMS product. From what I have heard the product validation for DIG are consistent with this message – dashboards, surfacing useful data within a workflow, etc. But that was not how DIG is being sold during the conference call [emphasis added].

    “We’ve been working on the scaffolding for [DIG] for well over a year now. I mentioned in our remarks that we already have product validation towards out there in the market. We have instructors and students consuming output from some of the initial experiments with DIG. And we anticipate later this year obviously to make more announcements around specific products and offerings and how we bring them into the market. DIG ultimately is a platform first and foremost based upon machine learning and artificial intelligence. I believe that any multi tenant SaaS company born in the cloud has the opportunity once they hit a certain market share. And in fact, it may even be incumbent upon those organizations to partner with the industry and evolve that industry with new insights and predictive modeling using AI and ML. That’s what DIG is at its heart.

    This is brand new behavior for Instructure as a company. Previously the company was reticent to talk much about non-released products, but now they are talking not just about a new initiative, they are touting buzzwordy machine learning and artificial intelligence and predictive modeling well before any of those capabilities exist or are in customer hands. Goldsmith further clarified the DIG plans during the investor conference discussion [starting at 9:00, emphasis added].

    “We already have analytical capabilities in our Canvas platform. I want to be really clear and delineate the difference between an analytics and reporting capability, and a machine learning and AI platform. [snip]

    “We have the most comprehensive database on the educational experience in the globe. So given that information that we have, no one else has those data assets at their fingertips to be able to develop those algorithms and predictive models.”

    Goldsmith then described an example of predicting a student’s expected performance in a class and how that prediction reliability goes up over time. Then we get the vision.

    “What’s even more interesting and compelling is that we can take that information, correlate it across all sorts of universities, curricula, etc, and we can start making recommendations and suggestions to the student or instructor in how they can be more successful. Watch this video, read this passage, do problems 17-34 in this textbook, spend an extra two hours on this or that. When we drive student success, we impact things like retention, we impact the productivity of the teachers, and it’s a huge opportunity. That’s just one small example.

    “Our DIG initiative, it is first and foremost a platform for ML and AI, and we will deliver and monetize it by offering different functional domains of predictive algorithms and insights. Maybe things like student success, retention, coaching and advising, career pathing, as well as a number of the other metrics that will help improve the value of an institution or connectivity across institutions. [snip]

    “We’ve gone through enough cycles thus far to have demonstrable results around improving outcomes with students and improving student success. [snip] I hope to have something at least in beta by the end of this year.”

    Wow. Robot tutor in the sky – meet the new kid on the block.

    For those readers who don’t follow the sector broadly, Phil’s reference to a “robot tutor in the sky” is from an infamous quote by the CEO of now-defunct Knewton that they liked to think of their product as “a robot tutor in the sky that can semi-read your mind.” In other words, Phil is accusing Goldsmith of using tone-deaf language that would be explosive to educators. And sure enough, it pissed a lot of people off. They didn’t like the vague hype, and they didn’t like the seemingly out-of-the-blue implication that students’ data from their in-course activities would be used without their permission for Instructure’s product development purposes. As I mulled whether and how to write this post, I received the following reply on Twitter to my retweeting of one of Phil’s posts on the topic:

    OK, OK, so somebody on the internets wrote a mean thing about Instructure’s DIG strategy. And is still upset nine months after the announcement. Maybe that evidence doesn’t persuade you (particularly if you don’t know who Laura Gibbs is).

    How about this?

    That’s a Twitter thread from Canvas end-users who are crowdsourcing a letter encouraging their institutions to lobby Instructure shareholders about Instructure’s lack of legally binding data privacy policies. Now, the authors had voiced a range of concerns in the last draft (plus comments) that I looked at before writing this post. Some of them may have been poorly phrased, overblown, or factually questionable. But others were unquestionably legitimate, sophisticated, and serious.

    Update: The authors of the letter have posted the most recent draft here, and a signable petition here.

    I see three big take-aways from this letter which are most important for our current purposes. First, this is the first time in my long history of covering EdTech that I have ever seen educators undertake such an effort to influence shareholders. The last company I would have expected to inspire this level of concern-driven activism is Instructure. And the existence of it strikes me as one of the most singular and remarkable milestones of Goldsmith’s tenure to date. Trust me: This should be taken seriously.

    Second, one reason this foment continues to build nine months after Dan’s original comments about DIG is that, at least to my knowledge, Dan himself has yet to address these customer concerns directly, publicly, and credibly. Even in this Twitter thread, he leaves the job to an anonymous PR person to desperately try to tamp down the anger. At this point, given what’s at stake, he should be making a direct personal statement as the CEO of the company. If not on Twitter, then on the company blog. Or somewhere. Anywhere.

    Finally, the authors of the letter make clear they understand that there are no obvious, well-trodden solutions to the student data privacy conundrum. They request some specific steps at the end of their letter, but they don’t pretend that these steps solve the complex, pervasive, and important challenges that universities who work with EdTech products face. They are struggling to balance the need to protect student privacy against the affirmative ethical obligation to learn how to better help their students succeed.

    THIS IS A PROBLEM THAT CUSTOMERS NEED HELP SOLVING.

    Instead of either assuming a defensive crouch about DIG or ignoring complaints altogether, Instructure could be listening to customer concerns with an ear toward making money by serving them better. This is a hard and important problem space that will not be solved without active participation by vendors. There have been academic convenings on the student data privacy challenge by groups like Asilomar. They do critical work. But they are not enough. There are initiatives by industry groups like IMS. They too are necessary but not sufficient. This is an important and growing problem, which makes it an important and growing commercial opportunity for a vendor that can actively partner with academia in finding a solution to it.

    Dan Goldsmith could have easily turned his faux pas into a moment of leadership. There is even precedent from Instructure for this under strikingly similar circumstances. I encourage you to (re)read Phil’s 2015 post on how Josh Coates handled customer complaints about the company charging universities for access to their own students’ data. The short version is that once Josh became aware of customers’ unhappiness, he took it as an opportunity to engage with them, changed the policy, published a mea culpa post on the company blog, and encouraged Phil to independently verify with the customers that their concerns had been addressed.

    Dan’s comments were significantly less serious than the implemented commercial practice that Josh had to correct. He could have easily addressed them. And there is a real problem space here that cries out for product development. EdTech needs an architecture of privacy. Instructure’s customers are being very direct about their needs and concerns. The company even has access to multiple academic experts who could help them think through the nuances of the problem. I know this for a fact because I introduced Instructure employees to those experts last spring when I urged them to turn the DIG situation around by taking leadership.

    That was over half a year ago. And now we have customers banding together to lobby shareholders about their continuing dissatisfaction. Because apparently, they have come to the conclusion that the company leadership is not listening to them.

    No. I would not bet the company on the 20-month record of Dan Goldsmith’s leadership and articulation of strategic direction. Maybe things will be different six or twelve months from now. But at this point, he has neither embodied nor provided a sound investment thesis. There is no strong reason to believe that Instructure, sold to private equity under this leadership at this moment, would be able either to continue to grow market share of its core product or to develop new solutions to real customer problems that would lead to greater profitability.

    Just how bad it could get

    I want to wrap up this post with a couple of hypothetical but plausible examples of just how bad things could get when an LMS company with no products to cross-sell and no customer-focused, problem-solving leader sit down in a room with PE owners who have big ambitions, a lot of money, and limited experience in the space. A player like Thoma Bravo is going to make acquisitions. If they make a number of small bets that don’t pay off, then there are likely to have to cut costs and raise prices to make up for their losses.

    But what I really worry about are the kind of colossal mistakes that can happen when a CEO who doesn’t know education and investors who don’t know education lock themselves in a room together and try to come up with something really big. Phil noted in a recent post about Thoma Bravo,

    Another point in the Forbes profile is that Thoma Bravo does not acquire a company and then figure out what other companies to tuck-in or combine [emphasis added].

    “Like a good tennis player who’s worked relentlessly on his ground strokes, Bravo has made private equity investing look simple. There are no complicated tricks. He figured out nearly two decades ago that software and private equity were an incredible combination. Since then, Bravo has never invested elsewhere, instead honing his strategy and technique deal after deal. He hunts for companies with novel software products, like Veracode, a Burlington, Massachusetts-based maker of security features for coders, or Pleasanton, California-based Ellie Mae, the default system among online mortgage lenders, which the firm picked up for $3.7 billion in April. His investments typically have at least $150 million in sales from repeat customers and are in markets that are too specialized to draw the interest of giants like Microsoft and Google. Bravo looks to triple their size with better operations, and by the time he strikes, he’s already mapped out an acquisition or turnaround strategy.

    Instructure fits into this playbook, and I suspect that we won’t have to wait long to see the next move. It could be tuck-ins in the vein of Portfolium, Practice, or MasteryConnect, or it could be something bigger and market-changing. It is worth noting that Bravo raised $12.6 billion in January of this year – the stakes are getting higher.

    What would fit into the category of “bigger and market-changing”? I can think of only two plausible acquisitions, particularly since Thoma Bravo seems to be disinclined to invest in people-heavy businesses like OPMs or textbook publishers. Either one of these ideas would be so incredibly, mind-bogglingly stupid that I’m hoping this part of the post is just good for laughs. (Or maybe a Halloween-style scare. Boo!)

    The first possible merger target is Ellucian which, as Phil has pointed out, has put itself up for sale. On the spreadsheets, this could look like a great prospect for Instructure. They sell to the same client base, have a big installed base, a portfolio of products to cross-sell, and have a massive lock-in.

    Anyone who actually knows EdTech and is thinking from a product-led perspective would see this as the obviously terrible idea that it is.

    In general, the SIS market is a smoking ruin that will take at least another half a decade to move itself into the cloud. The technological heritage and history of the product category conspire to make Ellucian—and their competitors—about the furthest thing from a product-led company possible. Think about how hard it was for Instructure’s competitors to make the transition they needed to make in order to catch up. Now multiply the challenge by a kajillion. Combining Ellucian with Instructure would be a disaster.

    The only worse idea I can think of that might somehow seem plausible to the wrong people having the wrong conversation at the wrong time would be for Instructure to buy—are you ready for it?—Blackboard. Again, from a paint-by-numbers perspective, it makes perfect sense. Instructure could buy Blackboard’s remaining customer base very cheaply, along with its more successful portfolio of cross-selling products. (Their Ally accessibility platform, for example, is a well-deserved smash hit.) And since Blackboard is close to having zero financial value, with their debts being close to the intrinsic value of their assets, the sellers could unload an investment that is no longer performing for them while the buyers could get assets they need practically for free.

    And in the process, Instructure would acquire the worst brand in the product category—which is an improvement from when they were the worst brand in the history of the sector—by applying the most infamous and most loathed business strategies of their infamous former Blackboard CEO Michael Chasen—namely, buying up one of the few competitors in the market. Instructure could literally become the new Blackboard. In doing so, they would utterly destroy one of the greatest brands in the history of the sector instantaneously.

    These guesses must be wrong. (Dear Lord, please let them be wrong.) Think of them as hypothetical examples of “really, Michael, how bad could it get?” than as actual predictions. I have to believe that the board, the executive team, and Thoma Bravo would not be that dumb. But the point is that of those three entities—the board, the financial owner, and the CEO—the only one we would reasonably expect to know how bad such decisions would be in practice, the only one that all parties must be able to count on to steer the ship away from the many rocks and icebergs in EdTech, is the CEO.

    Has Instructure provided customers with a detailed and credible enough strategic roadmap to inspire confidence that they have a more compelling alternative for growth? No, they have not. Has Dan Goldsmith thus far proven, lacking such a roadmap, that his reputation for performance alone is worth betting the company on? No, he has not. No smart PE company would make an attractive counter-offer under these circumstances. There is no sound investment thesis until Instructure is able to regain its footing as a product-led company.

    Instructure has been one of the best run, most consequential companies in the history of EdTech, and it could be again. It has not yet experienced the talent flight that would make a turn-around much, much harder. But until it has both a credible strategy and a leader who inspires customers to trust the company with their most pressing and complex problems—like fulfilling their ethical obligation to protect their students’ privacy in an era of digital learning—it will be just another EdTech company that is toiling away in an unprofitable product category and promising investors that it will somehow spin straw into gold.

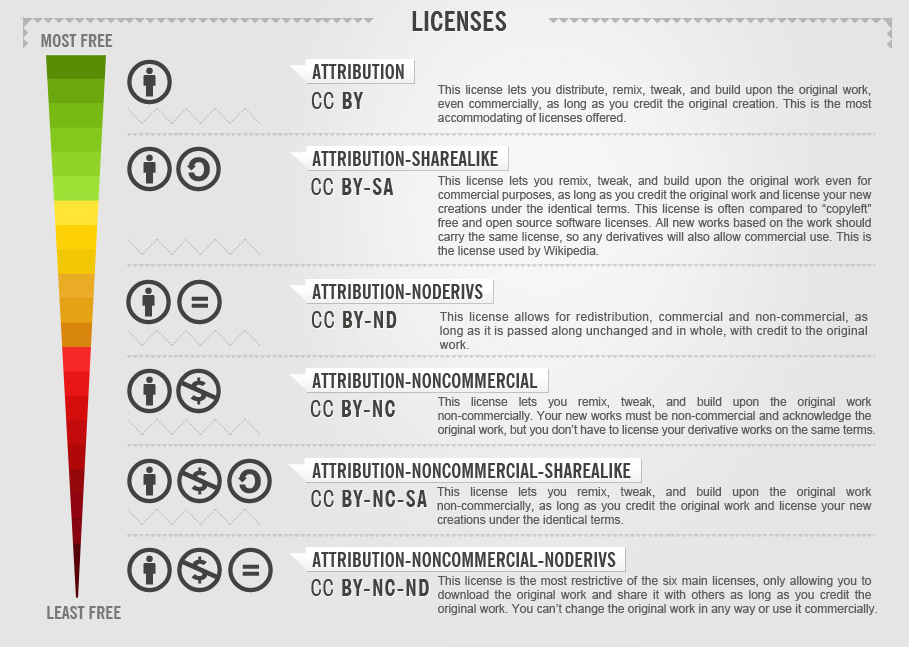
  • Instructure is not “the New Blackboard”

    Instructure is not “the New Blackboard”

    Yesterday, I wrote about my experiences at the recent IMS Learning Impact Leadership Institute. Today, I’m going to write about a sentence that I heard uttered several times while at that summit. One that I’ve been expecting to hear for nearly a year now.

    “Instructure is the new Blackboard.”

    It’s not the first time I have heard that sentence, but it has reached critical mass. I have known it was coming since last Instructurecon. I wrote a blog post specifically to prepare for this entirely predictable moment. It has finally arrived.

    And now it is time to explain why nobody should ever say “X is the new Blackboard” about any company ever again.

    Predicting the inevitable

    I have often characterized Instructure’s first decade of customer relations as “gravity-defying.” Once or twice, I have had people challenge me on the blog about that characterization. “Why are you rooting for them to fail?” they would ask. But I wasn’t. I was merely observing that gravity exists, and nobody can defy the laws of physics forever. What goes up eventually comes down. And in ed tech, any fall is a fall from grace. As a rule, educators are distrustful of ed tech companies, are really distrustful of large ones, and are bitterly resentful of companies that disappoint them. At some point, Instructure would have to slip from abnormally good and revert to mean. And when that happened, there would be blowback.

    It was clear that moment had arrived at Instructurecon 2018 because Instructure was no longer able to pull off the impossible. Josh Coates keynotes should have been impossible. Josh is a smart, interesting, thoughtful guy. He is not a good keynote speaker. He rambles. He careens. He talks about what he cares about, and what he thinks you should care about, but doesn’t give a lot of thought to what you think you need to hear from him. And yet, somehow, his Instructurecon keynotes came off as charming and fascinating. Nobody cared that he said not one damned thing about anything that every other LMS company CEO would have been shredded by their customers for not covering. He was like some funhouse mirror version of Mr. Rogers.

    Until 2018, when his keynote was a disaster. It wasn’t just that the quirky charm failed to work this time. Josh offended multiple groups in the audience. What goes up must eventually come down.

    Then there was Josh’s fireside chat with Dan Goldsmith, then the newly announced President. It was obvious to Phil and me that Dan was being introduced to the customers because he would be CEO within a year. Gravity-defying Instructure would have somehow magically helped the audience understand that they were being introduced to the line of succession while being reassured that things were steady-as-she-goes. But that would have been a near-impossible feat to pull off, and the Instructure of 2018 walked on the earth like you and me. So the audience reaction was, basically, “Uh, he seems nice, but why do I need to hear about how he was an Uber driver for a while?”

    There were also smaller signs, and other facts from which one could draw inferences. There was the small but noticeable reduction in spending on the conference. There was the increasing pressure from the stock market for Instructure to grow their sales of Bridge to corporations. The dominos had already started falling, and the pattern was set for the next ones to fall in a certain order:

    • Josh would leave soon. Other executives and senior managers would likely leave as well. Some would go because they had had a good run and were ready to move on. Others would go because Dan would want to put his own team in place.
    • Instructure was built around Josh, who is an idiosyncratic leader. It was also built to sell to higher education. In order to retool it so that it is something that can run well under Dan’s leadership style and sell into higher education, K12, and the corporate market, many things would have to change internally. People would move around. Some people would leave. Others would arrive. Processes would change.
    • All of this would be distracting to people who are trying to do their jobs. Things inevitably would fall through the cracks. Some of those things would be important to some customers. Those customers would notice.
    • All of this uncertainty would inevitably create some trepidation among the employees, even if the new management handles the situation beautifully. The fact is that when people are no longer sure what their job is or how they can be successful at it, which is inevitable in this kind of environment of change, they tend to keep their heads down until they figure it out. They may not challenge decisions that they think are on the wrong track.
    • Meanwhile, some of the new senior management, crucially including the CEO, were new to education and wouldn’t know where the landmines are. And there are many, many landmines. It wouldn’t matter how smart the new people are. It wouldn’t matter how decent and kind they are. Since they wouldn’t know where the landmines are, and their people would be likely too nervous or distracted to warn them, then sooner or later they would step on one.

    In March of this year, Dan Goldsmith said this:

    What’s even more interesting and compelling is that we can take that information, correlate it across all sorts of universities, curricula, etc, and we can start making recommendations and suggestions to the student or instructor in how they can be more successful. Watch this video, read this passage, do problems 17-34 in this textbook, spend an extra two hours on this or that. When we drive student success, we impact things like retention, we impact the productivity of the teachers, and it’s a huge opportunity. That’s just one small example.

    Our DIG initiative, it is first and foremost a platform for ML and AI, and we will deliver and monetize it by offering different functional domains of predictive algorithms and insights. Maybe things like student success, retention, coaching and advising, career pathing, as well as a number of the other metrics that will help improve the value of an institution or connectivity across institutions. [snip]

    We’ve gone through enough cycles thus far to have demonstrable results around improving outcomes with students and improving student success. [snip] I hope to have something at least in beta by the end of this year.

    That quote is pulled from Phil’s contemporaneous post on the statement, where he then goes on to reference the “robot tutor in the sky.” But Dan probably wouldn’t have gotten that reference, because he wasn’t in the industry at the time that former Knewton CEO Jose Ferreira made it. As a result, his own statement, which was predictably explosive to Phil and me, probably seemed somewhere between anodyne and exciting to him.

    So. You have an ed tech company that has spectacularly over-performed for a decade. Their performance slips, not to horror show levels, but to levels where some customers are noticeably unhappy. The company leadership makes a tone deaf statement or two about unreleased products that we really don’t know that much about.

    And that is all it takes to become a fallen angel in higher education ed tech. There is likely no way that employees at Instructure who have only ever worked at that one ed tech company could have known that to be true in advance of having experienced it. There is likely no way that executives coming in from outside of ed tech could have known that to be true without having experienced it either. Because it doesn’t make sense. But it is true. Instructure’s brand was destined to crash hard precisely because it was so good. That’s how it works in ed tech. Cynics are disappointed optimists, and we have a lot of those.

    But why, specifically, “the new Blackboard?” It’s not the first time I’ve heard that phrase used about a company. And really, it’s unfair to both Instructure and Blackboard. In fact, when I wrote in my last post about how some companies that used to be barriers to interoperability work now are among its most important champions, I was specifically thinking of Blackboard. The complaints I’ve had about them in recent years have been related to (1) trying to spin their financial challenges and (2) struggling to execute well during an extraordinarily tough transition. In other words, totally normal company stuff. Today’s Blackboard may not be perfect, but it is basically a decent company. In the moral sense.

    This sector has a lingering revulsion for a version of a company that ceased to exist in 2012–at the latest—and yet continues to loom as a shadow over the entire vendor space, creating a sense of ever-present subconscious dread. It’s like having a lifelong fear of clowns from something that happened at a circus when you were three years old but that you can no longer remember.

    It is time to remember.

    The personal as parable

    As I described in a recent post, my public debates with Blackboard over their patent assertion are something of an origin story for e-Literate. There is a lot about the story that I’m going to tell now—some of it for the first time on the blog—that became personal because certain parties at Blackboard chose to make it personal. Throughout that period, and through my writing since, I have tried to keep e-Literate professional and focused only on details that are worth sharing insofar as they advance the public good. I have not always succeeded in that aspiration, but it is important to me to try.

    Today I choose to share some actions that were taken against me because I think it is important to understand how truly bad actors behave. These are not the kinds of actions that either Instructure or today’s Blackboard would take. If the sector is going to improve, then we need to get better at distinguishing between bad behavior, which can have a variety of causes and can be corrected through engagement, and truly bad actors, with whom there can be no negotiating. In my experience, truly bad actors are rare.

    So I’m going to share some personal experiences later in this blog, but I’m going to try to keep this as minimally personal as I can. When possible, I’m going to avoid naming names, even though some of you will know who I’m talking about. I will share some details but not others. What I ask you to think about as you read my portion of the story is not what happened to me or who did what but how what happened then is qualitatively different from what is happening now.

    The old Blackboard

    The period of Blackboard’s history that I am talking about is specifically from roughly 1999 to roughly 2012 (or 2009, depending on how you mark the end of the era). During this period, the company carefully developed a carefully crafted and highly successful business strategy. First, they were pioneers in the software rental business. You didn’t own Blackboard software, even if you ran it on your own servers. You paid an annual license fee. I can’t say that Blackboard invented this strategy—I’m not sure who did; it might have been Oracle—but Blackboard certainly drove it deep into the education sector.

    This could be a handsomely profitable business model, particularly if they could hold market share and maintain pricing power. Which brings us to the second leg of their strategy. Blackboard sought to dominate ed tech product categories by buying up every vendor in the category as soon as it reached significant market share. Here’s how that looked in the LMS product category:

    • In 2000, they acquired MadDuck Technologies, which made Web Course in a Box
    • In 2002, it was George Washington University’s Prometheus
    • In 2006, WebCT (which had spun out of University of British Columbia but had been independent for a while)
    • In 2009, ANGEL Learning from IUPUI
    • In 2012, after reportedly failing to buy Moodle Pty, the company bought Moodlerooms and NetSpot, the biggest Moodle partners in the US and Australia respectively

    The reason that Phil’s famous LMS market share graphic is called the “squid graph” is because Blackboard formed the body by continuously gobbling up competitors as they formed.

    In every case except Moodle, Blackboard would kill off the acquired platform after acquisition. They weren’t really looking to acquire technology. To the contrary; they didn’t want the expense of maintaining multiple platforms and showed almost no interest any of the technical innovation until after the ANGEL acquisition, when Ray Henderson started driving some of the product strategy for them. Rather, Blackboard was interested in acquiring customers. They knew that some of those customers would leave—in fact, some of those customers had already left Blackboard previously to the platform that was now being acquired—but that was OK. Because by keeping competition low and competitors under a certain size, Blackboard was really controlling pricing power. LMS license fees were, not coincidentally, significantly more expensive during this period than they are today.

    There was one company—Desire2Learn—that represented an increasing threat to Blackboard but would not sell. So Blackboard tried a different tactic, which we’ll come to a little later in this narrative.

    Blackboard tried a similar trick of domination through acquisition, somewhat less successfully, in the web conference space by simultaneously buying Wimba and Elluminate, which were two of the largest education-specific web conferencing platforms at the time. If there hadn’t been an explosion of cheap and excellent generic web conferencing solutions soon afterward, it might have worked.

    Blackboard did not really consider itself a software development company during this period and was not afraid to say so explicitly to customers. I was told this by a Blackboard representative, and I know of one ePortfolio company that was told the same thing. They started up specifically because Blackboard’s response to them when they asked as university customers if Blackboard would an build ePortfolio was, “We don’t really develop software, but if you know of any good ePortfolio companies, we might consider acquiring one.”

    Blackboard did have an internal product development strategy of sorts, albeit an anemic one. Companies understand that it’s easier (and cheaper) to sell a second product to an existing customer than a first product to a new customer. So they often develop a portfolio of products and services to “cross-sell” to those existing clients. In and of itself, there’s absolutely nothing wrong with that. And like many companies, Blackboard had a formula for how many products they needed to cross-sell in order to hit their financial goals. Again, this is pretty standard stuff. The objectionable part was the way in which that formula drove the product road map.

    The quintessential example of this was Blackboard Community. Keep in mind that the LMS originated when universities started taking generic groupware (like Lotus Notes, for example) and adding education specific features like a grade book and a homework drop box. Blackboard’s idea was to strip those education-specific features back out of the product and license it separately to use for clubs, committees, and so on. I’m sure it wasn’t quite that simple from a development perspective, but it wasn’t very far off. Take the product you’ve already sold to the customer, strip out some features, integrate the stripped down version with the original version—badly—and sell it to the customer a second time.

    Blackboard also had epically bad customer service. Far worse than any of the LMS vendors today. To be clear, there were individuals at Blackboard who worked their butts off to serve their customers. There are always good people at sufficiently large companies. There were people in Blackboard—on their development teams, in customer service, and in other parts of the company—who tried desperately hard to serve their customers well. But the company’s processes were not optimized for customer service, and it did not invest in customer service. One can only conclude that customer service was not a priority of executive management, whatever the line employees may have felt about it.

    The patent suit

    As I mentioned earlier, Desire2Learn was becoming a thorn in Blackboard’s side. But Blackboard’s management team was developing a legal strategy that they thought would complement their acquisition strategy, especially in cases where pesky entrepreneurs would not sell. They started filing for patents. Now, software patents are an unfortunate reality in our world. I don’t like them, but since they exist, I understand why some companies feel the need to have them. That said, Blackboard’s intentions were neither for defensive purposes nor for demonstrating durable value to investors. They intended to assert their patents against other companies.

    In industries like pharmaceuticals or electronics, where innovation takes considerable investment up front but yields significant, long-term profits afterward, the economics can support patent assertion. There is enough money flowing in the system that there is at least a plausible argument that paying the inventor a licensing fee incentivizes investment in innovation. But education is not that sort of market, and the LMS product category in particular has thin margins. If new LMS vendors had to pay patent royalties, there likely wouldn’t have been new LMS vendors.

    Blackboard received a patent for LMS functionality, the precise definition of which I will get to momentarily. They immediately asserted that patent against Desire2Learn. They probably expected the company to fold and agree to either pay the royalty or sell. Companies usually don’t fight patents. If Desire2Learn had folded, that would have given Blackboard’s patent added legal weight. And Blackboard had other patents it had filed. There was every indication that they were attempting to create what is called a “patent thicket,” effectively making it impossible to bring a new product to market without running into one or another of their patents. If they had succeeded, they would have owned the LMS market forever.

    They would have killed the LMS market.

    And what was Blackboard’s first patent? What was their supposed innovation?

    A system where a user could log into one course as an instructor and another as a student.

    That’s it.

    Really.

    When I learned enough about how to read a patent to figure that out, I couldn’t believe it. And this is where Blackboard started fighting with me. But it was all non-denial denials. There is a moment in the legal process of a patent fight where the court determines the scope of the patent. Before that, legally speaking, the patent is undefined. So when Blackboard pushed back against my posts, all they were really saying was that the court hadn’t spoken yet.

    When the two companies faced each other in court and argued for their definition of the scope of the patent, what did Blackboard argue was the scope of their patent?

    A system where a user could log into one course as an instructor and another as a student.

    Blackboard didn’t like me writing stuff like that. They—where “they” means specific executives who I choose not to mention by name, rather than some hive mind of every human working at the company—did not like it when I called them out on it in advance. And they really did not like it when I pointed out afterward that they had been misleading at best in their previous statements about what they believed the scope of the patent to be.

    What concerned me was that their repeatedly calling attention to my writing by arguing with me in public was irrational. I was relatively unknown until they started responding to me. This kind of regular unforced error was out of character. It was telling me…something. What was it telling me? The most logical explanation was that I had gotten under their skin. I had cause to suspect that they were the kind of people who did not have a high tolerance for being challenged. That could be dangerous.

    As long as I was working at SUNY, I was protected. They may have been irrationally focused on me, but they weren’t stupid. They were not about to attack a university employee. However, once I became an Oracle employee, I was concerned that things would get ugly.

    I was right.

    What ugly looks like

    When I was offered the job at Oracle, I had a conversation with my prospective manager about the Blackboard situation. I told him that I thought the patent assertion was a threat to the health of the sector, that I did not intend to stop writing about it, and that it was possible that Blackboard would come after me once I was no longer working for a university. He replied that he respected my right to continue writing as long as I made clear on the blog that my opinions were my own—which I did, scrupulously—but that if the politics reached above a certain level in the organization, then his ability to protect me would have its limits. We agreed that it would be unfortunate if that were to happen, we each understood and respected the other’s position, and we agreed to give it a go. Nothing ventured and all that.

    It didn’t take long. I was at a Blackboard reception at EDUCAUSE when one of the executives approached me and started a conversation about my posts. “You know, I wouldn’t complain to Oracle about it. I would never do that. I respect your independence. But this isn’t good for the relationship between our two companies.”

    That’s a nice shiny new job you got there, kid. It would be shame if anything were to, you know. Happen to it.

    I kept writing.

    Not many months after that, the same executive, in the presence of my manager, sat down next to my colleague and started complaining to her about me. Repeatedly. Incessantly. To the point where my manager had to physically interpose himself between the executive and my colleague in order to protect her from what he perceived to be harassment. At which point, the executive started complaining to my manager about me.

    It had the opposite of the intended effect. My manager was very protective of his people.

    I kept writing.

    Not all of the writing was negative, by the way. For example, when Blackboard’s Chief Legal Counsel showed up at a Sakai conference to debate the Software Freedom Law Center’s Eben Moglen on the merits of the patent, I argued both that Blackboard’s representative had been unfairly treated and that it was important to continue to try to work with the company constructively on the larger patent problem if at all possible.

    Nevertheless, Blackboard continued what I can only describe as a widening and escalating campaign to convince my employer to either silence me or remove me. They were specifically told that I was unwelcome at Blackboard hosted events. The message was clear: Feldstein is harming Oracle’s relationship with Blackboard. And if that weren’t clear enough, I started being approached by random Oracle employees. The conversation would go like this:

    Do you know [Blackboard employee name redacted]?

    Yeah, I know him. Why?

    Well I don’t, but he just came up to me at BbWorld and started complaining to me about how you’re harming Oracle’s relationship with Blackboard.

    That same Blackboard employee accosted me at an IMS meeting, literally yelling at me, telling me that he had almost convinced his bosses to adopt the new version of the LIS standard we were developing—the one that was going to save universities time and money by getting rid of the need to manually monitor the integration between the registrar software and the LMS—but they killed it when they read my latest blog post.

    A Blackboard executive all but confirmed this in a later meeting. He looked me in the eye, with my manager present, and asked, “Why should we adopt Oracle’s standard?”

    “Oracle’s standard.”

    I kept writing.

    Next, the Blackboard executive decided to go up a few levels in the food chain. He told my manager’s manager’s manager that he was having Blackboard customers coming into his office in response to my blog posts and asking why Oracle hates Blackboard. This intervention too had the opposite of the intended effect. My manager’s manager’s manager did not believe for one second that people were confusing my personal blog posts with Oracle’s official position on Blackboard.

    After all of that, and some more that I’m not going to write about here, Blackboard lost the patent suit. They took a $3.3 million write-down for it. But that’s nothing compared to the actual loss, which the company is still paying today. If people are still using the sentence “X is the new Blackboard,” do you think there is any way that Blackboard itself is not still paying for the damage done by management that left the company seven years ago? Many people in this sector still hate that company with a fiery passion, and some of them don’t even know why anymore.

    Now, ask yourself this: Does what I just described bear any relation to the behavior of any company that you know of in ed tech today? Instructure? Blackboard? Anyone? I can think of a few that I would characterize as on the spectrum of bad actors. All of them are in immature product categories, where there is less transparency, more hype, and therefore more room for con artists. Jose Ferreira from Knewton was a bad actor in that he harmed our ability to have a productive discussion about the utility of adaptive learning or machine learning through his unsubstantiated hype (and the fundraising he did off it). But he didn’t do anything I’m aware of that rose to the level of anything like what I’ve described here. The robot tutor hype scam, and the new variation where vendors start claiming that all their competitors are robot tutor scam artists, are the main dangers at the moment. Anything AI-related still has some danger in it, as does the OPM space. But the bad actors I can think of are mostly little league compared to the Hall of Fame bad actors at old Blackboard.

    Instructure is the new Instructure

    Organizations change. Instructure changes. Blackboard changes. Your university changes. Your department changes. Change happens. Change is hard. Mistakes happen during the stress of transition. And what comes out the other side is not always predictable. But it often can be influenced.

    When I wrote my post in the wake of Instructurecon 2018, I knew that it might not make a ton of sense in the moment to either customers or employees of the company. So a lot of it was written in a way that would hopefully be memorable…I don’t know…maybe eleven months later, when the story had played out enough that we could have a real conversation about it.

    Here’s the important bit:

    Instructure’s unbelievably long age of innocence may finally be coming to an end. That doesn’t mean that it is going to fail or to become the next ed tech company that everybody hates. It does mean that it is beginning to go through some changes, that some of those changes will be awkward and hard, and that the company will eventually grow up to become somewhat different than it has been. Not necessarily better or worse. But necessarily different.

    So maybe you don’t like some of the things that they’ve been doing (or not doing) lately. Now what? You could try engaging with them. OK, maybe you tried that and didn’t get the results you wanted. Remember that extended metaphor about the awkward teenage years in my original post? I used to teach eighth graders, and I’ve raised kids of my own. One talk usually doesn’t do it during the challenging periods. Not because they don’t care about you, but because it’s just really hard being a teenager. You’re overloaded. Everything is changing at once, and you’re just trying to get through the day. If a teenager responds badly in the moment, it doesn’t mean that they’re a bad person, or even that they’re not listening. It usually means that they’re dealing with more than just you.

    A company isn’t a teenager; it’s a group of adults who you pay to do things for you. Nevertheless, it is also a group of humans who can experience change, individually and collectively, and who can have all the reactions that humans do to change and stress and all that stuff.

    These organizational transitions don’t finish up over night. Dan’s been CEO for less than a year now. Next month will be his first Instructurecon as CEO. He’s still in the steep part of his learning curve. Will he be a good CEO? I don’t know. I barely know the guy. You probably barely know the guy too. His employees are starting to get to know the guy by now. They’re figuring it out.

    Maybe you feel like you can’t engage with Instructure because other people in your university “own” that relationship, and you’re relatively powerless.

    Well, that’s a different sort of problem, isn’t it? I’ve written before about how bad LMS vendor behavior and bad LMS product development are actively driven by bad university LMS procurement processes. These internal conversations are hard ones to have, and sometimes the people who see the problems are not in a position to force the conversation. But ultimately, the vendors have to respond to whatever sorts of interactions the universities invite them to have (or don’t). It’s worth taking some time to understand why the vendors are thinking and acting the way they are so that you can find some productive ways into the conversation.

    And by the way, those vendors do read what you write. Heck, we live in an era where we pick the President of the United States on Twitter and Facebook. You think these companies don’t read your posts? They damned well do. They may be constrained in how they respond, but they do pay attention. How do you think I do what I do? I’m just a dude with a blog. How did I get myself into all the trouble you just read about? By being a dude with a blog. Turns out that using your voice can be a powerful thing, particularly if think carefully about who you want to hear you and how you want them to react. Yes, I do beat on vendors in public sometimes. But I always do it with a specific intention to make something happen. It may not be obvious in the moment, but it is always there. You can talk to these vendors and be heard, particularly if you have that intentionality and if they think that you are also listening.

    If you want your vendors to be better, it’s not that different from trying to get your kids to be better, or any humans with whom you want to have a genuine relationship to be better. That was really the point of my original blog post. Talk to them, listen to them, engage with them. It doesn’t mean you have to let them walk all over you, but it does mean you shouldn’t assume you understand what they’re thinking or that they are force of nature that cannot be influenced. If you’re reading e-Literate, then you’re probably an educator of some sort. Be an educator. Use that.

    Instructure is changing. I don’t know what they’re changing into yet. You don’t know either. I would bet money that Instructure doesn’t know yet. And this isn’t really just about Instructure. They are the case study of the moment. The point is, vendors make their money by responding to the conditions created by the university ecosystem. That’s you and your colleagues. If you want better vendors, then create the conditions under which they can succeed by behaving in the ways in which you would prefer them to behave. That’s hard work, and it may involve some family therapy inside your home institution. But the alternative is living in perpetual fear of clowns. And that, my friends, is no way to live.

  • The IMS at an Inflection Point

    The IMS at an Inflection Point

    A few weeks back, I had the pleasure of attending the IMS Learning Impact Leadership Institute (LILI). For those of you who aren’t familiar with it, IMS is the major learning application technical interoperability organization for higher education and K12 (and is making some forays into the corporate training and development world as well). They’re behind specifications like LIS, which lets your registrar software automagically populate your LMS course shell with students, and LTI, which lets you plug in many different learning applications. (I’ll have a lot more to say about LTI later in this post.)

    While you may not pay much attention to them if you aren’t a technical person, they have been and will continue to be vital to creating the kind of infrastructure necessary to support more and better teaching and learning affordances in our educational technology. As I’ll describe in this post, I think the nature of that role is likely to evolve somewhat as the interoperability needs of the sector are beginning to evolve.

    The IMS is very healthy

    I’m happy to report that the IMS appears to be thriving by any obvious measure. The conference was well attended. It attracted a remarkably diverse group of people for an event hosted by an organization that could easily be perceived as techie-only. Furthermore, the attendees seemed very engaged and the discussions were lively.

    On more objective measures, the organization’s annual report bears out this impression of strong engagement. They have strong international representation across a range of organization types.

    From the IMS Global 2018 Annual Report

    Whether your measure is membership, product certifications, or financial health, the IMS is setting records.

    From the IMS Global 2018 Annual Report

    This state of affairs is even more remarkable given that, 13 years ago, there was some question as to whether the IMS was financially sustainable.

    From the IMS Global 2018 Annual Report

    If you look carefully at this graph, you’ll see three distinct periods of improvement: 2005-2008, 2009-2013, and 2013-2018. Based on what I know about the state of the organization at the time, first period can most plausibly be attributed to immediate changes implemented by Rob Abel, who took over the reins of the organization in February of 2006 and likely saved it from extinction. Likewise, the magnitude of growth in the second period is consistent with that of a healthy membership organization that has been put back on track.

    But that third period is different. That’s not normal growth. That’s hockey stick growth.

    I am not a San Franciscan. By and large, I do not believe in heroic entrepreneur geniuses who change the world through sheer force of will. Whenever I see that kind of an upward trend, I look for a systemic change that enabled a leader or organization—through insight, luck, or both—to catch an updraft.

    There is no doubt in my mind that the IMS has capitalized on some major updrafts over the last decade. That is an observation, not a criticism. That said, the winds are changing, in part because the IMS has helped move the sector through an important period of evolution and is now helping to usher in the next one. That will raise some new challenges that the IMS is certainly healthy enough to take on but will likely require them to develop a few new tricks.

    The world of 2005

    In the first year of the chart above, when the IMS was in danger of dying, there was very little in the way ed tech to interoperate. There were LMSs and registrar systems (a.k.a. SISs). Those were the two main systems that had to talk to each other. And they did, after a fashion. There was an IMS standard at the time, but it wasn’t a very good one. The result was that, even with the standard, there was a person in each college or university IT department whose job it was to manage the integration process, keep it running, fix it when it broke, and so on. This was not an occasional tweak, but a continual effort that ran from the first day of class registration through the last day of add/drop. If you picture an old-timey railroad engineer shoveling coal into the engine to keep it running and checking the pressure gauge every ten minutes to make sure it didn’t blow up, you wouldn’t be too far off. As for reporting final grades from the LMS’s electronic grade book automatically to the SIS’s electronic final grade record, well, forget it.

    If you ignore some of the older content-oriented specifications, like QTI for test questions and Common Cartridge for importing static course content, then that was pretty much it in terms of application-to-application interoperability. Once you were inside the LMS, it was basically a bare-bones box with not much you could add. Today, the IMS lists 276 officially certified products that one can plug into any LMS (or other LTI-compliant consumer), from Academic ASAP to Xinics Commons. I am certain that is a substantial undercount of the number of LTI-compatible applications, since not all compatible product makers get officially certified. In 2005, there were zero, because LTI didn’t exist. There were LMS-specific extensions. Blackboard, for example, had Building Blocks. But with a few exceptions, most weren’t very elaborate or interesting.

    My personal experience at the time was working at SUNY Systems Administration and running a search committee for an LMS that could be centrally hosted—preferably on a single instance—and potentially support all 64 campuses. For those who aren’t familiar with it, SUNY is a highly diverse system, with everything from rural (and urban) community colleges to R1s to everything in between, with some specialty schools thrown into the mix like the Fashion Institute of Technology, a medical school or two, an ophthalmology school, and so on. Both the pedagogical needs and the on-campus support capabilities across the system were (and presumably still are) incredibly diverse. There simply was not any existing LMS at the time, with or without proprietary extensions, that could meet such a diverse set of needs across the system. We saw no signs that this state of affairs was changing at pace that was visible to the naked eye, and relatively few signs that it was even widely recognized as a problem.

    To be honest, I came to the realization of the need fairly slowly myself, one conversation at a time. A couple of art history professors dragged me excitedly to Columbia University to see an open source image annotation tool, only to be disappointed when they discovered that the tool was developed to teach clinical histology, which uses image annotation to teach in an entirely different way than is typically employed in art history classes. An astronomy professor at a community college on the far tip of Long Island, where there was relatively little light pollution, wanted to give every astronomy student in SUNY remote access to his telescope if only we could figure out how to get it to talk to the LMS. Anyone who has either taught a been an instructional designer for a few wildly different subjects has a leg up on this insight (and I had done both), but even so, there are levels of understanding. The art history/histology thing definitely took me by surprise.

    A colleague and I, in an effort to raise awareness about the problem, wrote an article about the need for “tinkerable” learning environments in eLearn Magazine. But there were very few models at the time, even in the consumer world. The first iPhone wasn’t released until 2007. The first practically usable iPhone wasn’t released until 2008. (And we now know that even Steve Jobs was secretly skeptical that apps on a phone were a good idea.) It is a sign of just how impoverished our world of examples was in January of 2006 that the best we could think of to show what a world of learning apps could be like was Google Maps:

    There are several different ways that software can be designed for extensibility. One of the most common is for developers to provide a set of application programming interfaces, or APIs, which other developers can use to hook into their own software. For example, Blackboard provides a set of APIs for building extensions that they call “Building Blocks.” The company lists about 70 such blocks that have been developed for Blackboard 6 over the several years that the product version has been in existence. That sounds like a lot, doesn’t it? On the other hand, in the first five months after Google made the APIs available for Google Maps, at least ten times that many extensions have been created for the new tool. Google doesn’t formally track the number of extensions that people create using their APIs, but Mike Pegg, author of the Google Maps Mania weblog, estimates that 800-900 English-language extensions, or “mash-ups,” with a “usable, polished Google Maps implementation” have been developed during that time—with a growth rate continuing at about 1,000 new applications being developed every six months. According to Pegg, “There are about five sites out there that facilitate users to create a map by taking out an account. These sites include wayfaring.comcommunitywalk.commapbuilder.net—each of these sites probably has hundreds of maps for which just one key has been registered at Google.” (Google requires people who are extending their application to register for free software “keys.” Perhaps for this reason, Chris DiBona, Google’s own Open Source Program Manager, has heard estimates that are much higher. “I’ve seen speculation that there are hundreds or thousands,” says DiBona, noting that estimates can vary widely depending on how you count.

    Nevertheless, even the most conservative estimate of Google Maps mash-ups is higher than the total number of extensions that exist for any mainstream LMS by an order of magnitude.

    There seemed little hope for this kind of growth any time in the foreseeable future. By early 2007, having failed to convince SUNY to use its institutional weight to push interoperability forward, I had a new job working at Oracle and was representing them on a specification development committee at the IMS. It was hard, which I didn’t mind, but it was also depressing. There was little incentive for the small number of LMS and SIS vendors who dominated specification development at that time to do anything ambitious. To the contrary, the market was so anemic that the dominant vendors had every reason to maintain their dominance by resisting interoperability. Every step forward represented an internal battle within those companies between the obvious benefit of a competitive moat and the less obvious enlightened self-interest of doing something good for customers. This is simply not the kind of environment in which interoperability standards grow and thrive.

    And yet, despite the fact that it certainly didn’t feel like it, change was in the air.

    Glaciers are slow, but they reshape the planet

    For starters, there was the LMS, which was both a change agent in of itself and an indicator of deeper changes in the institutions that were adopting them. EDUCAUSE data shows that the US LMS market became saturated some time roughly around 2003. At that time, Blackboard and WebCT had the major leads as #1 and #2, respectively. The dynamic for the next 10 years was a seesaw, with new competitors rising and Blackboard buying and killing them off as fast as it could. Take a look at the period between 2003 and 2013 in Phil’s squid graph: ((By the way, if you haven’t subscribed to Phil’s new blog yet, then you really, really should. Like, right now. I’ll wait.))

    It was absolutely vicious.

    None of this would materially affect the standards making process inside the IMS until, first, Blackboard’s practice of continually buying up market share eventually failed (thus allowing an actual market with actual market pressures to form) and, second, until the management team that came up with this decidedly anti-competitive strategy…er…chose to spend more time with their respective families. (I’ll have more to say about Heckle and Jeckle and their lasting impact on market perceptions in a future post.)

    But the important dynamic during this period is that customers kept trying to leave Blackboard (even if they found themselves being reacquired shortly thereafter) and other companies kept trying to provide better alternatives. So even though we didn’t have a functioning, competitive market that could incentivize interoperability, and even though it certainly didn’t feel like we had one, some of the preconditions for one were being established.

    Meanwhile online education growth was being driven by no fewer than three different vectors. First, for-profit providers were hitting their stride. By 2005, the University of Phoenix alone was at over 400,000 enrollments. Second, public access-oriented institutions, many of which had been seeded a decade earlier with grants from the Sloane Foundation, were starting to show impressive growth as well. A couple were getting particular attention. UMUC, for example, may not have had over 400,000 online enrollments in 2005, but they had well over 40,000, which is enough to get the attention of anyone in charge of an access-oriented public university’s budget. More quietly, many smaller schools were having online success that were proportional to their sizes and missions. For example, when I arrived at SUNY in 2005, they had a handful of community colleges that had self-sustaining online degree programs that supported both the missions and the budget of the campuses. Many more were offering individual courses and partial degrees in order to increase access for students. (Most of New York is rural, after all.)

    The third driver of online education, which is more tightly intertwined with the first two than most people realize, is that Online Program Management companies (OPMs) were taking off. The early pioneers, like Deltak (now Wiley Education Services), Embanet, Compass Education (now both subsumed into Pearson), and Orbis (recently acquired by Grand Canyon University) had proved out the model. The second wave was coming. Academic Partnerships and 2Tor (now 2U) were both founded in 2008. Altius Education came in 2009. In 2010, Learning House (now also owned by Wiley) was founded.

    Counting online enrollments is a notoriously slippery business, but this chart from the Babson survey is highly suggestive and accurate enough for our purpose:

    If you’re a campus leader and thirty percent of your students are taking at least one online class, that becomes hard for you to ignore. Uptime becomes far more important. Quality of user experience becomes far more important. Educational affordances become far more important. Obviously, thirty percent is an average, and one that is highly unevenly distributed across segments. But it’s significant enough to be market-changing.

    And the market did change. In a number of ways, the biggest one being that it became an actual, functioning market (or at least as close to one as we’ve gotten in this space).

    When glaciers recede

    Let’s revisit that second growth period in the IMS graph—2008 to 2013—and talk about what was happening in the world during that period. For starters, online continued its rocket ride. The for-profits peaked in 2010 at roughly 2 million enrollments (before beginning their spectacular downward spiral shortly thereafter). Not-for-profits (and odd mostly-not hybrids) ramped up the competition. ASU launched its first online 4-year degree in 2006. SNHU started a new online unit in 2009. WGU expanded into Indiana in 2010, which was the same year that Embanet merged with Compass Knowledge and was promptly bought by Pearson. (Wiley acquired Deltak two years later.)

    Once again, the more online students you have, the less you are able to tolerate downtime, a poor user interface that drives down productivity, or generic course shells that make it hard to teach students what they need to learn in the ways in which they need to learn. Instructure was founded in 2008. They emphasized a few distinctions from their competitors out of the gate. The first was their native multitentant cloud architecture. Reduced downtime? Check. The second was a strong emphasis on usability. The big feature that they touted which was their early runaway hit was Speed Grader. Increased productivity? Check.

    Instructure had found their updraft to give them their hockey stick growth.

    But they also emphasized that they were going to be a learning platform. They weren’t going to build out every tool imaginable. Instead, they were going build a platform and encourage others to build the specialized the tools that teachers and students need. And they would aggressively encourage the development and usage of standards to do so. On the one hand, this fit from a cultural perspective. Instructure was more like a Silicon Valley company than its competitors, and platforms were hot in the Valley. On the other hand, it was still a little weird for the education space. There still weren’t good interoperability standards for what they wanted to do. There still hadn’t been an explosion of good learning tools. This is one of those situations where it’s hard to tell how much of their success was prescience and how much of it was luck that higher ed caught up with their cultural inclination at that exact moment.

    Co-evolution

    The very same year that Brian Whitmer and Devlin Daley founded Instructure, Chuck Severence and Mark Alier were mentoring Jordi Piguillem on a Google Summer of Code project that would become the initial implementation of LTI. In 2010, the same year that Instructure scored its first major win with the Utah Education Network, IMS Global released the final specification for LTI v1.0. All this time that the market had felt like it had been standing still, it had actually been iterating. We just hadn’t been experiencing the benefits of it. Chuck, who had been thinking about interoperability in part through his work on Sakai, had been tinkering. Students like Brian and Devlin, who had been frustrated with their LMS, had been tinkering. The IMS, which actually had a precursor specification before LTI, had been tinkering. While conditions hadn’t become visible on the surface of the glacier, way down, a mile below, the topology of the land was changing.

    Meanwhile in Arizona, in 2009, the very first ASU+GSV summit was held. I admit that I have had writer’s block regarding this particular conference the last few years. It has gotten so big that it’s hard to know how to think about it, much less how to sum it up. In 2009, it was an idea. What if a university and a company that facilitates start-ups (in multiple ways) got together to encourage ed tech companies to work more effectively with universities? That’s my retrospective interpretation of the original vision. I wasn’t at many of those early conferences and I certainly wasn’t an insider. It was hard for me, with my particular background, to know what to make of it then and even harder now.

    But something clicked for me this year when it turned out that IMS LILI was held at the same hotel that the ASU+GSV summit had been at a couple of months earlier. How does the IMS get to 523 product certifications and $8 million in the bank? A lot of things have to go right for that to happen, but for starters, there have to be 523 products to certify and lots of companies that can afford to pay certification fees. That economy simply did not exist in 2008. Without it, there would be no updraft to ride and consequently no hockey stick growth. ASU+GSV’s phenomenal growth, and the ecosystem that it enabled, was another major factor influenced what I saw at IMS LILI this month.

    There is a lot of chicken-and-egg here. LTI made a lot of this possible, and the success LTI (and IMS Global) have experienced would not have been possible without a lot of this. The harder you stare at the picture, the more complicated it looks. This is what “systems thinking” is all about. There isn’t a linear cause-and-effect story. There are multiple interacting feedback loops. It’s a complex adaptive system, which means that it doesn’t respond in linear or predictable ways.

    Update: I got a note from Rob Abel noting that a lot of the growth in the last leg came from an explosion of participation in the K12 space. That’s good color and consistent with what I’ve seen in my last couple of LILI conference visits. It’s also consistent with the rest of this analysis. K12 benefitted from all of the dynamics above—the maturation of the LMS market, the dynamics in higher education online that pushed toward SaaS and usability, the massive influx of venture funding, and so on. All of those developments, plus the work inside IMS, made the K12 growth possible, while the dynamics inside K12 added another feedback loop to this complex adaptive system.

    But respond it finally did. We have some semblance of a functioning market, and with its rise, blockers preventing the formation of a vibrant interoperability standards ecosystem of the type we have today have largely fallen. Now we have to address the blockers of the formation of the vibrant interoperability ecosystem that we will need tomorrow. Because it will be qualitatively different. Tomorrow’s blockers are not market formation problems but rather collaboration methodology problems. They are about creating meaningful learning learning analytics, which will require solving some wicked problems that can only be tackled through close and well structured interdisciplinary work. That most definitely includes the standards design process itself.

    After the glacier comes the flood

    What I saw at the IMS LILI this year was, I think, a milestone. The end of an era. Market pressures now favor interoperability. The same companies that were the most resistant to developing and implementing useful interoperability standards in 2007 are among the most aggressive champions of interoperability today. This is not to say that foundational interoperability work is “over.” Far from it. Rather, the conditions finally exist where it can move forward as it should, still hard but relatively unimpeded by the distortions of a dysfunctional market.

    That said, the nature and challenges of interoperability our sector will be facing in the next decade are fundamentally different from the ones that we faced in the last one. Up until now, we have primarily been concerned with synchronizing administration-related bits across applications. Which people are in this class? Are they students or instructors? What grades did they get on which assignments? And how much does each assignment count toward the final course grade? These challenges are hard in all the ways that are familiar to anyone who works on any sort of generic data interoperability questions.

    But the next decade is is going to be about data interoperability as it pertains to insight. Data scientists think this is still familiar territory and are excited because it keeps them at the frontier of their own profession. But this will not be generic data science, for several reasons. (I will tell you right now that some of them disagree with me on this. Vehemently.) First, even in the most richly instrumented fully online environments that we have today, they are highly data impoverished relative to what we need to make good inferences about teaching and learning. For heaven’s sake, Amazon still recommends things that I have already bought. If I just bought a toaster oven last month, then how likely is it that I want to buy another one now? And I buy everything on Amazon. If they don’t know enough to make good buying recommendations on consumer products, then there’s no way that our learning environments are going to have enough data to make judgements that are orders of magnitude more sophisticated.

    Well then, some answer, we’ll just collect more data! More more more! We’ll collect everything! If we collect every bit of data, then we can answer any question. (That is a pretty close paraphrase of what one of the IMS presenters said in one of the handful of learning analytics talks I went to.)

    No. You won’t collect “everything”—even if we ignore the obvious, glaring ethical questions—because you don’t know what “everything” is. Computer folks, having finally freed themselves from the shackles of SQL queries and data marts, are understandably excited to apply that newfound freedom to the important problem space of learning. But it is not a good fit, because we don’t have a good understanding of the basic cognitive processes involved in learning. As I wrote about (at length) in a previous post, we have to employ multiple cutting-edge machine learning techniques just to get glimpses of learning processes even when we are directly monitoring students’ brain activity because these are extraordinarily complex processes with multiple hidden variables. Trying to tease out learning processes inside a student’s head based on learning analytics from running machine learning algorithms on LMS data is a little like trying to monitor the digestive processes of a flatworm on the bottom of the Marianas Trench based on studying the wave patterns on the surface of the ocean. There are too many invisible mediating layers to just run a random forest algorithm on your data lake—it all sounds very organic, doesn’t it?—and pop out new insights about how students learn.

    That doesn’t mean we should just throw up our hands, by any means. To the contrary, IMS Global has some extraordinarily good tools close at hand for tackling this problem. But it does mean that they are going to have to take some of the stakeholder engagement strategies they’ve been working at diligently to the next level, to the point where the standards-making process itself may evolve over time.

    Theory-driven interoperability

    There is an excellent data and processing resource that the learning analytics folks have yet to think deeply about how to leverage, as far as I can tell from the conference. The computational power is impressive (and impressively parallel). It is the collective intelligence of educators and learning scientists. Because there are too many confounds to making useful direct inferences from the data, educational inferencing needs to be theory-driven. You need to start with at least some idea of what might be going on inside the learner’s head. One that can be either supported or disproven based on evidence. And you need to know what that evidence might look like. If you can spell all that out, then you can start doing interesting things with learning analytics, including machine learning. There is room for learning science, data science, and on-the-ground teaching expertise at the table. In fact, you need all those kinds of expertise. But the folks with those respective kinds of know-how need to be able to talk to each other and work together in the right ways, which is really hard.

    The IMS has an outstanding foundation for this sort of work, because their Caliper specification turns out to provide the basis for a perfectly lovely lingua franca. To begin with, its fundamental structure is triples, which is the same basic idea as the original concept behind the semantic web. If you’re not a computer person and this is starting to make your eye’s glaze over, don’t worry, because this is plain English. Three-word sentences, in fact. Noun, verb, direct object. Student takes test. Question assesses learning objective. Student highlights sentence. Sentence discusses Impressionism.

    IMS Caliper expresses learning analytics in statements that can easily be translated into three-word plain-English sentences. These sentences can be strung together into coherent paragraphs. Notice, for example, how the last two example sentences are related. Three-word sentences in this format can be chained together to form longer thoughts. New thoughts. With this one, very simple grammatical structure, we have a language that is generative in the linguistic sense. As long as you have words to put into these grammatical placeholders, you can string thoughts together. Or “chain inferences,” to sling the lingo. And it turns out, unsurprisingly, that Caliper has a mechanism for defining these words in ways that both humans and machines can understand them.

    That has to be the bridge. Humans have to understand the utterances well enough to be able express their theories on the front end and understand whatever the machine is telling them it may have learned on the back end. Machines have to understand them specifically enough to be able to parse the sentences in their own, literal, machine-y way. Theoretically, Caliper could be an ideal language to enable educators and computer scientists to discuss theories about how to better support students as well as how to test those theories together.

    The challenge is that the IMS community, at least based on what I saw in the sessions I attended, is not using the specification as an interdisciplinary communication tool in this way yet. What I saw happening instead was a lot of very earnest data scientists pumping as much Caliper data as the can into their data lakes. They come to the conference, give a talk and, to their credit, shrug their shoulders and admit that they really don’t know what to do with those data yet. But then they go home and build bigger pipes, because that’s their job. That’s what they do.

    It’s not their fault. I’ve been friends with some of these folks for a very long time indeed. There are good people here. But if you work in the IT department, and you’re not a learning scientist or a classroom educator, and the faculty are somewhere between dismissive and disdainful of the idea of talking to you about working together to improve teaching and learning, then what can you do? You do what you know how to do and hope that things will change for the better over time.

    It’s not the IMS’s fault either. The conference I attended was called the IMS Learning Impact Leadership Institute. That’s not a new name. Caliper has board that helps guide its direction. That board includes educators who are the kind of advocates that I would like to see on such a body. They are productive irritants in the best possible way. But that’s not enough anymore. This is just a really hard problem. It’s the challenge of the next decade. To meet it, we need to do more than just make sure the right people are in the room together. We need to develop new ways of working together. New roles, methodologies, ways of talking with each other, and ways of seeing the world.

    I’m going to preview a bit of a post that I have in my queue for…I’m not sure when, but some time soon…by mentioning “learning engineering.” This term has gotten a lot of buzz lately, along with some criticism. I’ll be writing up my own take on it, but for now I’ll say that one reason I think the term is gaining some currency is that it represents a set of skills for being a mediator in the kind of collaboration that I’m describing here.

    As it turns out, it was coined by Nobel prize-winning polymath and Carnegie Mellon luminary Herb Simon, after whom Carnegie Mellon University’s Simon Initiative was named. And, as it also turns out, the Simon Initiative hosted this year’s EEP summit and made some news in the process by contributing $100 million worth of open source software that they use in their research and pratice of…wait for it…learning engineering.

    Here’s a slide that they used in their talk explaining what the heck learning engineering is and what they are doing when they are doing it:

    Copyright Carnegie Mellon University, CC-BY

    (By the way, the videos of all talks from the summit will be posted online, as promised. Please be patient a little longer.)

    This post has already run long, so rather than unpacking the slide, I’ll leave you with a question or two. Think about this graphic as representing a data-informed continuous improvement methodology involving multiple people with multiple types of expertise. What would that methodology need to look like? Who would have to be at the table, what kinds of conversations would they have to have, and how would they have to work together?

    I’m not suggesting that “learning engineering” is a magical conjuring phrase. But I am suggesting that we need new approaches, new competencies, and likely a new role or two if we are going to get to the next updraft.

  • Instructure: Plans to expand beyond Canvas LMS into machine learning and AI

    Instructure: Plans to expand beyond Canvas LMS into machine learning and AI

    It’s common knowledge that Instructure has shifted its focus to place more emphasis on its growth in corporate learning markets than in the educational markets that have fueled the company growth to date. We covered the initial news about their introduction of the corporate learning LMS, Bridge, four years ago.

    While Instructure has excelled on maintaining product focus and simplicity of user experience, this move outside of education raises the question about whether they can maintain company focus. The corporate market is very different than the education market – different product needs, fragmented vendor market, different buying patterns. Many companies have tried to cross over between education and corporate learning, but most have failed. Blackboard, D2L and Moodle have made a footprint in the corporate space using one product for both markets. Instructure’s approach is different.

    As noted, the other Big Four LMS vendors are also targeting corporate learning (or professional ed, or workplace, pick your name). D2L and Blackboard are using the same platforms in both markets (Brightspace for D2L, Learn and Open LMS for Blackboard), while Moodle released Workplace, a set of plugins on top of core Moodle. Instructure, however, has different products for educational and corporate markets.

    That is old news. What is more interesting is to understand Instructure’s emerging strategy given the new executive team. Thanks to the nature of Instructure being a publicly-traded company, we are getting more insight that should set expectations for educational customers. As CEO Dan Goldsmith said during an investor conference a week ago:

    We really changed the company, as I came in nine months ago and then took over as CEO January 1st of this year. We’re initiating the second chapter in the journey of Instructure.

    I should first note that the audience for these calls is the investment community, so naturally Instructure executives focused more on financial performance and projections that they would in academic meetings. But there is a lot to learn here.

    In some ways, the changes to operations of Instructure are welcome and are already helping them manage corporate finances. In other ways, however, that second chapter reads a lot like Blackboard. Moving beyond the LMS, willing to bet on corporate acquisition, expecting big focus on data and analytics, and continuing challenges in completing products.

    Operational Improvements

    One of the ongoing criticisms of Instructure, particularly by their competitors, is that they continue to lose money and are buying growth. While these observations are accurate, as long as Instructure keeps growing, they have never been at risk of running out of money or having their losses significantly impact their operations. Under the new leadership, Instructure has been much more aggressive in managing expenses, with a big milestone described on the conference call by CFO Steve Kaminsky [emphasis added].

    Turning to the expense side. With our focus on operational excellence during the second half of 2018, we’ve changed the mindset of our leadership team and the entire organization about how we approach the business and fund investment. We focused on disciplined investments for balancing profitable growth has been put in place and is reflected in the outlook we provided today. On the cash side, we have a strong cash position to support our important strategic objectives for both Canvas and Bridge. And looking forward to 2019, we anticipate being approximately free cash flow neutral for the full year.

    Beyond simple finances, we have seen some operational changes for international operations as well. The global regions (EMEA, Latin America, APAC) all have more autonomy now, including control over country-specific marketing and product management. The non-US operations have moved beyond being regional sales and support offices into more aggressive engines of growth. In Europe and other regions, the management team has more autonomy is deciding which countries are worth investment for expanding markets, and when. From the Feb 25th investor presentation:

    The Instructure Story

    With the improving operations, Instructure has reduced their operating losses from 57% of revenue to 10% of revenue in the past three years.

    Investor conference slide

    Moving Beyond the LMS

    On the same day as Instructure’s earnings call and release of FY2018 financial results, the company announced the acquisition of Portfolium for $43 million, a small startup focusing on “ePortfolio network, student-centered assessment, job matching capabilities, and academic and co-curricular pathways”. We interviewed Instructure staff the same day as the earnings call and noted a different message. In our initial call, the Portfolium acquisition was positioned primarily as a way to improve how Instructure can handle structured assessments in the education market – think CBE, mastery learning, with ePortfolios not as the goal but as the necessary infrastructure. During the earnings call, however, the positioning was more about bridging educational and corporate markets and expanding total addressable market (TAM).

    Today, we’ve taken a great stride towards enabling that transition with our expected acquisition of Portfolium, a successful long time Canvas partner. Portfolium vision is to help each person realize their full potential by connecting learning with opportunity, through e-portfolios, program and course level assessments, career pathways and by matching students to job opportunities. Portfolium will join Instructure with a wealth of shared customers, such as Virginia Tech, Santa Clara University and Swinburne University in Australia. This acquisition is a great match in vision and culture and represents our first major step into the Student Success market. And while Portfolium’s current offerings provide an excellent solution, more importantly, they establish the first Bridge between academia and the corporate world that aligns precisely with Instructure’s vision.

    Instructure now views itself as a company with a suite of products, and they are much more open to using corporate M&A to build this portfolio.

    Emphasis on Data & Analytics

    The second initiative announced on the earnings call was DIG, a strategic move with data and analytics.

    I am also pleased to share with you an early insight into our second growth initiative focused on analytics, data science and artificial intelligence. The code name for this initiative is DIG. And this technology platform combined with the most comprehensive SaaS database on the educational experience uniquely positions us to deliver meaningful value to our customers. And from a growth perspective, DIG has the potential to double our TAM in education.

    Instructure started ramping up their data and analytics efforts (again) about a year ago, although the focus was described at the time as being about internal analytics – that is, making Canvas a better and more valuable LMS product. From what I have heard the product validation for DIG are consistent with this message – dashboards, surfacing useful data within a workflow, etc. But that was not how DIG is being sold during the conference call [emphasis added].

    We’ve been working on the scaffolding for [DIG] for well over a year now. I mentioned in our remarks that we already have product validation towards out there in the market. We have instructors and students consuming output from some of the initial experiments with DIG. And we anticipate later this year obviously to make more announcements around specific products and offerings and how we bring them into the market. DIG ultimately is a platform first and foremost based upon machine learning and artificial intelligence. I believe that any multi tenant SaaS company born in the cloud has the opportunity once they hit a certain market share. And in fact, it may even be incumbent upon those organizations to partner with the industry and evolve that industry with new insights and predictive modeling using AI and ML. That’s what DIG is at its heart.

    This is brand new behavior for Instructure as a company. Previously the company was reticent to talk much about non-released products, but now they are talking not just about a new initiative, they are touting buzzwordy machine learning and artificial intelligence and predictive modeling well before any of those capabilities exist or are in customer hands. Goldsmith further clarified the DIG plans during the investor conference discussion [starting at 9:00, emphasis added].

    We already have analytical capabilities in our Canvas platform. I want to be really clear and delineate the difference between an analytics and reporting capability, and a machine learning and AI platform. [snip]

    We have the most comprehensive database on the educational experience in the globe. So given that information that we have, no one else has those data assets at their fingertips to be able to develop those algorithms and predictive models.

    Goldsmith then described an example of predicting a student’s expected performance in a class and how that prediction reliability goes up over time. Then we get the vision.

    What’s even more interesting and compelling is that we can take that information, correlate it across all sorts of universities, curricula, etc, and we can start making recommendations and suggestions to the student or instructor in how they can be more successful. Watch this video, read this passage, do problems 17-34 in this textbook, spend an extra two hours on this or that. When we drive student success, we impact things like retention, we impact the productivity of the teachers, and it’s a huge opportunity. That’s just one small example.

    Our DIG initiative, it is first and foremost a platform for ML and AI, and we will deliver and monetize it by offering different functional domains of predictive algorithms and insights. Maybe things like student success, retention, coaching and advising, career pathing, as well as a number of the other metrics that will help improve the value of an institution or connectivity across institutions. [snip]

    We’ve gone through enough cycles thus far to have demonstrable results around improving outcomes with students and improving student success. [snip] I hope to have something at least in beta by the end of this year.

    Wow. Robot tutor in the sky – meet the new kid on the block.

    The most generous interpretation I have is that they are being sloppy in their terminology and casually throwing out machine learning and AI to eager investors, while the reality could be more mundane but useful sharing of useful data to help instructors or administrators.

    If I had to guess, however, I would suggest that Instructure has its sights set on additional corporate acquisitions over the next year or two to try and back up these expectations. I hope they realize they are not the first company to believe that AI on top of their best-in-world data will deliver success for all.

    The message is also clear that Portfolium and DIG are intended to increase TAM. This means separate product categories with separate pricing in addition to Canvas. Either that or offering Canvas at different pricing levels to include add-on product bundles.

    Challenges in Completing Products

    We noted the modernization efforts behind Quizzes.Next, the next generation quizzing and test engine for Canvas, as well as the big schedule miss. In short, Quizzes.Next was announced at InstructureCon 2016 as being available within a few months. 12 months later at InstructureCon 2017 it entered limited beta, and at InstructureCon 2018 it entered general availability. But the story is not over. Quizzes.Next is still not at feature parity with the original quiz engine, as noted by Indiana University.

    Instructure has released a new quizzing tool for Canvas called Quizzes.Next. Quizzes.Next offers several new features and question types, but is missing many features from the current Quizzes tool on which many instructors depend. Both tools will continue to be available until Quizzes.Next has achieved feature parity with Canvas Quizzes. The original Canvas Quizzes tool will eventually be retired, but Instructure has not yet announced the timeline.

    If you read the Canvas Community page comparing features, it is clear that feature parity is not imminent. The transparency is impressive, however, and from what we are hearing customers are still giving Instructure some leeway because of trust. But Quizzes.Next and its delivery is a continuing problem, not least of which is the reduction in R&D spending growth for Canvas, described by CFO Steve Kaminsky on the call.

    Regarding the R&D investment, we don’t really break that out. But what we can tell you qualitatively is while we are doing some incremental investments on the Canvas side and DIG is a good example of that, the lion share of the growth in R&D is going into Bridge.

    What to Expect

    Instructure is at a crossroads. While they continue to grow, especially in education markets, and while they report improving financial performance, Instructure is entering uncharted territory (for them) in this second chapter. It is remarkable that they have not lost a major educational LMS customer in the 8+ years since Canvas was first selected by the Utah Education Network, but there are some warning signs that should not be ignored and some risky expectations being set.