With reporting contributions from Jeanette Wiseman and O’Neal Spicer
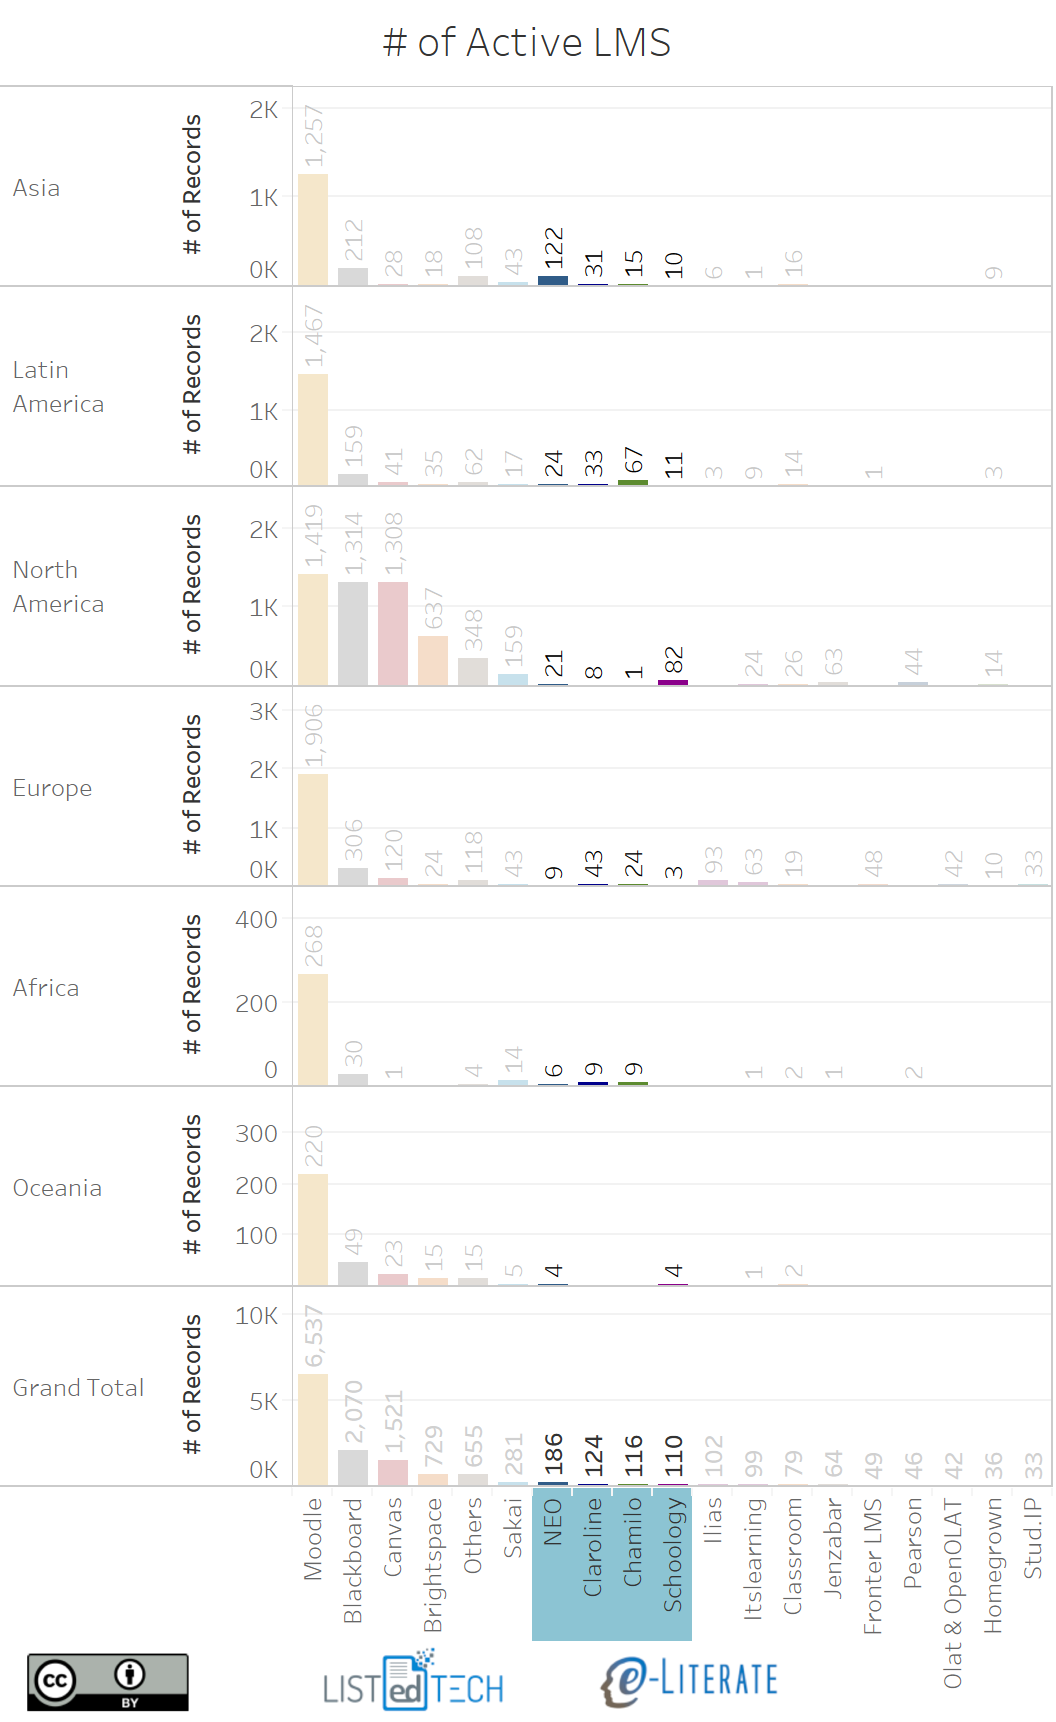
We have described how the global LMS market is converging in the sense that the Big Four – Moodle, Blackboard, Instructure, and D2L – end up being the primary competitors in more and more global regions, often with similar dynamics. We have also described Sakai and its decline in some detail. But what about the next level down? Let’s consider four LMS solutions that are still quite active but with fewer institutional users than Sakai – Schoology (whom we have described before), NEO, Claroline, and Chamilo. ((Disclosure: Blackboard, Instructure, D2L, and Schoology are subscribers to our LMS Market Analysis service. Blackboard, Instructure, D2L, and Pearson are sponsoring participants in our Empirical Educator Project.)) The following graphic shows both primary and secondary system usage in higher education in six different global regions, and all four systems have more than 100 active implementations.
Schoology NEXT
The Schoology NEXT conference occurred at the same time as BbWorld this year. This is a mostly K-12 conference – as that is the primary market for Schoology – with a different attendance demographic than most LMS conferences with the majority of the attendees being actual classroom teachers or instructional designers, not the typical administrators or IT staff that you see at the other user conferences. This audience is more focused on the use of technology to enhance teaching and learning in their classrooms, to assist with assessment, or to fill a requirement of use of technology for professional development. The break-out sessions reflected this academic focus.
The only new features or development that were discussed at any length during the keynote presentations involved the vague promise of “Personalized Learning” support. There was little information about what new features would look like, what they would encompass, or if they would entail additional charges like Schoology’s assessment platform. In an interview with CEO Jeremy Friedman and the new President Justin Serrano, they said that the vagueness is by design. The company is still working through their users’ needs and will be completing development on those features once that assessment was complete.
When discussing if the company saw Google Classroom’s continued growth in the K-12 market as a threat, Friedman said it is the opposite. They see that in K-12 space Google Classroom fills a need for a classroom, a school or a district that are dipping their toes in the LMS space, and once the school starts actively using the technology they quickly outgrow it. In these cases, Schoology sees Google Classroom as seeding the market for them, and they actively target those Google Classroom schools. In most cases, if responding to an RFP, it will be Canvas they will be up against. Rarely do they see Blackboard or even Moodle in these situations. They feel like, and this was reiterated by their users, that one of the most significant benefits that Schoology users see in the platform is their ease of use. The interface is reminiscent of Facebook; it is familiar to the teachers they quickly can navigate and load announcements and content to their site with very little training or IT support. It may not carry with it the bells and whistles of a Blackboard Learn or even Canvas by Instructure, but for what these K-12 teachers need, it fits the bill. For now.
Regarding targeting customers in higher education, the company stayed the course from January 2017 in which they will continue to support their higher education customers and will take easy sales opportunities, but are not planning to aggressively pursue that market. While this strategy only lightly targets higher education, Schoology has over 100 clients at universities and colleges worldwide – mostly small private schools, and often as secondary systems – using their platform. Customers using as a primary system include Wheaton College and Saint Vincent College in the US and the Universidad Metropolitana de Monterrey in Latin America. Schoology is also used as a secondary system at schools including UC San Diego.
NEO, Claroline, and Chamilo
The other three systems – NEO, Claroline, and Chamilo – are important in the global market, even if most academic buyers (in the US, at least) likely have not heard of them. All have more than 100 higher education implementations worldwide.
NEO is the academic LMS from Cypher Learning: Based on our conversations at the K-12 focused ISTE conference this summer, Cypher Learning has 60 employees and claims 2 million customers worldwide (combining NEO with the Indie and Matrix LMS for corporate markets). In higher ed, their largest implementation is with STI College in the Philippines with a systemwide deal that gives them 77 campus adoptions. The system has been designed native to the cloud and boasts a fairly intuitive user interface that addresses competency-based education and mastery learning.
Claroline Connect is an Open Source project run out of France: This system – which has the greatest adoption in Europe, Latin America, and Asia – is a second-generation open source project. In the early 2000s, the University of Lyon and the Université catholique de Louvain created two open source LMSs, and subsequently Claroline Connect combined these projects into the current system based on more modern technology. Get your French ready, or use captions.
Chamilo is an Open Source project run out of Spain: This system, used most often in Latin America and Europe, also has origins in the predecessors to Claroline, forking into the Dokeos project and then forking again to Chamilo in 2010. The system is supported by official supporting vendors in the following countries: Belgium, Spain, Italy and Germany. The Belgian company also has offices in Peru. Again, get your French ready.
While we have only described this second tier of global LMS providers in broad strokes, we hope this post gives a richer view of the broader LMS market and available systems.
I’ve written about how Instructure has, by our count, tied and (very) slightly surpassed Blackboard in US market share. Blackboard didn’t love that story. You know who else didn’t love it?
Instructure.
Up until now, Instructure has gotten enormous mileage out of playing the role of the scrappy underdog. Here’s co-founder Brian Whitmer reflecting on the company’s cultural roots in response to our reporting:
We showed up on the edtech scene in 2008, and people were more than happy to not just give us the time of day, but to unload their frustrations with Blackboard — and ideas for new hotness they were afraid they’d never see. Blackboard was really stinking it up from what we could tell. We crashed their user’s conference in Vegas after a few years and told everybody we were the anti-Blackboard. We didn’t need a better value prop than that. Just “not Blackboard” and a bunch of t-shirts was enough to get people excited.
At InstructureCarn 2018, current employees also admitted that the company preferred the role of the insurgent and that being perceived as the market leader is a fraught position for them.
Both because of that change and because they are now a publicly traded company, Instructure is in the process of becoming…something else. We’re not sure what it is yet, exactly, although there are some signs of what may be to come. Whatever it is, it will have to be more of an adult company. Instructure can’t get away with crashing the other guy’s party and passing out snarky T-shirts anymore. It has to grow up.
Along the way, there will be embarrassing and unsightly blemishes. There will be social awkwardness. There will be break-ups and friends lost. InstructureCarn 2018 marked the company’s transition into full adolescence. Officially, Instructure is 10 years old. But functionally…well…welcome to 8th grade. Good luck in junior high, kid.
Who are you and what have you done with my CEO?
The first sign of…the changes…came early in the conference. Instructure CEO Josh Coates is known for giving odd, almost stream-of-consciousness keynotes that appear to have little direct connection to the company and yet somehow, almost inexplicably, charm the audience while arriving at an unexpected and heartwarming ending.
Not this time.
In an awkward attempt at self-deprecating humor, Josh managed to insult adjunct faculty. He also made comments that irritated disability advocates and fans of the humanities in the audience. While none of these gaffes felt egregious to me, they were far enough off-target that you have to wonder whether they would have slipped through the filter had Coates had the benefit of review from now-departed executives who helped prepare for so many previous InstructureCons. At the same time, the audience reaction was more strongly negative than I’ve seen from an Instructure crowd before—to anything, really, including idiosyncratic and announcement-free CEO keynotes that would have set off riots at other LMS conferences. When you are a teenager (or market leader), your friends become less forgiving.
But hey, maybe all will be forgotten once Josh brings out the special guest. Who will it be this year? They Might Be Giants? Jewel? Nope. This year it was…drum roll please…
New Instructure President Dan Goldsmith!
What’s going on here? The most obvious explanation is that Josh, like much of the rest of the executive management team that took Instructure public, is likely getting ready to move on. Goldsmith is being groomed/auditioned as a successor, and part of that means preparing customers for this change.
It’s delicate. Nobody at Instructure said this is what’s happening, but they weren’t exactly hiding it either. Our analyst interview with the executive team seemed like part Coates coaching Goldsmith on how to handle us given our quirky role in the industry and part Goldsmith demonstrating that he has done his homework and understands the company.
For whatever it’s worth, our first impression of Dan is positive. He does do his homework, he did show an understanding and appreciation for the importance of the corporate culture, and he generally comes across as a nice, bright, adult human. ((You should know that my initial positive impressions of EdTech executives do not correlate well with future performance. Phil tells me I have too much faith in humanity.))
But his résumé portends other changes that might come with growing pains.
Get a job, kid
Instructure’s detractors are fond of reminding us that the company is not profitable. The company does indeed face some specific financial pressures now that it is publicly traded, although boiling it down to profitability is a bit of an oversimplification. Under certain conditions, investors will happily tolerate unprofitability in their investments for long periods of time. Amazon is the canonical example of this. The two things investors want to see from Instructure are (1) growth, and (2) indications on the balance sheet that the company is unprofitable only to the degree that it is choosing to invest in that growth (rather than because it simply can’t be profitable).
Instructure has three major options for growth, none of which will be easy:
Selling new products to existing customers: Both Blackboard and D2L have portfolios of products that they can sell to their existing customer base. (They can also sell these products to schools that don’t use their LMSs, but it’s often easier and cheaper to sell a second product to an existing customer than a first one to a new customer.) Blackboard has a particularly mature set of cross-selling products, including established ones like Collaborate and the new smash hit they have in the Ally content accessibility support system. D2L’s cross-selling success has been a little more uneven, but they do have a reasonably broad portfolio and appear to be doing particularly well at selling services. Instructure is well behind its competitors in this regard. The company backed off plans to sell an analytics data service in 2015 after customers pushed back on having to pay for it. While their Arc lecture capture product and their newer, K12-focused Gauge assessment management system seem to be well received by customers, they have not been runaway commercial successes. Instructure may turn out to have a bit of a sleeper hit on their hands with Practice, a clever video product they recently acquired and have been mostly promoting in the corporate market so far. But at the moment, these are all small ball compared to the kind of growth that their investors expect.
Growing internationally: All the major LMS vendors are looking abroad to new markets. Much of the world is running self-hosted Moodle. As distance learning grows in popularity in a given country, the LMS becomes more mission-critical. Students and faculty become more demanding about issues like downtime and usability and universities become more willing to spend money on their LMS. Given the potential size of the international market, this isn’t necessarily a zero-sum game for the LMS vendors—including Moodle support vendors. There is room for everyone to grow their respective businesses. Theoretically. In practice, there is no such thing as an “international” market. There are many national markets. Each one is different, each requires investment in product feature development, sales, and marketing, and each is growing at a different rate. International growth is hard, expensive, and often slower than casual observers might imagine.
Growing into the corporate market: With Bridge, Instructure has entered the corporate LMS market, which is substantially different from the educational LMS market in quite a few ways. The required functionality is different, the sales process is different, and the market is much more crowded and fragmented. Of the three opportunities for growth, this is the one that has the most potential to distract the company from its current core customer base. It is also the one that Wall Street seems most obsessed with.
I’ve written recently about the pressure that Blackboard is under due to its private equity (PE) ownership and the heavy debt burden they placed the company under. It’s important to understand the differences in the pressures on a PE-owned company like Blackboard versus a publicly traded one like Instructure. It’s a little bit like the difference between waterboarding and Chinese water torture. ((Also known as Spanish water torture, depending on your cultural frame of reference.)) In the big picture, Blackboard has a more mature product portfolio and—as far as we know based on limited public information—likely has better business fundamentals than their LMS market share trend line would indicate. But the combination of having a heavy debt burden and PE owners who typically want to be corporate “house flippers” makes the company vulnerable to sudden drastic measures imposed on them by outside forces. In contrast, there are few, if any, individual shareholders that can force Instructure to make drastic short-term moves. A single sudden stock price drop like the one that happened last week won’t force the company to make dramatic changes either. But the drip, drip, drip of investor pressure over time can eventually force a company to change course if that pressure isn’t actively managed.
Enter Dan Goldsmith.
I’d like to speak to your father, please
Here is how Goldsmith is described in the press release announcing his new position at Instructure:
With more than 20 years of experience in software and services, Goldsmith’s career is marked by directing high-performing global teams and achieving outstanding penetration and growth in challenging markets. Goldsmith spent the last eight years as a senior executive at Veeva Systems, a cloud-based software company, where he started and ran Veeva’s international business, led the company’s strategy in new markets and products, and most recently was responsible for Veeva’s global engagement and growth in strategic accounts.
“It is an exciting time for Instructure. We are well positioned for success as we focus on the continued growth of Canvas, expansion of Bridge, and international execution,” said Josh Coates, CEO of Instructure. “Dan’s energy, creativity and proven track record in driving go-to-market strategies and rapidly scaling businesses make him a tremendous addition to Instructure at the perfect time to lead us through our next phase of growth.”
Goldsmith was one of the first 50 employees at Veeva. He helped lead the company through a successful IPO and a growth path to a $10 billion market cap. Prior to Veeva, he worked in various executive positions at top companies, including Accenture, PwC and IBM. During his years in management consulting, Goldsmith led initiatives in global markets and developed new offerings. Goldsmith will have an immediate impact on Instructure’s strategy. His initial focus will be on market growth, with the sales leaders reporting directly to him.
Here’s a guy who has international business development experience, knows how to sell to the corporate market, has built out product portfolios, and would likely be perceived as a familiar, comforting presence by Wall Street analysts.
Friends, meet Instructure’s CEO-in-waiting:
Instructure President Dan Goldsmith
Assuming the trial period goes well, I think it likely that he will be promoted to the top job within 9 months. The reason I pick this time frame is anything too close to InstructureCon 2019 poses the danger of being a distraction during the most important event of the year for the company.
Goldsmith was working very hard in both formal and informal settings throughout this year’s conference to demonstrate that he understands, values, and intends to protect the company culture. If he’s going to be the dad, he wants to be the cool dad.
Nevertheless, even if he proves himself to be the coolest dad around, there will be changes, likely including the format and feel of the company’s unique and iconic annual conference.
Do you live in a barn?
Phil and I have bothwritten about how company culture has been one of Instructure’s most underestimated competitive weapons and how InstructureCon is the embodiment of that culture to the customers. It’s one of those things that you can’t fully understand if you haven’t experienced it. There’s nothing else quite like it in EdTech.
That is going to change. How much remains to be seen.
We saw some signs this year that Instructure has dialed back on the spending. It was still a spectacle and a unique cultural event. It was just a less expensive one. Carnival rides cost less than pop star appearances. The stage sets—yes, InstructureCon has stage sets, complete with props—were good, but didn’t rise to the Disney Imagineer-level quality of the past. Up to a point, that change is good. As an insurgent, Instructure’s extravagant spending on the conference seemed to successfully communicate the message of “people over profits” to the customers. But as the company is increasingly perceived as the market leader, educators will start looking around and asking themselves, “How much of this money could have gone toward lowering the cost for students or making the product better?”
At the same time, it will be a delicate transition. InstructureCon 2019 will be moved to Long Beach, which isn’t a bad thing in and of itself. Keystone is hard to get to, hard to navigate, and probably too small for the current size of the conference. But InstructureCon 2019 will be held at the Long Beach Convention Center.
InstructureCon has never been held at a convention center.
The company is going to have to pull off the transition to a more conventional (and cost-effective) venue without losing the gravity-defying magic of the ultimate unconference atmosphere they have managed to conjure consistently, year after year. And they may only get one shot at this. If customers walk away from InstructureCon 2019 feeling like they just attended any old LMS conference, that could have an outsized impact on their holistic perception of Instructure. That, in turn, may lead them to be less forgiving of mistakes.
Speaking of which…
Did you do your homework?
After announcing two years ago that they would be responding to customer concerns about the limitations of the quizzes and tests functionality in Canvas, Instructure finally delivered “Quizzes.Next,” their major rearchitecture of the quizzing functionality as a set of stand-alone micro services. The truth is that all of the major LMS providers have struggled at different times as the nature of the engineering challenges in LMS development evolve. D2L arguably hit the wall first a number of years ago, when they designed an innovative retention early warning system that was hampered by the core platform’s inability at the time to provide timely and reliable data streams. Blackboard is getting hammered now for their slow progress on Ultra and early mishaps with the SaaS transition (although, in fairness, they are taking on a real beast of a transition on multiple fronts and probably deserve more credit than they get on the technical front). For Instructure, Quizzes.Next turned out to be the publicly embarrassing stumble. ((Maybe I’m taking this adolescence analogy too seriously; I’m starting to have gym class floor hockey flashbacks.))
Decomposing the LMS into micro services is a seriously difficult challenge to think through and get right, both technically and functionally. It’s also critical if you want to be perceived as not just an LMS but a modern, flexible learning platform (or NGDLE, or LMOS, or whatever), which Instructure, D2L, and Blackboard all aspire to be. While it’s possible that Quizzes.Next was under-resourced, we tend to believe the company’s explanation that they just underestimated the complexity of the challenge.
But this won’t be the last such challenge. Between micro services and data analytics, today’s LMS engineering challenges are substantially different and harder than building a grade book that sucks less (which, by the way, is very hard in its own way). Meanwhile, Blackboard and D2L have both raised their game from user experience and architectural perspectives. If Instructure both loses its reputation as the LMS company that’s truly different and makes a couple of more stumbles like Quizzes.Next, the winds that are currently at its back could turn surprisingly quickly.
It’s all part of growing up, dear
Instructure’s unbelievably long age of innocence may finally be coming to an end. That doesn’t mean that it is going to fail or to become the next EdTech company that everybody hates. It does mean that it is beginning to go through some changes, that some of those changes will be awkward and hard, and that the company will eventually grow up to become somewhat different than it has been. Not necessarily better or worse. But necessarily different.
When we were at BbWorld the week before last, Blackboard’s executive management pushed back vehemently on our analysis of how their high levels of debt could impact their business decisions. We heard their strong disagreement expressed in our very first meeting of the conference from Chief Learning and Innovation Officer Phill Miller and in our very last meeting from CEO Bill Ballhaus.
We stand by our analysis. In fact, Blackboard’s pushback had the opposite of its intended effect. We left BbWorld more convinced that we are right rather than less.
But in fairness, there is an empirical fact of the matter here, and we do not yet have conclusive public evidence that the company’s high levels of debt will, in fact, affect their business strategy. So here’s what we’re going to do:
I will summarize their position as objectively as I can.
I will explain why we don’t find their position persuasive.
I will lay out the signs that concrete evidence we will be looking for going forward that will either support or undermine our thesis.
Phil and I will publish updates as we monitor these signs and, if there is no additional public evidence of our thesis by BbWorld 2019 (or strong evidence emerges that we are wrong before then), then we will publish a mea culpa post.
Blackboard’s position
The public kerfuffle of the last couple of weeks has been over our reporting that Canvas has (barely) surpassed Blackboard in US market share. But the focus of the company’s pushback at BbWorld was on the financial claims. The heart of the argument we heard was essentially the same as the one articulated by Blackboard to the Washington Business Journal:
A company spokesperson said in a statement that Blackboard was a “healthy business with a proven and sustainable business model” with strong financial backing from its private equity investors, who have placed hundreds of millions of dollars more over the last two years.
“We have made a strategic decision to focus on the future instead of just quarterly results or debt ratings. Thus, we’ve chosen to focus investments on long-term, market-driving opportunities that meet the evolving needs of our clients, including but well beyond the learning management system (LMS),” the spokesperson said in an email.
We’re not aware of public information about the “hundreds of millions of dollars more” that Blackboard claims their owner, Providence Equity, have placed in the company over the last two years, but Providence’s willingness to continue pouring money into Blackboard going forward is really the key question. Ballhaus argued to us that the amount of debt that Blackboard is carrying is a strategic choice that he and the private equity investors—he used the pronoun “we”—make together. In particular, he argued, “we” could choose at any time to invest more money in the company, paying down debt in exchange for equity. Further, he argued, it’s logical to assume that Providence would do so if needed because “they only make their money if we improve.”
Why it’s not credible
Paying down debt in exchange for equity, called “recapitalization,” is a strong vote of confidence by a private equity (PE) owner. First, since debt holders get paid before equity holders in the event of bankruptcy, it increases risk for the PE firm. Second, it would mean a substantial investment of cash, which is partly what PE firms typically try to minimize by requiring the companies that they own to take on substantial debt in the first place. When PE-owned companies find that they are in danger of being unable to make their debt payments—which both Moody’s and S&P Global Ratings have said is currently the case with Blackboard—the PE owners can and do employ a number of different strategies that are financially less risky to them in order to address the problem, either instead of or in addition to recapitalizing.
For example, when Cengage Learning found itself with unmanageable debt levels after its acquisition by private equity, they filed for bankruptcy:
“The decisive actions we are taking today will reduce our debt and improve our capital structure to support our long-term business strategy of transitioning from traditional print models to digital educational and research materials,” Michael Hansen, Cengage Learning’s chief executive, said in a statement.
To be crystal clear, I am not suggesting that Blackboard is likely to file for bankruptcy. Providence Equity has other options at its disposal, some of which I will write about in the next section.
Rather, the point is that Ballhaus’ claim that we should just assume Providence will see it as being in their interest to recapitalize Blackboard is not credible on its face to anybody with even passing knowledge of how private equity companies work. For example, the tone of the Washington Business Journal article I referenced above, which (obviously) was written by a business reporter, suggests significant skepticism that Providence will not let the company’s debt challenges impact their business decisions. The industry experts we typically consult with when writing financial or business stories like this one were even harsher in their evaluations of Blackboard’s position. Two literally laughed out loud at it.
Further evidence we will be looking for
All that said, there’s a lot we still don’t know. Because Blackboard isn’t publicly traded, we don’t have very good access to their financial information (though Moody’s and S&P do). And we certainly are not privy to the conversations that Ballhaus has with the company’s board of directors. It’s worth noting here that, in addition to being CEO, Providence chose to make him Chairman of the Board. So we will still label our analysis here as a (confident) hypothesis, subject to revision based on further empirical evidence.
Here are a few actions Blackboard could take in the future that would indicate Providence Equity has chosen to push Blackboard to solve its own debt problem rather than making it go away with more of Providence’s money:
Sell off one or more parts of the business: A Bloomberg piece written by journalists from their distressed debt desk reports, “With some of Blackboard’s bonds selling at deeply distressed levels, Ballhaus is crafting a comeback, and possible options include the sale of its payment processing division, said the people, who asked not to be identified because the discussions are private.” Said payment processing division, Blackboard Transact, is a cash cow for the company. If Blackboard sells off one of its more profitable business units at a time when the company is having trouble making debt payments, that would indicate a choice by Providence Equity to find a way to reduce debt pressure that is less risky for them in terms of cash investment but more risky for Blackboard in terms of long-term health. Particularly since Providence already tried to sell Blackboard once and has now owned the company for well past the normal sell-by date that PE companies like to follow, the sale of Transact might suggest further moves to follow.
Unload expenses (like office space): The Washington Business Journal article notes, “Blackboard is also interested in unloading its 70,000 square feet of office space at 1111 19th street, with 12,000 square feet already sublet, according to an April post on Tech Office Spaces. It’s unclear where Blackboard will go if it succeeds in leasing out its entire footprint. Blackboard stood to benefit from a tax rebate program for companies that agree to sign 50,000 square feet for at least a dozen years, valued at half the company’s tenant improvement costs, or a maximum of $5 million over five years.” Of course, companies take cost-cutting measures all the time, regardless of their financial health. The business reporter’s phrasing suggests that he may be detecting a whiff of desperation in the specifics of this transaction. Since that’s his expertise more than ours, we’ll be looking for additional confirmation of our thesis, such as if Blackboard were to…
Significantly restructure with major layoffs: If Blackboard were to move to a smaller office while also laying off employees—beyond those that might leave in a sale of a business division or the slow leak of headcount that the company has been having for a while now—that would certainly be an indicator that Providence is not ready to just give Blackboard the money the company needs to complete a turn-around and is instead pushing them to solve their own financial problems.
Given the sourcing of the first two potential indicators, we will not be surprised if at least those two come to pass by the end of 2018. Time will tell.
What evidence would suggest that our analysis is mistaken? The strongest would be if Providence recapitalizes Blackboard. Even that would not be black and white; for example, Cengage’s owners recapitalized the company along side of having them declare bankruptcy. The details will matter. But a significant recapitalization—where “significant” is defined by the markets and the financial experts—certainly would indicate that Mr. Ballhaus’ characterization of Providence’s willingness to invest further in Blackboard’s success is more accurate than current evidence suggests.
The other thing that could happen is nothing. If a year passes and Blackboard manages to weather the debt pressure without having to make any major moves, then it will only be fair to expect e-Literate to publicly revisit our analysis.
And of course, we are still listening to any arguments that Blackboard executives are willing to make. While they haven’t persuaded us thus far, we have accepted their invitation to keep the dialog going, and we remain open to more persuasive arguments. We will hold ourselves accountable, just as we will hold Blackboard accountable.
But honestly, I don’t think we will need to wait a year for public evidence that Providence is not going to wave its magic wand. I predict we will be writing a follow-up story within six months.
Sometimes breaking news overturns your blogging schedule. We have had e-Literate staff at four LMS conferences in the past few weeks and have a raft of news and analysis to publish. However, there’s some big news today out of Moodle that needs at least a timely mention while we write our other posts and chase down the details for more analysis of this event.
Moodle just announced that Blackboard “will transition out of Moodle’s Certified Moodle Partner program in the coming months.”
This is consequential for both Moodle and Blackboard. On the Moodle side, we have writtenabout Moodle’s financial dependence on Blackboard as a partner and how that creates some risk for the community. Since those posts, Moodle has received $6 million in outside investment. According to Moodle Pty’s press release, that investment, combined with a decline in Blackboard’s financial contributions to Moodle made it feasible for Moodle to break off from the partnership.
Note that all the information we have right now is Moodle’s press release; we will circle back to this story once we’ve had a chance to talk to folks from both Moodle and Blackboard and have caught up enough on our blogging schedule that we can give this story the attention that it deserves.
But here’s my snap reaction: For Moodle, there is good news and risk. The good news is that it clears up the uncertainty that we have been reporting on. Moodle will now have a chance to demonstrate that they can be sustainable without depending on Blackboard. The risk, of course, is that they will now have to demonstrate that they can be sustainable without depending on Blackboard. We’ll try to get some more color on this from Martin Dougiamas.
On the Blackboard side, it’s bad news in the short term, but the impact is hard to quantify. Because of the open source license under which Moodle is released, Blackboard can continue to use the code in their Moodlerooms business. However, Moodle Pty. owns the Moodle trademark. So unless Blackboard negotiated something with them, they will have to change the name of their product and division. In the medium term, there are open questions about their ability/willingness to continue contributing code to mainline Moodle, customer reactions to the split and, on the potential upside, Blackboard’s ability to make development decisions independently of Moodle Pty. There is some potential upside for them in that last piece, as well as not having to pay the partnership fee to Moodle. We will be reaching out to Blackboard (if they don’t reach out to us first) to hear more from them about how they see the future of their Moodlerooms business.
So there’s still a lot here that we don’t understand yet. But this is significant news in the LMS world.
There are three observations from Blackboard’s users conference that we feel are important to share before we pull together our thoughts for more comprehensive posts, and all three issues build off of Blackboard’s strong focus at the conference on Learn Ultra as the future of their LMS product line.
Learn Ultra “In Production” or “Using Ultra”
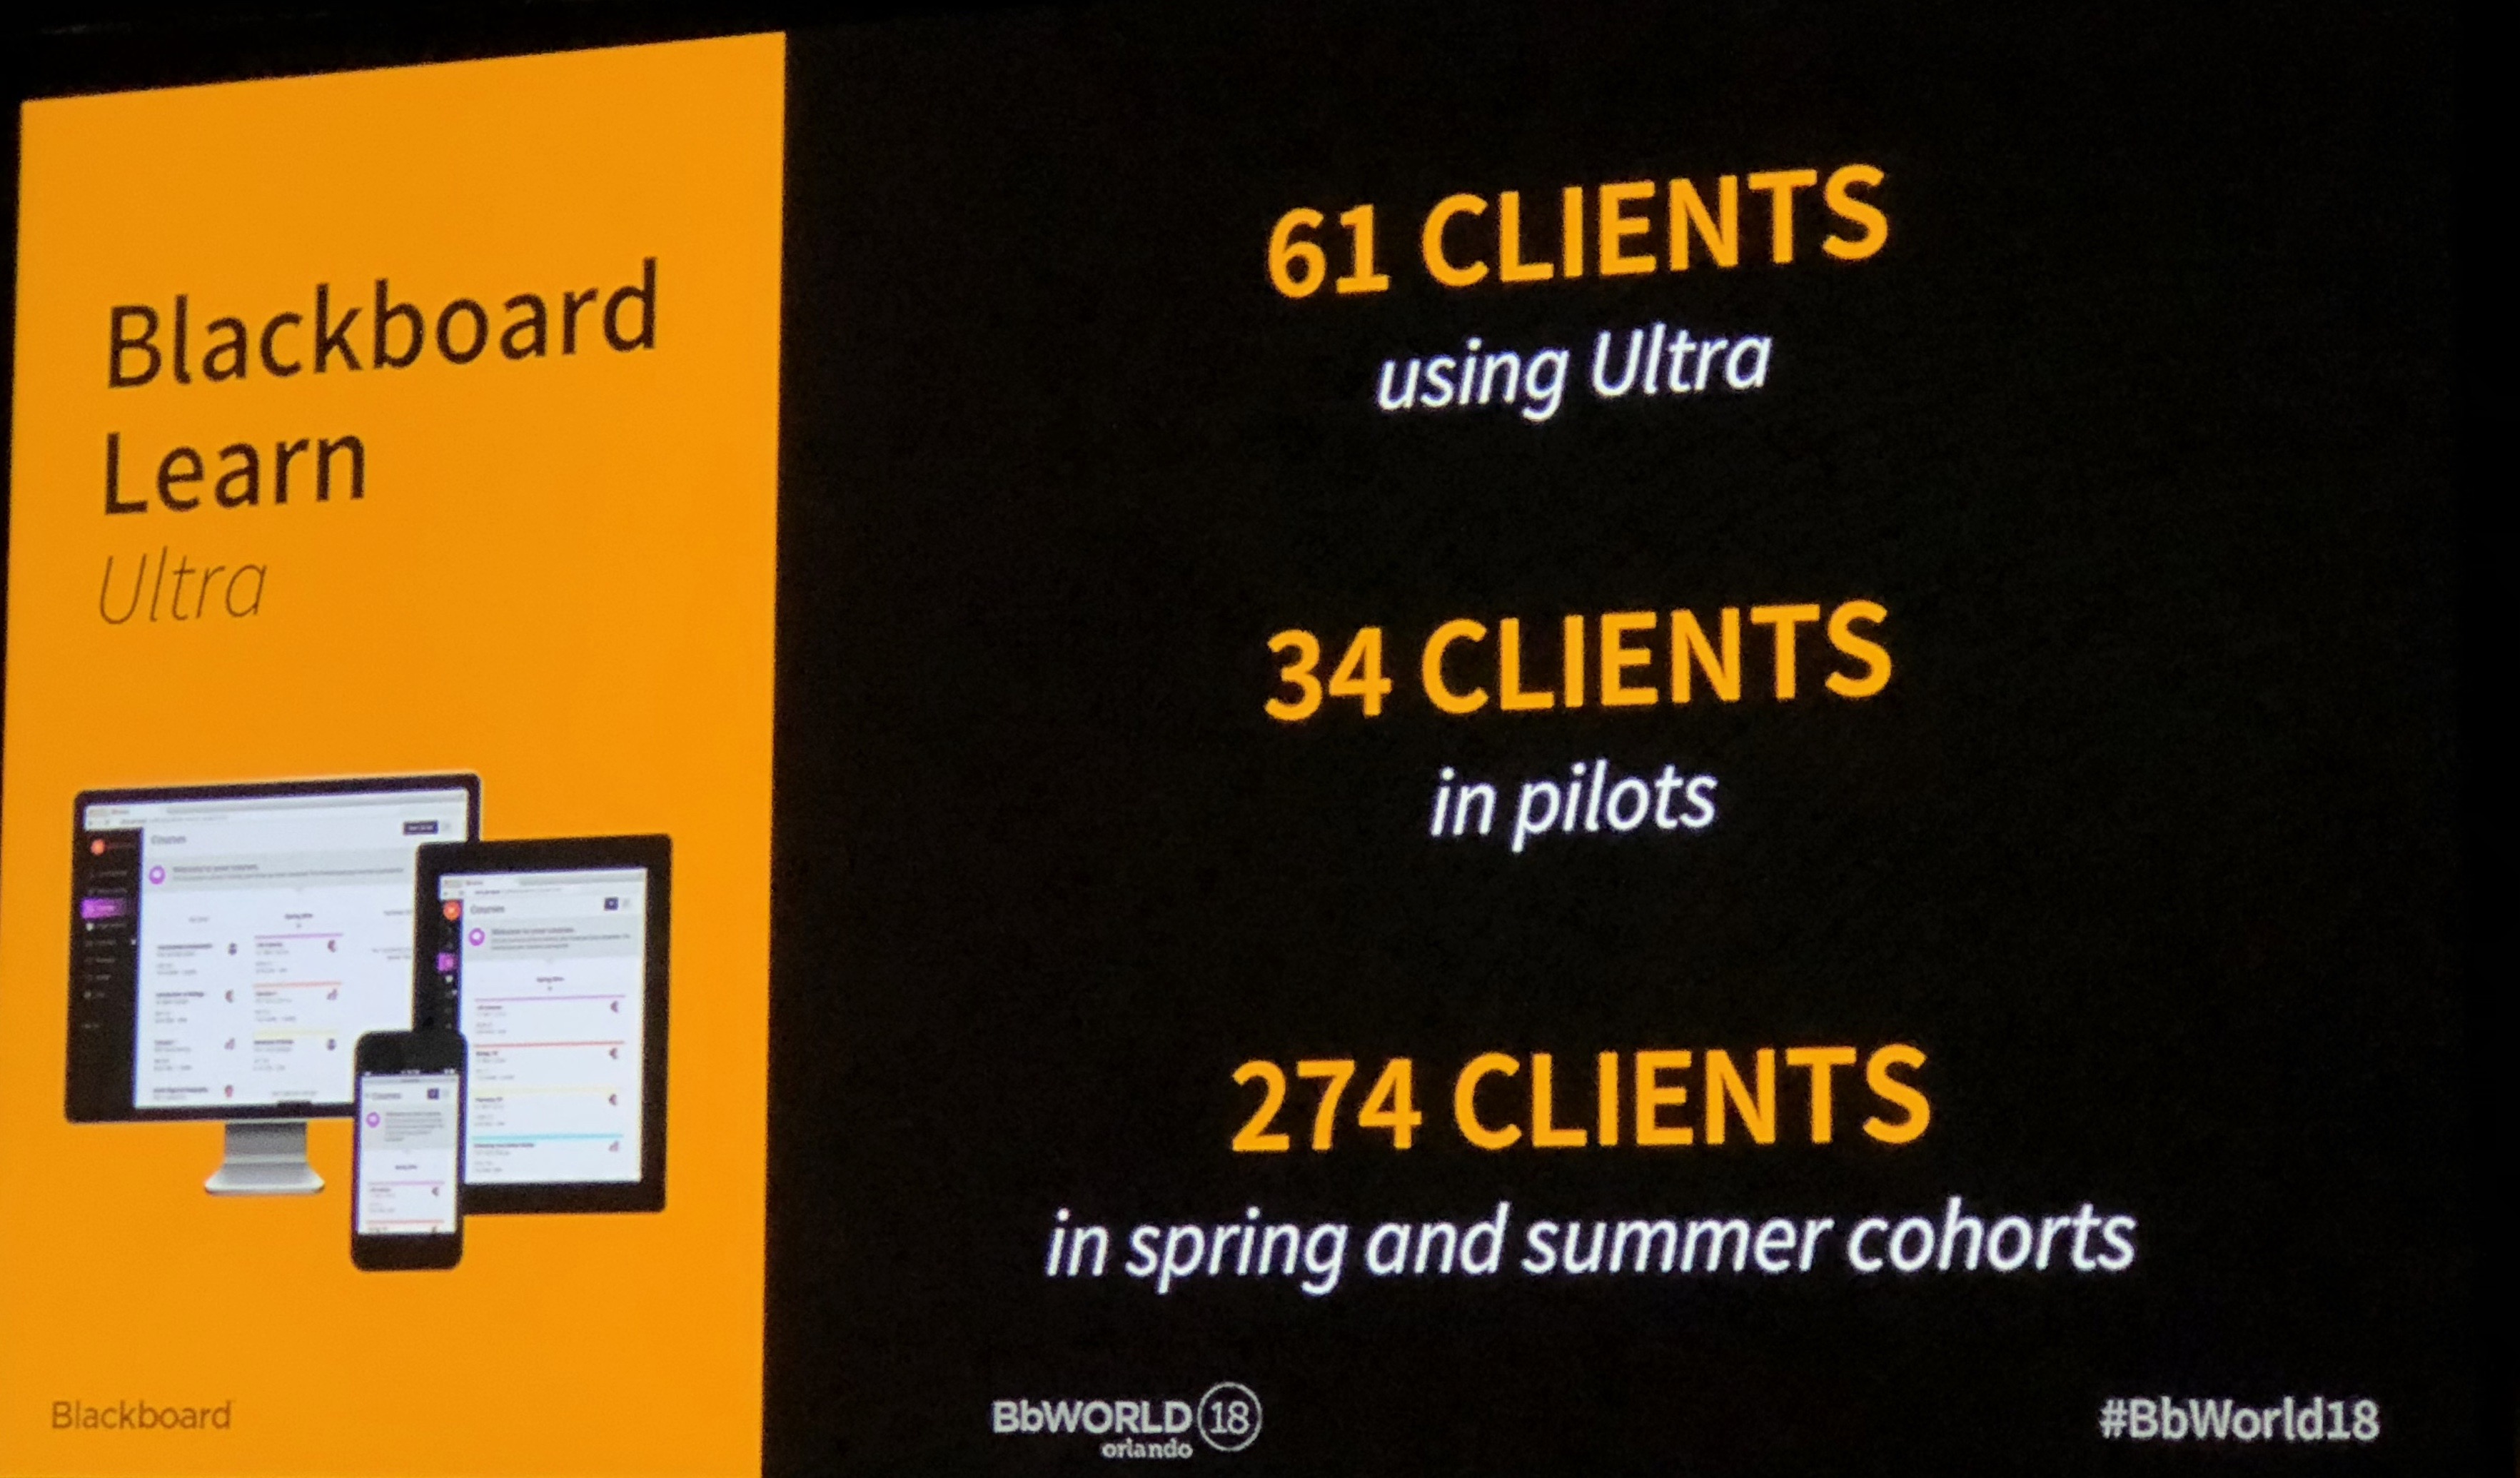
The first issue is terminology around Learn Ultra. Blackboard ((Disclosure: Blackboard is a client of the e-Literate LMS Market Analysis service and a participating sponsor in our Empirical Educator Project.)) is pushing the metric that there are 61 or 62 Learn Ultra customers “in production” or “using Ultra”, yet we have found very few that use, or even plan to use, Learn Ultra as their primary, institution-wide LMS. What gives? What became quite clear at the conference is that when Blackboard says in production, what they mean is that the LMS administrator has enabled the Ultra global navigation, which uses the new Ultra user experience framework as the landing page / dashboard with activity feed that users see before entering a specific course. The company calls this Base Navigation, but at this point every course can be configured to be in the Original Experience or the Ultra Experience. Thus, enabling the possibility of running a course in Ultra counts as in production.
Once a school has enabled Learn Ultra Base Navigation, they could choose to move exclusively to Ultra (e.g. the University of Phoenix, Northwest Florida State College, and a few others), or they could choose to keep all courses in Original (e.g. Northeastern State University), or they could choose to have some courses in Ultra and some in Original (used by the majority of schools investigating Ultra). This last mode is known as Dual Course mode, and even Blackboard executives are surprised to find out that the vast majority of schools putting Ultra in production are in fact running in Dual Course. For many of these schools, there are no definitive plans to ever move exclusively to Ultra.
This distinction is important, as the majority of functionality for an LMS occurs within a course, even if we did hear a few schools present that they saw some end-user benefits to having the landing page itself. We will add more commentary on this subject in future posts, but for now the takeaway is that Ultra in production numbers from Blackboard do not necessarily mean that any or most courses are in the Ultra Experience.
Product Variations Resulting in Three Dates for New Features
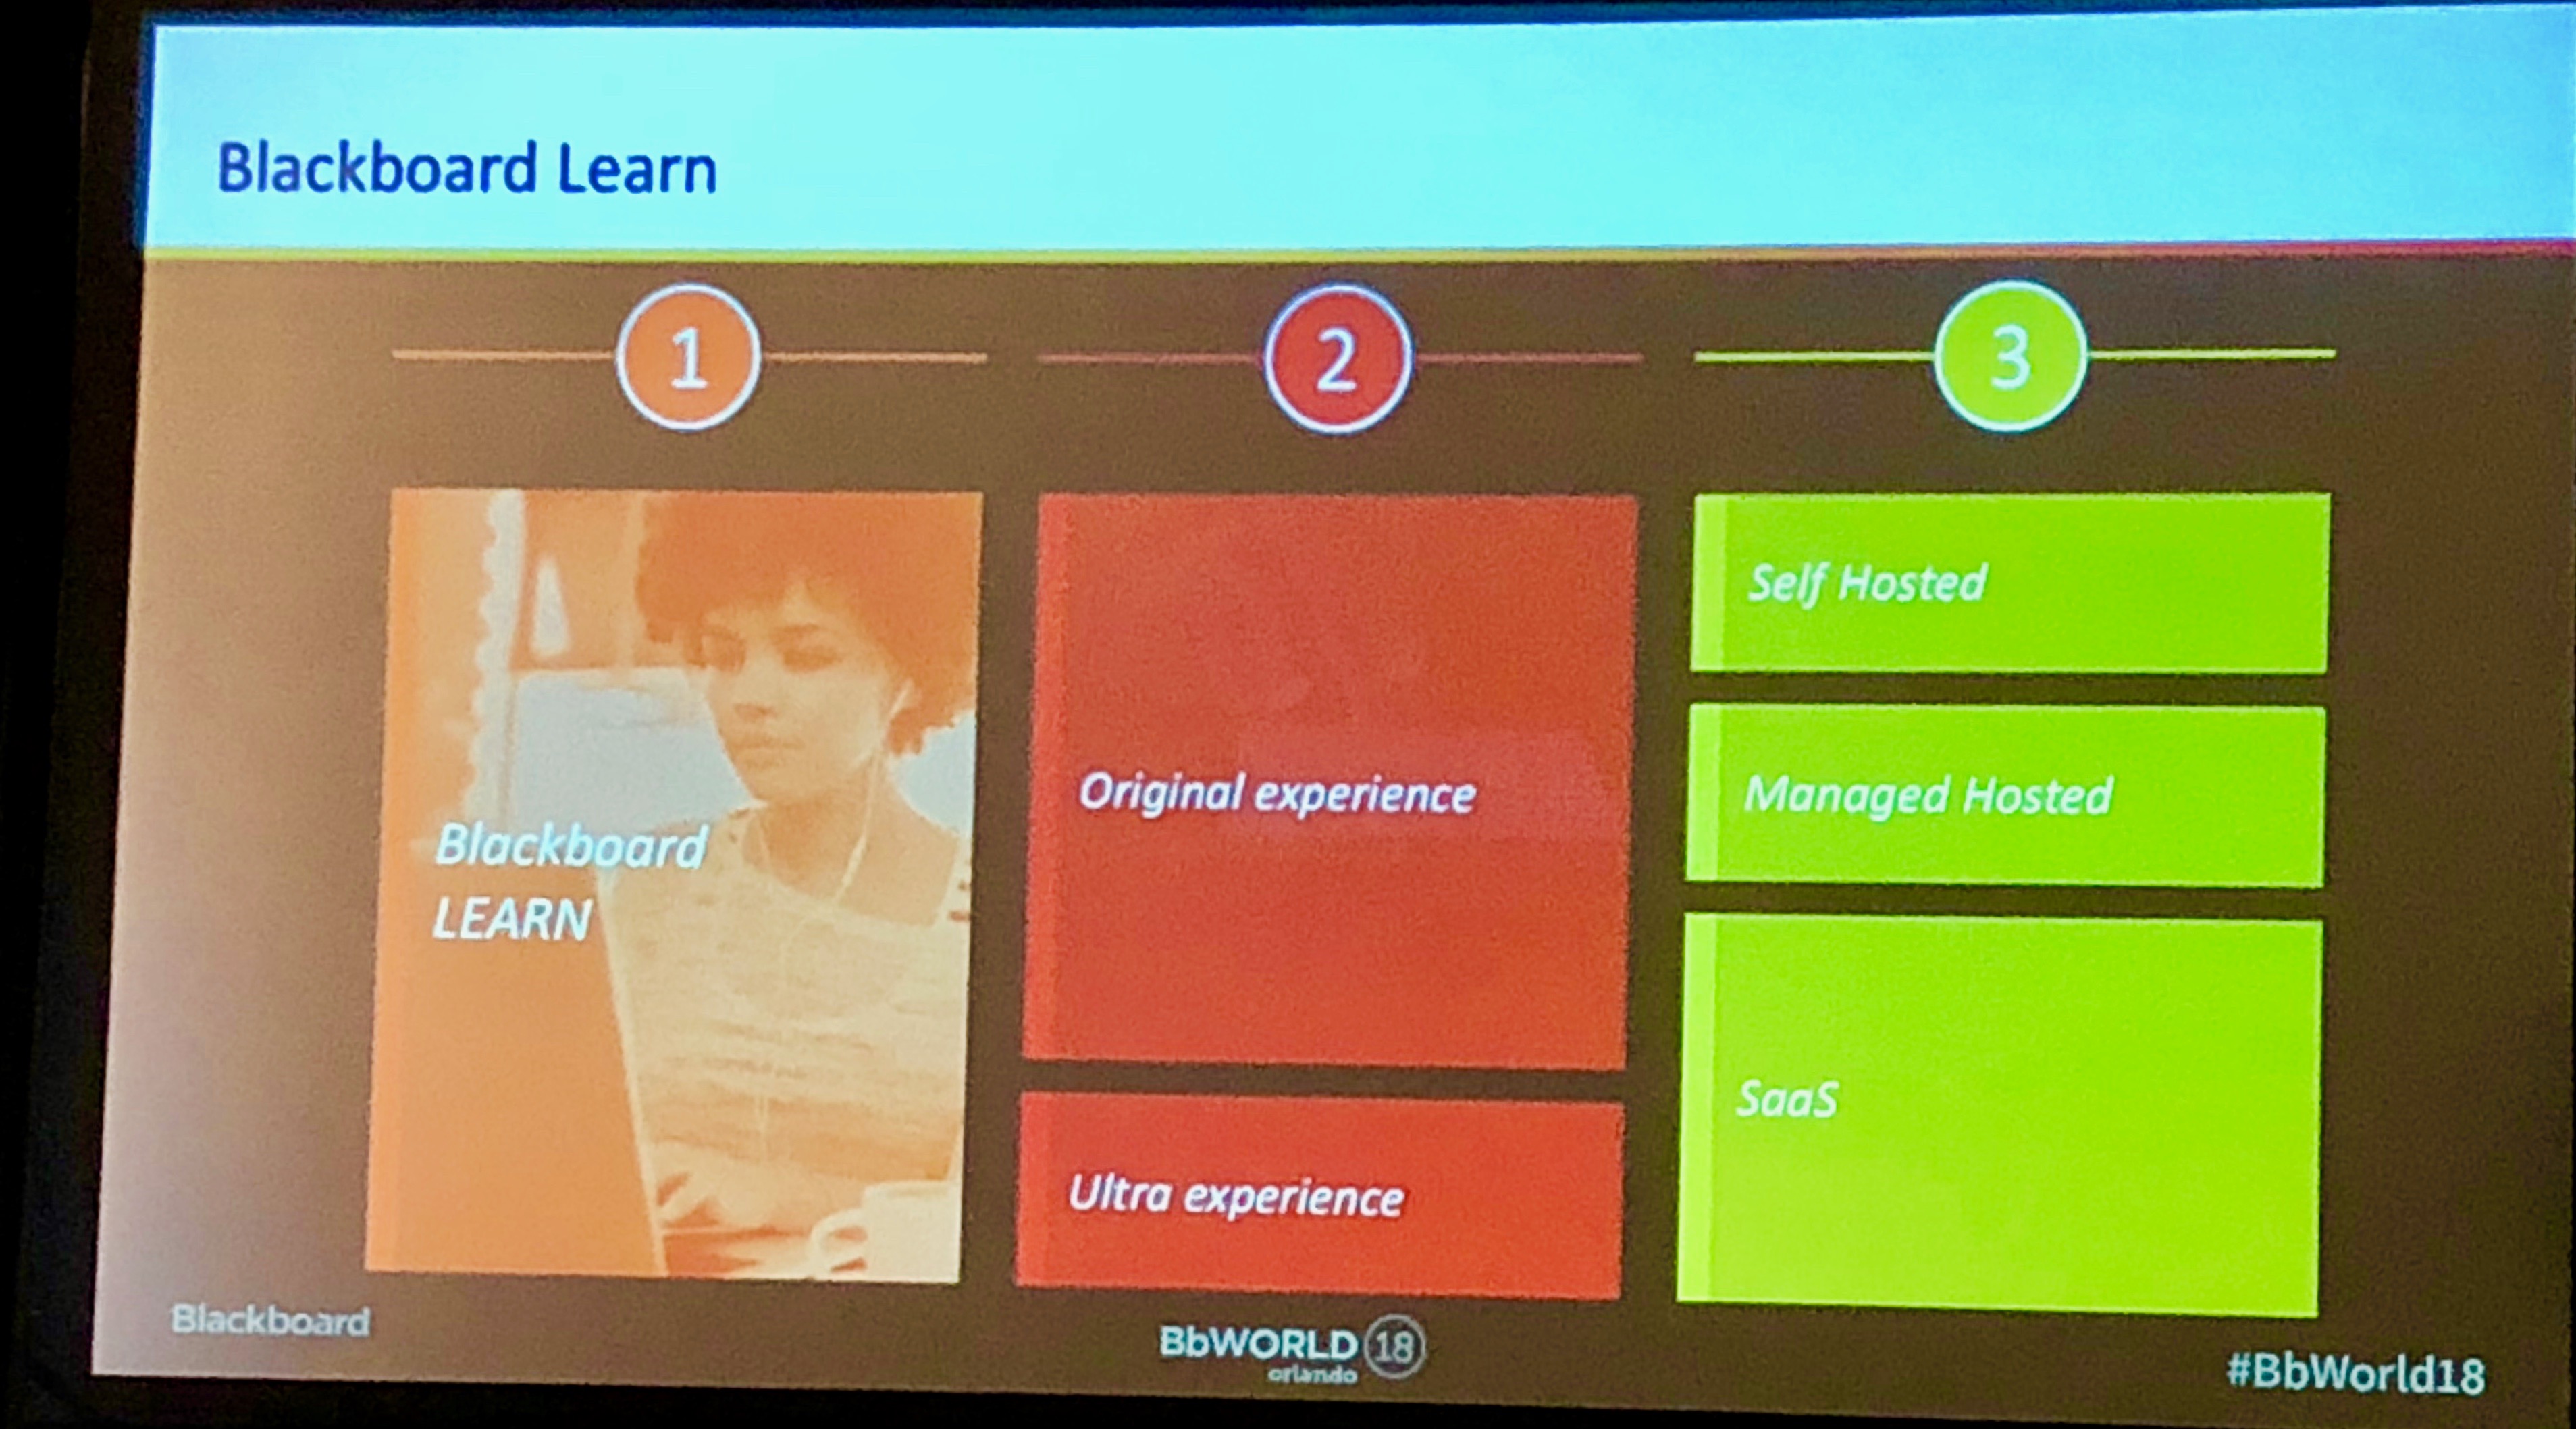
The second issue is that Blackboard Learn has two experiences (Ultra and Original), three deployments (self-hosting, managed-hosting by Blackboard, and SaaS-hosting at using AWS), often resulting in three different dates for full delivery of new features.
Keeping in mind that the Original Experience is available on all three deployment models but Ultra is available only in SaaS, here is the view of the final delivery groupings for the courses:
Learn Original on self-hosting and Learn Original on managed-hosting, which the bulk of their customers use, is the first case.
Learn Original on SaaS-hosting, which represents the bulk of their 383 customers on Learn SaaS announced at the conference, is the second case.
Learn Ultra, which represents some subset of the 62 customers announced as “Ultra in production”, is the third case.
Of course there is significant overlap in terms of common code, such as the micro-services running in the SaaS environment for both experiences, or shared source code between deployment options. But from a feature delivery perspective, the full release often has three different delivery dates – Original SH & MH, Original SaaS, and Ultra.
This is good news or bad news, depending on your perspective. For Blackboard’s customers, it means more options without forced migrations. Blackboard staff stated several times in presentations and in hallway conversations that none of the deployment options or experiences have any plans to go end-of-life or even into maintenance mode. But on the other hand, Blackboard will not achieve many of the benefits of becoming a cloud product company until they can move the majority of development purely onto SaaS.
SaaS Better Indicator Than Ultra of Client Retention
The third issue, which is related to the first two, is that we believe ((OK, OK. I admit that Michael should get credit for seeing this issue more clearly than I did. Not many people read footnotes, so I feel comfortable with this admission.)) that the migration to Learn SaaS might be a better indicator – at least in the short run – than Ultra adoption of whether a school plans to stick with Blackboard. Whether or not the school enables Ultra base navigation or any courses in the Ultra Experience.
When a school moves to Learn SaaS, they tend to sign contract extensions for 1 – 3 years to cover the new services. And the migration to Learn SaaS does not suffer from the vague terminology issues – a school either uses Learn deployed on SaaS (through AWS) or they don’t.
For now, just treat this as clarification on the complexities of Blackboard Learn LMS options that became more apparent at the conference.
Update 7/23: Changed header and some text in second section to focus on dates of feature delivery.
My last post on Canvas’ US market share surpassing Blackboard’s predictably got a fair bit of attention, including some follow-up press elsewhere on the internet. There were a few comments to the press made by Blackboard executives and industry experts that merit some further examination.
But let me start by being crystal clear about one point: In and of itself, the fact that (by our count) Canvas now has two more primary systems than Blackboard Learn in the US market, is purely symbolic. It has historic significance for those of us who have been long-time watchers (or sufferers) in the LMS market. But if Blackboard’s number were ten higher or ten lower, it wouldn’t change the big picture.
The more important question is this: If the crossing of the lines is purely symbolic, then what is it symbolic of? What actually matters about this story to colleges and universities, and why?
Let’s see if we can separate the signal from the noise by working our way through a couple of well-sourced articles and the commentary that they contain.
First, there’s Lindsay McKenzie’s piece in Inside Higher Ed. She chased down a number of customer reactions. Some of these were the usual pile-on of “we hate these guys and we love those guys.” ((See the comments on my original post; LMS personal commentary tends to be just a few steps removed from primal scream therapy. I’m not judging; just observing.)) But she also got an interesting pricing anecdote, which is helpful given how opaque LMS pricing tends to be:
Now that Canvas is the “hot product,” Instructure has been trying to aggressively increase its fees, said [Emporia State University’s Rob] Gibson. A 5 percent increase per year for such services is not unusual, but Instructure has been asking for more. Gibson said his institution has had to push back against further increases.
Blackboard, on the other hand, was “desperate to keep us,” said Gibson. They offered a 50 percent discount to stop Emporia from making the switch. “I think they could see the writing on the wall,” he said.
Customers take note: Blackboard’s change in fortunes may affect the behavior of all the LMS vendors.
The article also has a quote from Lou Pugliese who, in addition to being a current senior innovation fellow at ASU and CEO from Blackboard’s early days, was CEO of Moodlerooms when Blackboard acquired it. In other words, he knows something about the LMS market. He raised an interesting question:
Pugliese said that the statement that Canvas is “now the primary LMS in more U.S. colleges and universities than Blackboard Learn” is misleading. “The real measurement metric should be akin to website traffic. Statistical data on number of unique users, not total ‘installations,’” he said.
For a long time, Blackboard has been at the top of the LMS food chain not only in raw market share but in terms of having a high percentage of the largest customers. In fact, at one point the company killed off Learn Basic precisely because the company calculated that small colleges were not profitable enough to justify continuing to sell the cheaper, no-frills version of Learn.
So, if we look at number of students served in the US market rather than the number of universities served, is the market share picture substantially different?
Nope. ((But the picture of Brightspace’s market share relative to Moodle’s does.))
Second lesson: Blackboard’s customer loss is no longer contained to smaller colleges. Both the IHE piece and the Bloomberg piece that I will be commenting on next mention that Cornell, which is the birthplace of Blackboard, has announced that they will be moving to Canvas. This is another example of a milestone with more symbolic than literal significance. Blackboard’s loss of Cornell may sting from an emotional perspective, but it’s probably not material to the company’s balance sheet in and of itself. On the other hand, the loss of schools like Cornell is material. As is the loss of schools like Pugliese’s current professional home, ASU.
Lastly from the IHE piece, there’s a substantial quote from Blackboard’s Chief Learning and Innovation Officer Phill Miller:
Phill Miller, chief learning and innovation officer at Blackboard, said that the data shared by Feldstein were “not consistent with our own,” which show that “Blackboard remains the dominant ed-tech company around the globe.” He added that Blackboard Learn is not the only service that the company offers — “we have thousands of Blackboard Collaborate, Moodle and Blackboard Ally clients,” he said.
Miller said that over the past year and a half, Blackboard has “taken a hard look as a company at what we need to do to better serve our clients.”
In response to customer feedback, Blackboard has been working to improve existing products and develop new ones. Though Miller notes that development of Ultra “took longer than we anticipated,” he says institutions are reacting positively to the changes.
“We’re in a much different and better place than we were a year ago,” said Miller. “We’re seeing that RFPs are slowing down, our renewal rate is strong and we’ve won in a number of competitive situations recently.”
There’s a lot to unpack here. Let me preface my comments by saying that I’ve known Phill for well over a decade and have a high opinion of his integrity. I feel the need to say this because his comment about our data not being consistent with Blackboard’s own comes across in the context of the article as a dodge that I don’t believe Phill would make in regular conversation. Our numbers likely do differ modestly from Blackboard’s. Counting installations is more complex and requires more methodological decisions than you might think, such as the date when you officially register a switchover. But I don’t believe our numbers are different by much, and I don’t believe anyone can credibly deny that Canvas has achieved rough parity with Blackboard Learn in US market share.
The comment about Blackboard having “taken a hard look…at what we need to do to better serve our clients” is the right thing for any executive at a company with declining market share to say, and I believe it is also true in this case. Blackboard has had a long reputation hangover from former CEO Michael Chasen, who was notorious for his disregard of customer satisfaction. For what it’s worth, Blackboard is not that company anymore. Emphasis added here because people still have strong feelings about the company’s behavior from that era and don’t always realize that there has been a complete turnover in company management since then. (Twice.)
Case in point: To his credit, Miller owned up to the delays in Ultra. This isn’t new, but it is ongoing, so Blackboard needs to continue to be up front about the problem until customers are satisfied that it has been fully resolved. The company may be struggling to bring Ultra up to a level that customers consider “feature-complete,” but they have made a consistent and visible effort to take responsibility for their results.
Miller’s point that Blackboard sells more than just Learn is a valid and important one, but has to be weighed in the context of the company’s short- and medium-term financial challenges. The real issue of concern is the potential behavior of their debt and equity owners. I’ll come back to the point about Blackboard’s total product portfolio in that conxt.
Miller’s last comment, about seeing RFPs slowing down and a strong customer renewal rate, is the most consequential. Given that the market has been chasing Instructure on reliable SaaS, usability, and high-quality customer service, there has been (and continues to be) an outstanding question of how long Blackboard’s customer base will remain patient as it tries to catch up on these fronts. To be honest we at e-Literate are somewhat skeptical of Blackboard’s ability to forecast. Jay Bhatt, the company’s previous CEO, did enormous damage to the company’s sales force, which is an essential component of any company’s sensory apparatus. If customers are getting nervous and thinking about bolting, the sales reps should pick that up early. But it’s not clear that Blackboard’s early warning system is working properly at the moment. When the e-Literate team is at BbWorld next week, we’ll be looking for clues about customer sentiment.
The second “Blackboard alert” article worth reading is the one by Katherine Doherty and Eliza Ronalds-Hannon at Bloomberg News. This one wasn’t a reaction to our piece but rather coincidental timing triggered by the same underlying concerns. I spoke with Doherty, whose beat includes companies with distressed debt.
The debt is the real existential issue. Without it, Blackboard would just be a company that continues to struggle with its flagship product but which would have enough runway to turn itself around over time, one way or another. In the Bloomberg article, Blackboard CEO Bill Ballhaus repeats Miller’s reminder that the company sells other products and services. And as we have pointed out repeatedly here on e-Literate, the international markets are an increasingly large percentage of Blackboard’s financial picture. The fundamentals of the company may not be great, but they’re not dire either. Given time, good leadership, and low debt, a company in this position should be able to right itself.
But because Blackboard has high debt, their situation potentially a lot more volatile. One major reason why the market share milestone matters is that it’s an apt metaphor for Blackboard’s financial waterline. At their current debt levels, the company can’t afford for their market share to continue to drop.
Contract losses have sent Blackboard’s revenue and earnings sliding, according to people with knowledge of the matter, making it harder to carry more than $1.3 billion of rated debt. With some of Blackboard’s bonds selling at deeply distressed levels, Ballhaus is crafting a comeback, and possible options include the sale of its payment processing division, said the people, who asked not to be identified because the discussions are private.
Even in this situation, the results for Blackboard Learn customers won’t necessarily be bad, or even noticeable—depending on how the finances are resolved. If Blackboard sells off Transact, gets a good price for it, pays down some debt, and otherwise sticks with the current management’s plan, that could buy them some time and some ability to survive further erosion of market share around Learn. If the company’s owner, Providence Equity, decides to take more drastic steps, then the potential impact on customers is unpredictable. And Providence’s calculations regarding how much drastic action is required must be at least partly driven by their assessment of how close Blackboard is to bottoming out in LMS market share loss.
So what are the take-aways for LMS customers?
It is no longer the case the Blackboard is the big dog and Instructure is the underdog. And, as is suggested in the customer quote above about pricing, that may have consequences for the behaviors of all the vendors.
Blackboard is in a financially precarious situation in the short term. They have a number of options for getting themselves out of this situation, some of which are more impactful on customers than others. This is worth watching closely.
In the medium term, the fate of the company depends on them staunching the bleeding of market share, not because the loss of Learn customers is in danger of driving them out of business in and of itself, but because they need to buy time with their equity owners so that they can execute a turn-around strategy that will keep the company (relatively) intact. Ally may be a runaway hit in the market, but if its revenues aren’t growing faster than Learn revenues are shrinking, that will not go over well with equity investors.
The current situation is real trial by fire for Blackboard’s executive leadership, including some new players. Phill Miller in particular may have been in senior management for quite a while, but with the departure of Katie Blot, he is now very much in the hot seat now. And he’s not the only one. In the same company blog post that announced Phill’s promotion, Ballhaus announced a new Chief Portfolio Officer, Chief Strategy Officer, and Teaching and Learning product line lead. This is a particularly challenging moment to be an executive at that company.
All of this puts a lot of pressure on Blackboard to get customers migrated over to SaaS and convince the market that Ultra is ready for prime time now.
Blackboard may be in a tight spot, but don’t conflate that with behavior of the previous management in the bad old days. Schadenfreude may feel good, but it doesn’t help when you’re making strategic decisions. Evaluate Blackboard based on what they do today, not on what they did 10 years ago.
As of July 6th, our data partner LISTedTECH informs us that Canvas is now the primary LMS in more US colleges and universities than Blackboard Learn. By a margin of two; Canvas has 1,218 installations, while Blackboard Learn has 1,216. Statistically speaking, the two companies are tied for US market share:
Still, this is a stunning development for a company that seemed to have established an unbreakable market dominance a decade ago. When Blackboard, the number-one US platform in early 2005, announced that it would be acquiring its closest competitor (WebCT) in early 2006, the combined company owned approximately 70% of the US and Canadian market. Their next largest competitors were far, far behind. A few platforms, most of which no longer exist, were vying with “homegrown” to become the Dr. Pepper of the LMS market at the time that the Coke acquired the Pepsi.
Blackboard’s acquisition of WebCT hit the market like a thunderbolt. At the time, I wrote,
Yes, yes, we’ve all heard the news by now. BlackCT Wednesday has hit. Will it be remembered as The Day the Music Died? I don’t think so. Unfortunately, it could be remembered as The Day the Music Was So Badly Wounded That It Became Barely Listenable for a Really Long Time.
You know. Kinda like the ’80’s. Except with software.
Blackboard was already viscerally disliked, both as a product and as a company, by a large segment of the market in those days. Customers responded to the merger by talking with their feet. Moodle, Sakai, and Desire2Learn—A.K.A. Brightspace—all surged in 2006 and 2007 as customers began fleeing the Blackboard behemoth.
Blackboard responded by suing D2L ((D2L was called Desire2Learn at the time and shortened its name later.)) for patent infringement in 2006, acquiring ANGEL Learning in 2009, and acquiring Moodlerooms—the largest US Moodle support company—in 2012. It seemed like the US LMS market was done. Any time a competitor grew large enough to become a threat, Blackboard would acquire them and force migrate their customers to Learn. If they couldn’t acquire the company, then they would attempt to sue them into submission.
Nobody would have predicted that a project started by two graduate students Brigham Young University and assisted by their professor, who happened to be a bored former executive from a pioneering cloud storage company, would become the product that could break through Blackboard’s dominance. Yet that is exactly what happened. The Canvas LMS was concieved, and Instructure formed, in 2008. The combination of a reliable, cloud-based offering, updated user interface, reputation for outstanding customer service, and brash, in-your-face branding, the company surpassed all of the more established contenders to take the crown (at least in the US).
Not just symbolic
Anybody who has paid attention to this market at all knows that Blackboard’s market share has been dropping while Instructure’s has been rising. But this symbolic end of an era marks more than just those two market share lines crossing. Bigger changes are afoot.
Humans have a tendency to assume that what is true now and has been true for a while will continue to be true in the future. The LMS market was more vulnerable to change than we thought it was in 2006, and it is more vulnerable to change than many realize today. Blackboard in particular is in a precarious position. Their long-delayed Ultra user experience refresh has been dragging out for so long now that customers who have been hanging on waiting for it are in danger of losing patience. It’s not clear whether, as of the upcoming BbWorld conference this month, Ultra will finally be feature-competitive with either the original Blackboard Learn interface or the competition. And even if it is, it’s unclear whether that will be enough to prevent another mass exodus of Blackboard customers, nevermind attract new ones.
Meanwhile, their private equity ownership has the company in financial peril. Even with a shrinking customer base, Blackboard has been a relatively well-run and financially healthy company—if you don’t count the pile of debt that their private equity owner has saddled them with. But they have big interest payments to make. When Providence Equity bought Blackboard, they paid for it by taking out something analagous to a massive mortgage on Blackboard itself, with the plan that Blackboard would pay off that debt with the profit that it generates. This is a classic private equity investment strategy, but sometimes it backfires. Blackboard would be doing OK financially, despite its shrinking market share, were it not for those massive mortgage payments. The LMS market is seasonal, which means that Blackboard sells more in some months than in others. During the better months, the company can still comfortably make its debt payments. During the slower months, debt ratings company Moody’s warns that Blackboard’s margin for error on being able to make those debt payments is worryingly thin.
But it’s worse than that. Sticking with the mortgage analogy, some of Blackboard’s debt has what you can think of as very aggressive foreclosure terms, in the form of “lien covenants.” If the company’s cushion for making its debt payments drop below a certain level—even if it doesn’t actually miss a payment—then the bondholders can demand that Blackboard pay off the principle. If this were to happen, it would likely force the Blackboard into bankruptcy. (Keep in mind that bankruptcy doesn’t necessarily mean that the company disappears. But it’s not good.)
So because of its financing, Blackboard’s continuing loss of market share is at the tipping point of changing from a serious problem to an existential threat.
Lo, how the mighty have fallen.
What might happen next
Chances are good that we will see some fairly dramatic changes at Blackboard soon. Even if Ultra catches up with the competition this summer, and even if that is enough to prevent a major customer exodus, and even if all of that is enough for the company to avoid triggering the bankruptcy-inducing lien covenants, the company will have to take some steps to improve its financial soundness. The easiest place for them to start would be to sell off of some parts of the business so that they can pay down some of their debt. (Blackboard’s Transact commerce and security line of business is the most obvious candidate.) But that may only be the beginning. The next possible move would be for Providence Equity, the company that owns Blackboard, to sell them off—either as a whole or in pieces. Depending on how all of this plays out, it could be good, neutral, or bad for current customers. All we can say with confidence right now is that there will probably be some significant changes fairly soon.
The other companies are not static either. Instructure lostmuch of its executive management team, and we are now hearing rumors of a second wave of departures in the Asia/Pacific region. Between these changes and Wall Street’s pressure on the company to show more growth in the corporate training side of their business, it remains to be seen how much past performance will be predictive of future behavior. Meanwhile, D2L has quietly been improving their core product.
People tend to only focus on the top two competitors in any product category: Coke and Pepsi, Hertz and Avis, Uber and Lyft, and so on. And, as I noted at the top of the post, they also tend to underestimate potential for change. If Blackboard’s situation changes dramatically enough to shake up these default assumptions among customers, then that could open up all kinds of possibilities. Maybe Brightspace will rise, or Moodle will be resurgent. Maybe Instructure will continue to gobble up market share until it owns the market the way Blackboard did back in the day. Maybe a couple of kids in some university somewhere will come up with the next big thing. Maybe Blackboard will pull a rabit out of a hat. It’s hard to know right now. The market is approaching a tipping point, which means that a some basic assumptions about the LMS market that people could take for granted during the era of Blackboard’s dominance are not safe to assume anymore.
We just released our Spring 2018 report for our LMS market analysis subscription service, which provides more context for these potential changes (including a more international view of the markets than I’ve provided in this post). As we enter LMS conference season, we will be providing increased coverage of the market, both here on the blog and in the monthly newsletter in the subscription service.