e-Literate

Present is Prologue

Category: LMS & Learning Platforms

Everything you want to know about Learning Management Systems and whatever comes after them.


  • D2L Bets on The Cloud and Advances in User Experience

    D2L Bets on The Cloud and Advances in User Experience

    One of the arguments that we have made as part of our LMS Market Analysis service is that if you look beyond market share numbers, there has been a tectonic shift in the academic LMS market that started around 2012, moving from being Blackboard-centric to Canvas-centric. Meaning that the current market trends are largely driven by Canvas adoptions and market reactions to Canvas adoptions. This change has elevated the need for viable LMS solutions to have both a cloud-based deployment strategy as well as a more modern, intuitive user experience than what was acceptable just five years ago.

    Blackboard’s move to Learn SaaS (deployment) and Learn Ultra (new user experience) is a prime example of this market dynamic, and it has tended to get the lion’s share of analysis, including here at e-Literate. We have described that D2L has joined Canvas in “an emerging two-horse race for new implementations”, but we could do a better job of describing why we believe they are gaining in the market. ((Disclosure: D2L, Blackboard, and Instructure are subscribers in our LMS Market Analysis service and sponsoring participants in our Empirical Educator Project.))

    Short story – D2L has made fairly substantial bets on cloud deployment and a streamlined user experience, and the product design changes present the best explanation for the market gains.

    Head in the Cloud

    The data looking at new LMS implementations (changing from one system to another) in higher ed across the four global regions we cover in our market analysis shows a remarkable movement away from self hosting, or on-premises hosting, towards a combination of managed hosting by the LMS vendor or cloud hosting designed by the vendor but running on AWS, in particular. From 15% external hosting to 77% in just one decade. Within the external models, there is another major shift away from managed hosting and towards cloud hosting.
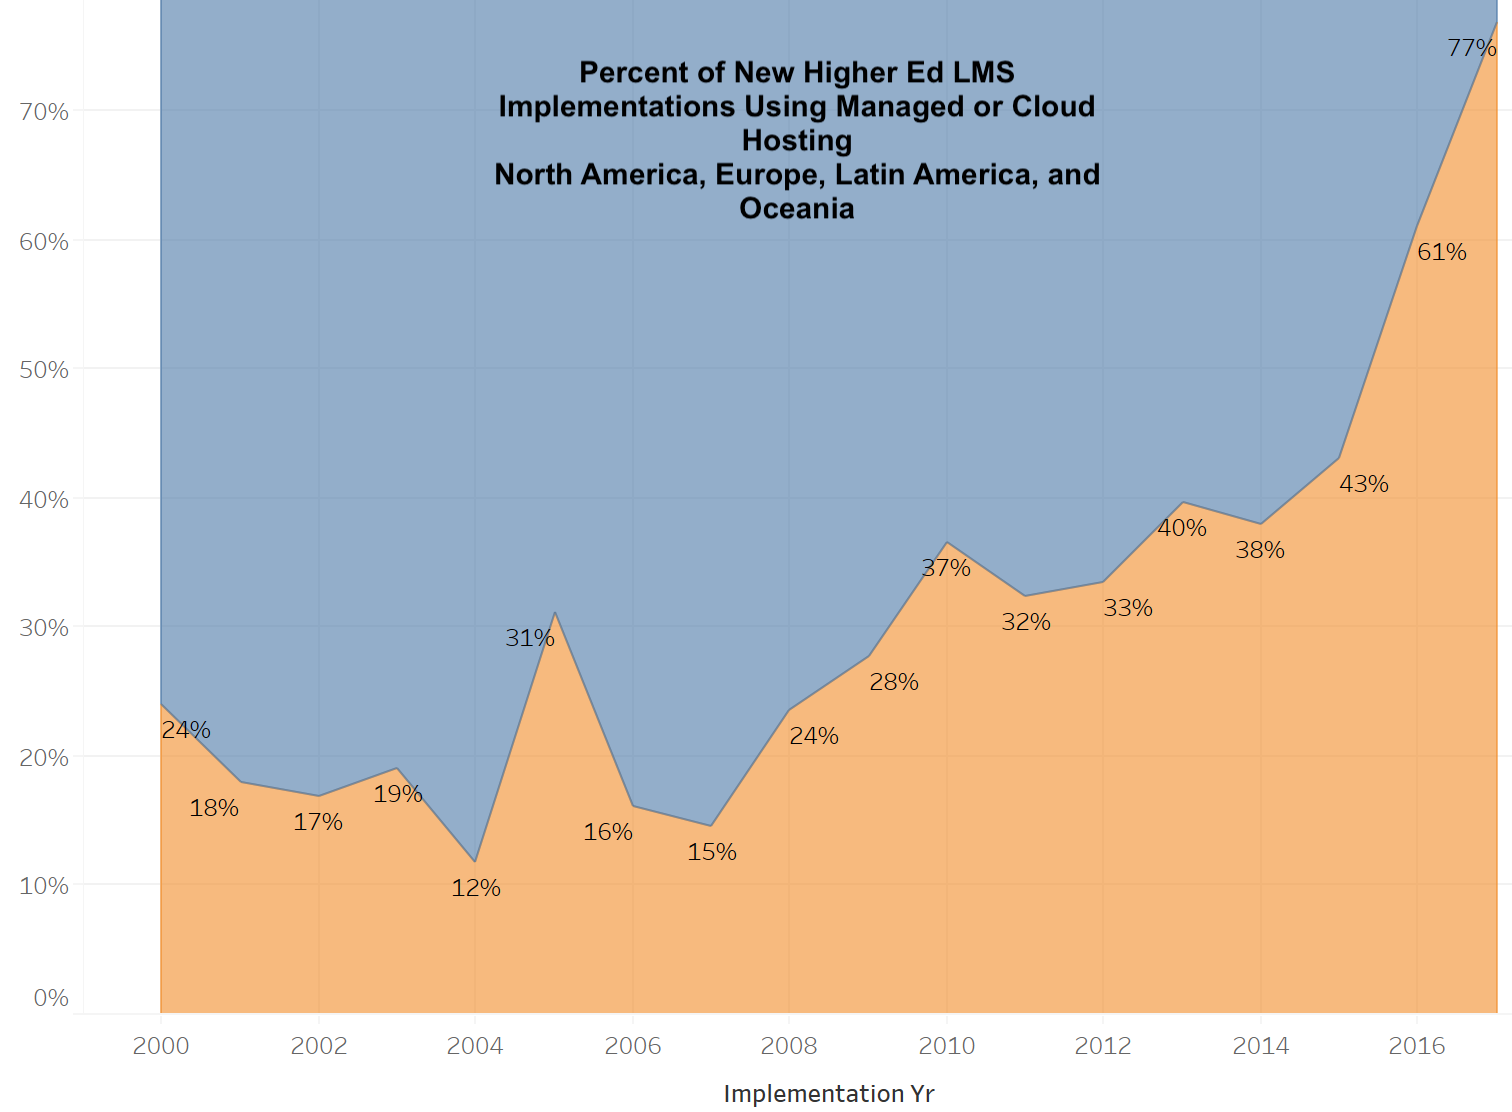
    Growth of LMS external hosting

    D2L has long worked on managed hosting options, but in late 2013 the company introduced Continuous Delivery where software releases are pushed to customers incrementally, such that customers would jointly run the latest versions of Brightspace, their LMS. This move is important, as one primary benefit of cloud deployment is to remove the explosion of software configurations and versions that make it expensive and difficult to diagnose and fix bugs and to release new features.

    Three years later in 2016 D2L announced their move to AWS for cloud deployment.

    AWS Data Centers for D2L

    While we heard grumblings from multiple clients during the transition – especially thru early 2017 – D2L clearly made some hard choices and and is aggressively moving to the cloud, not just as an option, but as their primary delivery model. According to David Koehn, VP of Product Management at D2L:

    • All new Brightspace implementations are on AWS cloud;
    • Virtually all current Brightspace implementations use Continuous Delivery; and
    • Approximately 50% of current customers are already on the AWS version of cloud deployment; and
    • By the end of 2018, a large majority of customers will be on cloud deployment.

    Contrast this move to the cloud with Blackboard’s where they plan to continue offering self hosting, managed hosting, and their own AWS-based cloud hosting options at the customer’s choice, while they believe SaaS and Ultra will lead on new sales. The primary constraint being that to go to Learn Ultra experience, you must first be on Learn SaaS, the cloud hosting option. But the key point is that Blackboard has tended to view the cloud as one deployment option among others, and the numbers show it. According to a company blog post this week from CEO Bill Ballhaus:

    As of today, more than 50 clients are running Ultra, with dozens more planning to start using the Ultra experience and courses in the second half of the year. Also, 361 clients around the globe have moved to SaaS deployment for Learn.

    Our data show more than 2,000 higher ed customers on Learn, but if you add in K-12 and corporate customers, this roughly equates to just over 10% on or moving to Learn SaaS and 2% on Learn Ultra. These are generous numbers, but more on that in a separate post.

    The point is that D2L is making a much more aggressive and focused bet on the cloud than is Blackboard, for better or worse. Canvas, of course, is designed natively for the cloud, and essentially 100% of their customers are on the AWS cloud.

    Run to Daylight

    David Koehn also pointed out that the real driver for the AWS cloud move by D2L is to enable a redesign of the user experience and to provide improved scalability and reliability. In other words, the cloud deployment is a means to the Daylight end.

    Daylight is the name for D2L’s redesign of the user experience and its streamlined user interface. When it was first announced just over a year ago, I was somewhat skeptical as the initial changes were evident in different fonts and cleaner look-and-feel, but not significant improvements in the workflow for faculty and students.

    As time goes on and I see more advanced demos, my view is changing. The Daylight Experience does have some real improvements not just in look-and-feel but in fewer and more intuitive clicks to get the same job done. A major focus on the release this summer (in time for D2L Fusion users conference) is more fully encouraging usage of the activity stream for higher ed clients (this feature was initially targeted at K-12 market but has been adapted for colleges and universities).
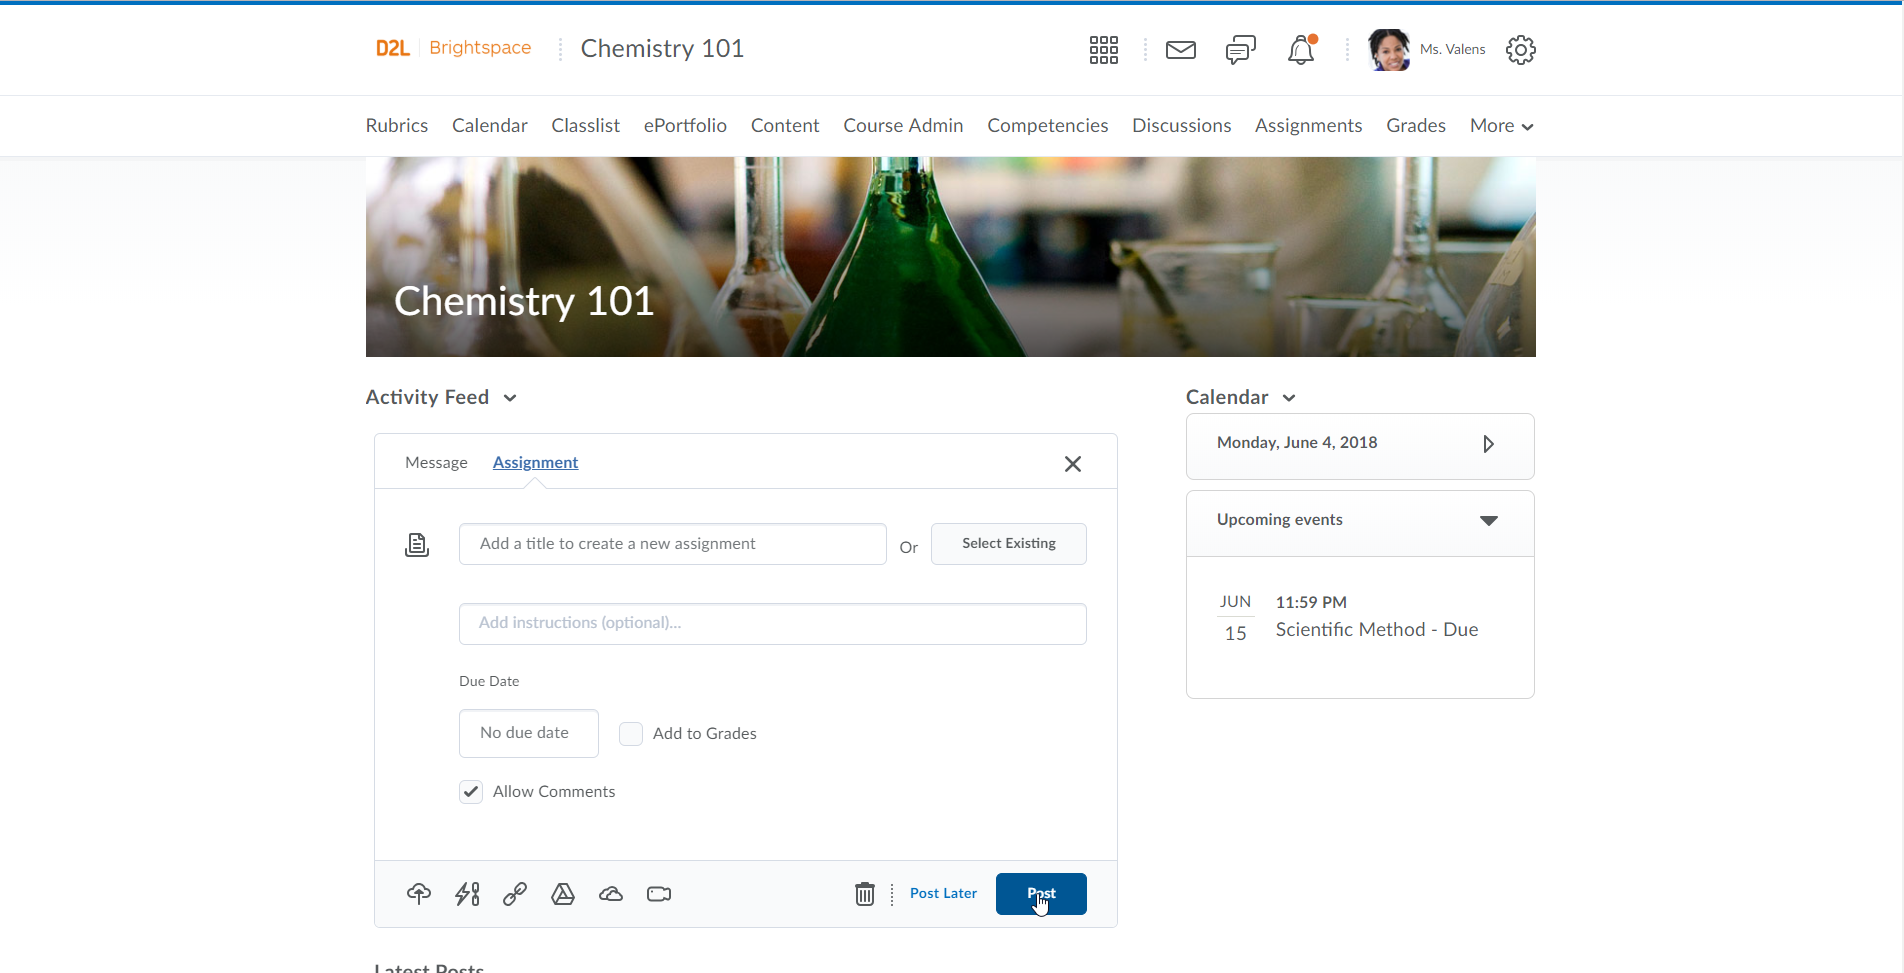
    Brightspace add assignment

    D2L has long played the Mutually Assured Destruction game of features, targeted at cumbersome procurement processes. D2L (along with Blackboard and Moodle) has a deep set of features which contrasts with Canvas and its streamlined set of features that rely on third-party integrations to solve some of the more specialized use cases. For D2L, it is important to maintain these features as a competitive differentiator with Canvas, and the design approach guiding them is Progressive Disclosure. This design technique relies on progressing from simple to complex, showing the user the information and options they need when they need it or request it and not before.

    Consider adding a multiple choice quiz, where the desire is to make this process very simple, but to then have a page or area that exposes more and more options as requested by user or in context of the quiz setup.
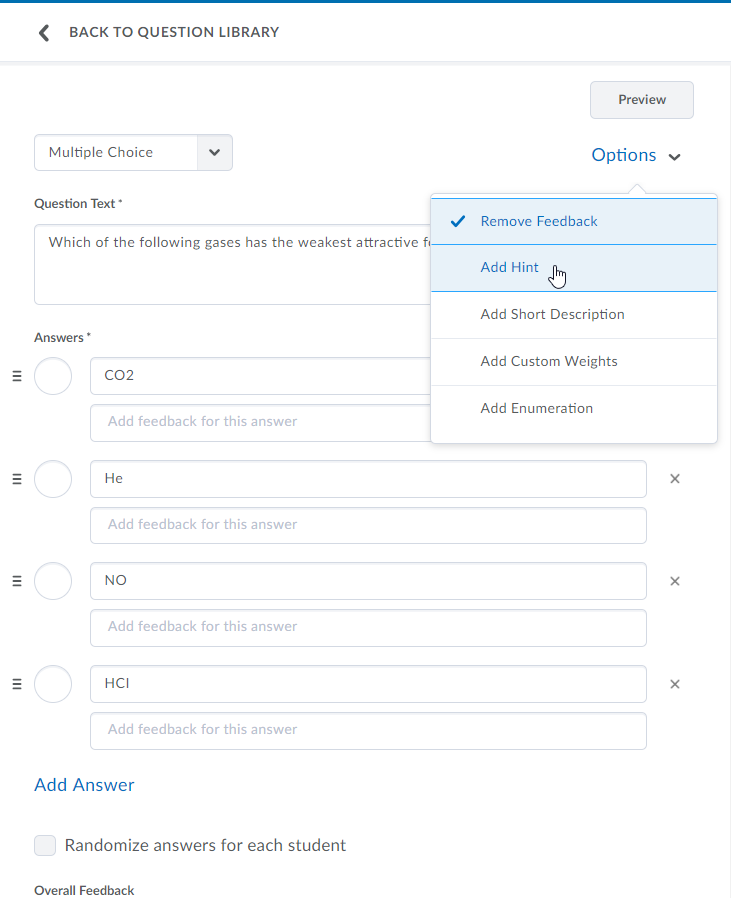
    Brightspace details on quiz

    As D2L further implements this design approach within the Daylight Experience, we are seeing a more modern and intuitive user experience for Brightspace customers, yet one that is showing real promise to also tap into deeper feature sets. And these changes are being used in production.

    Again by way of contrast, Blackboard’s user experience redesign for Learn Ultra has had a bumpy ride, with multi-year delays of getting any customers to use in production. They took more of a big bang approach to releasing Learn Ultra, and when customers pushed back saying that Ultra wasn’t ready, this led to additional delays and eventually a change in the design team. D2L’s Daylight has proven to be a more iterative release of their new user experience.

    What to Watch

    This year it is becoming difficult to separate LMS products from company finances. Instructure is trying to balance Canvas and Bridge growth to satisfy public markets along with a new executive team. Blackboard is dealing with corporate debt challenges while needing to fully release Learn Ultra. As mentioned in this post, D2L is moving strongly to the cloud with a new user experience while managing expenses. Schoology is trying to grow higher ed market under the radar. Moodle HQ took investment for the first time. There are a lot of open questions on the future of the academic LMS market, and we expect much to be revealed at the big summer (and fall) events.

    As for D2L Fusion, we plan to get a better read on how customers and prospects are reacting to the cloud deployment move and streamlined user experience. We are seeing real changes in the Brightspace design and deployment model, but do paying and prospective customers value these changes? Furthermore, will D2L be able to improve its customer service and delivery on promises made for new customers as well as it has improved its product design?

    As for Blackboard, Learn Ultra now has D2L’s Brightspace as a major user experience to compete with as well as Canvas. There is a lot more changing in the LMS market than what is obvious on the surface.

    Update: Clarified D2L numbers to be specifically for AWS cloud deployment. Also changed several instances of “cloud hosting” to be “cloud deployment” to make terminology more accurate.

  • Interview with CEO of Instructure on changes to executive team

    Interview with CEO of Instructure on changes to executive team

    Instructure is now a decade old as a company and faces a crucial test this year with recent changes to their executive management team and the need to scale both Canvas (academic LMS) and Bridge (corporate learning LMS). The long-time head of sales, Marc Maloy, and head of marketing, Misty Frost, left Instructure in the fall. The company eventually hired a new head of marketing, Bjorn Eriksson from the world of corporate HR, in January. After a months-long search, Instructure did not directly replace Marc with a new head of sales, but instead they hired a new president, Dan Goldsmith, who also has sales leaders reporting directly to him. With this move, Mitch Macfarlane, the long-time chief operating officer and former head of client services, will be leaving the company this summer. ((Disclosure: Instructure and D2L are subscribers to our LMS market analysis service and were sponsors at our recent Empirical Educator Project summit.))

    We’ve written about previous executive changes for Instructure – when their two founders left the company and when their CTO departed after just one year – but in each case the company managed the transitions and came out stronger in the end. As we have shared in our LMS Market Analysis service and on e-Literate, the Canvas track record is remarkable in terms of not losing customers and gaining new customers from most other LMS providers.

    But the executive changes over the past year come at a time when Instructure faces new challenges in product development and implementation support. At InstructureCon 2016, the company announced their next-generation quizzing platform, Quizzes.Next, stating that it would be “made available to you over the course of the next several months”. Last summer at InstructureCon 2017, Quizzes.Next entered a limited beta program, but the new set of tools is still not fully in production. To our knowledge, this might be the biggest product schedule miss in the company’s history, and it will be quite interesting to see what happens with this summer’s InstructureCon.

    In addition, we have had several people contact us privately, even before the most recent management change, telling us about a new level of frustration in implementation projects and product upgrades. None of the tales were extreme, but they were unusual for Canvas clients and in general spoke to distractions from staff and lack of clear answers and updates.

    The press release announcing the hiring of Dan Goldsmith included this description:

    With more than 20 years of experience in software and services, Goldsmith’s career is marked by directing high-performing global teams and achieving outstanding penetration and growth in challenging markets. Goldsmith spent the last eight years as a senior executive at Veeva Systems, a cloud-based software company, where he started and ran Veeva’s international business, led the company’s strategy in new markets and products, and most recently was responsible for Veeva’s global engagement and growth in strategic accounts.

    “It is an exciting time for Instructure. We are well positioned for success as we focus on the continued growth of Canvas, expansion of Bridge, and international execution,” said Josh Coates, CEO of Instructure. “Dan’s energy, creativity and proven track record in driving go-to-market strategies and rapidly scaling businesses make him a tremendous addition to Instructure at the perfect time to lead us through our next phase of growth.”

    Goldsmith was one of the first 50 employees at Veeva. He helped lead the company through a successful IPO and a growth path to a $10 billion market cap. Prior to Veeva, he worked in various executive positions at top companies, including Accenture, PwC and IBM. During his years in management consulting, Goldsmith led initiatives in global markets and developed new offerings. Goldsmith will have an immediate impact on Instructure’s strategy. His initial focus will be on market growth, with the sales leaders reporting directly to him.

    This was the setup for an interview that we had with Josh Coates, the CEO of Instructure, last week. Given our focus at e-Literate on education markets, we in particular wanted to ask about how the company is balancing the needs of Canvas and Bridge.

    Coates came prepared for the interview, and up front he made the point that the “vast majority of company resources” are allocated to the academic markets and that this is their foundational business. After we pointed out that the majority of discussions on quarterly earnings calls focus on Bridge, Coates noted that Wall Street is overly focused on corporate learning markets and unfortunately takes Canvas’ academic market performance for granted. He does not do so, but some of the investor community seems to.

    The primary selling points bringing Goldsmith to Instructure are that he helped Veeva grow into a $10 billion company, having joined as one of first ~40 employees, and that he specifically helped them grow international markets. According to Coates, Goldsmith spent his first three years opening up the Europe, Middle East, and Africa (EMEA) markets, and that yes, his international experience is a big reason for Instructure recruiting him.

    We have noted at e-Literate that Canvas really began international expansion just 3-4 years ago. According to our current data, Canvas leads in higher ed adoptions in Europe and Australia / New Zealand, but interestingly, D2L is beating Canvas in Latin America higher ed adoptions despite Instructure having a bigger investment in its regional office in São Paulo. At some point Canvas’ market share growth rate in North America will have to flatten out and international markets will naturally increase in importance for company finances. While market wins in Europe and Australia / New Zealand are impressive, Instructure will need more aggressive growth in other markets, and clearly Goldsmith is being tapped as a catalyst to increase sales overseas.

    We pointed out that Goldsmith had no education background and appears to be more closely aligned to corporate learning markets than higher ed or K-12 markets. Coates responded that Goldsmith has done quite well for himself at Veeva but is also passionate about education, as evidenced by his experience as the chair of the Montgomery School board of trustees. Coates acknowledged that this is not deep academic sector experience and that the company will need to give Goldsmith a big education on higher ed and K-12 markets. If we had a dollar for every time we heard of a rich dude who is passionate about education, well, we’d be rich dudes who are passionate about education. It is good to hear, however, the acknowledgement that the new executive brings rich software company scaling and international market growth experience but not domain knowledge of the academic markets for Canvas.

    We asked for an update on Quizzes.Next – when it will be generally available (GA) and whether the schedule challenges are related to the executive changes. Josh Coates assured me that no executives are working on the code, but Jared Stein, VP of higher ed product strategy, answered more directly.

    Quizzes.Next’s GA release is scheduled for Summer 2018. This is later than planned because we underestimated the complexity of building assessments entirely as a micro-service at the level of quality we set for ourselves and our users.

    The executive management team over the years has played a big role in establishing the company culture that is a large part of Instructure’s success. Now that the three M’s (Marc, Misty and Mitch) are out, the question is not whether the culture will change, but how. Coates’ acknowledges this reality and trusts that Instructure’s internal rudder is strong enough to keep the company on course.

    There are two company risks that stand out in trying to balance Canvas and Bridge. First is that complacency sets in not just with some in the investment community but with Instructure itself, and they begin to take their strong position in the academic market for granted. Second, and related, is that resources and talent end up flowing disproportionately to the corporate learning market given its increasing importance. These are risks to watch and not observations of actions, however, and Coates was emphatic that the academic market will always be the foundation of Instructure’s business. The corporate learning market is significantly larger than the academic market, however, and Coates estimated that in ten years or so, corporate will likely drive a larger portion of Instructure’s revenue.

    It should be noted that growth in corporate does not have to come at the expense of the academic market. It actually has the potential to strengthen product offerings in higher ed and K-12 as Instructure gains deeper insights into teaching and learning more broadly. There is also the potential for convergence, or at least cross-pollination, in these markets as the profile and needs of learners evolve.

    We’ll keep a close eye on academic LMS market trends in the coming months for signs of new developments. For the near term, at least, Instructure’s success is predicated on the continued success of Canvas in higher education and K-12 despite the quarterly investor calls skewing toward the corporate learning markets and new management hires with experience outside of the education sector.

  • Portentous Changes in Instructure’s Executive Management

    Portentous Changes in Instructure’s Executive Management

    Instructure just announced the hiring of a new president. Dan Goldsmith is a software executive with experience in SaaS, international markets, and business-to-business sales, but not with education. He “will have broad responsibilities overseeing sales, marketing, product, customer experience, engineering and business development.” At the same time, COO Mitch Macfarlane is leaving. So this is a major reorganization. Taken together with the earlier departures of the company’s long-time sales and marketing executives, there has been a near complete turnover and reorganization of their top-level management.

    To some extent, this is to be expected. People do start to cash out after an IPO. But the turnover and reorganization at Instructure seems quite significant—at a company that has stood out in the industry for having a tight, highly functional management team.

    We’ll have more to say about these changes in the coming weeks. For now, I’ll predict that 2018 and 2019 will continue to be eventful in the higher education LMS space.

  • Comparing the First Ten Years of Blackboard and Instructure in LMS Market

    Comparing the First Ten Years of Blackboard and Instructure in LMS Market

    Last year Blackboard celebrated their 20th anniversary as a company, and this year Instructure celebrated their 10th. Yes, the company with Canvas, the “new” LMS solution, is a decade old. To gain historical perspective, it is interesting to compare each company’s first ten years in business in terms of primary financials – revenue and income – and performance in their core North American Higher Education market.

    We can only go so far in comparing the companies on this basis, however, due to different circumstances.

    • Most importantly, Blackboard helped create the LMS market and therefore had significant portion of its expansion in a greenfield situation, picking up clients who had not previously used an institution-wide LMS. Canvas entered the market well after saturation, with greater than 90% of institutions already having a standard LMS.
    • Blackboard developed its product line pre-cloud, with on-premise hosting being the primary deployment model. Canvas was cloud-native, developed on top of AWS infrastructure.
    • Blackboard’s growth was heavily based on corporate acquisition of competitors – Prometheus, WebCourse, WebCT in the first decade – while Instructure’s growth has been almost exclusively organic.
    • Both companies sold in more than just the North American Higher Ed (NAHE) LMS market, even if that was the core. Blackboard acquired two companies in 2000 and launched a card-reader transaction business, and they played somewhat in the K-12 and corporate learning space. Instructure developed Bridge for corporate learning, Arc for video platform, and it has a heavy presence in the K-12 LMS market.

    Interestingly, both companies went public in Year 7 (Blackboard in 2004, Instructure in 2015).

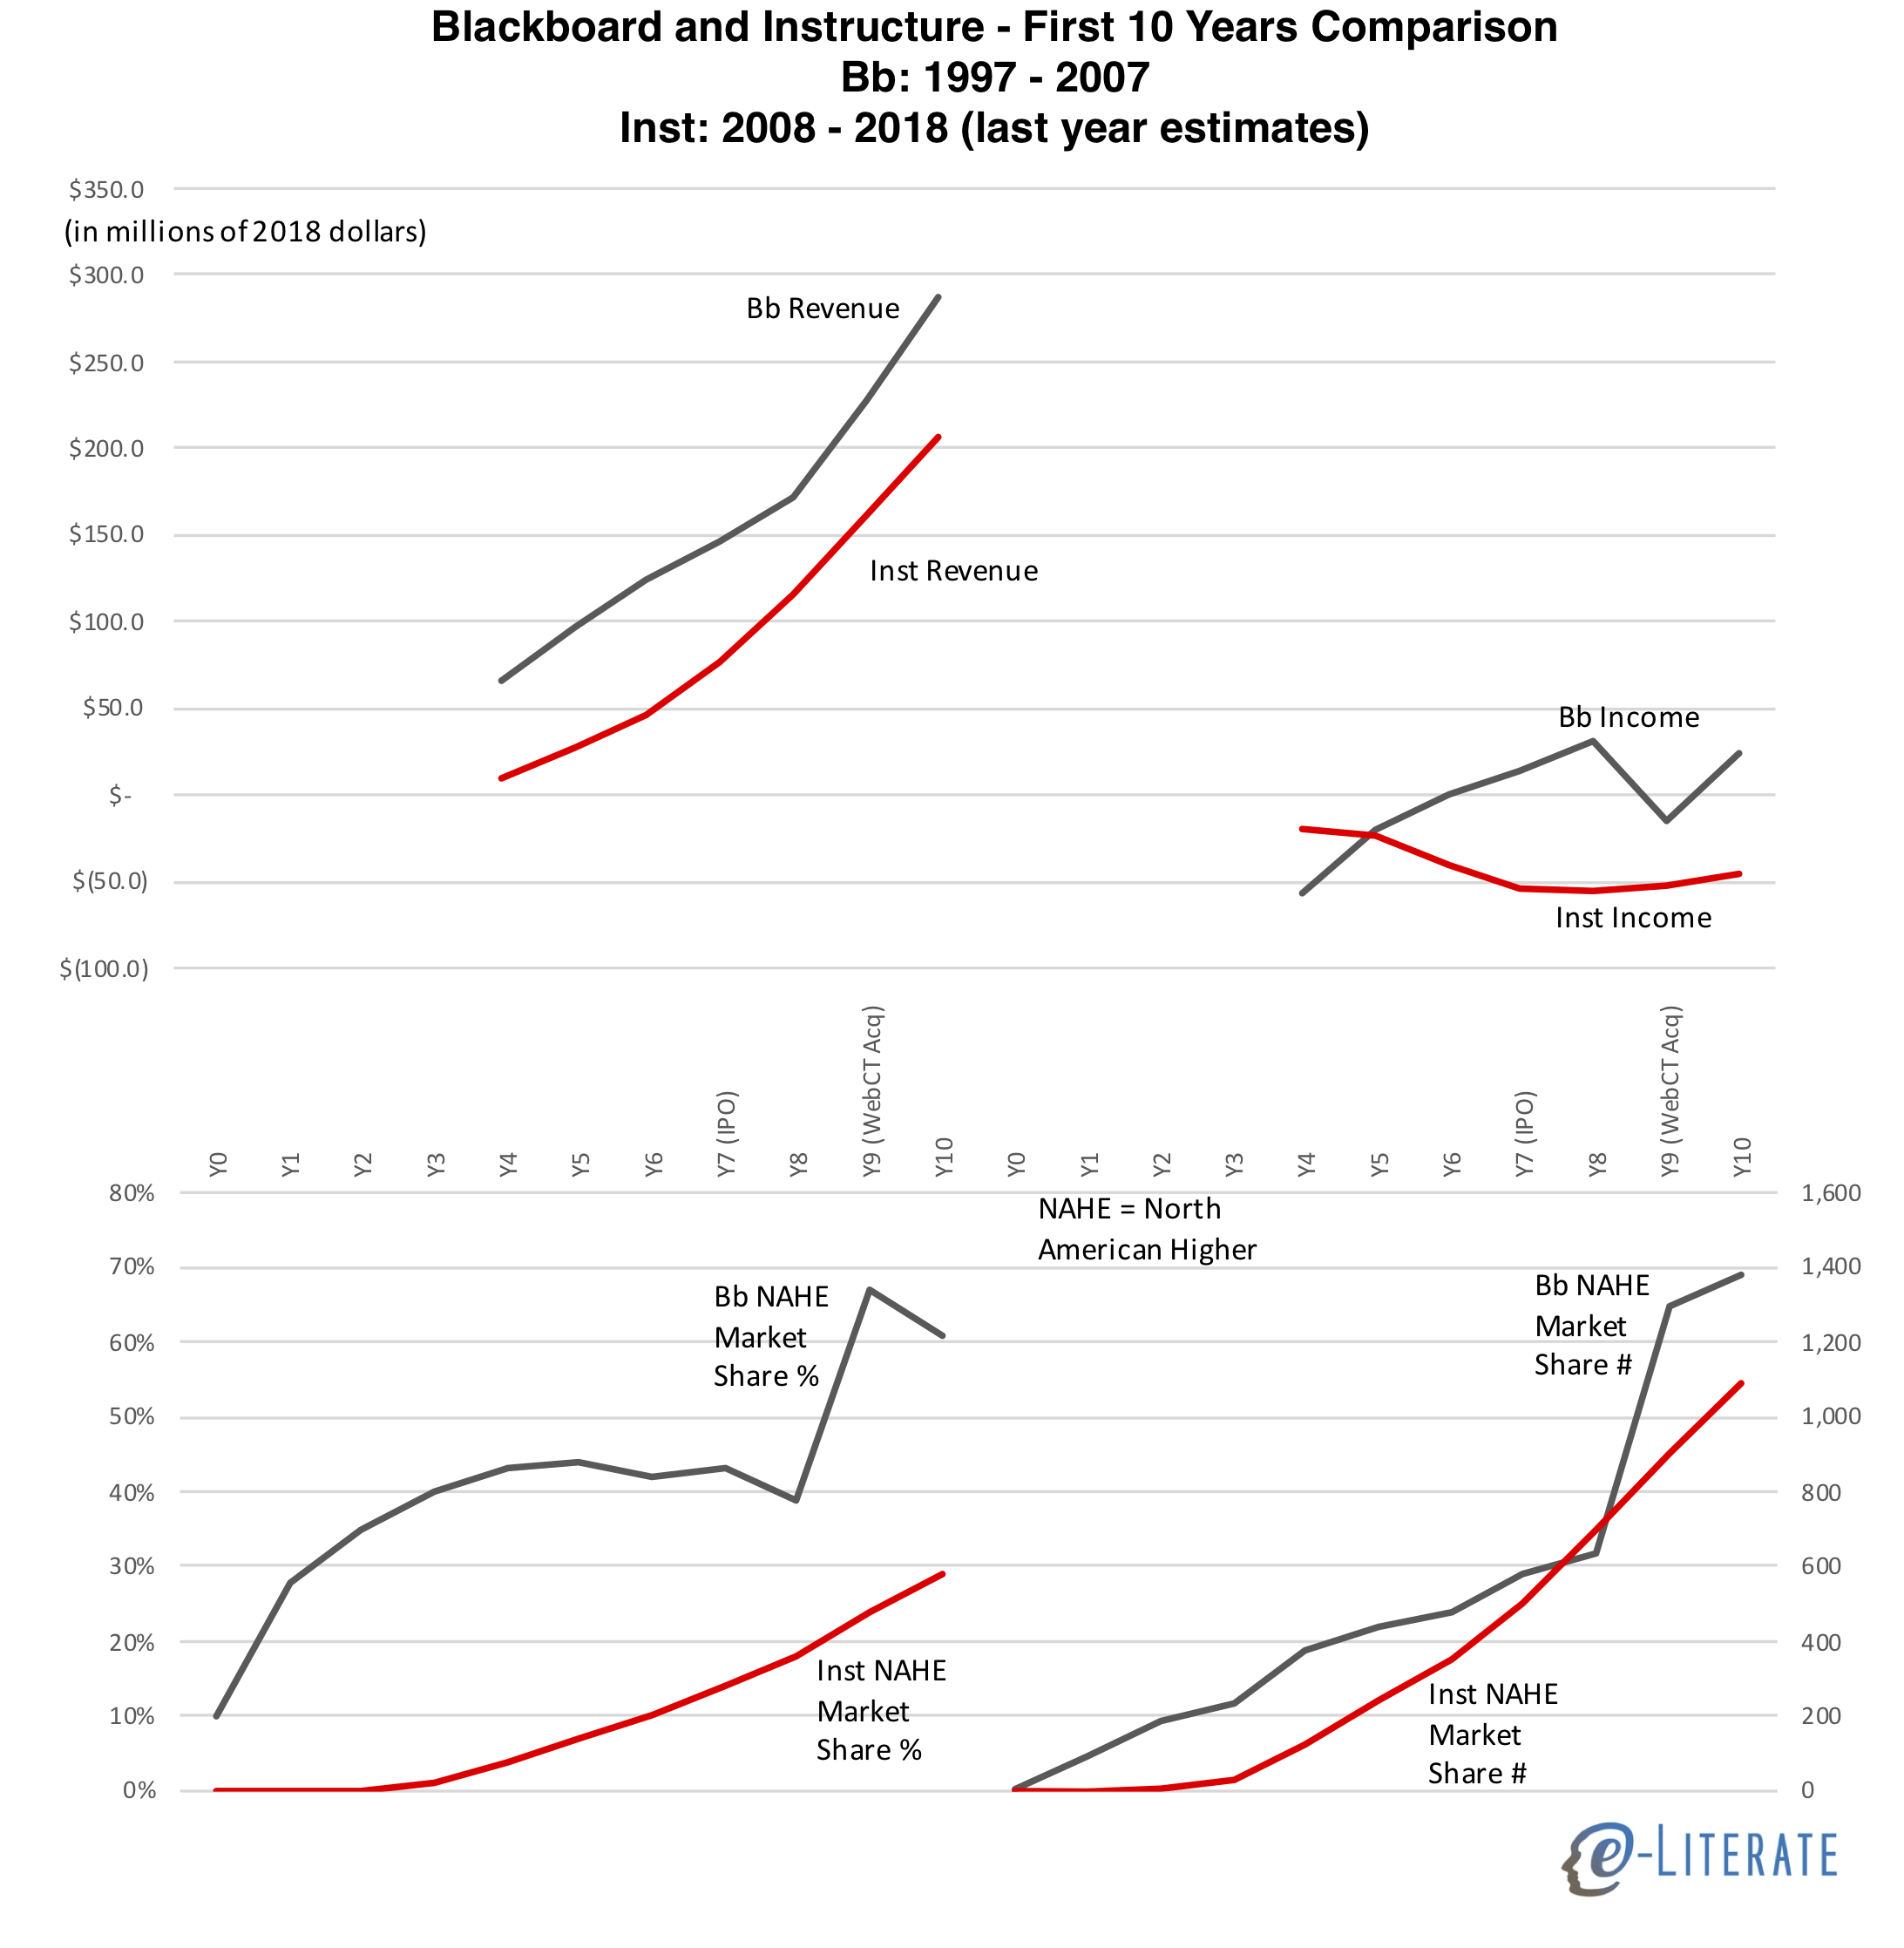
    With that in mind, let’s compare revenue, operating income – both derived from public SEC filings and adjusted to 2018 dollars – and market share in their core NAHE market. The financial data comes from public filings, and data for 2018 for Instructure are estimates based on their outlook presented in the most recent quarterly earnings release. Market share data is based on our LMS Market Analysis service and associated financial analysis for premium subscribers.

    Blackboard and Instructure revenue and income in 2018 dollars, and north american higher ed market share in percentage and numbers

    Some notes:

    • Blackboard raised ~$185 million in venture financing pre-IPO while Instructure raised ~$95 million (both in 2018 dollars). Part of this difference can be attributed to the much higher costs associated with pre-cloud enterprise software deployment models.
    • Blackboard’s revenue was higher than Instructure’s at similar points, and their operating income was mostly positive after Year 6. Instructure has maintained a significant loss each year from operations. One way to explain this difference is that Blackboard’s used funds for corporate acquisitions, thus fueling growth, while Instructure invested funds into sales & marketing and organic growth. This is not the whole story, but it is a big difference between the two companies.
    • In market share represented as a percentage, Blackboard’s growth was much faster, but this was in a period where the market was developing and not all schools had a standard LMS. When viewing this market share in raw numbers, we see that Instructure’s growth would have exceeded Blackboard’s were it not for the Year 9 WebCT acquisition.
    • Blackboard was already showing organic market declines (in NAHE market share %) and slowdowns in raw numbers outside of the immediate WebCT acquisition of customers. Instructure’s organic growth shows no signs yet of slowing down, is less lumpy and more predictable.


  • Moody’s Downgrades Blackboard Debt, Focuses On Learn Ultra Delivery

    Moody’s Downgrades Blackboard Debt, Focuses On Learn Ultra Delivery

    In Spring 2015 Moody’s affirmed their B2 rating for Blackboard’s nearly $1.4 billion in debt as part of the company’s acquisition of Schoolwires, with a negative outlook for the ratings (meaning there was risk of a further downgrade). Three weeks ago, that downgrade took place.

    (“Moody’s”) downgraded Blackboard Inc.’s Corporate Family Rating (“CFR”) by two notches to Caa1, from B2, as well as its Probability of Default Rating, to Caa1-PD, from B2-PD. Moody’s also downgraded Blackboard’s $135 million first-lien revolving credit facility and $920 million (remaining balance) first-lien term loan to B3, from B1, and its $378 million second-lien notes to Caa3, from Caa1. Moody’s also changed Blackboard’s outlook to stable, from negative.

    Put in regular terminology, the previous B2 rating indicated that Blackboard ((Disclosure: Blackboard is a subscriber to our LMS market analysis service and is a sponsor for our recent Empirical Educator Project summit.)) had “the capacity to meet its financial commitments. Adverse business, financial, or economic conditions will likely impair the obligor’s capacity or willingness to meet its financial commitments.” But with the new Caa1 rating, Blackboard “is currently vulnerable, and is dependent upon favorable business, financial, and economic conditions to meet its financial commitments.”

    The rationale for the downgrade is that Blackboard holds a very high amount of debt (now more than $1.4 billion) relative to its earnings, and revenue growth is not coming from its core markets.

    Blackboard’s core North American Higher Education (“NAHE”) and K-12 units, representing 56% of total revenue, continue to show weakening top line results, suggesting that the success of its new Ultra user interface is still uncertain. Blackboard’s international segment, also weak, has shown modest stabilization of late. Only the campus enablement segment, consisting of recently acquired educational community communications and transaction processing services and representing a quarter of Blackboard’s revenues, has shown healthy, reliable revenue growth. Some ratings support is provided by Blackboard’s high level of revenue visibility, with three quarters of 2017 revenues coming from recurring products and services, and underpinned by its 90% renewal rates in 2017. Both of these measures, however, represent declines from prior years.

    The turnaround is stalling, and the credit cards are maxed out. Blackboard has continued to cut costs, including “late-year layoffs”, and Moody’s expects “overall revenues to be flat to down slightly in 2018 as competitors have stifled market share gains”.

    While this is not good news for Blackboard, the ratings action does give the ed tech community additional insight into the operations and health of the company. Blackboard total revenues are between $700 – $720 million, with earnings (EBITDA, adjusted by Moody’s) between $160 – $180 million.

    And in the rationale for the ratings comes specific commentary on Learn Ultra.

    Software renewals have been weaker than expected in the NAHE [North American Higher Ed] segment, as the company strives to sell its latest learning management system (“LMS”) software enhancement, Ultra, into a crowded and very competitive marketplace. Given operating seasonality tied to the academic year, the behind-schedule launch of Ultra, in mid-2016, meant that measurable revenue and EBITDA [Earnings before interest, tax, depreciation and amortization] contributions from it began to be realized only in the 2017 academic year. There are indications that Ultra is gaining traction relative to Canvas and Desire2Learn, and Moody’s believes the packaging of Ultra with transaction- and payment-processing services may support its competitive positioning. But the success of Ultra is far from certain, and the threat from existing and possibly new competitors remains high as barriers to entry, specifically for web-based software, are relatively low. Meanwhile Blackboard, with a brand new CFO, is focusing its research, sales and marketing, and product development resources in an effort to ensure Ultra’s future.

    We have covered the 2014 announcement and ongoing fate of Learn Ultra here at e-Literate, and claiming a “launch of Ultra, in mid-2016” is generous at best. At that point there were educator previews with no ability for institutional adoptions. Fall 2017 is the closest to what I would say is an actual launch. As of a January, 2018 meeting Michael and I had with Blackboard’s management team, they claimed dozens of schools actively piloting Learn Ultra ((I have asked several times for this list, or a subset of this list, of schools piloting Ultra to allow interviews. If and when we receive schools to interview, we will cover in another post.)), and their flagship customer University of Phoenix is beginning rollout of the LMS starting this month.

    What is going well at Blackboard is the movement to a SaaS (software as a service, aka ‘the cloud’) model for the LMS – for both the traditional experience and Ultra experience. As of January there were 284 schools on Learn SaaS and 49 others in migration. In a purchase-only report, Moody’s acknowledged this strength and noted the investment that Blackboard is making in this area (more than $50 m expected in 2018).

    While the company has shown good progress in migrating its legacy Learn customers onto the appropriate SaaS-based platform from which those customers may choose, in turn, to migrate to Ultra, Blackboard’s efforts to make those transitions smooth for its customers have entailed elevated capital expenditures, which will likely continue through 2019, cutting into free cash flow.

    Put this all together, and 2018 is the year that Blackboard needs to transition from ‘wait until Learn Ultra is ready’ to ‘Learn Ultra had better lead to increased sales’.  I have been impressed with the new management team’s transparent approach to dealing with analysts, and with their honest approach to understanding the problems they need to solve. But the company needs to deliver, and this is shaping up to be a newsworthy year for Blackboard, for good or ill. There’s a lot to watch here.

  • Preliminary Data on K-12 LMS Market

    Preliminary Data on K-12 LMS Market

    Over the past several months, we have worked with our partners at LISTedTECH as they ramp up their efforts to collect data on LMS usage in the K-12 market in the United States. This is a massive effort as the market includes more than 130,000 individual public and private schools, and more than 13,600 school districts, according to recent NCES documentation. We are aware of several private data sources with estimates on the K-12 LMS market, but there are no public sources.

    Part of the challenge is that the K-12 market is messier than higher education’s and its roughly 7,200 institutions. One reason is that the general IT infrastructure in K-12 is less mature than in higher ed, and for smaller schools there are a lot of ad hoc implementations running on a local server not even in a data center. Another reason is the availability of free options such as Google Classroom, or freemium options such as that offered by Schoology and Canvas for individual faculty.

    As we build up the data and improve our methods, we believe we are starting to see some interesting trends in the data worth sharing.

    Our initial sample looks at 6,875 public schools from across the country in the NCES-designated primary, middle, high and other (special ed, vocational or alternative) categories. These results were analyzed over several data collection methods along with manual evaluation of that data. That said, we expect to see movement in the numbers as we collect and verify additional data, including LMS usage at private schools.

    As in our analysis of the higher ed market, we are focusing on school-wide implementations of LMS platforms. At many K-12 schools, in the absence of a school-wide implementation, individual teachers opt to use an LMS for their particular classroom, often for free. We do not consider this case a school-wide adoption and therefore do not include those use cases in our data. This methodology does not fully analyze total usage of a platform like Schoology that has a freemium model, including a free option for individual teachers and an enterprise solution which is a school-wide adoption based on a fee per student model. A platform like Google Classroom likewise has usage by individual teachers as well as school-wide implementations.

    Before we share the preliminary data, some caveats are in order to hopefully avoid anyone misrepresenting this information:

    • This is preliminary data that will likely change as we learn more. While we believe there are some broad trends already emerging, there will be refinements as we increase our coverage over time. We expect the changes to be in small adjustments to specific numbers but not in big changes to market shape.
    • This view is based on number of schools that have implemented an LMS, which is a different metric than district-wide implementations (where many or most of the purchasing decisions occur) or implementations scaled by student enrollments. We will add these views in the future.
    • This view is based on installed base (which represents total estimated deployments), which is different than new implementations in a given time period (which would measure market momentum). Again, we will add these views over time, just as we have done for the higher ed LMS market.
    • Due in particular to the free options available in K-12, there will be schools that have more than one LMS available at the institutional level. Google Classroom in particular is often available as an option at a school even when there is another LMS.
    • As is our practice at e-Literate, we’ll describe the caveats and present the data as is. As we learn more, if the relative percentages change significantly, we will share updates.
    • For more information on our data methods, see this post.

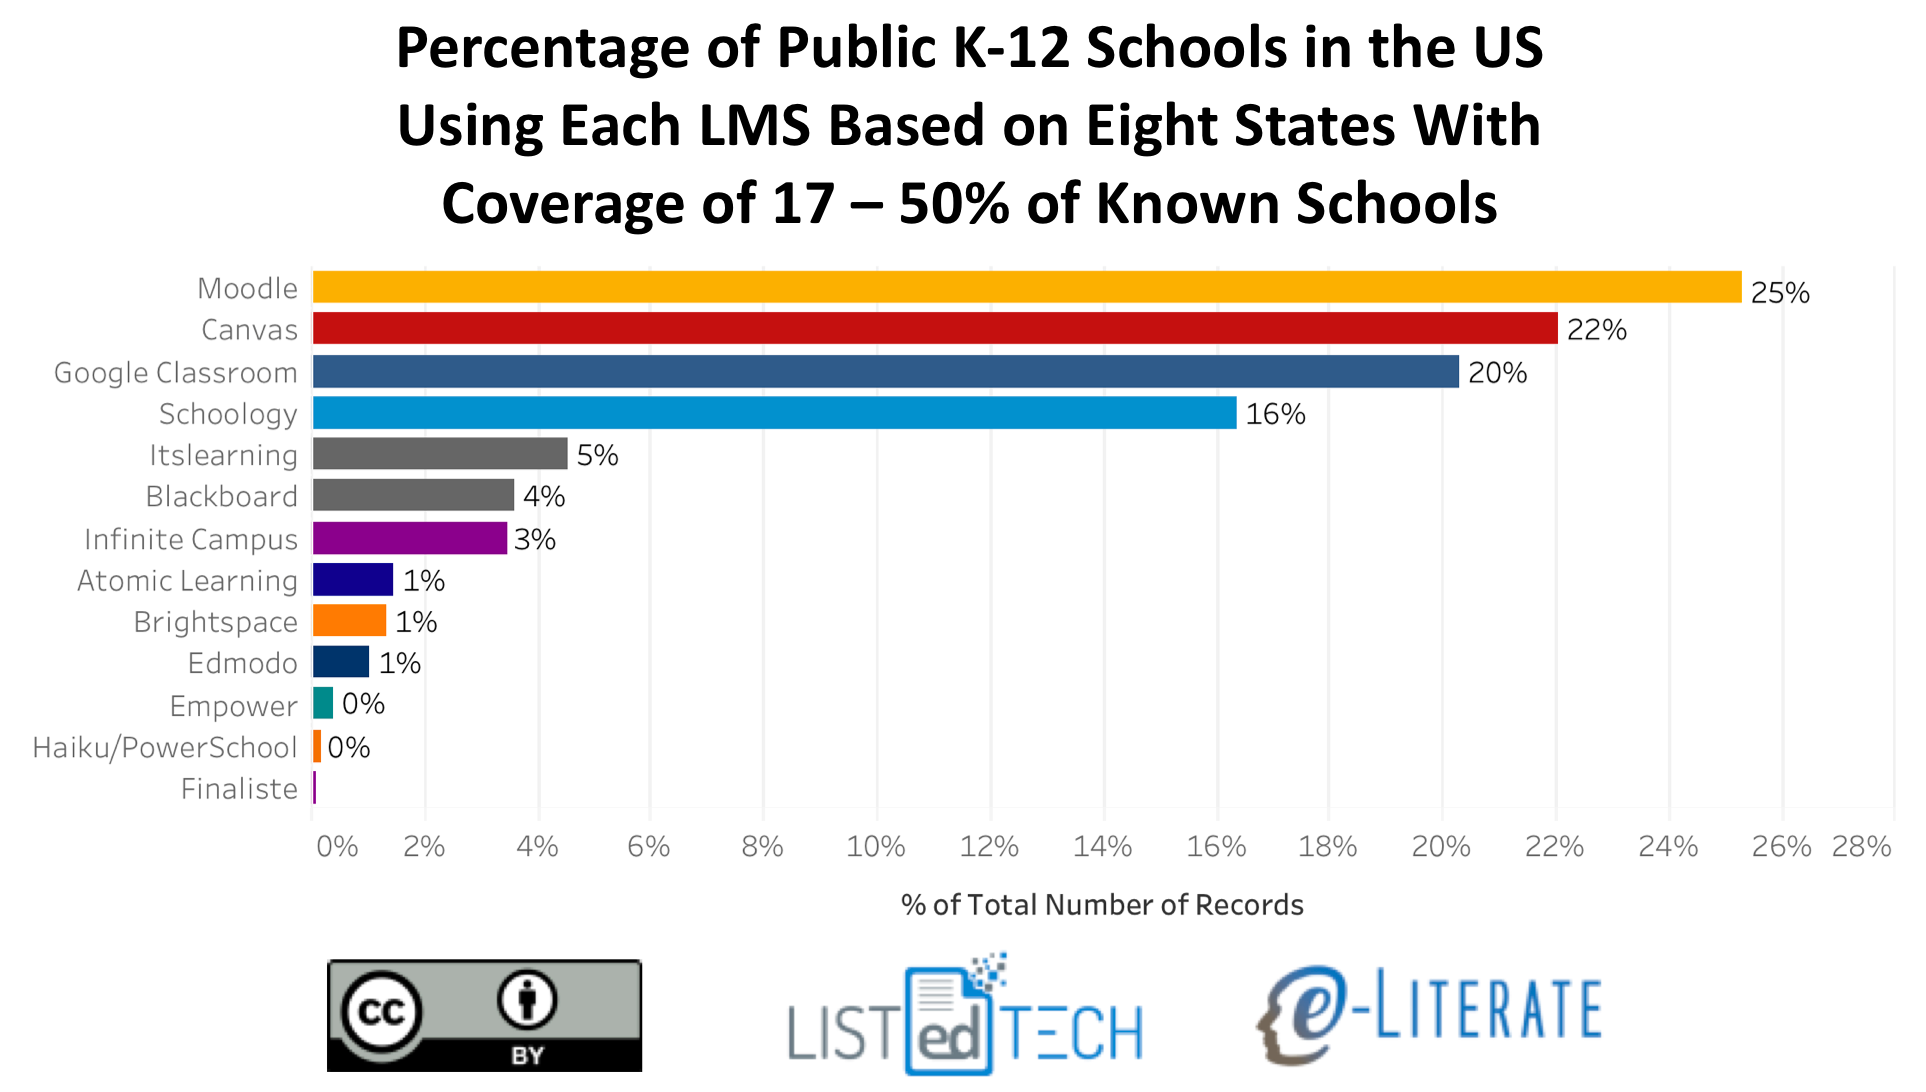
    The first graph presents a view of K-12 school-wide LMS implementations in the United States for the 8 states (and DC) where we have at least 17% coverage of known schools (Alaska, Delaware, District of Columbia, Florida, Massachusetts, Minnesota, Texas, Wisconsin).

    LMS Market Share for K-12 in US, 8 States

    To get a sense of how representative this initial market share is, we made the same calculations across all 6,875 schools from 50 states and DC that in our data thus far. The data for each LMS matched within ~2% for each LMS (e.g. Canvas went from 22% to 24%, Moodle went from 25% to 24%) between the two views.

    As in the higher education market, there appears to be four top contenders in K-12 – Moodle, Canvas, Google Classroom, and Schoology – with all others having 5% or less of market share. Moodle and Canvas are both present in the Big Four for both higher education and K-12, but in K-12 Google Classroom and Schoology are the other big players. We believe that this is the first data set showing just how widely Google Classroom has been adopted. ((Disclosure: Instructure, Schoology, Blackboard, and D2L are subscribers to our LMS Market Analysis service; Instructure and Blackboard also are sponsors for an upcoming event we are organizing.))

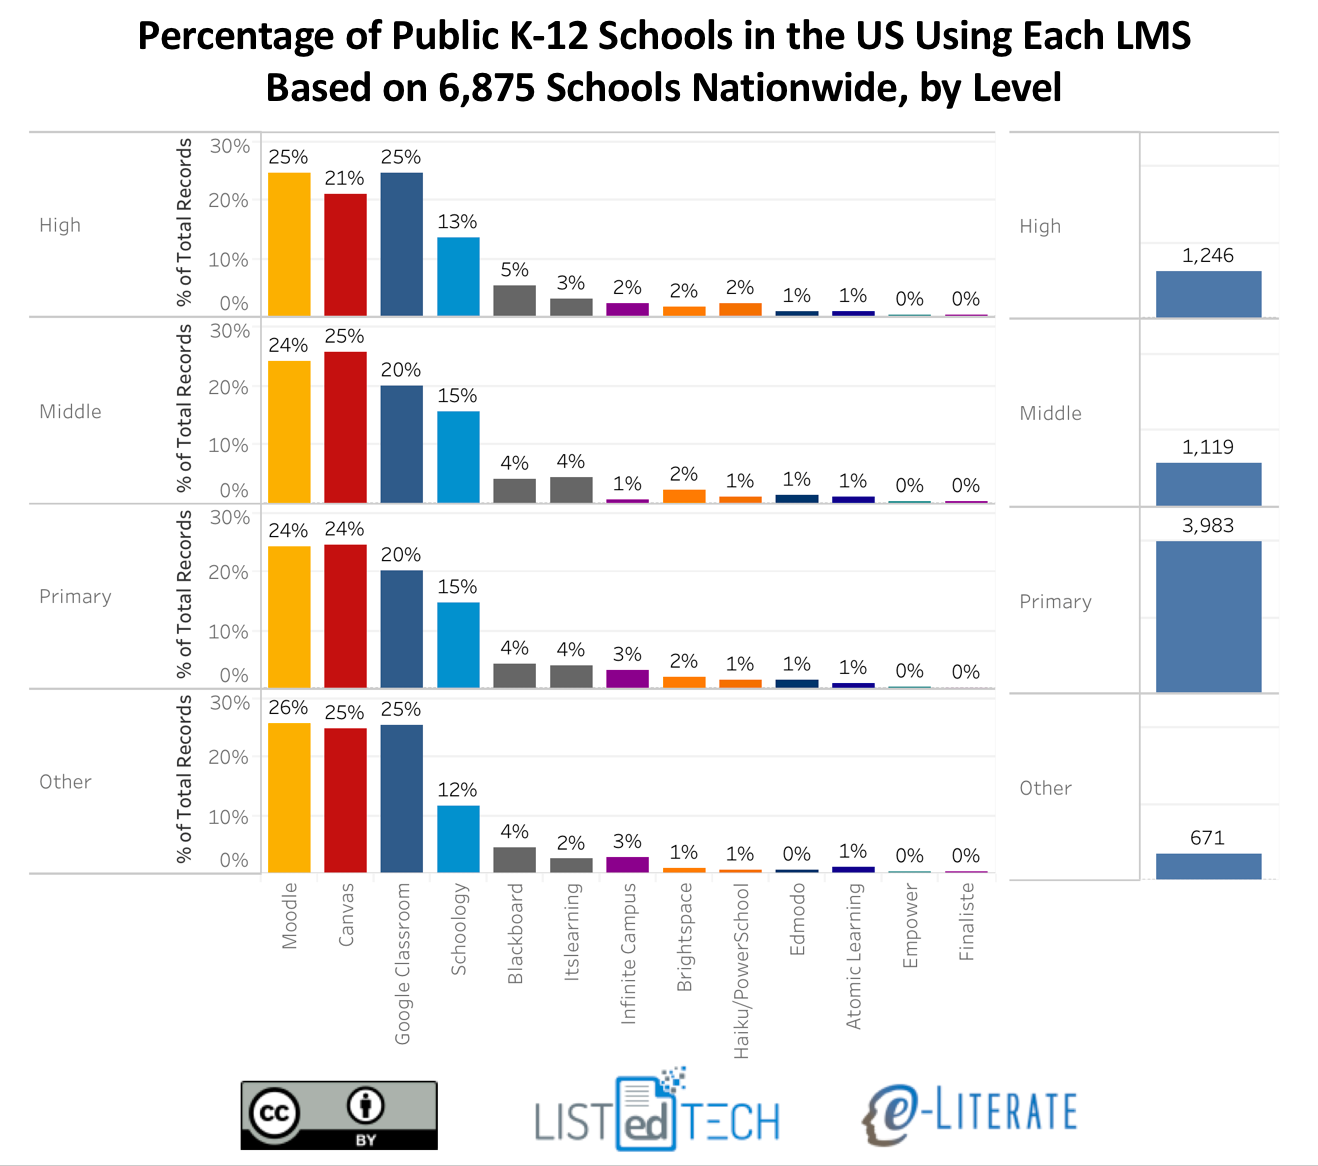
    The general distribution is somewhat consistent across school levels – primary, middle, high school, and others – with some interesting smaller variations. The following view also gives a sense of our relative data coverage by level. In this case we are using all our data across the 6,875 schools. Note that totals are higher than this number due to multiple systems being available at some schools.

    LMS Market Share for US K-12, By Level

    We hope this new data provides a broader view of the academic LMS market. We’d love to hear your feedback and questions.

  • Why Moodle Supporters Should be Concerned

    Why Moodle Supporters Should be Concerned

    In Phil’s last post, in which he explained our data gathering methods for our LMS analysis work, he started with a quote from Moodle leader Martin Dougiamas that suggested our numbers were primarily US-based. Because it captured a common misconception about our data (and was based on a fair question), it was a good launching point for the post. But there was more to Martin’s comments on the subject, and we’ve heard various objections from some Moodle advocates about why our numbers are either inaccurate or irrelevant. ((The Moodle community is no more monolithic than any other; we have of course heard a wide range of opinions from Moodle advocates about the state of the union.))

    I’d like to review those arguments here. While Moodle is still by far the most widely adopted LMS in higher education globally and is no danger of disappearing any time soon, I believe that our data should give the Moodle community cause for considerable concern about their long-term future and should trigger some soul searching about how the community can ensure it continues to have the development resources necessary to continue to be relevant in the long term.

    The Data

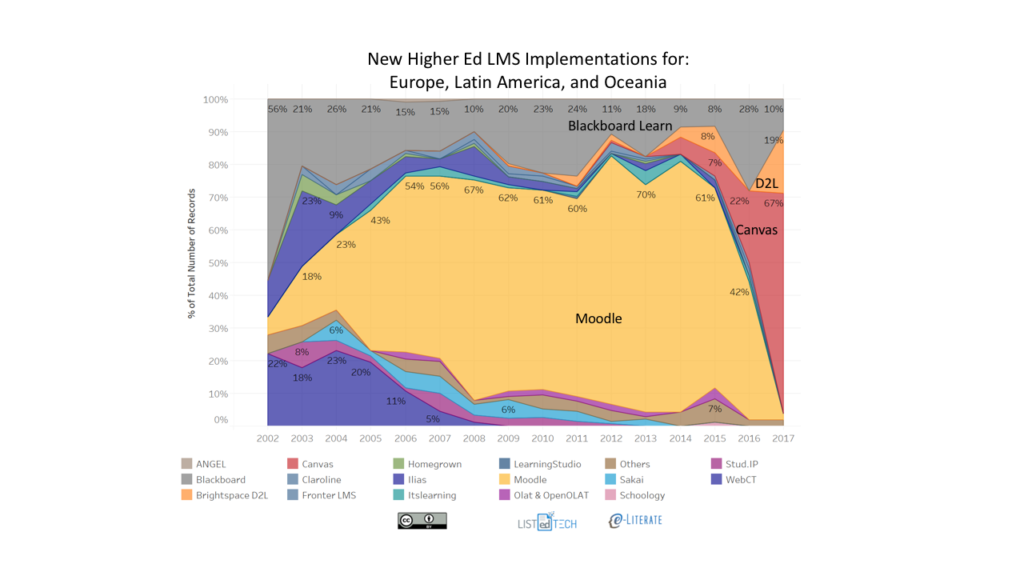
    Let’s start by reminding ourselves of the data in question. It really boils down to this one chart:

    Notice the scope of the chart: It does not include the US and Canada. This is data for Europe, Latin America, and Oceania. So this chart is not biased in any way by US-centric trends.

    There are two important caveats here. First, as Phil states in his post, our coverage of these areas of the world are not as complete as they are in the US and Canada, so trends we see in our data for these parts of the world should be considered directional and somewhat provisional rather than pinpoint accurate. That said, we only publish data for regions where we have enough coverage to be confident that our sample is representative. We don’t yet cover China or Africa for this reason. We believe the chart above is directionally correct, but there is a margin of error because we have a sample rather than a close-to-100% complete data set.

    The second caveat is that the chart shows new adoptions. When we look at installed base, Moodle still looks formidable:

    So the issue we’re talking about is not that Moodle is disappearing but rather that it is losing ground during new adoption cycles.

    The three most common arguments we hear from Moodle advocates are the following:

    1. The e-Literate numbers aren’t global or aren’t accurate.
    2. e-Literate is using the wrong adoption measure.
    3. e-Literate’s numbers are irrelevant, because an open source project doesn’t need to worry about growth in the same way that a profit-motivated company does.

    Phil’s earlier post addressed the first objection by describing the data we have, how we get it and validate it, and how we try to be transparent about its limitations.

    I’d like to address the other two objections in this post.

    The Wrong Measure?

    We measure higher education institutional adoptions. That means there are Moodle adoptions that we don’t measure or don’t report. We don’t have counts K12 or corporate adoption at all; Moodle has significant uptake in both of these areas. While we have data on secondary higher education adoptions (e.g., adoption by a school of education at a university that uses a different LMS for the rest of the institution), we don’t report these numbers. Nor do we report adoption by individual faculty. All of these are meaningful numbers and we do not dismiss them.

    But institutional higher education adoption is a particularly meaningful measure for Moodle’s long-term health. While Moodle is open source, Martin Dougiamas’ company Moodle Pty—more widely known within the Moodle community as Moodle HQ—does most of the development of the core Moodle code and maintains tight control over which code submitted by third parties gets accepted into the code base. This is what is sometimes known as the “benevolent dictator” model of open source, which was popularized by Linus Torvalds, the creator and development leader of the Linux kernel.

    Under the current way of doing things, both the direction of Moodle development and velocity at which occurs are largely controlled by Moodle Pty. However much input the company may take from the community, the ultimate decisions and, perhaps more importantly for this post, the work of implementing those decisions, fall under the purview of Moodle Pty, a for-profit company that must generate revenue to pay the employees who actually write that code. Moodle Pty’s revenues mostly come from Moodle Partners, which are companies that are licensed to use the Moodle trademark by Moodle Pty in return for a percentage of their Moodle-related gross revenues.

    If Moodle Partners lose paying customers, then Moodle Pty loses revenue. If Moodle Pty loses enough revenue, then at some point it would have to start laying off developers. If Moodle Pty starts laying off developers, then the pace of Moodle development will slow. If the pace of Moodle development slows, then the loss of Moodle-adopting schools may accelerate, creating a vicious cycle.

    While we don’t know the percentage of Moodle’s revenues that come from higher education (as opposed to K12 and corporate), we know it’s significant. The anecdotes I have heard from various sources suggest that it may well be the substantial majority of the total financial resources that fund the development of Moodle’s core platform. So, while other kinds of adoption may be great and may bring in new participants to the Moodle community, Moodle advocates should be concerned with higher education institutional adoption if they are concerned with having development resources for the Moodle platform in the long term.

    Irrelevant?

    Another argument we hear sometimes is that the Moodle community doesn’t need to care about these numbers because, as an open source project, it will fulfill its purpose if meets the needs of its adopters and doesn’t need growth for its own sake the way that a for-profit project does. Martin himself made this argument in the comments referenced above:

    Martin ended his comment on this topic by saying what makes our project different is that we are not driven by numbers. We are driven by the needs of our users and that he would be happy if there were only 100 universities using Moodle if we are following that approach.

    From an abstract philosophical perspective, this is undeniably true (or was at the time the comment was made, at any rate). An open source project does not need to satisfy investors or meet revenue targets. It just needs to attract enough developer resources to keep the code base viable and up-to-date. But there are a few serious problems with this argument in Moodle’s specific case.

    First, Moodle’s growth model was spectacularly successful in its first decade in part because it was a Robin Hood model. In richer countries, adopters could afford to pay hosting or management companies to run their mission-critical instances. A portion of this money would flow back to Moodle Pty and get invested in the salaries of developers who would improve Moodle and continue to release it under an open source license. In poorer countries, they could adopt Moodle themselves without paying a hosting or support vendor. Moodle has always been unusually easy to install and run on even modest hardware relative to its competition, so poorer schools could still manage to adopt it with the resources that they had. But if Moodle is losing ground in the richer countries (or, more accurately, the countries that can invest and are investing more dollars in educational technology), then it is also losing its development revenue base.

    (I would add that the message, “Hey, it’s no big deal to us if we lose some adopters” is not a great one for members of the community who feel like their needs are not being met.)

    But the problem is potentially worse for Moodle, because we’re beginning to see a pattern take hold in international markets as they reach a certain level of maturity, and it’s not good a good one for Moodle. In the US and Canada, the big hurdle to LMS migration was the move from self-hosted to cloud. Once institutions became comfortable with cloud hosting, the market changed rapidly, with Canvas in particular taking a strong lead and Moodle (among others) losing ground.

    We are seeing early evidence that the same pattern may be beginning to take hold in Europe now. While the data we have are not definitive yet, they are suggestive and are supported by the qualitative research we are doing. And this pattern could easily take hold elsewhere as well. For example, my colleague O’Neal Spicer and I recently had the good fortune to visit Brazil, where Moodle is still very much dominant. But consider this: Seventy-five percent of Brazil’s college students go to for-profit universities, and those businesses are enormous and growing. For example, Kroton, the country’s largest university, has about 2 million students. Given that these organizations are companies with investors and profit motives, there is no particular reason to believe that they are ideologically inclined toward open source. The fact that both Instructure and D2L have offices in São Paolo suggest that they believe they have an opportunity to win over the Brazilian market now that it has gotten big enough to be profitable for them. In other words, Moodle’s Robin Hood model is under threat because whenever a market becomes rich enough to generate significant revenue for Moodle Pty, it also becomes rich enough for universities to consider switching to cloud hosting by one of Moodle’s commercial competitors.

    Adding to this pressure is the fact that Moodle Pty just took $6 million in investment money. This is not a grant; it is an investment. However well-aligned and patient those investors may be, they still will eventually need to see a return on their $6 million. When investors do not see the return they expected, they eventually begin to put pressure on the company management to take steps that improve the finances. I don’t know enough about the terms of this particular investment relationship to know what kind of leverage Leclercq has to push for changes in Moodle Pty if they are not happy with its performance, but the fact of the matter is that Moodle Pty now has financial performance targets to meet.

    Put all this together, and it strongly suggests that members of the Moodle community should be concerned about the adoption trends we are seeing, for both mission and strategic reasons.

    Moodle’s Role

    I want to return to the example of Brazil for a moment to show why this matters not just to Moodle advocates but to anyone who cares about education. According to the 2016 Analytic Report of Distance Learning in Brazil published by Brazil’s premiere distance learning association, the Associação Brasileira de Educação a Distãncia (ABED), about three-quarters of a million Brazilians took online or blended courses in 2016. According to our analysis, Moodle has over 80% of Brazil’s higher education institutional LMS market share. It’s entirely possible that we would not have seen that kind of growth in access to education if Moodle had not existed. Yes, one or more other open source LMSs might have been adopted, but the existence of that Robin Hood sustainability engine built by Martin Dougiamas ensured that significant developer resources went to developing a high-quality globally adoptable LMS that could be deployed by even poor institutions. It has been an engine of educational growth.

    If the data patterns we are observing hold, then that engine may be under long-term threat. While Moodle has far too broad an installed base to disappear any time soon and just received an infusion of investor money, the fact is that its sustainability model is now in question. That’s bad for everyone. It’s bad for Moodle advocates, it’s bad for people who care about improving educational access for the developing world and economically challenged people in general, and it’s bad for those educational technology companies that have depended on international maturation of markets that open up new commercial opportunities for them.

    For everyone’s sake, I hope that the Moodle community—and particularly its leadership—owns up to this potential challenge to its sustainability model and confronts it head-on.