e-Literate

Present is Prologue

Category: Ed Tech

The “Ed Tech” category includes posts about educational technology products themselves, including LMSs and other learning platforms, adaptive learning and other digital curricular materials products, learning analytics, and educational apps of all types. It also includes technical aspects of ed tech products, especially interoperability.

  • Announcing a #ResilienceNetwork Procurement Solution for COVID

    One of the massive challenges facing colleges as they prepare for the return to school during COVID is procuring everything they need, from equipment to keep people safe, to educational software and services to keep students learning online. That’s why I’m delighted to announce that E&I Cooperative Services is joining the Empirical Educator Project as a sponsor and contributing their COVID-19 Recovery Solutions Navigator as a resilience network project.

    You may not have heard of E&I, but if you work at a U.S. college or university, chances are very good that your institution has a relationship with the cooperative. E&I is the only member-owned, non-profit purchasing cooperative solely focused on serving the needs of education. They use the aggregate purchasing power of more than 5,000 member institutions to develop competitively solicited contracts that comply with generally accepted procurement standards, including those of state systems.  E&I has been a member-owned organization since its founding in 1934, and membership is free.

    We all know what a bottleneck the procurement process can be. It’s extra time (and costs) that a lot of colleges don’t have right now. E&I has been working with its members to map out their needs, create a list of solutions, and offer competitively-solicited or adoptable contracts as quickly as the process will allow. The E&I team has been working hard to get ahead of this part of the problem for you, both by anticipating solutions you may need and negotiating contract terms so you don’t have to. The COVID-19 Recovery Solutions Navigator is itself a contribution to the resilience network, since it provides a map of potential needs that will help accelerate institutions’ internal planning conversations. The contract negotiation that E&I handles is priceless.

    As part of their participation in EEP, E&I has engaged e-Literate to advise them on potential areas of need in teaching and learning and, more broadly, student success. Because procurement can only proceed so quickly and still pass muster with compliance requirements, there will likely be several waves of these RFP solicitations. The first, which focuses on online learning program consulting and faculty training, can be found here.

    This is the heart of it, though:

    E&I’s intent of this Request for Proposal is to solicit qualified, experienced, financially sound, and responsible firms to provide Online Learning Program Consulting and Faculty Training as required by members. The Respondent(s) must have the expertise and experience with providing faculty training for online course development & pedagogical design. This may include the building of new or expansion of online programs for higher education institutions and K-12 school districts. Additionally, E&I is soliciting qualified, experienced, financially sound, and responsible firms to provide consulting for institutional and/or organizational change management for online learning programs.

    Proposals are due by 1:00 PM ET on Thursday July 23, 2020, so if you are a vendor that wants to be considered in this process (or work with a vendor that you think should submit a proposal), now is the time to apply.

    More support for COVID and empirical education is coming

    As I mentioned earlier, this is the first teaching and learning-related solicitation. E&I will be conducting at least one more teaching and learning-related COVID RFPs in areas that are yet to be determined. Suggestions are welcomed.

    E&I has also signed an MOU with EEP to collaborate on the creation and execution of procurement processes that incorporate research and evidence of impact directly into the procurement process. While we are focused on the urgent needs of the COVID crisis for now, we also intend to make it easier for institutions to evaluate and procure educational products and services through a process that takes evidence of educational impact into account.

    Register for the e-Literate LIVE! event on Wednesday, August 26th from 1:30 PM to 3:00 PM ET with E&I leadership to talk with them about their #resiliencenetwork EEP contribution and provide input for the next steps in the project.

  • Reminder: Webinar Thursday on Historic #PivotOnline Event for Faculty (Now with Correct Link!)

    Hi gang. I’m writing a reminder to you that I’ll be hosting a webinar tomorrow about next week’s free REMOTE Summit next Monday and Tuesday. (Embarrassingly, this is partly necessary because my last post included the wrong for the webinar registration page. The webinar is Thursday, July 9th from 1:30 PM to 3 PM ET. Register HERE. (The summit itself is next Monday and Tuesday.)

    This thing is shaping up to be an historic #ResilienceNetwork-scale event. There are somewhere in the neighborhood of 80 talks and 10K+ attendees registered the last time I checked. Please, please, please, get this information out to your networks of faculty. There’s room for ~90K more attendees. Let’s fill it up.

    The e-Literate LIVE webinar tomorrow will feature David Levin, ASU’s Entrepreneur in Residence who conceived of and organized the event. We’ll be giving you a preview of the event itself and, importantly, giving you a chance to have input on what steps might be taken to build on the event afterward.

    Again, the webinar is tomorrow, i.e, Thursday, July 9th from 1:30 PM to 3 PM ET. Register HERE.

    In case you actually want to register.
  • Having the Hard Talk

    Note from the editor: This is a guest post from Susan Baldridge, one of the authors of the book The College Stress Test: Tracking Institutional Futures across a Crowded Market.

    A couple of months ago I wrote a blog post about the need for conversations about change on college and university campuses and some of the challenges to that kind of engagement.  At the end of that post, I promised a second installment in which I offered some thoughts on how one might begin such a conversation.  And then the world changed – you know, COVID.  Those of you serving institutions of higher education as administrators, faculty, and staff have been hit with a tsunami of change, and nearly everything about your work has been upended.  At first, it might seem that the kind of conversations I was calling for is a luxury that can’t be afforded in this moment of crisis.  But I’m going to make the case that it’s more urgent than ever that communities find ways to have these conversations, especially under these circumstances, and I want to offer some suggestions for how one might try to do this.

    As to the “why,” we know that many institutions are being forced to make fundamental changes to the way they do business in the current circumstances.  Although many are hoping against hope for a return to “normal,” that seems pretty unlikely at this point.  All commitments are being examined, all assumptions being questioned, and every dollar scrutinized.  We knew that change was needed, but the urgency has just been turned up to 11.  We had a very brief window in which most members of academic communities understood that decisions were being made very quickly and with little guidance or evidence to support one decision over another.  But already, barely 2 months since these changes have begun to be implemented, calls are coming from campus groups, from the AAUP, from unions, for transparency, consultation, and communication about how we will operate going forward.  The fact that we are all working in physical isolation, connecting only virtually, increases the fear and sense that decisions are being made “behind closed doors” and that normal processes for engagement, consultation, and shared governance are being thrown out the window.  When those concerns take over, people find it very hard to devote their energies on behalf of the institution – which ironically, we need right now more than ever.

    So that’s the “why.”  But in these strange circumstances, how is it possible to have the kinds of conversations and engagements that are needed?  Well, the short answer is start with what you have.  I’ll offer some concrete suggestions here, but welcome the ideas and thoughts of others about practices for meaningful consultation and engagement.

    Let me start with the obvious: Technology is going to be the new context.  Everyone has gotten a crash course in Zooming with students and colleagues, and you are going to have to think about how to use those tools and skills both in the short term – and perhaps in the longer term.  Zoom and other virtual meeting tools are being used not only for small groups, but sometimes for very large ones, convening dozens and even hundreds of individuals for a “live” experience. What lessons are we learning about how and when these work well?  Take advantage of the recent lived experiences of your community members and ask them – what are the most effective ways that videoconferencing is being used for learning?  For meetings?  What are the practices that feel most inclusive and effective?  The same questions can and should be asked of asynchronous teaching and learning tools and practices, of course.

    But if these tools are the medium, we also need to be intentional about the content of the work that needs to get done.  If change is inevitable, that means there are many decisions to be made, and we need to be mindful of governance as much as possible.  OK, committees and faculty meetings need to happen differently, but that doesn’t mean we should forego them.  Ask yourself the question:  If we were going to make these changes a year ago when we were all together on campus, who would have been involved?  What groups would have been consulted?  What communications would have gone out?  As much as possible, continue to work within these structures, and when you can’t, say so and explain why.  If possible, work with groups and constituencies already in place.  These are not ideal circumstances for creating new committees, charging a new Task Force, or bringing people together for the first time to do difficult work.  If it isn’t obvious who should be involved in making these sometimes unprecedented decisions, review your Handbook and find the groups whose charges most naturally overlap with the situation at hand.

    Once the parties have been engaged, everyone involved in making these hard decisions is going to have to face the reality that…well, they are hard.  The decisions you and others are making will most likely involve uncharted territory, and chances are good that there isn’t an obvious “right” choice about how to proceed.  So how do you make these kinds of decisions?  I refer you to a wonderful TED Talk by philosopher Ruth Chang, in which she points out that hard choices are sometimes hard not because there is a right answer that you haven’t yet figured out, and you must simply wait for the right piece of information or evidence to solve the puzzle.  Rather, the choices may be difficult because there are two or more roughly equal choices available to pursue — equal in the sense that they all may contain some positives and some negatives, and even some uncertainty.  She suggests, then, that the key is to ask not “What is the right answer?” but “What kind of person do I want to be?” and let this be your guide in choosing.  To quote from her talk, “It is here, in the space of hard choices, that we have the power to create reasons for ourselves to become the distinctive people that we are.”  I want to suggest that we extend her point to apply to institutions as well.  None of us has a crystal ball about the future, and if we do, it’s cloudier now than ever.  In that context, let’s try to let our values, commitments, and vision be our guide. This means, of course, articulating what those values and commitments are.  Many campuses already have existing frameworks and principles that spell these out.  If they don’t exist, then at least be able to reference the values that are informing the decisions being made.

    Of course, not everyone can or will be engaged with making or even providing input into those decisions.  It’s worth being honest and clear about that.  But since the stakes of some of these deliberations will be very high, it is all the more important to be especially diligent about clear and frequent communication.  Most of us loathe email, but let’s face it, it’s one of the primary modes of communication available to us right now.  So use it, and any other communication tool available.  Whatever the medium, regular updates, even when there isn’t much to report are better than no updates.  Remember that the question foremost in people’s minds is “What about me?” followed closely by “Who’s talking with whom about what?” and  “When will they decide?”  Answer any questions you can, and when you can’t, say so.  The more that folks have a sense of what to expect, the less likely they are to have to manufacture narratives about what is really happening, and the less time will need to be devoted to addressing erroneous conspiracy theories.

    Finally—and I know this one may feel most challenging of all—try to create space for creativity.   This may sound like a luxury: “Who has time for creativity when we are desperately trying to put out fires??”  But a crisis, especially one as unprecedented as this one, is precisely when creative solutions are most needed.  One leader with whom I’ve spoken has taken a brief time in her regular (virtual) meetings with colleagues for explicitly creative brainstorming – she calls it “idea factory” time.  She reports that not only have some of these ideas been enormously helpful, but that colleagues felt a bit more optimistic and energized for having tried to focus, even momentarily, on positive and creative solutions, rather than dwelling only on challenges and worst-case scenarios.  And sometimes the most innovative ideas come from those who are closest to the work – so don’t be afraid to be broadly inclusive in seeking creative solutions.

    None of these suggestions are specific to this pandemic.  But the current circumstances have increased the urgency around implementing them.   And if you’ll indulge my tendency toward optimism, I’ll note that while many have complained that higher education is notoriously slow to change, we have all just demonstrated that when we had to, we could fundamentally change nearly every aspect of how we do business in a few short weeks.  It wasn’t easy, and time will tell how effective these efforts have been thus far.  But we have demonstrated that significant change, even rapid change, is possible.  Let’s be intentional about the lessons we take from the changes thus far, and use them to inform the future we need to create.

    Post-script:  If you work in higher education, in case no one has said it to you:  Thank you for all the hard work you are doing under extraordinary circumstances.  Thank you for caring for your students, your communities, and your institutions in such trying times.  We need an educated populace now more than ever, and your efforts matter.

  • COVID-19: What comes next

    One of the weird things about humans is that we most want to be told what will happen next at the exact moment when the future is uncertain because the outcome depends upon decisions we have yet to make. Most of the time, the future is predictable partly because there isn’t a lot we can do to change it. This is not one of those times.

    Like so many aspects of this civilizational crisis, our choices—as individuals, institutions, and societies—will shape the future. We can decide to let our institutions fall apart. We can try to hold them together with chewing gum and string. We can let others decide for us, which risks letting the most powerful and self-interested actors determine our future. Or we can choose to mindfully rebuild. Each of us gets some say in what happens next (though, tragically, some more than others).

    I don’t know how all of this will play out, and pretending otherwise would be harmful. We all need to dwell in the uncertainty that enables us to make choices, and we need to make our choices together as a sector. For this reason, I’m reluctant to advocate too forcefully for my views of what is likely happen, or even what should happen. There may be time for that later. But at this moment, as our educational first responders are struggling to deal with the first wave of the crisis while beginning to brace themselves for the second wave, I think it important for those of us who are not in that role to exercise some situational awareness. Now is not a great time to pontificate or prognosticate—at least not without extra doses of humility and empathy.

    That said, we are far enough into the first wave that it is time to start thinking about the future. For some of us, that will mean learning to walk, chew gum, and juggle chain saws at the same time. So with that in mind, I’m going to offer up some of the change vectors I’ve been thinking about lately as conversation starters

    Everyone will be cash-strapped

    Students and their parents have lost income. Adjunct faculty, upon whom so many colleges and universities rely, are also highly vulnerable to a social safety net with many holes in it. Universities face the possibility of refunding student tuition and fees, and may well experience a major shift in enrollments next year as students reconsider their options. States face massive budget deficits.

    While all of this is obvious, the implications are not. We don’t know yet how our federal governments will respond. Or the states. Or the institutions. Or the students. Or anyone, really.

    When I think about these sorts of multi-level problems, I try to find the highest organizational level at which I think I can have a significant influence. For climate change, I am more focused on state and local actions than at Federal or global ones because I feel more able to influence my state and local governments. For COVID-19 and higher education, it may be at the institutional level. University communities have never been terribly good at understanding the mechanics of their institutional sustainability models. How much money comes from public funding vs. grants vs. tuition vs. alumni donations? Which programs cross-subsidize which others? What have been the drivers of cost increases? How are these dynamics shifting? Now is the time to get smarter about this so that we can make smarter decisions going forward. While this sort of thinking feels uncomfortably close to reducing education to a consumer commodity, there will be no higher education if universities can’t get their budgets to balance. This is a particularly urgent conversation to be having.

    Online isn’t going away any time soon

    While I find some of the cheerleading for #pivotonline to be too soon and sometimes too opportunistic—particularly from folks who are not working on the front lines—we shouldn’t expect the need for online education to magically disappear by September, or for the world to eventually revert to the way it used to be. What holds for all other aspects of the post-coronavirus world also holds for education. Social distancing is a reality that we will be living with for a long time. Long enough that new patterns of life and work will set in. The implications are both deep and wide.

    First, this change will impact the sustainability models I referenced above. Students are already asking for their housing costs to be refunded for the semester. Those who have been paying attention to the trends in online pricing are aware of a wide range of price-relevant experiments in various stages of progress in the market, from xMOOCs to stackable credentials to affordable degrees at scale to premium-priced OPM-designed master’s degrees. There is no one right answer here. Colleges and universities will find different combinations that fit their missions, sustainability needs, and organizational capabilities.

    Second, we will need to pay extra attention to equity. This is an area that was already beginning to get some much-needed focus, but the current crisis will bring the problem into sharper relief. For example, universal access to affordable broadband is more obviously an equity issue when it is inextricably tied to access to education. More broadly, we know, based on a rich body of research, that underserved students underperform relative to their peers online. (This is likely even more true in hastily and poorly executed remote education courses like the ones that are being thrown up out of necessity this term.) We need to redouble efforts to understand their needs and fill gaps in our support for them.

    One potential bright spot in the larger crisis is the opportunity to introduce more faculty to both new ways of thinking about their teaching practices and closer relationships with expert support staff. We know that both of these things tend to happen when faculty are introduced to online teaching on a more orderly and voluntary basis. Unlike with face-to-face instruction, many instructors don’t feel like they should be expected to somehow know how to be master teachers online and therefore are less reluctant to see themselves as novices and students. On the other hand, if the transition goes disastrously poorly at a moment when faculty (like all of us) are feeling vulnerable in other parts of their lives, the trend could turn in a different direction. This is a moment when the deep structure of academic culture will get rewired, one way or another. We need to be mindful about how we support and enable the support staff so that they have the best chance of steering the change in a productive direction.

    The curricular materials ecosystem is especially fragile

    This one may be less obvious to some. The curricular materials ecosystem was already in danger. Almost none of the textbook publishers were financially healthy even before the virus hit. OER is doing fine, but it is not on a growth path that is remotely fast enough to fill the giant hole in course coverage that would be left should the publishers start to implode. And while it may be tempting for some to say “good riddance” to the traditional providers, try telling frazzled faculty who are in the midst of a sudden, unplanned, and unwelcome online transition that they will also have to cobble together a replacement for their textbook in the process.

    At the same time, if we really are facing a new reality of a large-scale and long-term switch to online education, then we need to find the means and measures for closing online achievement gaps for transitioning students in general and underserved populations in particular. To do this, we will need to embrace digital affordances. The sector is in no way prepared for this. We don’t have the privacy policies, procurement practices, or widespread literacy among faculty regarding how to make effective use of digital affordances. Furthermore, if the publishers collapse, where will these digital products come from? The majority of sophisticated courseware authoring platforms have either died on the vine or been acquired by the publishers. There is very little in the way of sustainable open-source alternatives. Nor is there an alternative ecosystem in place to produce content for these platforms.

    As part of this larger shift, we need to engage in some big, out-of-the-box, but reality-grounded thinking about how we might reconfigure the entire curricular materials ecosystem to create more stable and beneficial sustainability models. I don’t have a lot to say about this yet but hope to have more to say about it soon.

    Working together more effectively

    Finally, folks who have been reading e-Literate regularly over the last few years know that my current professional obsession is about how ineffectively higher education collaborates as a sector, despite the deep reservoirs of goodwill and generosity among the people who work in it. I have written quite a bit about the Empirical Educator Project in general and the idea of a resilience network in particular. We need to work on improving our collaboration now more than ever.

    As Ben Franklin memorably put it, “We must, indeed, all hang together or, most assuredly, we shall all hang separately.”

    Truer words….

  • What’s Next for Instructure?

    So, Instructure CEO Dan Goldsmith is “stepping down.” Going to “spend more time with his family.” “Hiking the Appalachian Trail.” Choose your euphemism. He has been forced out. Don’t shed too many tears for him; he made about $12 million during his roughly 14-month tenure as CEO. That’s enough to pay maybe 25 decent software engineers for 5 years in the Salt Lake City area.

    The truth is that nobody would have paid much attention to how much Goldsmith was getting paid had he been doing a good job. But in the education market, people tend to pay attention to who is getting a big payout if they worry that their vendor is not putting the students first. I hope that is a lesson that Thoma Bravo is taking note of. (More on that in a bit.)

    That said, the Goldsmith era is now water under the bridge. The more important question is what happens at Instructure going forward and how it impacts the students and educators who depend on the company.

    Short-term

    The acquisition of Instructure by Thoma Bravo is not dead. If anything, it is considerably more likely now, for a variety of reasons, including but not limited to a higher bid by the private equity company. As usual, Phil has a terrific breakdown of the financial drama. The short version is that there is likely to be a bit more drama that will take a bit more time, but the acquisition looks close to a done deal at this point.

    In the meantime, there is no CEO. Instead, the company is being run by a team of its senior executives, some of whom are the veterans that I’ve been complaining have been stifled. Within hours of the announcements of Dan’s departure, I began seeing private signs of aggressively renewed outreach from this team. The bunker mentality is gone. We’ll see how well this team coordinates that outreach, but the horse is out of the barn on this one. I think it will be hard for the next CEO to go back to a classic corporate command-and-control customer interaction style. That is one good outcome from the interregnum (though it is possible to go too far in the other direction if they don’t all pull together).

    The bigger question for customers, assuming that the deal does go through, is what happens afterward.

    Medium-term

    My position has always been neutral-positive on Instructure being acquired by a private equity company in general and neutral on being acquired by Thoma Bravo in particular. Instructure needs some time to move past its current growth plateau. There is a reasonable argument to be made that they could focus on doing that with fewer distractions that could harm their core work for customers if they were under private ownership rather than under the quarter-by-quarter performance pressures of the public stock market. Instructure’s acquisition could be good or bad for education, depending on two major factors.

    The first factor is Thoma Bravo’s plan. I am quite confident that they already have one. And as Phil wrote in the aforementioned post, it is likely an ambitious one:

    One other note – with these aggressive moves, I have to believe that Thoma Bravo has much bigger plans than simply buying a few more Portfoliums while divesting Bridge. Bravo is sitting on a pile of cash ($12+ billion in their latest round), and there are likely bigger plans that depend upon this Instructure acquisition.

    The post by that other guy

    The danger is that the typical private equity merger and acquisition playbooks have a decidedly mixed record in EdTech. At best. Education is a weird market. Combinations that look good based on the spreadsheets are often terrible ideas IRL. I can think of one or two possible big combinations that might work—Coursera comes to mind—but by and large, the impulse to combine two EdTech giants more frequently results in the destruction of value than in the creation of it.

    Private equity folks are rarely stupid. On the contrary, the ones that I’ve met have generally been incredibly smart. They simply lack education market domain knowledge. They apply their disciplinary skills in an area where those skills don’t translate straightforwardly. That can work out if they have a partner in the form of an excellent CEO who does understand education (or can learn it quickly) and is a strong advocate for customers. Dan Goldsmith wasn’t that person, which meant that private equity ownership under him was virtually guaranteed to be disastrous. Assuming the Thoma Bravo acquisition does go through, then the CEO that Thoma Bravo brings in to replace him will be critical.

    They almost certainly have somebody already lined up. Private equity companies tend to keep stables of CEOs that they rotate from company to company. That is probably just fine in the short term. While I have a lot of respect for Instructure’s management team, managing a company of that size through a committee will only work for so long. So bringing in a caretaker CEO quickly is a good idea. But that person may or may not be a good long-term solution. I would argue, for example, that somebody who comes from running an enterprise software company, like Goldsmith did, is not likely to be a good long-term fit. The market dynamics are very different, which is one reason why Goldsmith was completely blindsided and seemed slow to learn.

    There are major opportunities in EdTech. The education sector is entering a period of massive and uncharacteristically rapid evolution. That represents opportunities for a company that can identify new, unmet needs, engage in innovative, user-informed product development, and keep good relations with a particularly demanding customer base. Leadership matters in this kind of situation.

    I see two possible candidate profiles. The first is somebody from EdTech. There is now a generation of executives who have grown up in the space, seen all the many mistakes that have been made, know the customers, and have an eye for the market shifts as they happen. The ideal candidate in this mold is one who is old enough to be seasoned but young enough or unorthodox enough not to be stuck in the first-generation mindset from the established product categories like LMS or textbook publishers (which is where they will likely have earned their stripes). The second possibility is somebody more like Josh Coates, by which I mean a strong product-oriented CEO from the consumer software space who knows how to listen to—and speak to—customers. This person would have more of a learning curve, but since Instructure has a seasoned management team, it could work. But it would take more time before such a person could provide good guidance on acquisitions.

    Those awkward teenage years

    In the summer of 2018, I wrote that Instructure was entering its awkward teenage years. We just survived eighth grade. After a year of monosyllabic responses and long periods in the bedroom with the door closed, the pale young thing has emerged into the sunshine.

    But now comes high school. There will be new friends and new temptations. There will be strange ideas of what it means to be cool and how to get to the top of the ladder. Instructure didn’t become popular by being the cool kid that everyone had to be with. They became popular by being the kid that was fun to be with. That was good at making friends. That listened to you, cared about your problems, and laughed at your jokes.

    It’s that kind of popularity that makes the company valuable and that will enable the right leadership team to build value going forward. Whatever clever plans Thoma Bravo may have, they need a CEO who can provide them with ground truth, push back when necessary based on an education-informed perspective, and keep faith with the customers.

  • Instructure’s Better Possible Future

    Having reluctantly weighed in on Instructure’s proposed acquisition by Thoma Bravo, I would like to turn back toward positive rather than negative possible futures by describing a different potential vector for the company. Despite the criticisms of my previous post, I do not believe that Instructure is in a deep hole, inevitably heading deeper, with no way out in the foreseeable future. If there are two takeaways from that post, they are these: First, it is easy for an EdTech company to have a sudden and dramatic reversal of fortunes and of customer perceptions, especially in the downward direction. Instructure is at an inflection point where the risk of such a turn is particularly high. (I warned about this over a year ago, after Instructurecon 2018.) Second, the seemingly obvious or proximal causes of a company’s success can be misleading. When we misunderstand causality in this way, it heightens the risk. Instructure has not been a well-understood company in general, and my concern is that the current board of directors and executive management may not have a good understanding of the causes of the company’s historic success. So that post wasn’t about what will happen. It was about what could happen.

    In this post, I want to explore the company’s actual current competitive strengths as the basis for the kind of growth in value generation that both customers and shareholders would like to see. In the process, I’m going to have to spend a little more time analyzing their missteps. But beating up on Instructure’s management is not my goal. Rather, I want to offer up a case study for how value can be created in EdTech in the 2020s. In the process, I am going to spend some time on the promise and perils of data-driven affordances.

    Reminder: D2L, one of Instructure’s major competitors, recently became the first foundational sponsor of e-Literate’s Empirical Educator Project (EEP). Given that big decisions are in the process of being made about Instructure’s future right now, I am obliged to call special attention to the appearance of a conflict of interest.

    Instructure’s remaining competitive strengths

    As I highlighted in my previous post, Instructure entered the market with competitive strengths that were difficult and time-consuming for their competitors to duplicate. One was that Canvas was built from the ground up to be cloud-native. From their customers’ perspective, that’s a critical ingredient to the product’s reliability. From their competitors’ perspective, it is a very hard technical task to retrofit a cloud architecture onto a mature product that was designed to run on individual customers’ own servers. Another competitive advantage was that Canvas was built from the beginning to delight end-users, whereas older platforms were at least partly built to delight the IT managers who had made purchasing decisions in the early years of LMS sales, and who often had different concerns than the end users. This too is very hard to retrofit onto an older application. Arguably, Blackboard’s biggest mistake with Ultra has been to set customer expectations too high regarding the pace of progress. The rearchitecture and redesign they have undertaken are genuinely, seriously hard.

    But given time and motivation, these challenges can be overcome. And sure enough, Instructure’s competitors have been steadily narrowing these gaps over the years. The race is now competitive in these areas where Instructure had the field to itself for a long time. Likewise, their competitors have improved their customer service and focus on improving the end-users’ interactions with the companies.

    So what’s left?

    First, while Instructure’s brand has taken a couple of hits lately, it’s still strong enough, and customer memory of their positive experiences with the company is long enough, that lost ground can be regained. There are some customers who have had bad experiences, or growing concerns. The CEO has said potentially alarming things in public and failed to correct his mistakes. Nevertheless, I get the sense that the customer base is still rooting for the company to find its footing again.

    Second, there’s the culture. Most of the front-line people and important mid-level to senior managers who grew up in Instructure’s culture of excellence are still there. They still have the same knowledge, skills, experience, and convictions. And they have a collective muscle memory of how to work together in ways that were successful for customers in the past. Until we start seeing either talent flight or layoffs that cut deeply into the wrong parts of the company, then the heart of the original company is still beating.

    As for the core platform, while it’s no longer dramatically differentiated, it’s still solid. All things considered, nobody enjoys migrating to a new LMS. Instructure is still on a glide path to at least maintain its market share in the US and grow abroad. They would have to actively screw that up for the situation to change. And while that is easier than it may seem, it would take a while.

    Finally, while the market has caught on to the value of Canvas being designed as a cloud-based application with a focus on end-users, there is one other novel decision the company made early on that is still underappreciated. Canvas was designed to be a platform, not an application. To grasp the difference, think about the difference between a Blackberry (if you are old enough to remember those) and an iPhone. The Blackberry was a good phone that had a great keyboard. So, in a world where texting and email were becoming at least as important as voice communications, adding text communication features to a phone was a good idea. Yes, there were a few “apps,” for Blackberry. But there weren’t many, and most of them were bad. The iPhone, in contrast, was built for apps. Instead of making the primary interface a great physical keyboard, Apple made it a pane of glass. The interface was anything that could be created for a touch screen. Including interfaces and applications that Apple hadn’t even dreamed of. The iPhone is a platform. It is infrastructure that is designed for other people to write applications that run on it and through it.

    Instructure made a series of principled decisions not to develop certain capabilities in Canvas. Instead, they built both the technical infrastructure in Canvas and the relationships with integration partners to have a very strong ecosystem of EdTech companies that have deep relationships with the company and deep integrations with the platform. Rather than building a great keyboard and email app, they built a metaphorical pane of glass and app store. They created a technology platform and ecosystem that attracted other people to extend Canvas with new capabilities.

    This too was a pioneering strategy. Before Instructure, the model for LMS partner relationships had been set by Blackboard in the Chasen/Small era. They recognized that the vast majority of digital education products would have to integrate with the LMS. So they decided to monetize that by charging every integration partner a (significant) fee. In those early days, there was some business justification for that strategy. After all, Blackboard had invested in developing integration APIs—Blackboard Building Blocks—and, since they were by far the largest player in the market, integration with their platform offered substantial business opportunities in the form of access to Blackboard’s customer base. This became a significant revenue source for Blackboard that its competitors envied and, to varying degrees, tried to emulate.

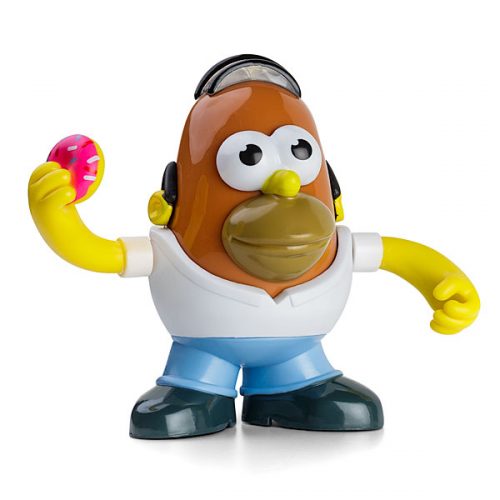
    But just as Instructure was lucky to come along right when the nature of the LMS customer was shifting, and right when cloud-based development had matured enough to make building a cloud-based LMS feasible, they were also lucky to come to market right when the IMS LTI interoperability standard was starting to take off and EdTech venture funding was really taking off. The LTI technical integration standard made charging a toll harder to justify, while the proliferation of EdTech startups transformed the locus of value for an LMS from a Swiss army knife into the hub of an ecosystem. Or, as my friend Kelvin Thompson from UCF has memorably characterized it, the potato part of Mr. Potato Head. On the one hand, there is no Mr. Potato Head without the potato. On the other, the potato itself is not where the personality (and personalization) come from. Instructure was less focused on charging partners and more interested in enticing them into adding character to Canvas in new and imaginative ways.

    Dalek Mr. Potato Head
    Homer Simpson Mr. Potato Head

    Their platform differentiator is subtle in the LMS world, but one that is critical to their current situation.

    In fact, it is essential to the first of two paths Instructure has for developing a product portfolio that I’m going to describe in the remainder of this post.

    Acquisitions

    There is now a whole galaxy of small EdTech companies that have developed new products or services that touch the LMS in one way or another. Instructure arguably is in the best position of any of the players in the market to identify good companies with products that already integrate well with Canvas and snatch them up. It’s not an exceptionally strong or durable advantage, but it’s one that they could be utilizing aggressively right now.

    Former Instructure CEO Josh Coates had a philosophy about acquisitions. Specifically, he was against them most of the time. I heard him give a talk about it once. His strategy was thoughtful and well-reasoned. And it would have been justified had the company succeeded in organically developing a portfolio of compelling offerings. But that didn’t happen. So, at least for the short term, the company is going to need to be more acquisitive in order to become financially healthy. But for that strategy to work, Instructure will need to rely on the knowledge of its employees who have worked on the platform aspects of Instructure’s business to identify truly good companies. What I mean by “truly good companies” is ones that have earned customer loyalty by solving some important problem well. Instructure needs to find compelling products, which is not easy in EdTech. The company leaders will also need to clearly and consistently articulate the reasons why they are proud to have acquired those products and how the acquisitions will better serve their Canvas customers.

    Instructure has made one high-profile acquisition under CEO Dan Goldsmith: Portfolium. Here’s the relevant bit from Instructure’s press release announcing the acquisition:

    Portfolium was created to help every person realize their full potential by connecting their learning with opportunity. The company helps institutions inspire, assess, and showcase student achievements via its powerful ePortfolio network, student-centered assessment, job matching capabilities, and academic and co-curricular pathways.

    “Working with Portfolium advances our mission since it enables us to help people move from the classroom to the workplace,” said Dan Goldsmith, CEO of Instructure. “Portfolium has been a great partner of ours. With their team, and by adding their student success capabilities built on the leading learner network, we will, together, provide more value to both current and new customers.”

    Instructure Enters Into Agreement to Acquire Student Success Network Portfolium

    Honestly, I don’t know what that means. Portfolium is an ePortfolio. That blurb mostly describes what an ePortfolio does, but adding some pleasant adjectives. Shorter version:

    Instructure is acquiring Portfolium, which is an ePortfolio company. Portfolium does things that ePortfolios do. We like it and think you will too.

    Honest press release

    The only bit in there that isn’t completely generic is the sentence fragment about job matching. But they don’t do anything with it.

    In fairness, most people who haven’t written a press release don’t appreciate how hard it is to write a meaningful one. I’m a pretty good writer, but I will readily admit to having struggled with that particular genre at times. That’s exactly why smart companies don’t rely on the press release to carry all the weight. They go out and repeat and elaborate on the message. Relentlessly.

    I haven’t heard any such message about Portfolium.

    Again, in fairness, I have not been following the LMS market as closely as I used to. But the thing is, if Instructure were really doing this right, it shouldn’t have been possible for me to miss this. I should have read it in the articles in outlets like EdSurge, Inside Higher Ed, and The Chronicle. In preparing to write this post, I did a search to see if I missed anything in the coverage by these or any other outlets.

    Nope.

    No quote from the CEO beyond what was in the press release. In fact, no quote that I could find from anyone that wasn’t already in the press release. There was an interview with the Portfolium founder in the San Diego Tribune. But it was clearly a local business story, in a local outlet—Portfolium was San Diego-based—and not anything aimed at Instructure’s customers. There’s nothing. Nada. Zip.

    When I ask Instructure customers about the deal, they tell me they haven’t heard anything either. And when I have run into Instructure employees at conferences—specifically, ones who are in a position to know about Portfolium—none of them have brought it up with me. In the old days, they would have. These are the same humans. There has been no invasion of the body snatchers. So it appears that the corporate communication strategy has changed. Where it used to be the case that you could get any random Instructure employee driving a golf cart at Instructurecon ((Golf carts driven by employees at Instructurecon is an actual thing. Or at least, it used to be.)) to talk about just about anything, it is now difficult to get even senior Instructure managers to talk about…well…just about anything.

    So there is at least one and possibly two serious but very fixable problems here. First, there is definitely a communication problem. Specifically, it would be good to have meaningful communication directly from the people within the company who understand why acquisitions are being made. Instructure employees have been some of the best brand ambassadors in the sector. Circumstantial evidence strongly suggests that they are no longer empowered to speak for the company. By muzzling them, Instructure is voluntarily throwing one of its remaining competitive strengths in the garbage can. And the only senior manager who has been allowed to speak on the record about the Goldsmith era’s first important, high-profile acquisition—to anybody, apparently—is the CEO. The one who has the most to prove about actually knowing the sector and caring about it. And his only statement that I can find amounts to a spoonful of bland pap in a press release.

    I don’t know much about sports, but I know what an unforced error is.

    While it would be easy to lay much of this at the feet of the marketing department, there has been a pattern of communication in the Goldsmith era that started immediately after he became CEO and has been consistent despite some churn in marketing department senior personnel. In fact, that churn may be an indicator in itself. The leader sets the tone.

    The second possible problem is harder to assess precisely because of the effects of the first one. I can’t tell if Portfolium is a good acquisition or not. A lot depends on what problems Instructure’s managers think it solves for customers and how they intend to make it more useful. Which they’re not really talking about. I can’t tell if this acquisition was a paint-by-numbers decision or if there is a real effort to increase value for the customers in a mindful, meaningful way. Instructure has people who know which partners are good potential acquisitions and why. They know their partners and customers really well. I can name a handful of them off the top of my head. In general, they are not being heard externally, which is unfortunate. If they are also not being heard internally—and again, I can’t tell one way or another—that would be a lot worse.

    I am confident that Instructure has the right ingredients and the right chefs to cook up an effective acquisition strategy. But the proof of the pudding is in the eating. If Instructure doesn’t both prioritize the acquisition of companies that will serve their customers well and communicate the reasoning and intentions behind the acquisitions, that could easily mean the difference between customers who are hungry for more and ones who are left with a bad taste in their mouths.

    Insights

    The other area for growth is in providing educators and students with better insights that support student success. It is impossible to overstate both how important and how fraught a topic this is.

    On the one hand, colleges and universities fail huge swathes of students all too often. There are students who want to go to college, get admitted to college, but haven’t had anybody to teach them how to succeed in college. Students who never make it to the first day of class. Or who get partway to a degree and drop out, due to lack of skills and support or tough personal circumstances. Students who need to come back to school and reskill while they are holding down full-time jobs and raising families.

    Many colleges and universities are not very good at serving some or all of these groups and routinely fail them. This used to be “only” a moral failing. Now it is an existential one, because the most obvious path to long-term sustainability for an increasing number of colleges and universities is to serve more students in their area more effectively for 20 or 40 years rather than for two or four. Institutions of higher education need to learn to perform better. And they need to learn it urgently. To do that, they need new insights. To get new insights, they need better information—that is, better data—and better ways of analyzing it.

    On the other hand, we live in an era when people have good reason to be concerned about the misuse of data in a seemingly ever-increasing variety of deeply troubling ways. Educators are responsible for their students. Many of them take this responsibility very seriously indeed. And particularly when it comes to the experimental use of data—even for the best of purposes—that responsibility is hard-wired into institutional processes in very particular ways.

    In academia, educational research falls into a larger bucket of “human subjects research.” That category also includes research on topics like how to perform open-heart surgery, how to deal with intractable clinical depression, and how people can be manipulated or fooled by social media. Think about the possible unintended consequences of poorly designed experiments in any of those three areas. We have canonical examples from bygone eras. The Milgram experiment. The Stanford Prison Experiment. Today, any academic research conducted in the United States that involves human subjects must submit its experimental design and protocols for experimental subjects’ informed consent to a rigorous peer review and approval process before the experiment can be undertaken. Educational research must be submitted to the same approval process by the same oversight board that would approve life-and-death surgery or psychological experiments.

    But unlike in medicine, an EdTech company that wants to conduct research using student data for product development purposes is required to do…nothing at all. They don’t even have to inform the students that they are being experimented on.

    In fact, EdTech companies conduct experiments on a weekly basis that would require a lengthy approval process in some universities. ((Different universities interpret the rules around such approvals differently, in part because a university that has a world-class medical school will likely understand their responsibilities differently than one with no medical school at all but a significant psychology research program, for example.)) Suppose, for example, that product developers want to test which design of a button is more likely to raise user awareness of a feature. They conduct what is known in the industry as an “A/B” test. They show some users one design, other users the other design, and track which design gets the most clicks. This is an absolutely routine software development practice. It is a foundational strategy that developers use to learn how to make their software more useful and usable.

    But let’s also suppose that the feature the button activates has a significant impact on improving student outcomes. Using the feature helps to improve learning. The developers, with the best of intentions, are trying to figure out which version of the button will get more students to use the feature that will help them. But in this experiment, the button that turns out to be worse may negatively impact the learning outcomes of students using that version of the software.

    This is exactly the kind of contingency that might trigger a requirement for an experimental design review process inside a university.

    Imagine that you’re an academic who feels responsible for your students and who lives in that kind of a culture surrounding anything that remotely looks like it could be human experimentation. Imagine that you read the following statement by the CEO of a company whose EdTech product you, personally, require your students to use extensively every single day:

    We’ve been working on the scaffolding for [DIG] for well over a year now. I mentioned in our remarks that we already have product validation towards out there in the market. We have instructors and students consuming output from some of the initial experiments with DIG. And we anticipate later this year obviously to make more announcements around specific products and offerings and how we bring them into the market. DIG ultimately is a platform first and foremost based upon machine learning and artificial intelligence. I believe that any multi tenant SaaS company born in the cloud has the opportunity once they hit a certain market share. And in fact, it may even be incumbent upon those organizations to partner with the industry and evolve that industry with new insights and predictive modeling using AI and ML. That’s what DIG is at its heart.

    We already have analytical capabilities in our Canvas platform. I want to be really clear and delineate the difference between an analytics and reporting capability, and a machine learning and AI platform. [snip]

    We have the most comprehensive database on the educational experience in the globe. So given that information that we have, no one else has those data assets at their fingertips to be able to develop those algorithms and predictive models.

    Instructure CEO Dan Goldsmith

    Heads would explode. Heads did explode. Heads are still exploding.

    Even so, as I said in my previous post, that was a very fixable problem. Dan was still new. He easily could have played the “new guy” card. A mea culpa, a couple of comments to reporters, and a brief but earnest listening tour likely would have blunted the worst of it. The company could have reset and been in a position to have productive conversations with customers about this thorny set of challenges that they need to face together. Instead, Goldsmith said nothing, and the problem festered.

    In July, Instructure VP of Higher Education Jared Stein wrote a blog post on DIG trying to settle things down and dispell some of the concerns. I trust Jared and, more importantly, Instructure customers trust Jared. He did a decent job in that post, as far as it went. But one blog post by a senior employee, three months later, is not going to undo the damage of such a bad faux pas by the CEO. A CEO trumps a VP. Therefore, a CEO’s misstatement can only be credibly corrected by the CEO. Furthermore, Pandora’s Box had been opened. Because Instructure didn’t jump on the lid the moment they saw it crack open, all the deeply difficult questions about uses of student data in EdTech have come flooding out. The company didn’t lose everybody’s trust, but they lost the trust of enough vocal customers that now they have a persistent problem.

    This too is fixable, but it must be fixed. Some damage has been done to Instructure’s reputation. Enough that a more concerted and sustained effort must now be made which includes actions and not just gestures. But the imbroglio has not yet permanently damaged the company. People have long memories of their experiences with Instructure and personal relationships with employees who still work there.

    Update: Jeff Young just published a piece out about the data concerns in EdSurge. It includes quotes from Instructure’s chief spokesperson Cory Edwards, who I don’t know well but have found so far to be a good actor, and Melissa Loble, a long-time Instructure vet and current SVP for Customer Success, who is exactly the kind of person we should be hearing from directly more often. There’s even a quote from a Thoma Bravo representative. All were responding directly to the data use uproar. So this is progress. But still nothing from CEO Dan Goldsmith. Why EdSurge was able to get Instructure’s prospective PE owner on record but not its CEO, about a problem that was set off by a comment made by that CEO…it’s just mystifying.

    Education needs insight-providing, data-driven tools to help educators better serve a wider range of students who could succeed if only we were offering them the right kind of help. Furthermore, educational institutions need productive partnerships with the private sector to get these solutions out to as many students as possible as quickly as is possible and responsible. But this partnership can only take place in a high-trust environment. Instructure has had the necessary level of trust from their clients to do this kind of work. They have damaged that trust in this particular area. But not beyond repair. There is still a sound foundation, and any cracks still can be repointed.

    This brings me to Instructure’s most compelling product. It is not Canvas. Canvas has only been Instructure’s second-most compelling product.

    Brand, brand, brand

    Most people interpret “brand” as shorthand for a banal series of tactics employed by marketing departments. Academics, in particular, are inclined to load the word with distasteful connotations of shallow window dressing at best and obnoxious disingenuousness at worst.

    Nothing could be further from the truth. “Brand” is another word for reputation. It is who people think you are. It’s how much they trust that you are who you say you are. How much they trust you, period. Brand isn’t a series of tactics. It is the outward manifestation of the character of an organization or individual, as understood by people who have come to know them based on their actions over an extended period of time. Far from being a small set of eye-rolling marketing gimmicks executed by a small set of individuals, an organization’s brand is the gestalt impression that people get from every single interaction they have with every single member of that organization and every single product, website, or other touchpoint. That gestalt is “monetizable” to the extent that people trust the organization to understand their needs and have their interests at heart. They will give you their money if and when they believe they can trust you with it.

    Instructure’s brand has, until now, been its primary and best product. It is still one of the best in the sector, even if it is getting a little ragged around the edges. Because the brand is still good, the company can still build the relationships it needs to make good acquisitions, evangelize those acquisitions to its customers, and work with its customers on even the most sensitive (and important) product research and development efforts.

    That is what I hope for Instructure and why I have expended so much energy writing these last two blog posts. I want to live in a world where EdTech vendors are successful because their customers and partners believe in them. Instructure has been that kind of company. And it still could be.

    But back to the proof of the pudding. In this 21st-Century economy, as the saying now goes, if you’re not at the table, you’re on the menu. Instructure can recover, succeed, and thrive to the degree that the company’s leadership can reignite their customers’ faith that they have a seat at the table. Every decision they make, including financial transactions, should be judged by how it helps or hinders them from doing so.

  • Instructure’s Proposed Acquisition is a Bad Risk for Everyone

    I did not want to write this post. I really didn’t.

    For starters, I’ve been delighted to get away from this sort of corporate analysis and accountability writing, knowing that Phil has it well covered on his blog. That goes doubly for LMS inside baseball. Second, having recently announced a major sponsorship from one of Instructure’s competitors, there’s no way I can write about this topic without the appearance of a conflict of interest, particularly when my assessment is negative. Third, After watching the fights about what the acquisition means breaking out on social media, I have about as much desire to insert myself in the middle of that as I do to stick my index finger into my garbage disposal.

    But people keep asking me to write about Instructure’s prospective acquisition by Private Equity (PE) company Thoma Bravo. And it’s a consequential moment. One of only a very few mainstream LMS providers is at an inflection point. Perhaps more than customers realize. I have become increasingly worried that, by going through with this particular sale at this particular time, there is a very high risk of destroying the company’s value to customers and shareholders alike.

    So here I go. Stickin’ my finger in the garbage disposal.

    In this post, I’m going to explain why I worry the current deal on offer to take Instructure private runs a high risk of being bad for everyone.

    Instructure probably needs to do this at some point

    Let’s start with a basic reality: The reason that Instructure is moving toward a sale to private equity is that the company is at an inflection point and, despite its history of success, could very easily fall apart. Most Instructure customers don’t see this; what they see is a company that keeps growing and, on the surface, doesn’t seem to have changed dramatically. But major shareholders and board members have a different perspective. They see financial problems down the road, and they also see that life under private equity could buy the company the time it needs to address these challenges in ways that staying publicly-traded might not. There is some debate among shareholders about how quickly this move must be made and how to best accomplish it. But I haven’t heard objections from these stakeholders that taking the company private is a bad idea in general. I agree with them on that point. I personally believe that a sale to the right PE firm is probably a good idea in principle, both for shareholders and for customers.

    Instructure’s competitors have made a big deal out of the fact that the company still isn’t profitable after all these years. That’s a bit of a red herring. Instructure has chosen to reinvest profits in the company. When you do that, the “extra” money the company has made from a sale is no longer called “profit.” But that is a choice.

    The real problem is that selling Learning Management Systems is, in and of itself, not a very good business. Yes, Instructure could have been profitable sooner. But not very profitable. The way that LMS companies become financially healthy in the long run—to the extent that they do—is by selling other products and services to their existing LMS customer base. They increase the number of dollars per customer that they earn by selling those customers other things. (We’re going to return to that last sentence later in this post, because even though it is true, it is framed in a way that often leads EdTech Private Equity acquirers to make very bad decisions.)

    Instructure has a strong and growing customer base (even if the rate of growth has slowed recently). That’s why investors are attracted to them. What the company lacks is a portfolio of other products and services to sell. They have a good foundation, but they need to build on it. So there are a few critical questions that I am going to address in this post which are relevant to everyone who wants to see Instructure become more valuable rather than less:

    1. How did the company manage to grow so dramatically for so long?
    2. What does the company need to do in order to avoid breaking the engine that enabled them to acquire and retain customers?
    3. What would a credible plan for increasing Instructure’s future value to customers look like?
    4. What is the gap between a credible plan and what Instructure has presented so far?
    5. Why is that gap bad for current shareholders and dangerous for customers in the context of a potential acquisition?

    Before I get to these questions, though, I want to address a source of anxiety that I am seeing on social media that I think is misplaced. There is a narrow and outdated notion of what PE does that is leading to some unrealistic fears among some concerned academics. While there are real risks to worry about here, it’s important to focus on the fears that are realistic.

    Private equity is…equity that is private

    From a definitional standpoint, a private equity (PE) company purchases equity—stock shares—of the companies it invests in, but it does so outside of the publicly traded stock markets. For many years, private equity companies tended to follow one of only a couple of well-defined playbooks. Sometimes they would be house flippers, fixing up an undervalued house and then turning it over (relatively) quickly for a profit. Sometimes they would be junk dealers, stripping a car with a broken engine for the parts that still had value. Sometimes they would be slumlords, extracting as much “rent” from the asset as they could while putting as little investment in maintenance as they could. While the word “slumlord” is (intentionally) pejorative, some of these models could work out fine for the customers and employees, depending very much on the specifics. More on that in a bit.

    Now that the private equity markets have reached over three trillion dollars (and growing rapidly), there is a lot more diversity in the kinds of investors buying equity privately. Their goals, risk tolerance, and strategies vary pretty widely. There are, for example, family offices where rich people invest their money in individual companies rather than on the public markets. Depending on the goals of the family, the behavior of these funds can be quite long-term-minded and benign. Or not. You just can’t conclude much from the label “private equity” by itself anymore.

    Here’s another way to think about it: Academics tend to be suspicious of venture capital, private equity, and IPOs. Basically, any funding is anxiety-provoking because of the potential strings attached. In Instructure’s case, they earned a spectacular reputation with customers while being venture-backed. They’ve done less well, but not horribly, since their IPO. What can we conclude, then, about the relative badness of VC-backed companies versus publicly traded ones?

    Uh…not much. It comes down to the alignment of incentives between the investors and the customers. Understanding that will help to clarify which fears about this particular acquisition are realistic and which are not.

    Instructure has no parts to fleece

    One concern I’ve read is that the new private equity (PE) owners will sell off parts of the company. To which I reply, Which parts are you worried about them selling off?

    Canvas?

    No. There would be no company without Canvas.

    Arc?

    Are people massively freaked out about the potential sale of Arc? I’m guessing not.

    Portfolium?

    I’m not saying anything bad about the product itself (or any of Instructure’s products), but is all of this hand-wringing about the possible sale of Portfolium? Doubtful.

    Bridge?

    Hmm. Let’s set Bridge aside for a moment, look at a situation with an LMS company where selling off parts actually was a viable business strategy, and then return to it.

    Blackboard’s PE owners sold off CashNet less than a year ago. It was an absolute nightmare for the company’s bread-and-butter education customers.

    Oh, wait. No, it wasn’t.

    Blackboard Learn customers, by and large, didn’t even notice that CashNet was gone. It was an asset that had more value to those customers in the form of the cash that Blackboard got for it than in the actual ownership of the product. This was a case in which selling off a part of the company was both a good strategy from a financial perspective and inconsequential at worst to customers.

    In fact, Instructure is struggling now largely because it doesn’t have enough valuable parts to sell. To anyone, including current customers. The company failed to develop a strong portfolio of products they could “cross-sell.” Going back to Blackboard for a moment, however much people may grumble about them (rightly and/or wrongly), when the conversation shifts to the topic of their Ally accessibility product, eyes light up. It solves a real and important problem. People want it. Current Learn customers want it. Prospective Learn customers want it. Customers who wouldn’t touch Learn with a 10-foot pole want it. Therefore, it has financial value.

    Instructure needs a portfolio of offerings that are compelling as Blackboard’s Ally in order to be financially viable in the long term. Because the company has thus far failed to develop such a portfolio, it developed an alternative growth strategy to sell an LMS into the corporate market instead. And not its existing LMS. No, a new one. Bridge.

    This, frankly, was a dumb idea that was never going to work. Where the LMS is a mission-critical application that inspires passion—positive or negative—from users in the education markets, it is the polar opposite in the corporate markets. Whenever corporate budgets get slashed, Training and Development is the first departmental budget to get hit. And unlike the academic LMS market, there are somewhere in the neighborhood of 173,000 corporate LMS products. OK, I’m exaggerating. A little. But it’s a large enough list that whole companies have been built on writing up catalogs that describe the different LMSs in that market. Not even reviewing them, really. Mostly just listing them all in one place.

    Ask yourself how detrimental it would be for you if Instructure sold off or killed off Bridge. If your answer is “not very,” then you don’t have much to worry about in terms of new owners selling off pieces of the company.

    It’s important to understand that a profit motive and a motive to serve students and educators well are not inherently opposed to each other. They can be. They are almost always in tension with each other. But if the best way to make money is to serve students and educators well, then good results for education can be driven by a profit motive. Money will be more likely to be invested in the right things. I say “more likely” because the other challenge is knowing how to invest that money such that it will be likely to have the net effect of serving students and educators well. My father likes to say, “Never attribute to malice that which simple incompetence can explain.” More on this later in the post.

    The PE acquisition would be to support a return to a focus on education

    One way to read the PE acquisition is as an admission of failure of the Bridge strategy. That is certainly, explicitly, the line that Instructure’s activist investors have been pushing. If you’re worried about the impact of the short-sighted view of PE, then you should also be worried about the quarter-to-quarter pressures of the public markets. Instructure’s Bridge strategy failed to produce the financial results that were promised. One argument for PE acquisition in this situation is that the public markets would not be patient with Instructure as it attempts to recover from this misstep and build the product portfolio that it should have started working on five or more years ago. The right PE firm would give Instructure time to ditch Bridge and refocus on its core market. (That’s you.)

    I don’t know much about Instructure’s PE acquirer, Thoma Bravo. Phil describes their investment style thusly:

    Thoma Bravo is widely known for the “buy and build” acquisition strategy, where a platform company with solid customer base is purchased (often for high price), enabling subsequent acquisitions of smaller companies that have lower price multiples. This is not the same as buying company A and B and combining them; rather, this strategy is based on multiple acquisitions tied to the platform company.

    That fits with what Instructure needs to do to become more sustainable in its core education markets. It needs more educational products to sell. So at first blush, Instructure being owned by Thoma Bravo could be better for customers than Instructure being publicly traded has been.

    Interestingly, though, the current Instructure shareholders who oppose this acquisition also argue that Instructure should return its focus to its core market of education. They just don’t think this particular deal is the best way to do it and are suspicious that there are other, more venal reasons for this particular merger at this particular time. Here, for example, is what Instructure investor Rivulet argued in its SEC filing protesting the merger:

    We invested in Instructure because we admire the company, and we see plenty of opportunity for continued growth and success. With Canvas, Instructure has developed the market-leading learning management software product for the higher education market. The Canvas story has provided an incredible lesson about the success that comes from a focus on innovation, putting students first, and offering a compelling alternative to a greedy incumbent that was run for the enrichment of management and shareholders. Unfortunately, with the announced sale of the company to Thoma Bravo, Instructure is providing a different sort of lesson to its customers and shareholders. Here, it appears that the company has run a rushed strategic review process that was designed to result in a sale to management’s chosen buyer at a low price…in order for management to save their jobs and enrich themselves in the years ahead. It is outrageous.

    Rivulet SEC filing

    In other words, investors both in favor of the merger and opposed to it agree that Instructure is a growth company that has stalled because it has lost focus on its core education markets. They believe the company can continue to serve its shareholders well by serving its education customers well. The debate among them is over whether this deal was really designed to serve those customers (and thus generate profit for shareholders), or whether it was corrupted by an agreement that exchanged preferential treatment of Thoma Bravo in the bidding process for particularly rich compensation for Instructure CEO Dan Goldsmith and his sister, who Goldsmith hired as a senior executive of the company.

    I will not write about the details or the merits of those accusations in this post. That’s not e-Literate‘s beat anymore, and I have no insights to offer about them that would add any value. If you want to read more insightful and in-depth coverage of that fight than I could offer, then go read Phil Hill’s coverage.

    Rather than speculating about motives or analyzing the finances, I am going to write about strategy and execution. Does Instructure’s current executive team have a credible strategy and a strong track record of execution that is consistent with its previous, incredibly successful strategy for growing and retaining its installed base? And does it have a credible, market-validated strategy for increasing the value that it provides to its customers such that customers will likely be willing to pay more for that value? If the answer to these questions is “yes,” then current shareholders can have increased confidence that they will receive a good price for their shares while the end users of Instructure’s products and services can have increased confidence that they can continue to count on the company to serve them well.

    Unfortunately, it looks to me like the answers to these questions are “no.”

    Why Instructure has succeeded—and failed—to date

    We have long argued at e-Literate that Instructure came to market with three critical advantages that incumbent competitors were slow to see and which were difficult, time-consuming, and/or expensive for them to replicate. Those advantages are as follows:

    1. Reliability (implemented as cloud-native infrastructure)
    2. Ease of use (implemented as a rethink and redesign of existing LMS functionality)
    3. Customer rapport (implemented through a variety of formal and informal ways and tied together by a strong company culture)

    These three advantages can be collected under one unifying strategic insight of the original executive management team: They brought a consumer software sensibility to what had been treated by incumbent vendors as an enterprise software business.

    Instructure understood who their customer really was in a changing market

    For readers who are not software industry aficionados, one way to get at this difference is to ask yourself a few questions about software products being used at your institution that are generally treated as enterprise software products. How involved were you in selecting your registrar software? How broadly and intensively were different stakeholder groups involved in the selection process? Who made the final decision? Do you even know the answers to any of these questions? Do you know how the decision was made?

    Generally speaking, registrar software is part of a larger package of software that includes modules for things like payroll and expense tracking. There is usually a very small group of people who both make the decisions on the procurement of such software and who also decide who else will have input on the process. This is typical with enterprise software selection—even for critical enterprise software that has many end-users who depend on it and use it daily. For enterprise software companies, their customers are those few decision-makers. They only have to care about reliability, ease of use, and end-user happiness to the degree that the decision-makers do. And often, those decision-makers have other priorities, like cost, or arcane but important support for regulatory requirements, or making their bosses happy in some way.

    In the early years, LMSs were procured like enterprise software. CIOs generally selected the LMS vendor and decided on whose input they would take when making their selection. But by the time Instructure came on the scene, that was changing. Faculty were much more intensively involved with LMS selection, and it was not unheard of for a university to form a student advisory committee or conduct focus groups as part of the selection process. Instructure made and kept three promises to these stakeholder groups. First, they would build and run the LMS such that it would be extremely unlikely to go out for two weeks at the beginning of the semester or in the run-up to finals week. Second, it would be less painful and time-consuming to use than the alternatives which existed at the time. And finally, end-users would be treated as human beings, with good customer service and both visibility and input into the product roadmap.

    Given the pedigree of the executive team at that time, these changes should not be surprising. CEO Josh Coates’ previous gig was running Mozy, a startup that was essentially the precursor to Dropbox. Think about what life was like trying to back up or share locally stored files across multiple devices before Dropbox. There was FTP. There were email attachments. And there was Sharepoint. But in order for a Dropbox product to replace those well-entrenched incumbents, it had to be rock-solid reliable, be dead simple to use, and feel completely approachable and safe.

    Instructure has been spectacularly successful not because it has been a great education company but because it has been a great consumer software company. And the early management team was very clear about this distinction. Here’s what I wrote in a 2012 post:

    The founders of Instructure aren’t educators, and they think that’s a good thing. The way they see it, educators tend to build software that solves their own problems from their own perspective, and the results are often idiosyncratic. As technologists coming in with no strong opinions about how teaching “should” be done, the Instructure leadership feel they have an advantage of humility and open-mindedness when considering solutions. As CEO Josh Coates put it, educators “are experts in their context. But their context is one or two classes in a specific university in a specific part of the country. Software developers don’t even pretend to know the domain.” So they have to go out and do the research. Instructure co-founder Brian Whitmer added, “And we know that we have to do it. We know that we have to validate it against a bunch of different people.” And they do. Instructure, as a company, is extremely attentive to the conversations among educators, to the point where they have Twitter feeds from various ed tech folks sucked right into the IRC channel that all their developers use for internal communications. They do their homework.

    Educators tend to get hung up on the profit motive and, ironically, miss the disciplinarity of starting a company. Co-founder Devlin Daley talked about a “new style of development” that was “not true in the ’90’s,” and all three of them talked a lot about Agile development. As they see it, a lot of companies that implement Agile miss the fundamental aspect of the methodology that is about getting closer to customer needs.

    e-Literate, “What Are Ed Tech Entrpreneurs Good For?“

    Instructure lost its way after solving the obvious problems

    In a lot of ways, Instructure got a big leg up by being late to the market. The product category was well defined through the experiences of the early incumbents. Does an LMS need a gradebook? Definitely. A test engine? For sure. A blogging system? Ehh…. Instructure’s product team could go to a lot of people who were already using LMSs and ask them, “What do you hate about this thing and what are you really trying to accomplish that is possible but painful in it?”

    And, in fact, that is exactly what Instructure did. They figured out what problems people were trying to solve when they used an LMS and then, rather than building yet another, more feature-packed version of the same tool, they set out to build solutions to those problems. For example, they figured out that instructors who were entering grades wanted to do so as quickly as possible and focus their energy on adding educationally useful comments. So rather than cramming more features into the same spreadsheet-style gradebook that every other LMS had implemented, they built SpeedGrader, a novel user experience that helped instructors focus on the aspects of grading that they cared about while moving other functions out of the way. Why should instructors have a grade curve-setting widget taking up screen space when they’re trying to comment on a student’s paper?

    But once Canvas had caught up functionally with the other LMSs, Instructure seemed to run out of ideas. Internal to the LMS, we haven’t seen many truly major customer-facing improvements in the past four years. In fairness, Instructure claims to have been doing a lot of under-the-hood work that will yield future benefits. But I’m still fairly unclear on what those future benefits will be.

    Meanwhile, what new customer problems have they solved outside of the LMS? What new products have they given us?

    Arc. They gave us Arc. A lecture capture tool. Another lecture capture tool. Is it good? Yeah, it’s pretty good. Did it set the world on fire? No, it did not.

    I don’t want to overplay the we-don’t-need-another-one-of-those card, because Canvas itself could have been dismissed on those grounds when it first came out. In fact, it was dismissed on those grounds. I, personally, dismissed it on those grounds.

    Nor is it the only example of such a product. Not by a long shot. Consider Zoom. It dominates the webconference market, both in education and elsewhere. How did that happen? Cisco already had a very mature and very widely adopted product in Webex. Google had Hangouts. Adobe had Connect. Blackboard had the education-specific Collaborate solution. There are multiple open source options, like Big Blue Button. There are other options like GoToMeeting and Bluejeans. There was no good reason to believe that a startup with yet another webconferencing solution would survive, nevermind thrive.

    And yet, it did.

    Why? This is the critical question for Instructure to both maintain its current strength and build new ones. Maybe Instructure just got lucky by coming in when they did. Maybe they weren’t nearly as talented as they seemed to be. Humans tend to over-credit skill and under-credit timing and luck.

    Even so, I don’t believe that luck and good timing were the primary reasons for Instructure’s success. Permit me to repeat a snippet from the quote above of my 2012 post:

    Co-founder Devlin Daley talked about a “new style of development” that was “not true in the ’90’s,” and all three of them talked a lot about Agile development. As they see it, a lot of companies that implement Agile miss the fundamental aspect of the methodology that is about getting closer to customer needs.

    I believe Instructure had an approach to building their business that worked. They lost some mojo because, among other reasons, the pressure for them to grow pushed them into flattening what had been a philosophy and corporate culture into something closer to a paint-by-numbers formula. This is one reason why sales have slowed. Instructure is no longer performing as a truly great company. And if they don’t find their mojo again before they enter into an acquisition, then things are far more likely to get worse—possibly catastrophically worse—than they are to get better, because building a culture of product development excellence is not one of the things that PE knows how to do well. Whatever patterns are there when the company is purchased are likely to stay. Whatever direction the CEO has set will stay. And without the bulwark of leadership protecting a strong culture of excellence, the tendency to paint by numbers is likely to get worse rather than better. PE firms may or may not understand education, but they all understand numbers and find a high level of comfort in them.

    Product-led Growth

    Back when Instructure was being started, the software product development buzzwords were “Agile” and “Lean.” Today, a new buzz-phrase that also fits with that quote above is “product-led growth.”

    “Product-driven company” can be defined narrowly or broadly. The narrower version involves some fremium model where people adopt a free version of the product through a self-service process, use it a lot and, once again through self-service with no human salesperson involved, upgrade to a paid version. Zoom works like this. So does Dropbox. I had a free Dropbox account for a long time. To borrow a phrase from Apple, it “just worked.” I used it to the point where I needed more space. So I paid for an upgrade. At peak Dropbox for me, I had a personal paid account as well as a larger one for my company.

    Spreadsheet jockeys like product-driven companies because they have low sales and marketing costs. People adopt the product because it’s easy to do so. It spreads because people tell their friends and colleagues about how good it is. It makes money because people love and use the product so much that they will pay for an upgrade. The customers do much of the sales and marketing work and pay for the privilege.

    But as with Agile, people who implement a product-driven company design miss the fundamental aspect of the methodology that is about getting closer to customer needs. And again, Josh Coates’ last gig before becoming Instructure’s (previous) CEO was building the precursor to Dropbox. There wasn’t a big self-service component to Canvas sales, but the core philosophy of creating a customer experience that carries a lot of the sales and marketing load by inspiring fanatical loyalty was there.

    At least, it was there in the beginning, and for quite a while. It has been less evident in recent years. When a company is under pressure to grow, either financially or just to scale up to meet the needs of new customers that are walking in the door, it is easy to slip from a focus on finding new problems to solve toward one of finding new things to sell. In EdTech, there aren’t many obvious things to sell, particularly “at scale.” Painting by numbers under these circumstances is a weak strategy that fails often.

    But education has many, many problems to solve. If you have a strong rapport with your customers, a really solid team of education specialists who understand the complex nuances of educational problems, and a leadership team that is absolutely committed to growing by understanding their customers’ needs better than anyone else does, then you can find ways to make money by solving new problems. Product-driven companies are problem-driven companies.

    A good example of solving new problems is Blackboard’s decision to acquire Ally. Was there a healthy, established product category for an educational content accessibility checking platform that would be sold to colleges and universities? Absolutely not. Could anyone calculate the total addressable market (TAM) for such a product without wildly guessing? Not in any way that I can think of. Were Blackboard’s customers begging them to build and sell such a product? I very much doubt it, since there really wasn’t any such thing on the market.

    But Blackboard saw that the little startup that had found this problem to solve. I’m sure they talked to Ally’s customers—and their own—about it to make sure that it was a real and large problem, solved by the product in a useful way. And they made a bet. It’s turning out to be a good one.

    In retrospect, you could argue that the product is adjacent to Blackboard’s LMS business. But almost everything in EdTech is adjacent to the LMS because almost everything has to connect with it or work with it. If you had grabbed a random EdTech mid-level manager off the street and asked them for their top suggestions for hot product categories that are adjacent to the LMS, I doubt that learning content accessibility would have shown up on anybody’s list. This is the kind of thinking that made Instructure, and it’s the kind of thing it needs to be doing again if it wants to find its next leg of growth while holding off its newly resurgent competitors.

    So who did Instructure’s board hire to lead the charge at this critical moment to reinvigorate that deep culture of devotion to solving the problems of the end-users? A guy whose last job was running a company that sold enterprise software to life sciences companies.

    Now, Dan Goldsmith is not his résumé. He’s a multidimensional person who is capable of learning. (And to be fair, Josh Coates was not an obvious candidate for the job either.) But Dan has been in his current job for less than two years. In order for him to establish that he is up to this challenge in this industry within that length of time, he would have had to perform extraordinarily well. This is vital right now because the very same shareholder ballot they are voting on to accept Thoma Bravo’s offer would also change Dan’s compensation package to one that would attempt to lock him in with a very generous amount of stock that vests over time. If Instructure’s board and shareholders have decided that now is the time to go private, with this CEO, then they need to be very confident that he will deliver. If they are not, then the customers are under increased risk, the new owner is under increased risk, and the current shareholders are less likely to get attractive competing bids for their shares.

    Has Dan Goldsmith met this high bar in the brief 20-month period that he has been on the job?

    In my opinion?

    No.

    A case study in the opposite of what Instructure needs to do

    Instructure hasn’t made a lot of significant moves in the education space since Dan took the helm. Off-hand, I can think of two. The first was the acquisition of Portfolium. In and of itself, that’s not an obviously genius move. The ePortfolio product category has been around almost as long as the LMS product category and has been a hot seller since…uh…never.

    It could turn out to be an interesting move. Instructure has to bet that (a) potential trends like comprehensive learner records or stackable credentials will turn into something more substantial and that (b) an ePortfolio in general and this ePortfolio, in particular, provides a good infrastructure from which to start supporting those trends. I’m troubled by the fact that I’ve not heard an articulation from the company about their vision for the product. Dan made some comments about the potential for cross-selling. But those comments characterize Portfolium as a thing to sell, not as a solution to a customer problem. I simply don’t know what they’re thinking with Portfolium.

    The other move was Dan’s announcement about their DIG learning analytics initiative in the spring of 2019, which Phil covered in his own inimitable way:

    The second initiative announced on the earnings call was DIG, a strategic move with data and analytics.

    “I am also pleased to share with you an early insight into our second growth initiative focused on analytics, data science and artificial intelligence. The code name for this initiative is DIG. And this technology platform combined with the most comprehensive SaaS database on the educational experience uniquely positions us to deliver meaningful value to our customers. And from a growth perspective, DIG has the potential to double our TAM in education.”

    Instructure started ramping up their data and analytics efforts (again) about a year ago, although the focus was described at the time as being about internal analytics – that is, making Canvas a better and more valuable LMS product. From what I have heard the product validation for DIG are consistent with this message – dashboards, surfacing useful data within a workflow, etc. But that was not how DIG is being sold during the conference call [emphasis added].

    “We’ve been working on the scaffolding for [DIG] for well over a year now. I mentioned in our remarks that we already have product validation towards out there in the market. We have instructors and students consuming output from some of the initial experiments with DIG. And we anticipate later this year obviously to make more announcements around specific products and offerings and how we bring them into the market. DIG ultimately is a platform first and foremost based upon machine learning and artificial intelligence. I believe that any multi tenant SaaS company born in the cloud has the opportunity once they hit a certain market share. And in fact, it may even be incumbent upon those organizations to partner with the industry and evolve that industry with new insights and predictive modeling using AI and ML. That’s what DIG is at its heart.“

    This is brand new behavior for Instructure as a company. Previously the company was reticent to talk much about non-released products, but now they are talking not just about a new initiative, they are touting buzzwordy machine learning and artificial intelligence and predictive modeling well before any of those capabilities exist or are in customer hands. Goldsmith further clarified the DIG plans during the investor conference discussion [starting at 9:00, emphasis added].

    “We already have analytical capabilities in our Canvas platform. I want to be really clear and delineate the difference between an analytics and reporting capability, and a machine learning and AI platform. [snip]

    “We have the most comprehensive database on the educational experience in the globe. So given that information that we have, no one else has those data assets at their fingertips to be able to develop those algorithms and predictive models.”

    Goldsmith then described an example of predicting a student’s expected performance in a class and how that prediction reliability goes up over time. Then we get the vision.

    “What’s even more interesting and compelling is that we can take that information, correlate it across all sorts of universities, curricula, etc, and we can start making recommendations and suggestions to the student or instructor in how they can be more successful. Watch this video, read this passage, do problems 17-34 in this textbook, spend an extra two hours on this or that. When we drive student success, we impact things like retention, we impact the productivity of the teachers, and it’s a huge opportunity. That’s just one small example.

    “Our DIG initiative, it is first and foremost a platform for ML and AI, and we will deliver and monetize it by offering different functional domains of predictive algorithms and insights. Maybe things like student success, retention, coaching and advising, career pathing, as well as a number of the other metrics that will help improve the value of an institution or connectivity across institutions. [snip]

    “We’ve gone through enough cycles thus far to have demonstrable results around improving outcomes with students and improving student success. [snip] I hope to have something at least in beta by the end of this year.”

    Wow. Robot tutor in the sky – meet the new kid on the block.

    For those readers who don’t follow the sector broadly, Phil’s reference to a “robot tutor in the sky” is from an infamous quote by the CEO of now-defunct Knewton that they liked to think of their product as “a robot tutor in the sky that can semi-read your mind.” In other words, Phil is accusing Goldsmith of using tone-deaf language that would be explosive to educators. And sure enough, it pissed a lot of people off. They didn’t like the vague hype, and they didn’t like the seemingly out-of-the-blue implication that students’ data from their in-course activities would be used without their permission for Instructure’s product development purposes. As I mulled whether and how to write this post, I received the following reply on Twitter to my retweeting of one of Phil’s posts on the topic:

    OK, OK, so somebody on the internets wrote a mean thing about Instructure’s DIG strategy. And is still upset nine months after the announcement. Maybe that evidence doesn’t persuade you (particularly if you don’t know who Laura Gibbs is).

    How about this?

    That’s a Twitter thread from Canvas end-users who are crowdsourcing a letter encouraging their institutions to lobby Instructure shareholders about Instructure’s lack of legally binding data privacy policies. Now, the authors had voiced a range of concerns in the last draft (plus comments) that I looked at before writing this post. Some of them may have been poorly phrased, overblown, or factually questionable. But others were unquestionably legitimate, sophisticated, and serious.

    Update: The authors of the letter have posted the most recent draft here, and a signable petition here.

    I see three big take-aways from this letter which are most important for our current purposes. First, this is the first time in my long history of covering EdTech that I have ever seen educators undertake such an effort to influence shareholders. The last company I would have expected to inspire this level of concern-driven activism is Instructure. And the existence of it strikes me as one of the most singular and remarkable milestones of Goldsmith’s tenure to date. Trust me: This should be taken seriously.

    Second, one reason this foment continues to build nine months after Dan’s original comments about DIG is that, at least to my knowledge, Dan himself has yet to address these customer concerns directly, publicly, and credibly. Even in this Twitter thread, he leaves the job to an anonymous PR person to desperately try to tamp down the anger. At this point, given what’s at stake, he should be making a direct personal statement as the CEO of the company. If not on Twitter, then on the company blog. Or somewhere. Anywhere.

    Finally, the authors of the letter make clear they understand that there are no obvious, well-trodden solutions to the student data privacy conundrum. They request some specific steps at the end of their letter, but they don’t pretend that these steps solve the complex, pervasive, and important challenges that universities who work with EdTech products face. They are struggling to balance the need to protect student privacy against the affirmative ethical obligation to learn how to better help their students succeed.

    THIS IS A PROBLEM THAT CUSTOMERS NEED HELP SOLVING.

    Instead of either assuming a defensive crouch about DIG or ignoring complaints altogether, Instructure could be listening to customer concerns with an ear toward making money by serving them better. This is a hard and important problem space that will not be solved without active participation by vendors. There have been academic convenings on the student data privacy challenge by groups like Asilomar. They do critical work. But they are not enough. There are initiatives by industry groups like IMS. They too are necessary but not sufficient. This is an important and growing problem, which makes it an important and growing commercial opportunity for a vendor that can actively partner with academia in finding a solution to it.

    Dan Goldsmith could have easily turned his faux pas into a moment of leadership. There is even precedent from Instructure for this under strikingly similar circumstances. I encourage you to (re)read Phil’s 2015 post on how Josh Coates handled customer complaints about the company charging universities for access to their own students’ data. The short version is that once Josh became aware of customers’ unhappiness, he took it as an opportunity to engage with them, changed the policy, published a mea culpa post on the company blog, and encouraged Phil to independently verify with the customers that their concerns had been addressed.

    Dan’s comments were significantly less serious than the implemented commercial practice that Josh had to correct. He could have easily addressed them. And there is a real problem space here that cries out for product development. EdTech needs an architecture of privacy. Instructure’s customers are being very direct about their needs and concerns. The company even has access to multiple academic experts who could help them think through the nuances of the problem. I know this for a fact because I introduced Instructure employees to those experts last spring when I urged them to turn the DIG situation around by taking leadership.

    That was over half a year ago. And now we have customers banding together to lobby shareholders about their continuing dissatisfaction. Because apparently, they have come to the conclusion that the company leadership is not listening to them.

    No. I would not bet the company on the 20-month record of Dan Goldsmith’s leadership and articulation of strategic direction. Maybe things will be different six or twelve months from now. But at this point, he has neither embodied nor provided a sound investment thesis. There is no strong reason to believe that Instructure, sold to private equity under this leadership at this moment, would be able either to continue to grow market share of its core product or to develop new solutions to real customer problems that would lead to greater profitability.

    Just how bad it could get

    I want to wrap up this post with a couple of hypothetical but plausible examples of just how bad things could get when an LMS company with no products to cross-sell and no customer-focused, problem-solving leader sit down in a room with PE owners who have big ambitions, a lot of money, and limited experience in the space. A player like Thoma Bravo is going to make acquisitions. If they make a number of small bets that don’t pay off, then there are likely to have to cut costs and raise prices to make up for their losses.

    But what I really worry about are the kind of colossal mistakes that can happen when a CEO who doesn’t know education and investors who don’t know education lock themselves in a room together and try to come up with something really big. Phil noted in a recent post about Thoma Bravo,

    Another point in the Forbes profile is that Thoma Bravo does not acquire a company and then figure out what other companies to tuck-in or combine [emphasis added].

    “Like a good tennis player who’s worked relentlessly on his ground strokes, Bravo has made private equity investing look simple. There are no complicated tricks. He figured out nearly two decades ago that software and private equity were an incredible combination. Since then, Bravo has never invested elsewhere, instead honing his strategy and technique deal after deal. He hunts for companies with novel software products, like Veracode, a Burlington, Massachusetts-based maker of security features for coders, or Pleasanton, California-based Ellie Mae, the default system among online mortgage lenders, which the firm picked up for $3.7 billion in April. His investments typically have at least $150 million in sales from repeat customers and are in markets that are too specialized to draw the interest of giants like Microsoft and Google. Bravo looks to triple their size with better operations, and by the time he strikes, he’s already mapped out an acquisition or turnaround strategy.“

    Instructure fits into this playbook, and I suspect that we won’t have to wait long to see the next move. It could be tuck-ins in the vein of Portfolium, Practice, or MasteryConnect, or it could be something bigger and market-changing. It is worth noting that Bravo raised $12.6 billion in January of this year – the stakes are getting higher.

    What would fit into the category of “bigger and market-changing”? I can think of only two plausible acquisitions, particularly since Thoma Bravo seems to be disinclined to invest in people-heavy businesses like OPMs or textbook publishers. Either one of these ideas would be so incredibly, mind-bogglingly stupid that I’m hoping this part of the post is just good for laughs. (Or maybe a Halloween-style scare. Boo!)

    The first possible merger target is Ellucian which, as Phil has pointed out, has put itself up for sale. On the spreadsheets, this could look like a great prospect for Instructure. They sell to the same client base, have a big installed base, a portfolio of products to cross-sell, and have a massive lock-in.

    Anyone who actually knows EdTech and is thinking from a product-led perspective would see this as the obviously terrible idea that it is.

    In general, the SIS market is a smoking ruin that will take at least another half a decade to move itself into the cloud. The technological heritage and history of the product category conspire to make Ellucian—and their competitors—about the furthest thing from a product-led company possible. Think about how hard it was for Instructure’s competitors to make the transition they needed to make in order to catch up. Now multiply the challenge by a kajillion. Combining Ellucian with Instructure would be a disaster.

    The only worse idea I can think of that might somehow seem plausible to the wrong people having the wrong conversation at the wrong time would be for Instructure to buy—are you ready for it?—Blackboard. Again, from a paint-by-numbers perspective, it makes perfect sense. Instructure could buy Blackboard’s remaining customer base very cheaply, along with its more successful portfolio of cross-selling products. (Their Ally accessibility platform, for example, is a well-deserved smash hit.) And since Blackboard is close to having zero financial value, with their debts being close to the intrinsic value of their assets, the sellers could unload an investment that is no longer performing for them while the buyers could get assets they need practically for free.

    And in the process, Instructure would acquire the worst brand in the product category—which is an improvement from when they were the worst brand in the history of the sector—by applying the most infamous and most loathed business strategies of their infamous former Blackboard CEO Michael Chasen—namely, buying up one of the few competitors in the market. Instructure could literally become the new Blackboard. In doing so, they would utterly destroy one of the greatest brands in the history of the sector instantaneously.

    These guesses must be wrong. (Dear Lord, please let them be wrong.) Think of them as hypothetical examples of “really, Michael, how bad could it get?” than as actual predictions. I have to believe that the board, the executive team, and Thoma Bravo would not be that dumb. But the point is that of those three entities—the board, the financial owner, and the CEO—the only one we would reasonably expect to know how bad such decisions would be in practice, the only one that all parties must be able to count on to steer the ship away from the many rocks and icebergs in EdTech, is the CEO.

    Has Instructure provided customers with a detailed and credible enough strategic roadmap to inspire confidence that they have a more compelling alternative for growth? No, they have not. Has Dan Goldsmith thus far proven, lacking such a roadmap, that his reputation for performance alone is worth betting the company on? No, he has not. No smart PE company would make an attractive counter-offer under these circumstances. There is no sound investment thesis until Instructure is able to regain its footing as a product-led company.

    Instructure has been one of the best run, most consequential companies in the history of EdTech, and it could be again. It has not yet experienced the talent flight that would make a turn-around much, much harder. But until it has both a credible strategy and a leader who inspires customers to trust the company with their most pressing and complex problems—like fulfilling their ethical obligation to protect their students’ privacy in an era of digital learning—it will be just another EdTech company that is toiling away in an unprofitable product category and promising investors that it will somehow spin straw into gold.