e-Literate

Present is Prologue

Tag: LMS

  • University of Wisconsin System to Migrate From D2L Brightspace to Canvas LMS

    University of Wisconsin System to Migrate From D2L Brightspace to Canvas LMS

    In one of the most significant LMS selection projects of the past few years, the University of Wisconsin System (UWS) has chosen to migrate from D2L’s Brightspace to Canvas as its centrally-supported Learning Management System (LMS). ((Disclosure: UWS, UW Madison, Instructure, and D2L are all subscribers to our market analysis service, and we aided UWS in the needs analysis portion of this project.)) UW Madison already moved to Canvas as part of its Unizin membership, but now the rest of the 180,000 student, 26 campus system will also make the change.

    The decision was first noted on the UWS procurement portal and in a investor analysis note from Raymond James. A representative from UWS confirmed the news and added that “Canvas has been issued the Notice of Intent to Award and a final contract is going to the UW System Board of Regents for formal approval in October”.

    The UWS project page describes the process leading up to the LMS selection, starting with needs analysis kickoff in 2015.

    The Learning Environment Needs Analysis (LENA) project was undertaken as a continuation of a multi-year UW System effort to: 1) understand the current and future learning technology landscape, 2) uncover the wants and needs of UW System institutions with regard to academic technologies that support teaching and learning, and 3) identify gaps that exist in supporting teaching and learning through academic technology. The results of the LENA project were presented to the Learn@UW Executive Committee, along with a recommendation that the Committee charter the process for planning to move into a next generation learning environment for the UW System. The intention was that through this process, UW System would discover potential paths forward to support such an environment.

    Last year UWS developed the request for proposal (RFP) requirements list, and the formal RFP was released in January of 2017.

    Beyond the size of the system, UWS decision is significant due to it being the first major customer of Desire2Learn (as the company was known prior to 2014). Back in 2002 / 2003, most LMS decisions were framed as Blackboard vs. WebCT, and when UWS selected little-known D2L, it sent shock waves through the market. The decision really put D2L on the map as a true contender, and they followed up with wins at the University of Iowa ((Disclosure: In previous consulting company I advised U Iowa on their LMS selection.)), the Ohio State University, Minnesota State Colleges and Universities, and the University System of Georgia.

    We have noted several times at e-Literate and as part of the e-Literate Big Picture: LMS market analysis service that D2L has an impressive record of client retention. The company has been a fierce competitor in keeping customers, as seen when the Colorado Community College System recently chose to remain on D2L Brightspace after their LMS selection process. ((Disclosure: CCCS is a subscriber to our market analysis service. I also advised CCCS when they originally chose D2L in 2008.)) This loss of UWS is the biggest setback for the company in terms of losing clients, and it is a major win for Instructure’s Canvas system.

    Expect more market news to come out in the next month based on WCET and ECUCAUSE conferences.

  • Response on LMS Market Size Analysis

    Response on LMS Market Size Analysis

    Josh Kim wrote a post yesterday at Inside Higher Ed questioning some claims about the LMS market size.

    The first result that comes up in Google is from Zion Market Research. Their estimate is that the global LMS market is valued at $5.19 billion in 2016, and expected to reach $19 billion by 2022.

    According to Statista, the LMS market in 2016 was valued at $3.21 billion. CNBC claims that the learning management system market is worth $5.2 billion today, and will grow to $16 billion in four years.

    Can these numbers be right?

    Josh then did a quick analysis based on Instructure’s revenue and came up with much smaller numbers.

    If we assume that the cost of Canvas is about average for LMS companies, we can get an estimate of the total market size by multiplying Instructure’s revenues by five. This gives us an estimate for the total size of the LMS market $555 million.

    He extended this by 50% based on Instructure growth to give an estimate of $555 – $832 million, which is way below the big numbers claimed by Zion, MarketsandMarkets, and other market analysts.

    The biggest difference here is that all of these analysts combine corporate learning markets with academic LMS usage, and corporate learning platforms account for somewhere between $2 – $4 billion, with best estimates (although outdated) coming from Bersin. This point has already been pointed out in the comments at IHE.

    tl;dr – the ~$5 billion number is reasonable if you combine academic and corporate LMS markets.

    There are two caveats, however.

    • First, the market growth claims are marketing fluff to generate interest in buying the reports, as companies love to show growth potential to investors. Anything close to $20 billion in a few years is ludicrous.
    • Second, as Michael commented on this approach based on a post I wrote criticizing MarketsandMarkets:

    If anything, my Phil understates the case here. Lumping higher ed, K12, and corporate LMSs into the same category is a little bit like lumping railroad cars together with automobiles because they are both called cars, have wheels, and carry things and/or people from one place to another. On top of that, nobody has decent data on the size of the global market, never mind the growth of it. MarketsandMarkets’ “analysis” effectively gives us made-up numbers about a mythical automobile/train car market.

    So a better question is what is the size of the global academic LMS markets, combining K-12 and postsecondary?

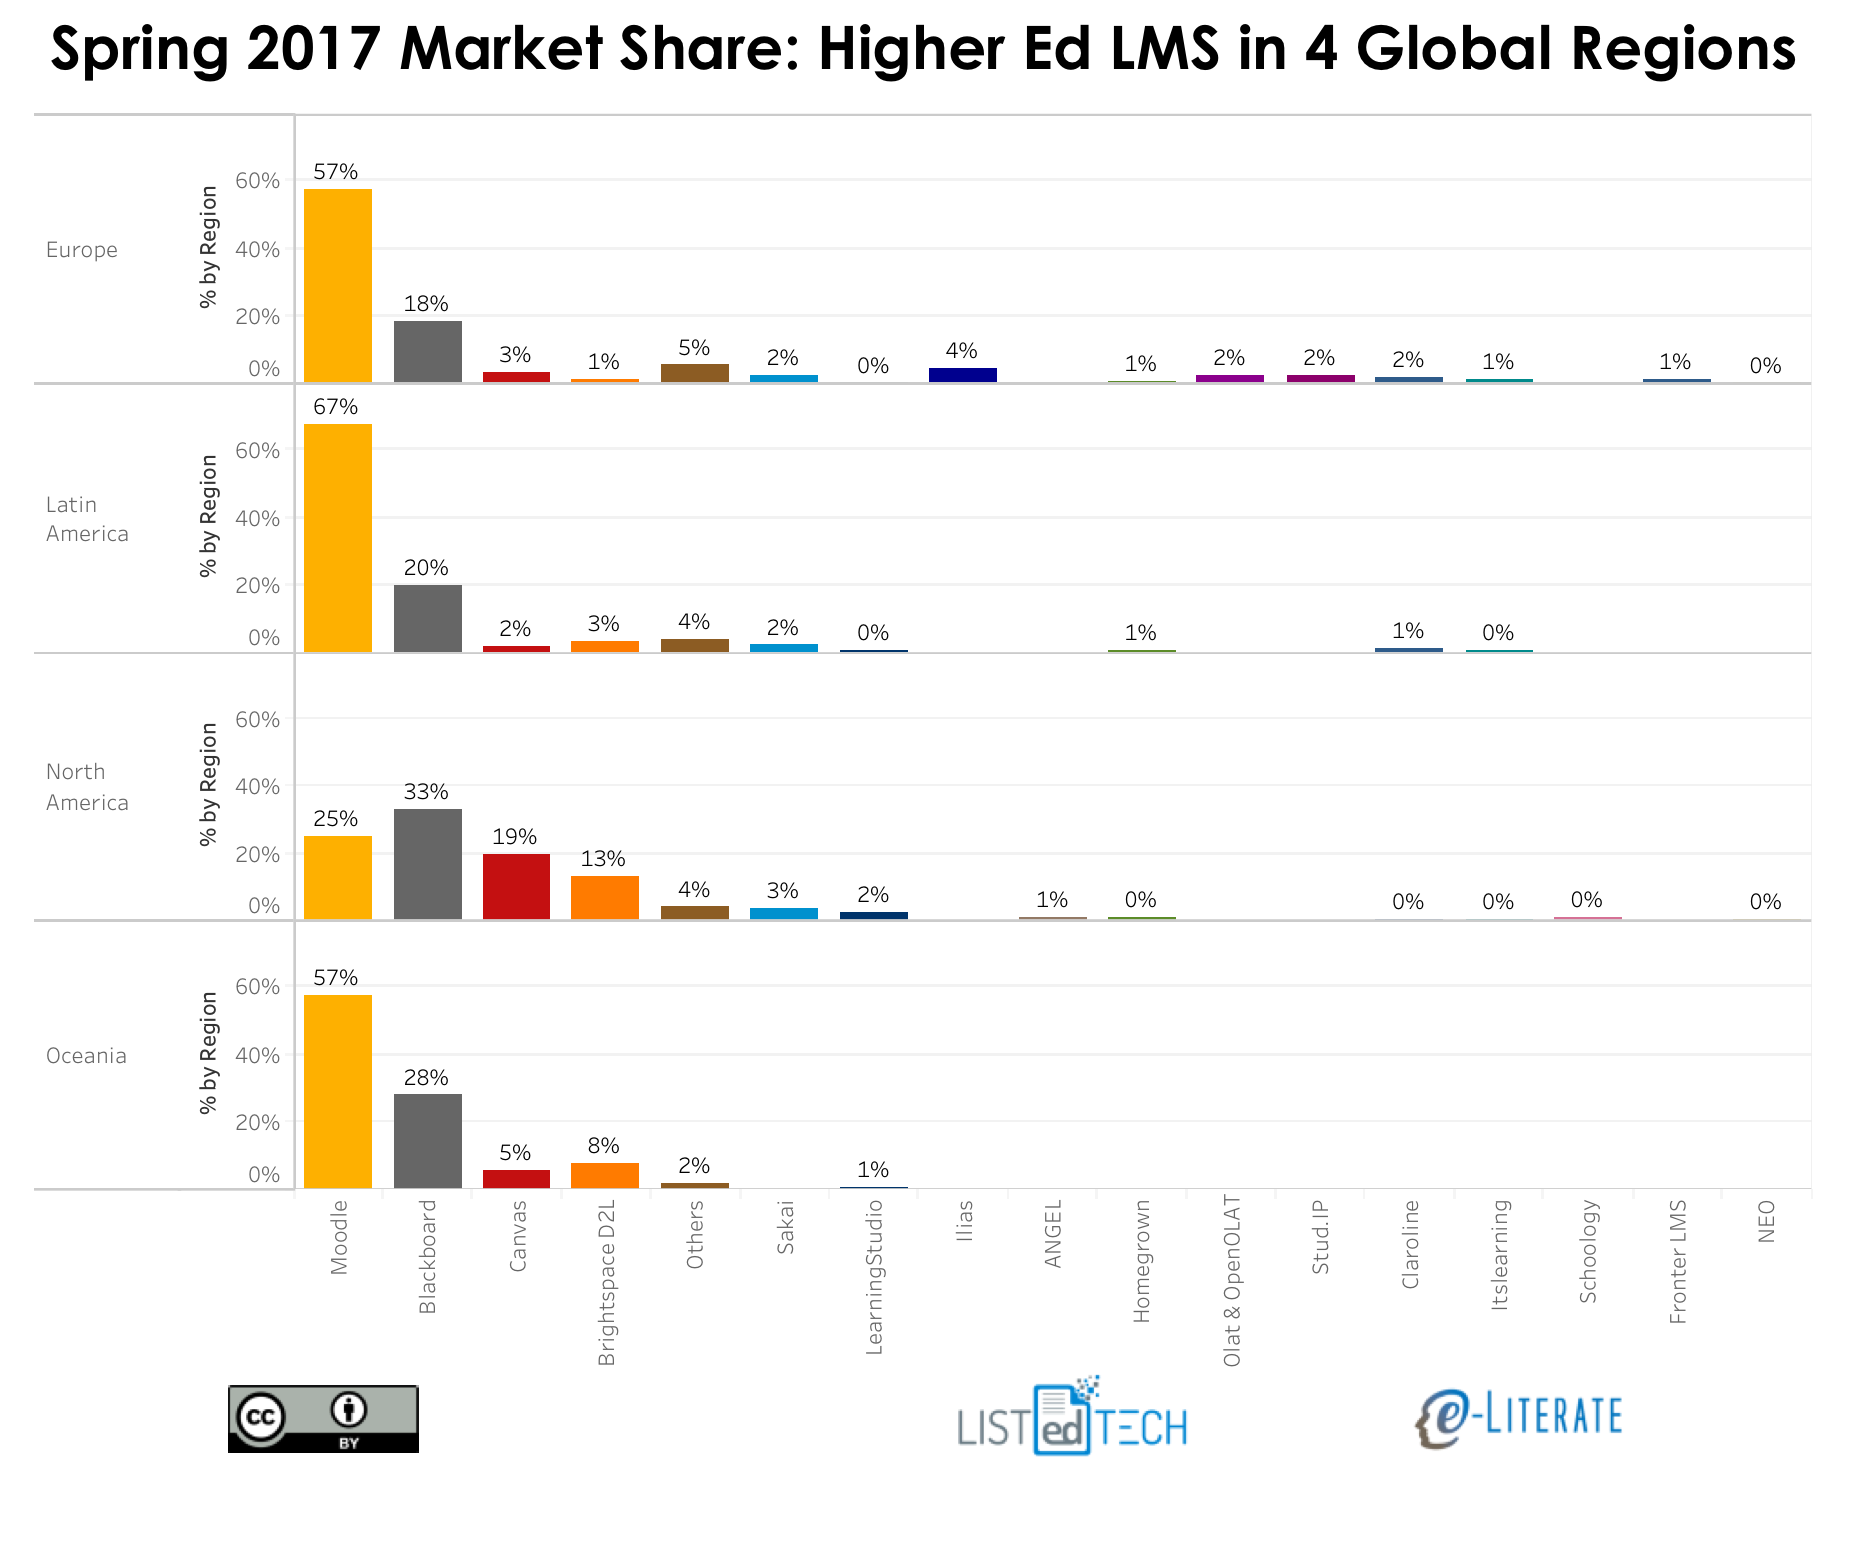
    One issue from the IHE post is that Josh used our 20% market share as basis for extrapolating Instructure’s market share, but that number is only for North American higher education. Globally, Instructure’s market share is much smaller as shown in our recent analysis (data provided by our partners LISTedTECH).

    Furthermore, while Canvas by Instructure and Schoology seem to be leading vendors for new adoptions in the K-12 market, at least in the US, no one has reasonable measures of market share in this area. Long and short – we need a different approach than extrapolation from Instructure alone.

    LISTedTECH estimated the global LMS market just in higher education as $1.7 billion based on (# of students) * (average cost of LMS per student) = annual spending approach. In the US, the best estimates I’ve seen in that K-12 learning platform markets are worth 30 – 40% of higher ed market. This likely is smaller globally, as anecdotally there is not a big emphasis on LMS usage outside North American and Northern Europe. So one very rough estimate is that academic LMS market is worth approximately $2 billion per year.

    If you want to use the company revenue method, then I would use additional data. Blackboard’s LMS revenue is likely $450 – $550 million per year based on reviews of corporate debt filings and extrapolation from their time as a public company. D2L’s revenue is smaller than Instructure’s, so let’s assume the two companies combined have $200 million revenue. Note that in all of these companies this is global revenue for K-12 and higher ed combined. The question is how to scale this $700 million combined revenue from all three companies. Is it reasonable that global spending for academic LMS could be 2 – 3x larger than this number? When you add in all of the Moodle hosting – both Moodle Partners and unofficial Moodle hosting – as well as Chinese market adoption, European providers, and K-12 players like Schoology and Powerschool/Haiku, this seems at least believable.

    So my highly-researched, thoroughly-documented estimate of the global academic LMS market is $1.5 – 2.0 billion per year. And it is forecast to grow to $8.2134526 billion by June 3, 2022.

    Note to investors – ignore that forecast.

  • InstructureCon 2017: Culture as a competitive weapon

    InstructureCon 2017: Culture as a competitive weapon

    In our recent coverage of BbWorld and D2L Fusion, Michael and I came away impressed. Both companies are improving and doing so in ways showing them listening to customers, empathizing, and developing product enhancements with more engaging user experiences. Both companies are doing so by attempting to change their company cultures to support these behaviors. Their challenge, however, is that Instructure is already there – their company culture has supported simplicity, customer-centric empathy, and openness from day one. And what struck me (again) at this year’s InstructureCon was how well the company is managed and how consistent is their approach, over time and throughout the organization.

    Instructure launched its Canvas LMS back in 2010, and it is remarkable how Michael’s description from June 2010 could still be applied today.

    If I had to summarize Instructure’s strategy in one sentence, it would be “They use the lessons learned by consumer web companies to clear the clutter out of LMS software design and business model.” They’re not focusing particularly on open education or analytics or any other hot topics in online education, although they are aware of these and do pay some attention to them. Rather, they are looking at core use cases and trying to make them as simple as possible, throwing out some outdated LMS design assumptions in the process.

    From the early days when they had dozens of employees to today, when they have over 1,100 employees, the strategy is the same and the company culture is the same. This despite the departure of both founders and the 2015 IPO and all the resultant pressure from investors.

    This is Instructure’s secret. They continue to manage the company to support the strategy of clearing the clutter out of LMS software design and business models.

    Product News

    The biggest product news at InstructureCon this year:

    • Release of Gauge, an assessment management platform for K-12 usage, which might impact higher ed in the future
    • Redesigned Quiz engine and Gradebook, leading to what we saw as the biggest interest from conference attendees
    • Release of blueprint courses
    • Investment in back-end platform design (e.g. microservices) to increase speed of design improvements
    • Reintroduction of analytics – visualizations initially targeted at faculty usage
    • Introduction of Alexa integration

    The focus on assessments, quizzes and grade books is both problematic and encouraging. Problematic for the industry as we spend too much time on measurements and grading and accountability and too little time on learning and continuous formative assessment. Yes, the quizzing engine can be used for formative assessment, but in most cases the usage is for summative assessment. But even with this viewpoint, it is encouraging that the primary focus of these product enhancements to Canvas is on reducing the time spent on the grading activities. It is a fact of life that an enormous amount of effort is spent by faculty, particularly in the US, on managing grades. It is good to see tools that directly reduce the pain in this area.

    In a standing-room only session, Instructure’s Christi Wruck explained the initial phase of a multi-year effort to redesign and improve the grade book. Most features shown were of the nature of reducing the number of clicks or simplifying the navigation of grading activities. I won’t go into the minutiae here, but this session seemed to generate the most excitement at the conference.

    The (re)introduction of analytics surprised me, as I had seen most public efforts in Canvas lately focusing on getting data out to let customers do their own analytics. The initial analytics in Canvas were introduced in 2012, and there were and are a few cool visualizations for faculty mostly, but there is little meat on the bones. There never seemed to be a real product strategy on the developing role of analytics within an LMS nor a full team to work on this challenge. In the meantime they rolled out Canvas Data, which we have talked to staff from several colleges and universities who are actively playing with and exploring the data. But this year Instructure described how they’ve been hiring a new analytics team and working on new visualizations. As with the previous effort, the initial focus is on helping faculty get a better view of how students are performing. We will have to watch this current focus on analytics to see if a real strategy develops.

    Blueprint Courses is a overdue features set to allow course design templates or components across courses or shared between instructors. This capability finally provides direct support for centralized course design models involving master courses and multiple course shells as typically used in large online programs. While this capability could be considered late, conference attendees seemed to be quite impressed with the design of the new features.

    Market News

    I shared in my post on D2L’s Fusion conference how their Brightspace LMS has made impressive wins recently, particularly for schools with large online programs. Canvas continues to gain market share and lead all competitors in new implementations (schools choosing a new LMS), but over the past 12 months they’ve allowed D2L to at least become a clear competitor.

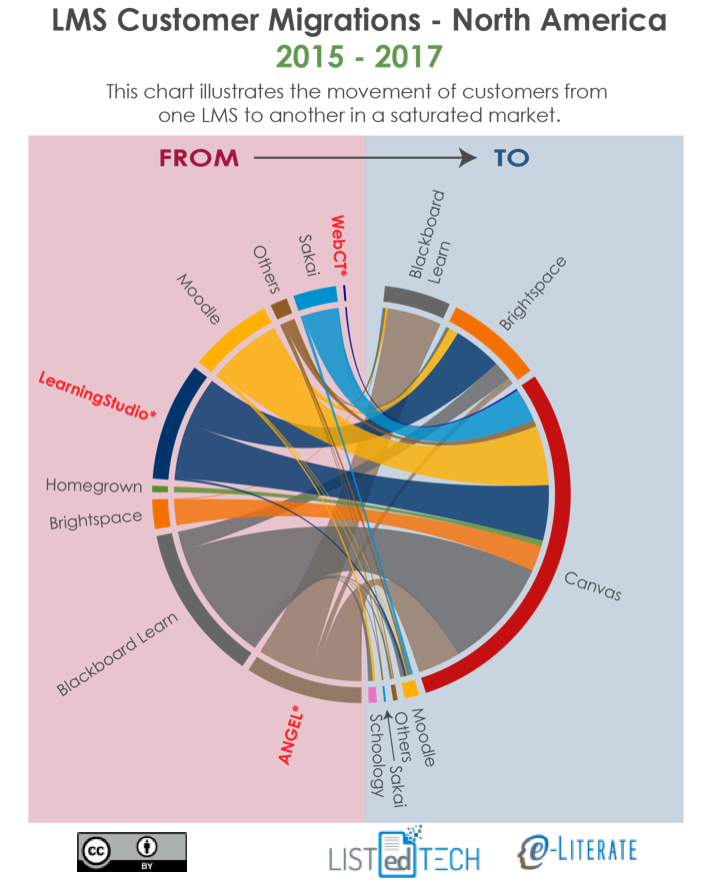
    Michael also shared a view from the North American (US and Canada) market for higher education showing that most of Blackboard’s “wins” over the past few years have come from ANGEL end-of-life migrations. Looking at that same image, however, it becomes even more obvious just how well Canvas has performed for new implementations. It is not just that Canvas has the lion’s share of new implementations, it’s also the breadth of migrations coming from Blackboard Learn, Moodle, ANGEL, LearningStudio, Sakai, and even several from D2L Brightspace.

    Instructure has recorded strong international grown in just the past two years, and this interest was evident at the conference. The most notable difference between the early users conferences and this year’s event was the expansion of the customer base. There must be similar numbers of K-12 attendees as there are higher education attendees, and we’re now seeing clients from Europe, Latin America, and Australia & New Zealand.

    Just 2-3 years ago Canvas as an LMS brand was virtually unknown outside of the US and Canada, but now Canvas is winning more than any others in North America, Europe, Latin America, and Oceania.

    Challenges

    Instructure certainly has challenges to face. In terms of market share, it will be very interesting to look at data for the end of 2017 to see if D2L has maintained its momentum in new implementations. And being a publicly-traded company, investors care not just that Instructure is growing but also whether Instructure is growing fast enough in multiple markets. That’s a lot of pressure.

    On the product front, Canvas was late to the game in terms of supporting mastery learning and associated competency-based education initiatives, although their introduction of MasteryPaths is showing some ability to catch up. Likewise, they certainly are behind their competitors in terms of learning analytics and associated research. And I would even say that they are late in supporting centralized course design models. In all three areas, there are initiatives introduced over the past 12 months to address these product needs. The challenge is for the company to catch up with competitors not necessarily in terms of full feature sets, but more in terms of supporting basic use cases and doing it well.

    When I asked various Instructure management at the conference whom they saw as their greatest competitor, the most common answer was themselves. The company knows they have work to do, and there is a real sense of “we have to do better” that permeates the company. For Instructure’s competitors, the good news is that Canvas has weaknesses. The bad news is that the company knows it.

    Back to Culture

    But the real event of InstructureCon is not really based on product news or market share. As Michael noted last year:

    Throughout the conference, I asked a number of attendees what percentage of their motivation for coming was to find out what the company was planning to develop in the next year. The range of answers averaged between 10% and 20%. They all told me that, while they were looking forward to the roadmap sessions later in the week, they didn’t expect any big surprises and weren’t all that focused on finding out what the developers had been doing. I have never been at an LMS conference where that was true, including Sakai conferences and Moodle Moots.

    Consider the Instructure company profile at Glassdoor. Last year the company was rated #4 best place to work for all small and medium-sized businesses, and Josh Coates was rated #15 for all CEOs in the same category. But also look at the video that Instructure management chose to include in the “Why Work For Us?” section. Other companies tend to put up platitude-filled dreck that tells you very little about their company. But Instructure puts up a 7+ minute video where they talk primarily about company values. In the video, they talk about the behavior the company does and doesn’t want – and even nods that they’ll get rid of people who have have these behaviors – and they avoid all the pseudo-inspirational messages.

    While Canvas is a market-changing platform, that is not really Instructure’s primary strength. Instructure as a company is the real strength.

  • LMS Revival: D2L picking up new customers and showing they can listen

    LMS Revival: D2L picking up new customers and showing they can listen

    D2L the company and Brightspace the company’s LMS are undergoing something of a revival in the past year. It’s not as if they have dropped in terms of market share – in fact the have a history of strong client retention, losing few customers – but the early 2010’s did not lead to rapid customer growth as they had expected after raising two rounds of a combined $165 million in 2012 and 2014. If you read that second post you’ll find that I stated that their growth claims “defied logic” at the time. Recently, however, D2L is on a roll, racking up significant client wins in higher education, and the company shows real signs of change and its ability to truly listen to and empathize with customers.

    As I sat down to write my analysis of the D2L Fusion users conference and what it meant to the Brightspace LMS, I noticed that several of the same themes I described last year applied to this year’s observations – just updated in terms of effect on customers and whether the changes seem to be sticking. To explain my current thoughts it is useful to start with commentary from last year.

    Update on Listening and Product Changes

    From last year’s post:

    As I have described to several executives at D2L, there is an interesting gap between the progress we have seen with the company’s product improvements and the reaction we hear from many of their customers. With the tighter integration with LeaP and the improved usability, particularly in content authoring, I would have expected to hear more customers react to the changes. But when talking directly to many of the institutions using the Brightspace LMS, staff describe D2L as if the company and product line had not changed in several years. What is not clear is whether this gap is due the company missing the mark (and my judgement of improvements not aligning with what colleges and universities want) or whether there is just a lag where it will take time for most customers to believe in and take advantage the new product designs and features.

    2016 has been an eventful year for D2L. [Chief Operating Officer] COO Cheryl Ainoa, a longtime veteran of Yahoo! and most recently Intuit, joined the company in April. Although this move was not advertised through press releases or even blog posts, I believe this is a significant change to how the company operates. [snip]

    And this gets back to the gap noted in the first paragraph. When I talk to people at schools migrating from D2L or considering whether to migrate, I do not hear much about the recent product changes or the new management described above. For several of these schools, the issue isn’t even whether they like or dislike the recent product and management changes, it’s as if these changes are a non issue in their decision-making. No conclusions yet, just noting the gap.

    What I noticed since last year are two updates to the above analysis.

    Listening – Besides adding a new COO, D2L has made several other executive-level hires in the product in the past two years, and to me it seems like we are seeing a new way of thinking largely caused by this new group. The interviews with executives were much more consistent than in past years, and there is a new focus on actively listening to customers. It’s not that D2L didn’t have conversations before; it’s more that they didn’t know how to truly listen and empathize.Part of this change according to D2L exec interviews was that in the past it was easier to talk to CIOs, but now they are learning how to talk to faculty and end users. All interviewees seemed to be singing from the same hymnbook. For the most part.

    Narrow but Excellent – The product focus is less on big-news features and more on small-news everyday items. In the past D2L has seemed too interested in being able to do some chest-thumping “We’ve got CBE. We’ve got Predictive Analytics. We’ve got Adaptive Learning.” while missing something on what current and even prospective customers need in their daily lives. The new focus is more on taking the drudgery out of end-user activities with a mantra of “narrow but excellent”. They are trying to fall in love with problem solving more than in features, even if these problems can be non-sexy.

    One example from the Fusion users conference was making it easier to shuffle questions within a quiz. Sounds trivial, but Canius College staff have a description that captures the essence of the change. Yes, you could have done this before, but it was a chore. Now it’s much easier to the point that more people will want to use it.

    Later this month, D2L will introduce a nice feature for Canisius faculty who use their online quiz/exam tool. D2L’s quiz engine has powerful features for randomizing question order in a quiz or exam, and can even deliver a subset of questions at random from larger question banks. This is nice, but until now it was a bit of a chore if you only wanted to randomize delivery of, say, five to ten questions, since you needed to install those questions in the question library, and then import them into a random section within the quiz. Along the way, there were a lot of clicks and the process wasn’t always so intuitive. With the update coming late July, D2L has installed a checkbox feature within the quiz editor: “Shuffle order of questions at the quiz level.” Simply add your questions directly in the quiz, click that box, and the quiz will deliver those questions in a random order to each student.

    The Brightspace product demonstrations during the conference keynote got significant spontaneous reactions from crowd (along with hallway discussions) likely reflecting this improved ability to listen
    to customers. And the improvement to quiz question shuffling led to one of the biggest reactions.

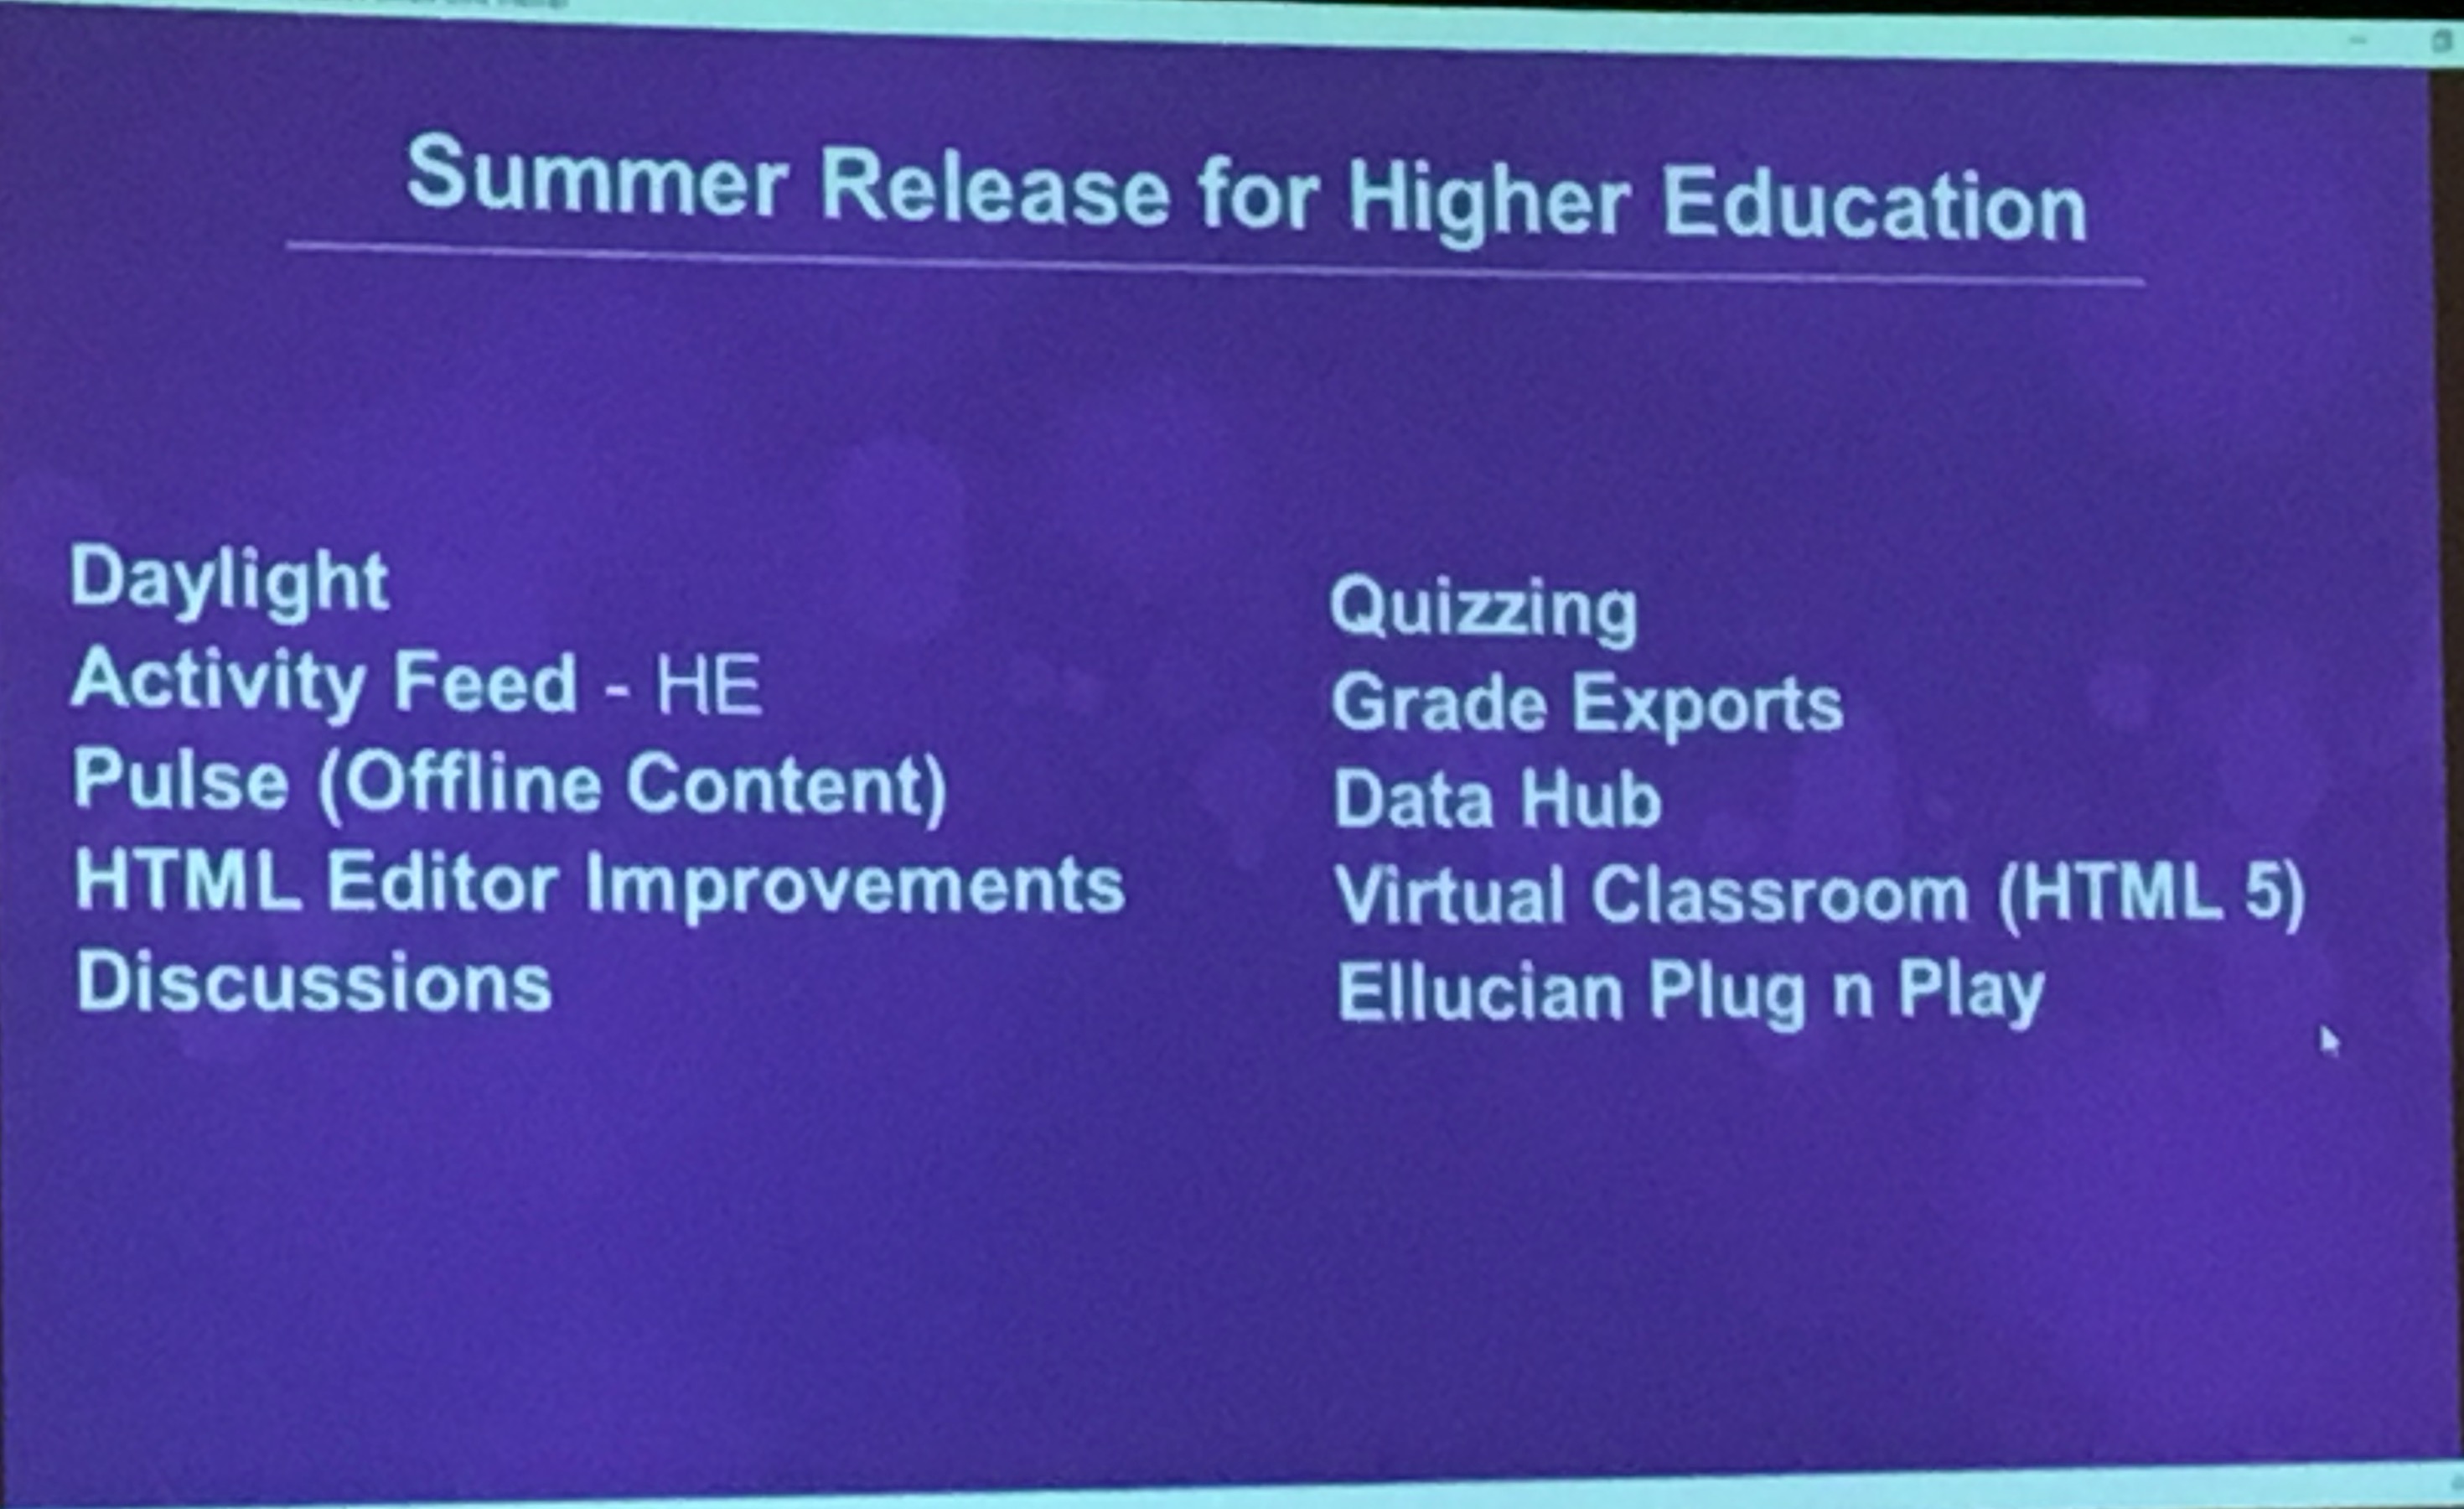
    Here are the major product announcements / new functionality as of this summer:
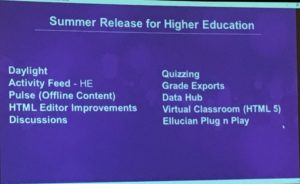
    Another product change worth noting is the new Data Hub. This is a re-architecture of how data can be exported to allow bulk access to data, either manual or through application program interfaces (APIs). The announcement is significant as we have noted in the past that D2L has had challenges getting data reliably and quickly to customers. Data export is not an easy problem to solve due to the complex technical challenges involved in analytics, and D2L had its share of customer challenges several years ago. However, we heard from at least one customer with early access to the Data Hub that their situation is improving. Sounds trivial, but this could be significant. We will have to keep a close watch on this development.

    Update on Market Share

    In last year’s post I noted:

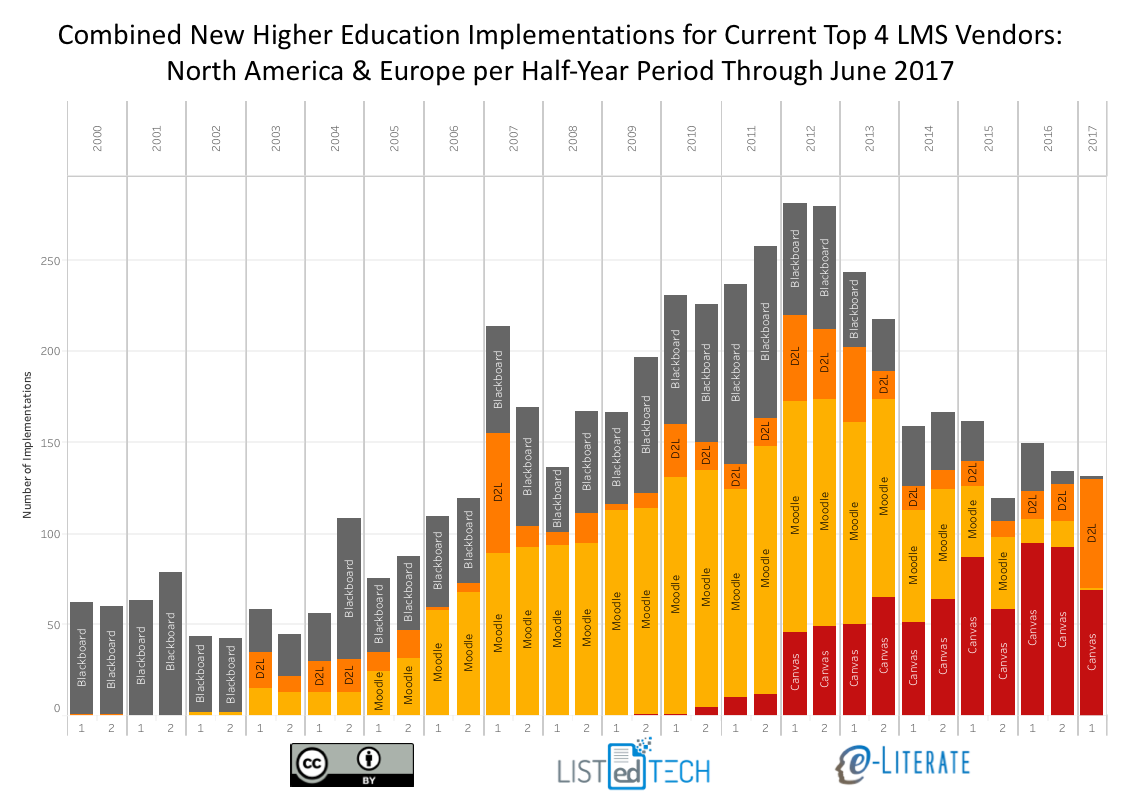
    On the sales front, D2L has experienced somewhat slow but steady growth in new US / Canadian higher education clients as seen below, but they have not had the big-name wins of the caliber of UMUC, Tennessee Board of Regents, University System of Georgia, as they had 2013 and earlier.

    They had won Kaplan University as of last year, but since then they’ve also won with EDMC, Saint Leo University, University of Cardiff, University of Ottawa, Bournemouth University, and most recently Southern New Hampshire University (SNHU), among others. In other words, over the past 12 months D2L has won several big-name accounts in higher education. ((Disclosure: I advised UMUC during their strategy and evaluation process in 2011-2012. Bournemouth, SNHU, and D2L are subscribers to our LMS market analysis service.))

    The net effect has been a dramatic uptick in the percentage of new implementations (schools switching from another LMS to a new one) for D2L. The following chart looks at new implementations in North America (US and Canada) and Europe highlighting the top four academic LMS solutions (Blackboard, Moodle, Canvas, D2L) in half-year increments, with a remarkable spike in D2L’s activities in the past 12 months.
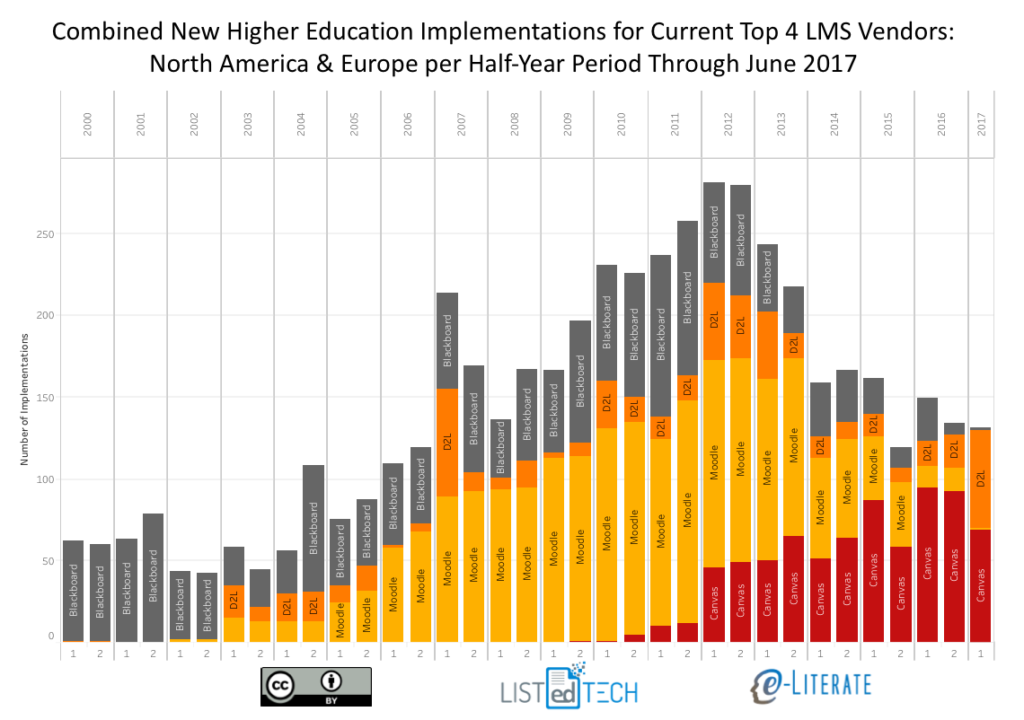
    This data aligns with our anecdotal conversations where, more often than not, there seems to be a pattern of new implementations going to Canvas or D2L – an emerging two-horse race for new implementations.

    Part of the reason for the recent acceleration and for the unknown future is the fact that quite a few of D2L’s wins for Brightspace have been large systems (single decision affecting multiple campuses, e.g. Kaplan University) or large enrollment single institutions (e.g. SNHU). And many of these are for schools with large, centrally-managed online operations. The large systems have benefitted from the Pearson LearningStudio (aka eCollege) end-of-life forcing many for-profit systems to change LMS, with that activity mostly running its course by the end of this calendar year. Big wins, but quite dependent on a small number of deals.

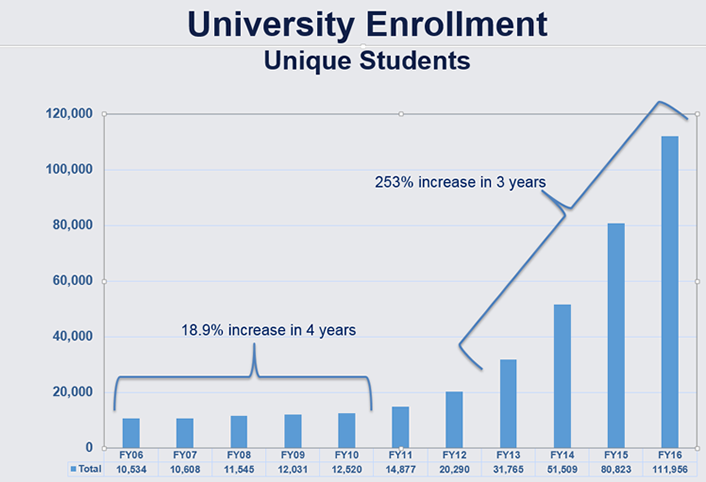
    The recent win at SNHU is very important to understand, however. It is not driven by end-of-life (SNHU moving off of Blackboard Learn in a voluntary migration), and this comes from a long-time Blackboard customer. Quite often people equate SNHU with its College for America (CfA), one of the leading competency-based education (CBE) programs in the country. But SNHU is much bigger than CfA, and it is the fastest-growing university in North America overall. According to an article last year in EDUCAUSE Review, SNHU’s online enrollment has grown at 253% per year over the past several years.
    It certainly seems probable that this increase in market wins is related to the change in how D2L listens to customers and the resultant change in emphasis from big-news capabilities towards smaller-news but customer-pleasing improvements to everyday functionality. It is important that Brightspace has such a deep feature set, but have the company understand customer everyday needs is more important.

    What we do know is that D2L has increased its number of higher education wins over the past 12 months. What we don’t know is whether and how strongly this trend will continue.

    Update on Conference Attendance

    This was the first on-site Fusion visit we’ve had in a couple of years, leading to the title and commentary in last year’s post “Changes at D2L: A second-hand view from users conference”:

    The reason I titled this post as a second-hand view is that D2L is the only major LMS provider (and I include Moodle and Sakai here) that discouraged our participation in their users conference (and we did not attend), citing concerns over direct conversations with attendees without getting their permission first. Other providers are happy to allow and even encourage this type of interaction. In the nature of full disclosure, we think it is important for the reader to understand this difference in access.

    Michael and I value the ability to not just hear official presentations and get in-depth demos, but to also go, roam, and talk to customers.

    True to their word, D2L management have changed their approach on how analysts can be involved in their conference. This year we were invited to attend (along with others), and more importantly, we were allowed to freely talk to the users and prospective users at the conference. I even had several people from D2L pass me in the hallway and ask if I was getting the access to customers that I needed. I did.

    This change aligns with the aforementioned improvements and focus on how D2L as a company listens to customers. Less control and more desire to learn (sorry, couldn’t help myself). A welcome change.

    Open Questions

    While most of what we’ve seen in the market and at the conference has been an improvement over the past few years, it is important to understand the tall order of the changes being made.

    Learning to listen, especially to end users, really represents a cultural change, and these changes are not easy. They take a lot of management time and energy to implement, and they take patience. Will these changes take hold and further permeate the organization? Certainly we’re seeing results over the past 12 months, but companies have plenty of pressures to fall back into old habits.

    In terms of market positioning, the competition is not standing still. We’re also seeing improvements coming from Blackboard’s change in executive team, and we’re seeing Instructure to continue their strong improvements to Canvas and their support. New entrants like Schoology and older solutions like Moodle are also improving, albeit more slowly than the big commercial vendors. Further complicating the matter, a lot of D2L’s new business came from a handful of large decisions. Will D2L’s market momentum of new implementations continue, particularly in North America and Europe? I expect we’ll learn a lot when we look at the data at the end of this calendar year.

  • Google Classroom: Isolated adoptions for higher education institutions

    At last month’s Future Trends Forum hosted by Bryan Alexander, I received several questions around the intersection of K-12 and higher education markets for learning platforms. A condensed version of my answer is that the mainline LMS vendors are seeing increased overlap (Canvas, D2L Brightspace, Blackboard, Moodle, and Schoology in particular), but that there was little overlap when it comes to the teacher-oriented Big Classrooms (Google and Facebook).

    Three years ago when the buzz over Google Classroom was at its peak, I wrote several posts looking at the platform, ultimately concluding in the post titled “Why Google Classroom won’t affect institutional LMS market … yet”:

    None of this argues that Google Classroom is an inferior tool – it is just not designed to replace the full-featured LMS. Remember that Google is a technology-vision company that is comfortable putting out new tools before they understand how the tools will be used. Google is also comfortable playing the long game, getting more and more instructors and faculty using, giving feedback, and pushing forward the new toolset. This process will take some time to play out – at least 2 or 3 years in my opinion before a full institutional LMS may be available. If Google like the direction Classroom usage is going.

    Subsequently, Google has addressed some of the gaps in the product, including a programming interface that could allow deeper integration with student record systems used at higher ed institutions.

    We’re now 3 years down the road from the initial analysis – has Google Classroom started to be adopted as a full institutional LMS?

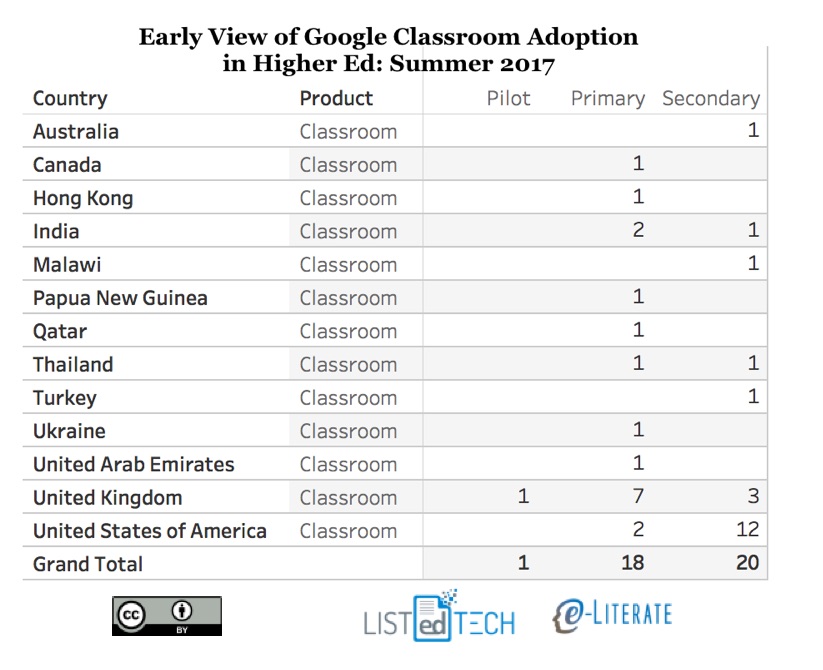
    Our partners at LISTedTECH have performed an initial analysis on this question. We do not yet have full data coverage in the same fashion as our LMS market analysis, but this early view should give some insight into higher ed adoption of the platform.

    For this initial view, we are looking at institutional adoption. Where a school supports Google Classroom as their primary or secondary system. There are plenty of other cases where individual faculty choose to use the platform in an unsupported manner.

    Notes from initial view:

    • A lot of the interest seems to come from developing countries where the education budgets are quite low. Malawi, Papau New Guinea, etc.
    • For the United Kingdom, the number is artificially high as 5 of the institutions are all part of Warwickshire College Group (a collection of Further Education colleges). Nevertheless, the UK has the higher number (so far) of institutional adoptions.
    • The usage of Google Classroom as a secondary system makes sense – an alternative platform that doesn’t have all the features and integrations typically needed for primary system usage – but there are cases now of primary usage.
    • In the US, the most notable adoption is the California University of Management and Sciences, a Student and Exchange Visitor Program (SEVP)–certified institution in Anaheim. They support both Moodle and Google Classroom for primary LMS usage.
    • While we don’t have comprehensive coverage yet, it appears that there are some isolated cases of Google Classroom institutional adoption in higher education. The platform is still not a true LMS competitor, but we’ll keep watching.
  • Academic LMS Market Share By Enrollments, Part Deux

    Academic LMS Market Share By Enrollments, Part Deux

    Based on our recent publication of market share data and graphics, we have had multiple requests to share similar data by enrollment. In Friday’s post I shared a non-traditional view of the LMS market based on the percentage of institutions within small, medium, and large enrollment bands for North America (US and Canada) and Europe. This view gave some interesting insights, particularly with large positive correlation (Canvas) and negative correlation (Moodle)  between enrollment bands and market share in North America. Meanwhile, there were other LMS solutions (D2L and Sakai in particular) that have fairly consistent distribution in market share.

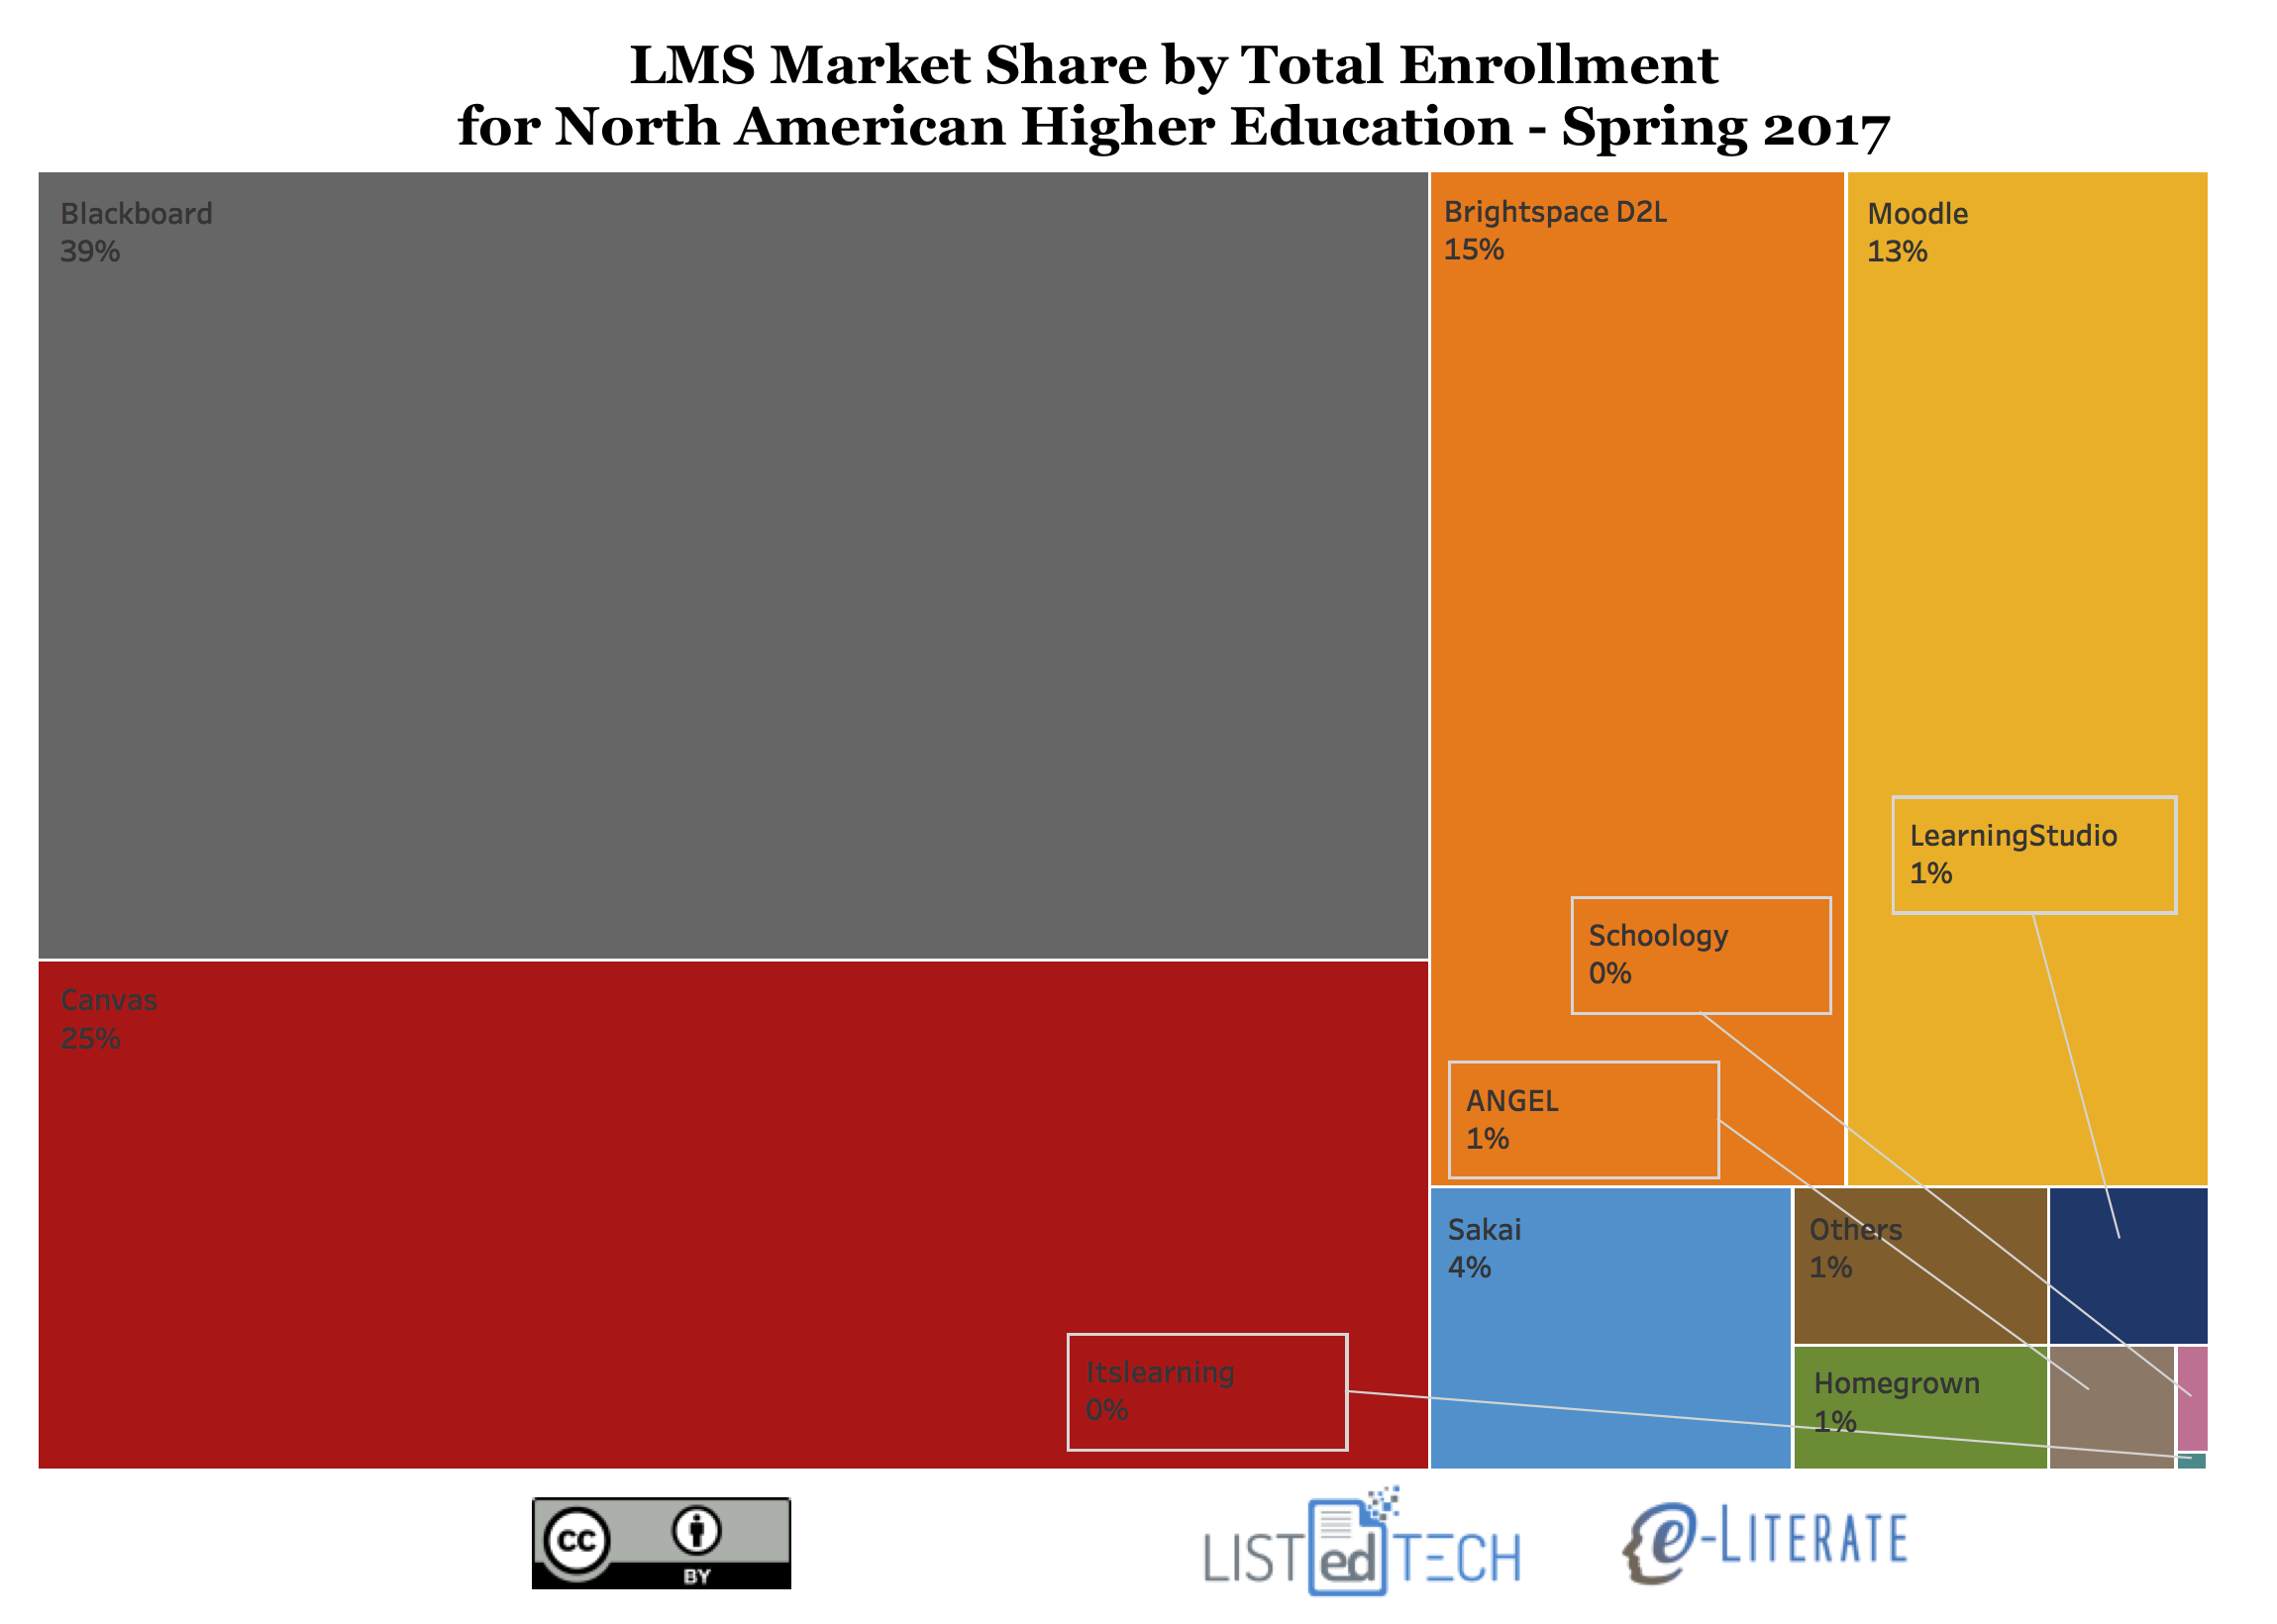
    For this second view, instead of showing percentage of institutions within each enrollment band, the data is aggregated for all North American institutions and scaled by each institution’s official enrollment data (e.g. the US data is from IPEDS). The net result shows the percentage of enrollments across the region that have different LMS solutions as their primary system at their school. As always, the underlying data for these market share studies is provided by our partner LISTedTECH.

    Some Notes:

    • For North American Higher Education, Blackboard Learn at 39% is still in first place, Canvas is second at 25%, D2L Brightspace is third at 15%, Moodle is fourth at 13%, and Sakai is fifth at 4%.
    • It has been widely reported when just looking at percentages of institutions that Moodle has long been the second most-used system in North America, but in this view both Canvas and D2L Brightspace have a larger market share.

    It is useful to look at different views using institutional and enrollment metrics to get a deeper understanding of the academic LMS market dynamics.

  • Academic LMS Market Share By Enrollments, Part I

    Since the earliest days of Campus Computing and EDUCAUSE measurement of LMS market data up through recent analysis by Edutechnica and LISTedTECH (the latter our partners for the LMS market analysis service and data behind our LMS graphics), the most common measurement used has been “number of institutions adopting system X as their primary LMS”. But that is only one view, and like any view it has limitations. Sweet Briar College with 900 students is treated with the same metric as Ohio State University with 55,000. I’m sorry, The Ohio State University.

    Based on our recent publication of market share data and graphics, we have had multiple requests to share similar data by enrollment. Both Edutechnica and LISTedTECH have provided such views here and there in the past, but given our recent analysis expansion along with LISTedTECH to cover non-North American regions, we thought it would be worth sharing LMS market data based on enrollments.

    What we cannot do is look at how many students actually use the LMS. But for North America (US and Canada in this case) and Europe, we have sufficient coverage of official enrollment figures that we can scale each institution by its enrollment data. This is how most LMS companies determine their prices for each school, so it is a much better measurement to correlate with market revenues. Not a perfect measure, but a better one.

    In addition, this view gives additional insights into the market and likely future direction of the LMS providers.

    Hey Phil, will you just get to the damn graphics? Let us judge the importance.

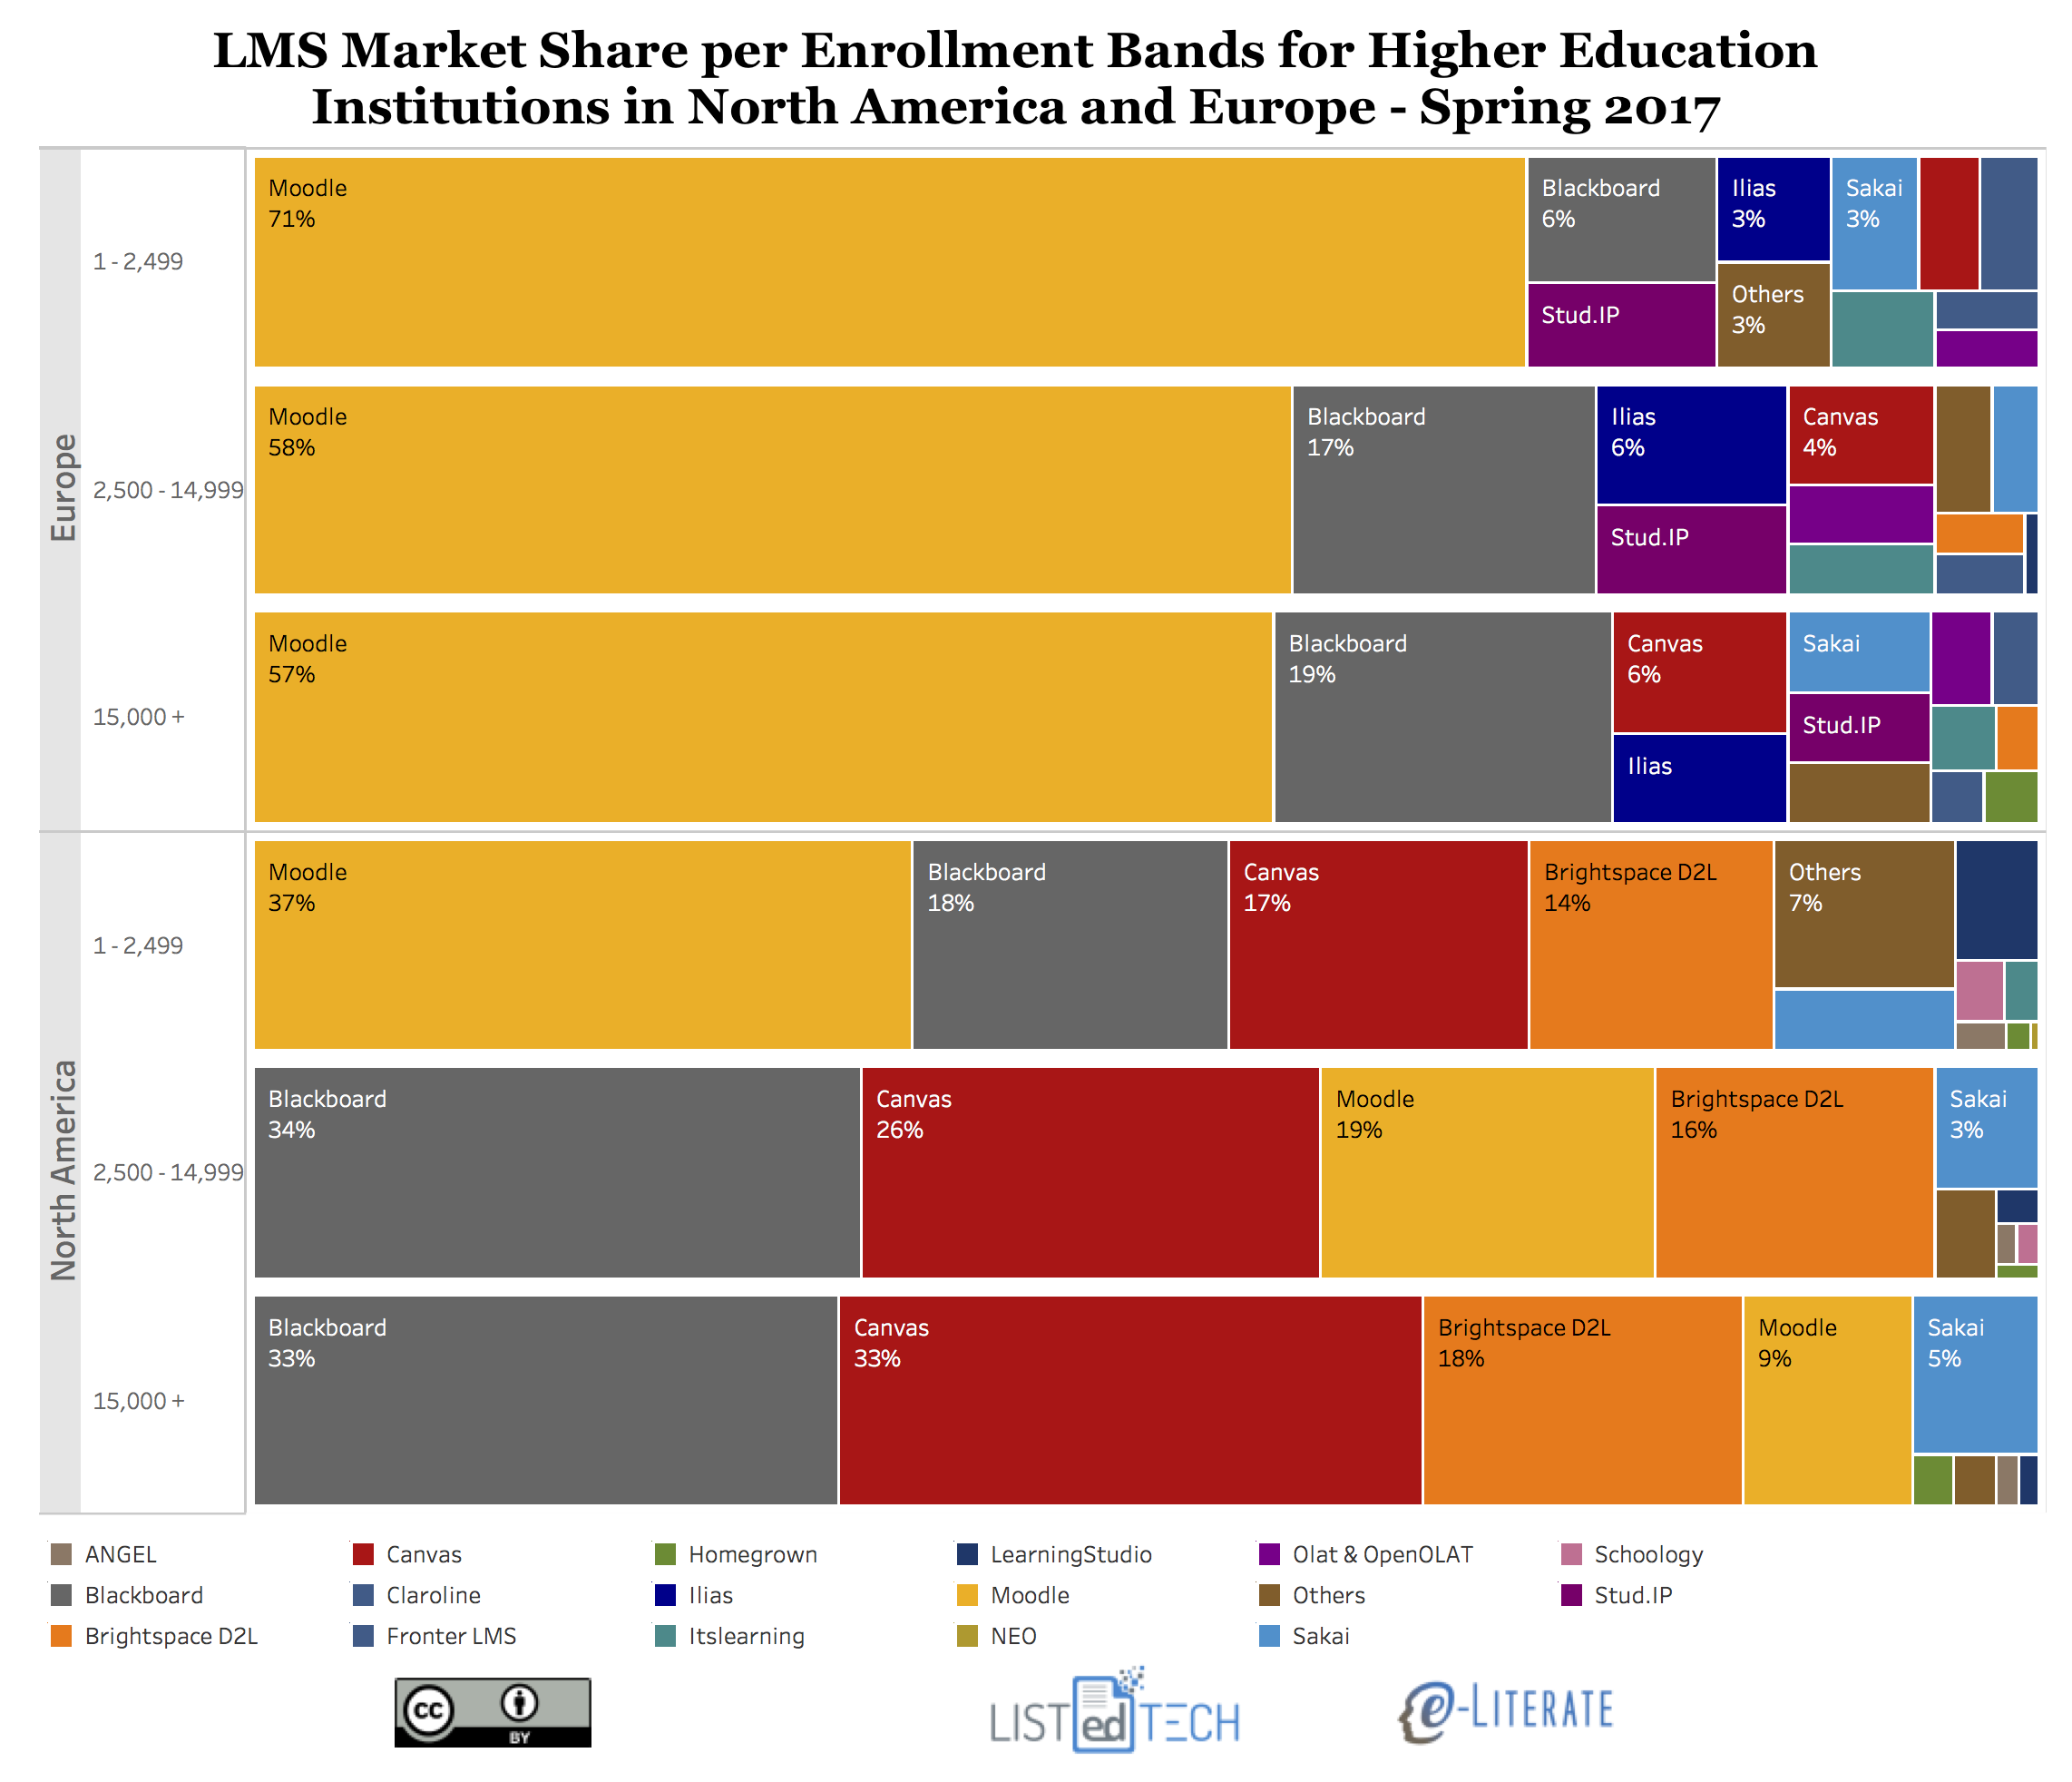
    OK, OK – for our first view, we group all institutions into separate bands of total enrollment and show market share for each band for each region (North America and Europe). Percentage of institutions adopting each LMS within each enrollment band of Small (1 – 2,499), Medium (2,500 – 14,999) and Large (15,000+) enrollments. Update: Clarified language.

    Some Notes:

    • The LMS with the greatest enrollment variation is Moodle, particularly in North America. For small schools below 2,500 students, Moodle is #1 at 37%, but for medium schools it’s #3 at 19% and for large it’s #4 at 9%. A huge difference. In Europe, Moodle market share also inversely correlates with enrollment but to a far smaller degree (71%, 58%, 57%) and it is still #1 in all bands.
    • Blackboard Learn and Canvas vary in North America the opposite direction – larger enrollment sizes equals larger market share – but not quite as dramatically as Moodle’s inverse relationship. Blackboard is #1 with roughly 33% market share for both large and medium institutions but is #2 with 18% for small institutions. Canvas goes from 33% for large to 26% for medium to 17% for small institutions. And note that Canvas and Blackboard Learn are virtually tied for first place for large institutions in North America.
    • D2L Brightspace has the most even distribution, with 18% of large, 16% of medium, and 14% of small institutions. That’s interesting.
    • In Europe, the overall distributions are more consistent with less variation between enrollment bands. While Moodle has smaller market share for larger enrollment bands, the general shape of the market does not change that much – just scaled a bit and with minor variations.
    • In what might be a surprise given its roots in larger research universities, Sakai (like D2L) has a fairly even distribution and similar market share across small, medium and large institutional bands.

    Coming soon – combining data not in enrollment bands but as scaled by each institution’s enrollment numbers.

    Update: See second post here.