e-Literate

Present is Prologue

Author: Phil Hill

  • Response to MoodleNews: Some considerations for critical reading of market sizing claims

    Response to MoodleNews: Some considerations for critical reading of market sizing claims

    There is an interesting post at MoodleNews titled “Open Source LMS Alive And Well: Moodle Breaks World Higher Ed Records, Tops North America, Grows Everywhere” looking at some of our recent LMS market data, focusing primarily on what the data reveal about open source systems such as Moodle, Sakai, Claroline, and Chamilo.

    Open Source LMS Alive And Well Moodle Breaks World Higher Ed Records, Tops North America, Grows Everywhere

    We welcome the usage of our data posted at e-Literate for these purposes, ((That’s why the blog is available for use under a Creative Commons Attribution license.)) but there are some misunderstandings evident in the MoodleNews post that we see too often in critical readings of market sizing reports. Unfortunately the misreadings can cloud otherwise valuable analytical reporting.

    The latest e-Literate report on “active LMS” shows Moodle as the incontrovertible LMS leader in global Higher Ed for primary and secondary systems, including North America.

    Incontrovertible seems quite strong, and we at e-Literate try to be very careful in our language and we rarely use words like incontrovertible or unequivocal. ((For the record, in the 14 year history of e-Literate, the former has been used one time and the latter five times.)) The reason is that for most people reading the data is a translation exercise. There is a need to understand the level of confidence the reader should have and what the limits of the claims are.

    It is useful that MoodleNews called out the global nature of data and measure of primary and secondary systems.

    Assuming it uses data provided by self-reporting service LISTedTECH from the last month, it shows dominance in every region, unsurmountable everywhere but the US, and healthy growth rates. The report mentions the “LMS long tail” as well as “the Big Four” (Moodle, Blackboard, Instructure Canvas and D2L Brightspace) but by their own accounting a more accurate distinction would be “the big one.”

    The data set used from our partners LISTedTECH is not a self-reporting service. Read this post for more information on the multiple channels of data collection used.

    But unsurmountable comes out of the blue. The whole point of doing reports like we do is that we don’t know for certain what the future trends will be, and we gather the data to reduce uncertainty. A while back, many would have said that Blackboard has an insurmountable dominance in North America, but we have seen major changes that would have made those claims invalid.

    I can see the argument for describing Moodle as “the big one” as an alternate description to “the Big Four”.

    LISTedTECH sample (apparently totaling 12,879 active LMS) lists 1,419 active Moodle sites in Higher Ed for North America, self-acknowledged as their most complete dataset. It appears that the advantages in Canada compensate for Instructure Canvas’ growth in the US. In July, it had listed 1,000 sites only for Higher Ed in the US.

    The first sentence is a good example of characterizing the data in a useful way, as it gives the reader a sense of the data set while also clarifying usage in a specific global region.

    Unfortunately the article then jumps into some confusing claims based on misreading the data descriptions. The June 2017 post captured percentage of primary systems at degree-granting institutions for each of four global regions with North America = US and Canada combined, the July 2018 post captured primary LMS in … US colleges and universities, and the August 2018 post captured total counts of both primary and secondary system usage in six global regions. We chose this latter method for the August post due to the frequency of long tail and open source LMS systems being used as secondary systems (i.e. some other LMS is the campus standard, or primary system). There is little basis for concluding that Moodle’s advantages in Canada compensate for Instructure Canvas’ growth in the US.

    The larger point here is that there are lots of ways to slice and dice data that end up with similar-lookinggraphs that represent different things – it’s important to read the legends and surrounding text carefully. To give a sense on the issue of primary vs. secondary systems  for North America, consider the difference shown below. ((Graphic shown as clarification, not present in articles referenced by MoodleNews.))
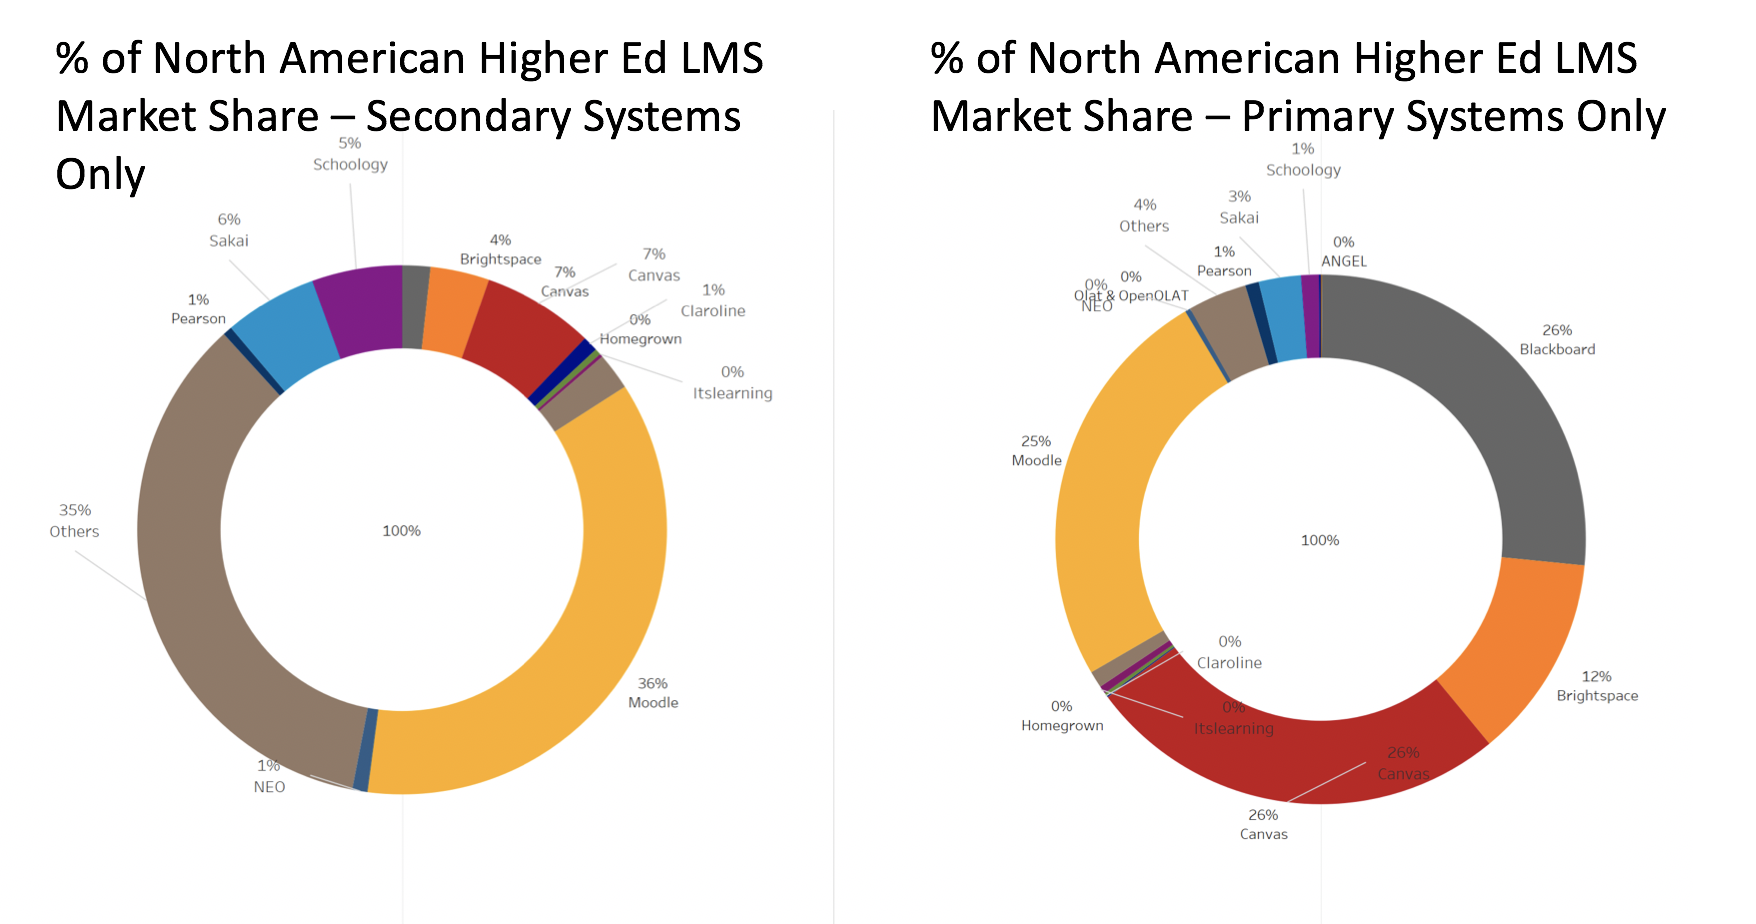
    With MoodleNews’ natural focus on Moodle, it would be accurate to note that Moodle is used quite frequently as a secondary system.

    For comparison, official stats at moodle.net set the total figure at 11,490 as of writing. 9,776 for the US, the biggest Moodle nation; 1,714 for Canada. Moodle does not offer discriminated site data for Higher Ed only.

    This is a helpful comparison and description with a different data set.

    Unfortunately, I need to be careful with further quotations. MoodleNews does not use a creative commons license and clearly limits usage based on the site’s terms of use. So the remainder of this post will have to be limited to short descriptions.

    There is a useful section looking at Moodle’s shares in six different global regions. The main caution I would add comes from our November 2017 post describing the data.

    Market share information provided in percentages and trends are more reliable than absolute counts outside of North America. When we do provide absolute numbers, we advise caution for readers or subscribers to not over-interpret the absolute numbers, at least without us providing additional details to keep the data in context.

    But in this case, MoodleNews also included the percentages for each region, which is helpful.

    The next four paragraphs all focus on market trends (year over year comparisons) that cannot be supported by the data (see above).

    At the end of the MoodleNews post, there is some valuable commentary about other (non-Moodle) open source LMS system and the origins and deployments across various regions.

    Given these clarifications, I would also add the the MoodleNews title has some serious flaws.

    All-in-all, it’s good to see valuable discussions spawned from our CC-BY licensed posts. But readers should be cautios when trying to understand market sizing data and make comparisons and trends analysis carefully.

    Update 8/26: Please see comment from Martin Dougiamas clarifying that MoodleNews “is not associated or affiliated with the Moodle organisation in any way”.
  • D2L Fusion 2018: Product improvements and potential signs of addressing challenges

    D2L Fusion 2018: Product improvements and potential signs of addressing challenges

    This year’s D2L Fusion conference in Houston carved out a space somewhere between the carnival atmosphere of InstructureCon in Keystone and the subdued feel of BbWorld in Orlando (note: we plan another post on each of these conferences to share more details of our observations). This  was the perfect note to hit for where D2L is in its evolution as an educational technology company. A number of things seem to be falling in place for D2L ((Disclosure: Blackboard, Instructure, D2L, and Schoology are subscribers to our LMS Market Analysis service. Blackboard, Instructure, D2L, and Pearson are sponsoring participants in our Empirical Educator Project.)) with its LMS product, but we will have to see if the recently expanded management team will be able to address the ongoing challenges that D2L faces with customer experience and expectations.

    Like Blackboard and Instructure, D2L is in the middle of a transition partially driven by financial considerations. In D2L’s case, the issue is that the two rounds of $165 million aggregate funding in 2012 / 13 lead to expectations of larger market gains. In August of 2017 we shared that “D2L is on a roll, racking up significant client wins in higher education, and the company shows real signs of change in its ability to truly listen to and empathize with customers.” Two months ago we described D2L’s concerted effort to move customers to the cloud and some promising improvements surfacing in the new Daylight user experience. Despite these improvements, however, D2L has lost some marquee customers such as the University of Wisconsin system to offset some of the wins, and the company has remained steady or made slight gains in North America, European and Latin American LMS market share.

    At D2L Fusion, our goal was to get a better read on how actual customers and prospects are reacting to the cloud deployment move and streamlined user experience that we have observed. A second goal we had was to get a better sense of whether D2L will be able to improve its customer service and delivery on promises made to customers.

    Reactions to Cloud and User Experience

    From customers we spoke to at D2L Fusion, the value of the move to the cloud as well as user experience improvements have provided breakthroughs. On the cloud front, D2L now has upwards of 98% of their customer base either hosted through Amazon Web Services (AWS) or in the company’s data centers.  According to a company spokesperson, 55% of what they describe as cloud implementations are hosted by AWS, the remainder by D2L in their leased data centers. All new implementations moving forward will be hosted by AWS and by fall 2019 D2L estimates that nearly all implementations will be on the AWS infrastructure. This will be a significant achievement for a legacy on-premises software provider to make this transition. From our June post:

    D2L has long worked on managed hosting options, but in late 2013 the company introduced Continuous Delivery where software releases are pushed to customers incrementally, such that customers would jointly run the latest versions of Brightspace, their LMS. This move is important, as one primary benefit of cloud deployment is to remove the explosion of software configurations and versions that make it expensive and difficult to diagnose and fix bugs and to release new features.

    Three years later in 2016 D2L announced their move to AWS for cloud deployment.

    At Fusion 2018 we saw a continuation of this strategy, and we heard largely positive reception from customers and prospects, and we are not hearing the grumblings from customers as was evident in late 2016 / early 2017. We should also note that this move to the cloud is more aggressive than that being made by Blackboard and Learn SaaS, but more on that in a future post.

    As for the new user experience and recent changes in product design, it’s useful to first establish context for what’s been happening internally at D2L. About three years ago D2L brought in a new chief operating officer, Cheryl Ainoa, and a new VP of Product, David Koehn. One of their goals was to turn the product development process on its head and, drum roll, put the users first. This means engaging with users, listening to users, understanding their problems and viewing them as partners in the effort to deliver better software. It also means solving the small things that annoy users on a daily basis and shifting away from feature releases as the key metric of progress. For companies that have been engaged in agile methodology and iterative development, this likely sounds basic. For D2L, it was a fundamental cultural shift in how development is done. At this year’s Fusion, we are seeing concrete signs that change has taken root both with the company and with customers.

    Daylight Experience is the name for D2L’s redesign of its streamlined user interface. When it was first announced in early 2017, we were somewhat skeptical as the initial changes were evident in different fonts and cleaner look-and-feel but not significant improvements in the workflow for faculty and students.

    As time goes on and we see more advanced demos, our view is changing. The Daylight Experience does have some real improvements not just in look-and-feel but in fewer and more intuitive clicks to get the same job done. A major focus on the Emerald Release this summer (in time for D2L Fusion users conference) is more fully encouraging usage of the activity stream for higher ed clients (this feature was initially targeted at K-12 market but has been adapted for colleges and universities).

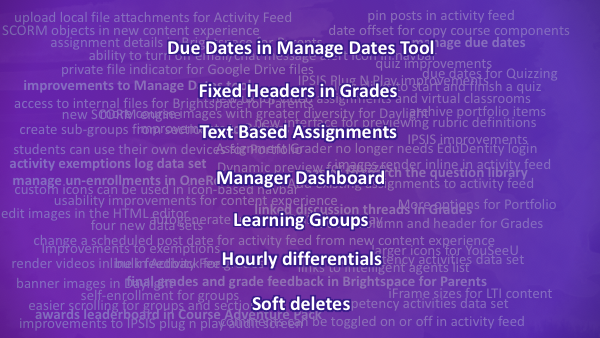
    The product showcase slide that arguably got the most enthusiastic response from the crowd was the one that focused on the small changes that users had been clamoring after for years – things like “Due Dates in Manage Dates Tool”, “Fixed Headers in Grades”, “Learning Groups”.

    New features from D2L Fusion conference

    These are not sexy, headline-making announcements, but they matter to users. D2L has long been viewed as a platform for people and institutions that like to have a lot of control over how to configure and run an LMS; however, the breadth and complexity of options often came at the expense of an intuitive user experience. While D2L has had a solid product for a sub-set of the market for years, they have had difficulty being viewed as ‘intuitive’ or ‘easy to use’, at least since the advent of Canvas and the resultant change in user expectations. The streamlined design afforded by the Daylight Experience, and the progressive disclosure of more advanced features, could change this situation if they’re able to get it in front of potential customers for a serious look.

    Customer Experience and Expectations

    On the second question regarding customer service and delivery on promises there are several reasons to be upbeat, but also reason for concern. Several new customers we spoke with, from Europe, Latin America and North America, all spoke about “partnership” as being a key reason for their choosing D2L over the competition. During lengthy procurement processes, these institutions got the sense that D2L was eager to engage and work with them to achieve their goals with broad service offerings as well as an eagerness to shape product development to suit these new clients.

    That said, D2L has a mixed record on follow through. A number of sources we have spoken with over the past 6-12 months have discussed a pattern of the company over-promising and under-delivering when it comes to implement promised changes. For example, these sources have told us they went into the relationship with this same expectation of a partnership, of having a voice in product direction, only to find out they are having trouble getting D2L staff to respond in a timely manner. It is not clear yet on how prevalent these concerns are, but we do believe they will need to be addressed in order for D2L to make material changes in overall market share.

    D2L has made two key hires in recent months, seemingly in recognition of potential market opportunities as well as persistent internal challenges. One targets growth, the other customer satisfaction. Puneet Arora, a former sales executive with several SaaS companies, has been brought in as chief revenue officer, and April Oman, a veteran customer success executive with a number of enterprise software companies, has been added as as Senior VP of Customer Experience. Arora is new to the education space but seems to be asking a lot of the right questions, and his task is to grow the user base in a meaningful way. Expect to see some changes in how D2L positions itself and who they try to sell to, shifting the balance away from administrators and towards faculty and student end users. Oman’s role is a new one and speaks to the need to develop a stronger relationships and partnerships with customers. This will be critical as D2L tries to establish themselves as much more than a software solution and as they attempt to improve customer experience.

    Better Position but Needing Results

    The center of gravity of D2L’s executive team is more diffuse than it used to be. Much of the longer-tenured leadership of D2L is based out of the Kitchener, Ontario home office: John Baker, CEO; Nick Oddson, CTO; Melissa Howatson, CFO; Jeremy Auger, SVP Strategy; and Ken Chapman, VP of Market Research. Ainoa, Koehn, Arora, and Oman (the new hires), however, are all in the Bay Area in California, and Tracy Strauss, SVP Marketing, is out of Los Angeles. There seems to be a deliberate approach to finding new ways of thinking from a broader field of expertise.

    D2L appears to have largely revamped its approach to product development that is more responsive to customer needs, and is putting resources into building partnerships. Yet they have not made the market gains envisioned after winning the Blackboard patent wars and then raising two large rounds of financing. We still see a two-horse race for new implementations (LMS product switches) in higher education, largely shared between Canvas and D2L, but the second horse that is looking better than it used to still needs to make further adjustments and run faster.

  • Schoology, NEO, Claroline, Chamilo: The beginning of the LMS long tail

    With reporting contributions from Jeanette Wiseman and O’Neal Spicer

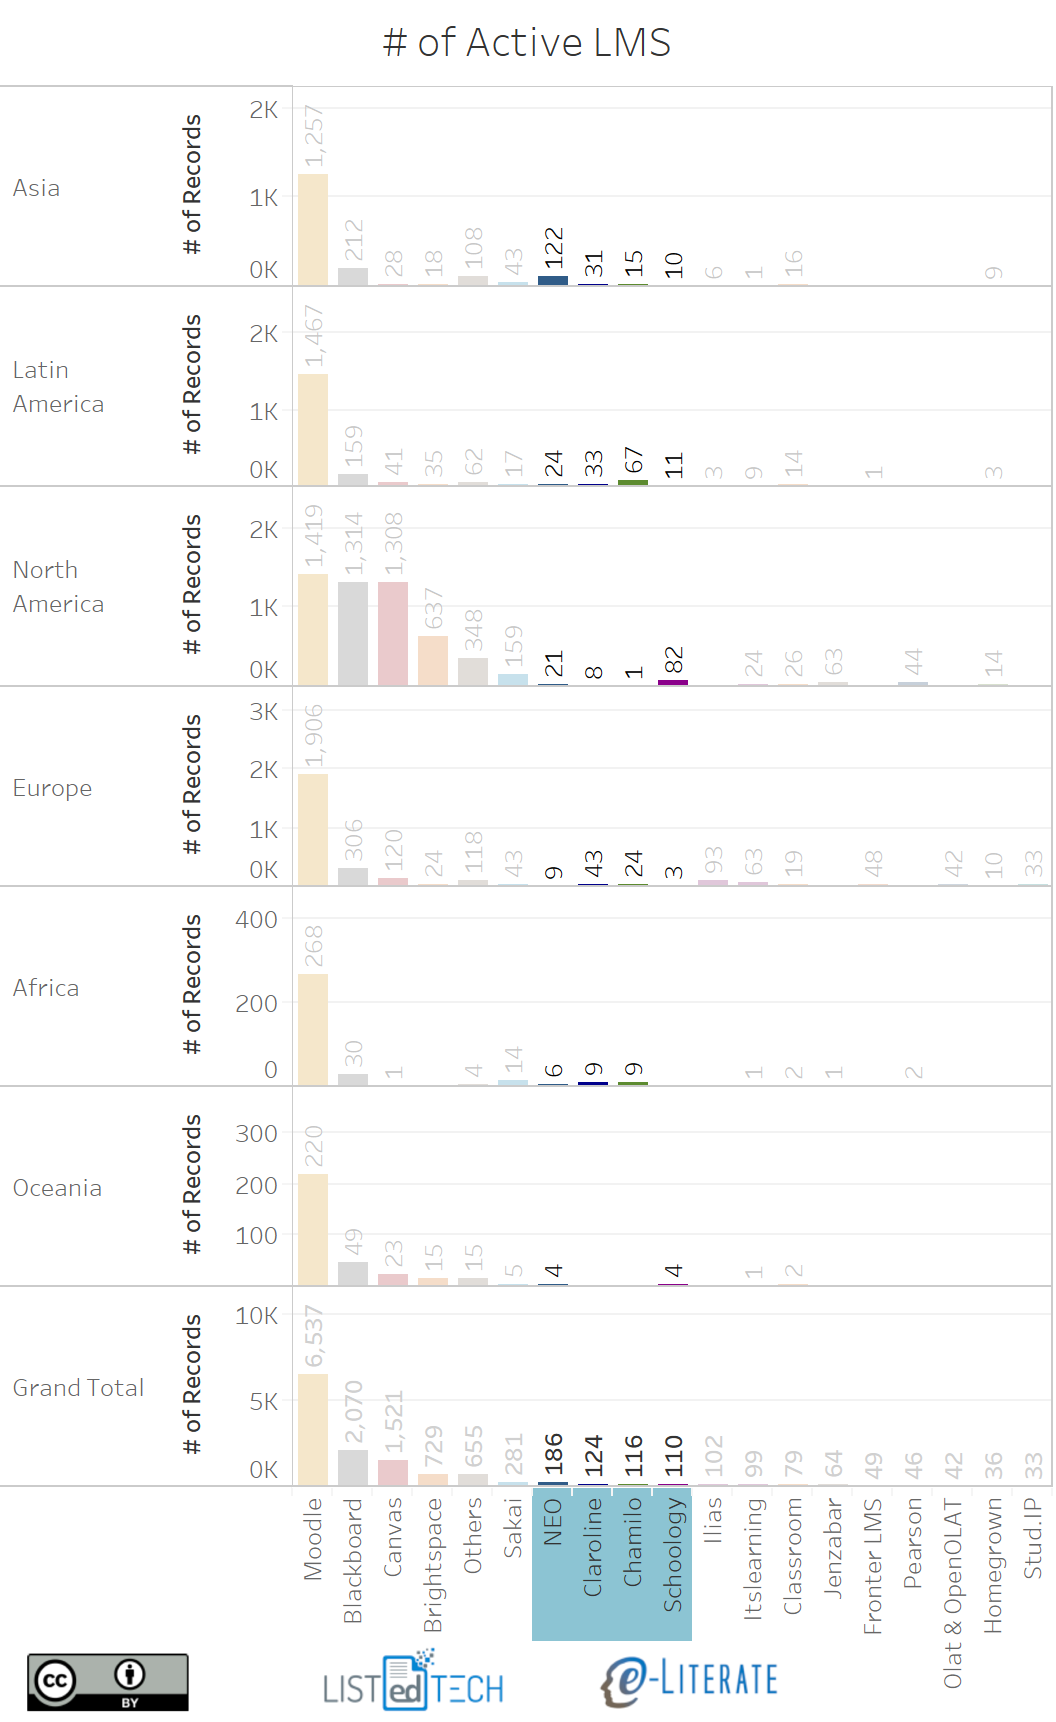
    We have described how the global LMS market is converging in the sense that the Big Four – Moodle, Blackboard, Instructure, and D2L – end up being the primary competitors in more and more global regions, often with similar dynamics. We have also described Sakai and its decline in some detail. But what about the next level down? Let’s consider four LMS solutions that are still quite active but with fewer institutional users than Sakai – Schoology (whom we have described before), NEO, Claroline, and Chamilo. ((Disclosure: Blackboard, Instructure, D2L, and Schoology are subscribers to our LMS Market Analysis service. Blackboard, Instructure, D2L, and Pearson are sponsoring participants in our Empirical Educator Project.)) The following graphic shows both primary and secondary system usage in higher education in six different global regions, and all four systems have more than 100 active implementations.

    LMS higher ed counts by global region


    Schoology NEXT

    • The Schoology NEXT conference occurred at the same time as BbWorld this year. This is a mostly K-12 conference – as that is the primary market for Schoology – with a different attendance demographic than most LMS conferences with the majority of the attendees being actual classroom teachers or instructional designers, not the typical administrators or IT staff that you see at the other user conferences. This audience is more focused on the use of technology to enhance teaching and learning in their classrooms, to assist with assessment, or to fill a requirement of use of technology for professional development. The break-out sessions reflected this academic focus.
    • The only new features or development that were discussed at any length during the keynote presentations involved the vague promise of “Personalized Learning” support. There was little information about what new features would look like, what they would encompass, or if they would entail additional charges like Schoology’s assessment platform. In an interview with CEO Jeremy Friedman and the new President Justin Serrano, they said that the vagueness is by design. The company is still working through their users’ needs and will be completing development on those features once that assessment was complete.
    • When discussing if the company saw Google Classroom’s continued growth in the K-12 market as a threat, Friedman said it is the opposite. They see that in K-12 space Google Classroom fills a need for a classroom, a school or a district that are dipping their toes in the LMS space, and once the school starts actively using the technology they quickly outgrow it. In these cases, Schoology sees Google Classroom as seeding the market for them, and they actively target those Google Classroom schools. In most cases, if responding to an RFP, it will be Canvas they will be up against. Rarely do they see Blackboard or even Moodle in these situations. They feel like, and this was reiterated by their users, that one of the most significant benefits that Schoology users see in the platform is their ease of use. The interface is reminiscent of Facebook; it is familiar to the teachers they quickly can navigate and load announcements and content to their site with very little training or IT support. It may not carry with it the bells and whistles of a Blackboard Learn or even Canvas by Instructure, but for what these K-12 teachers need, it fits the bill. For now.
    • Regarding targeting customers in higher education, the company stayed the course from January 2017 in which they will continue to support their higher education customers and will take easy sales opportunities, but are not planning to aggressively pursue that market. While this strategy only lightly targets higher education, Schoology has over 100 clients at universities and colleges worldwide – mostly small private schools, and often as secondary systems – using their platform. Customers using as a primary system include Wheaton College and Saint Vincent College in the US and the Universidad Metropolitana de Monterrey in Latin America. Schoology is also used as a secondary system at schools including UC San Diego.

    NEO, Claroline, and Chamilo

    The other three systems – NEO, Claroline, and Chamilo – are important in the global market, even if most academic buyers (in the US, at least) likely have not heard of them. All have more than 100 higher education implementations worldwide.

    • NEO is the academic LMS from Cypher Learning: Based on our conversations at the K-12 focused ISTE conference this summer, Cypher Learning has 60 employees and claims 2 million customers worldwide (combining NEO with the Indie and Matrix LMS for corporate markets). In higher ed, their largest implementation is with STI College in the Philippines with a systemwide deal that gives them 77 campus adoptions. The system has been designed native to the cloud and boasts a fairly intuitive user interface that addresses competency-based education and mastery learning.

    • Claroline Connect is an Open Source project run out of France: This system – which has the greatest adoption in Europe, Latin America, and Asia – is a second-generation open source project. In the early 2000s, the University of Lyon and the Université catholique de Louvain created two open source LMSs, and subsequently Claroline Connect combined these projects into the current system based on more modern technology. Get your French ready, or use captions.

    • Chamilo is an Open Source project run out of Spain: This system, used most often in Latin America and Europe, also has origins in the predecessors to Claroline, forking into the Dokeos project and then forking again to Chamilo in 2010. The system is supported by official supporting vendors in the following countries: Belgium, Spain, Italy and Germany. The Belgian company also has offices in Peru. Again, get your French ready.

    While we have only described this second tier of global LMS providers in broad strokes, we hope this post gives a richer view of the broader LMS market and available systems.

  • Welcome Change: OpenStax using more accurate data on student textbook expenditures

    Welcome Change: OpenStax using more accurate data on student textbook expenditures

    Last week OpenStax, the Rice University-based publisher of open educational resource (OER) materials, announced that according to their data more than 2.2 million students at 48% of colleges in the US and 1,150 outside the US are using OpenStax free textbooks, saving an estimated $177 million.

    This is compelling data in its own right, and we are working on analysis around this organization and its model, but somewhat buried in the press release is another significant statement around what students currently spend on textbooks and what savings are possible with OER.

    “Our community is creating a movement that will make a big impact on college affordability. The success of open textbooks like OpenStax have ignited competition in the textbook market, and textbook prices are actually falling for the first time in 50 years.”

    As a result of the unprecedented downward shift in textbook prices, OpenStax will be decreasing its estimated student savings figure from $98.57 to $79.37 based on federal data. The U.S. Department of Education’s National Center for Education Statistics published a study in May stating the average undergraduate student spent $555.60 on required course materials for the academic year. Dividing that number by seven courses (the undergraduate average, according to enrollment data) comes out to $79.37 in savings for each student using an OpenStax book.

    I have long argued that OER groups and others arguing for making college more affordable should use baseline numbers based on what students actually pay for textbooks, rather than the all-too-common $1,220 – $1,420 per year numbers from a misuse of College Board budget numbers (see chart at top of page 10 in this document). With OpenStax moving to new federal data showing $556 average expenditures, we should start to see more reliable estimates of student savings. Kudos to them.

    However, this level of student spending should not be a surprise to anyone following the curricular materials market.

    Our 2015 post “How Much Do College Students Actually Pay For Textbooks?”, as well as a follow-up post, show in detail that we have had data for years showing that students roughly $600 per year on textbooks and related course materials, and that that number has been falling since at least 2008. Using data from the National Association of College Stores (NACS), we knew three years ago about the rough level of spending and the multi-year decline. NACS has continued to release annual updates, with the most recent public release from last summer:

    NACS data showing course material expenditure

    What OpenStax refers to, however, is the new National Postsecondary Student Aid Study (NPSAS) restricted-use data from the US Department of Education’s National Center on Education Statistics, showing $555.60 average student expenditures per year. Which is right in line with the NACS data.

    We plan to explore the NPSAS data in more detail, as it provides rich data for crosstabs and exploration of student expenses. But for now, kudos to OpenStax for this change in student savings estimates, even if it is years overdue. I would hope that other OER advocates would follow their lead.

  • Terminology is Key to Understanding Blackboard Learn Prospects

    Terminology is Key to Understanding Blackboard Learn Prospects

    There are three observations from Blackboard’s users conference that we feel are important to share before we pull together our thoughts for more comprehensive posts, and all three issues build off of Blackboard’s strong focus at the conference on Learn Ultra as the future of their LMS product line.

    Learn Ultra “In Production” or “Using Ultra”

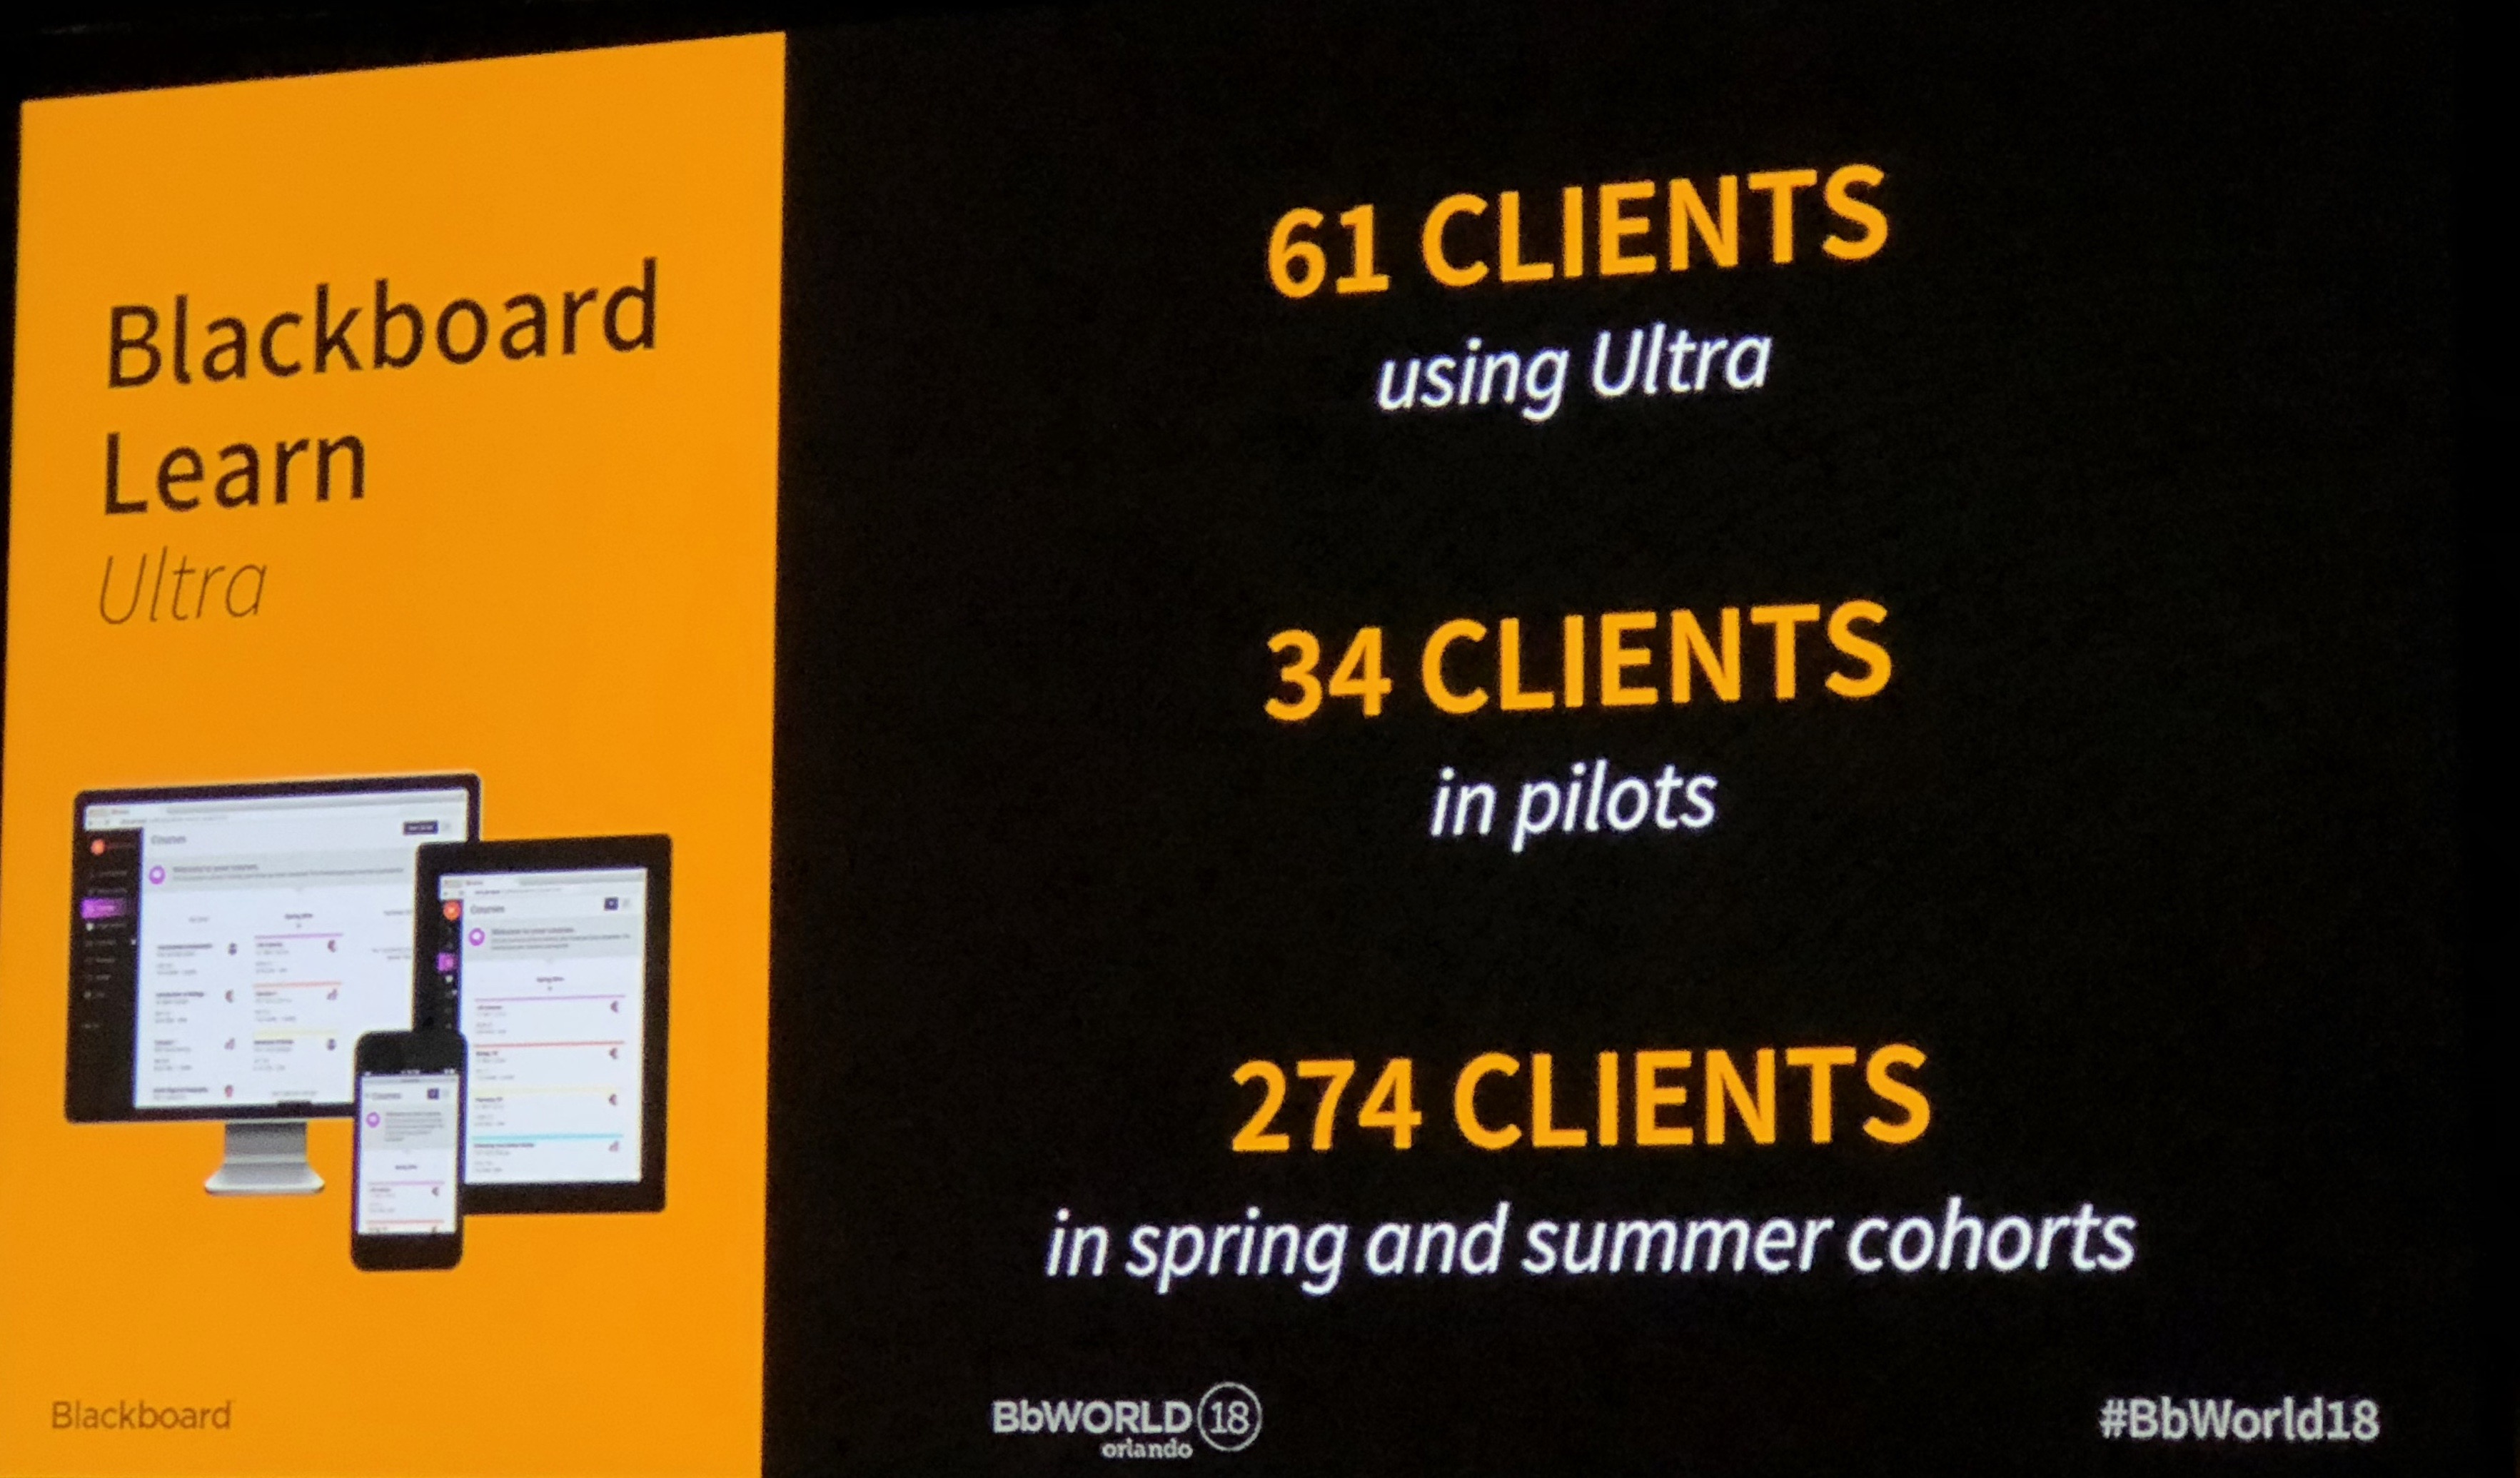
    The first issue is terminology around Learn Ultra. Blackboard ((Disclosure: Blackboard is a client of the e-Literate LMS Market Analysis service and a participating sponsor in our Empirical Educator Project.)) is pushing the metric that there are 61 or 62 Learn Ultra customers “in production” or “using Ultra”, yet we have found very few that use, or even plan to use, Learn Ultra as their primary, institution-wide LMS. What gives? What became quite clear at the conference is that when Blackboard says in production, what they mean is that the LMS administrator has enabled the Ultra global navigation, which uses the new Ultra user experience framework as the landing page / dashboard with activity feed that users see before entering a specific course. The company calls this Base Navigation, but at this point every course can be configured to be in the Original Experience or the Ultra Experience. Thus, enabling the possibility of running a course in Ultra counts as in production.

    Slide from BbWorld18

    Once a school has enabled Learn Ultra Base Navigation, they could choose to move exclusively to Ultra (e.g. the University of Phoenix, Northwest Florida State College, and a few others), or they could choose to keep all courses in Original (e.g. Northeastern State University), or they could choose to have some courses in Ultra and some in Original (used by the majority of schools investigating Ultra). This last mode is known as Dual Course mode, and even Blackboard executives are surprised to find out that the vast majority of schools putting Ultra in production are in fact running in Dual Course. For many of these schools, there are no definitive plans to ever move exclusively to Ultra.

    This distinction is important, as the majority of functionality for an LMS occurs within a course, even if we did hear a few schools present that they saw some end-user benefits to having the landing page itself. We will add more commentary on this subject in future posts, but for now the takeaway is that Ultra in production numbers from Blackboard do not necessarily mean that any or most courses are in the Ultra Experience.

    Product Variations Resulting in Three Dates for New Features

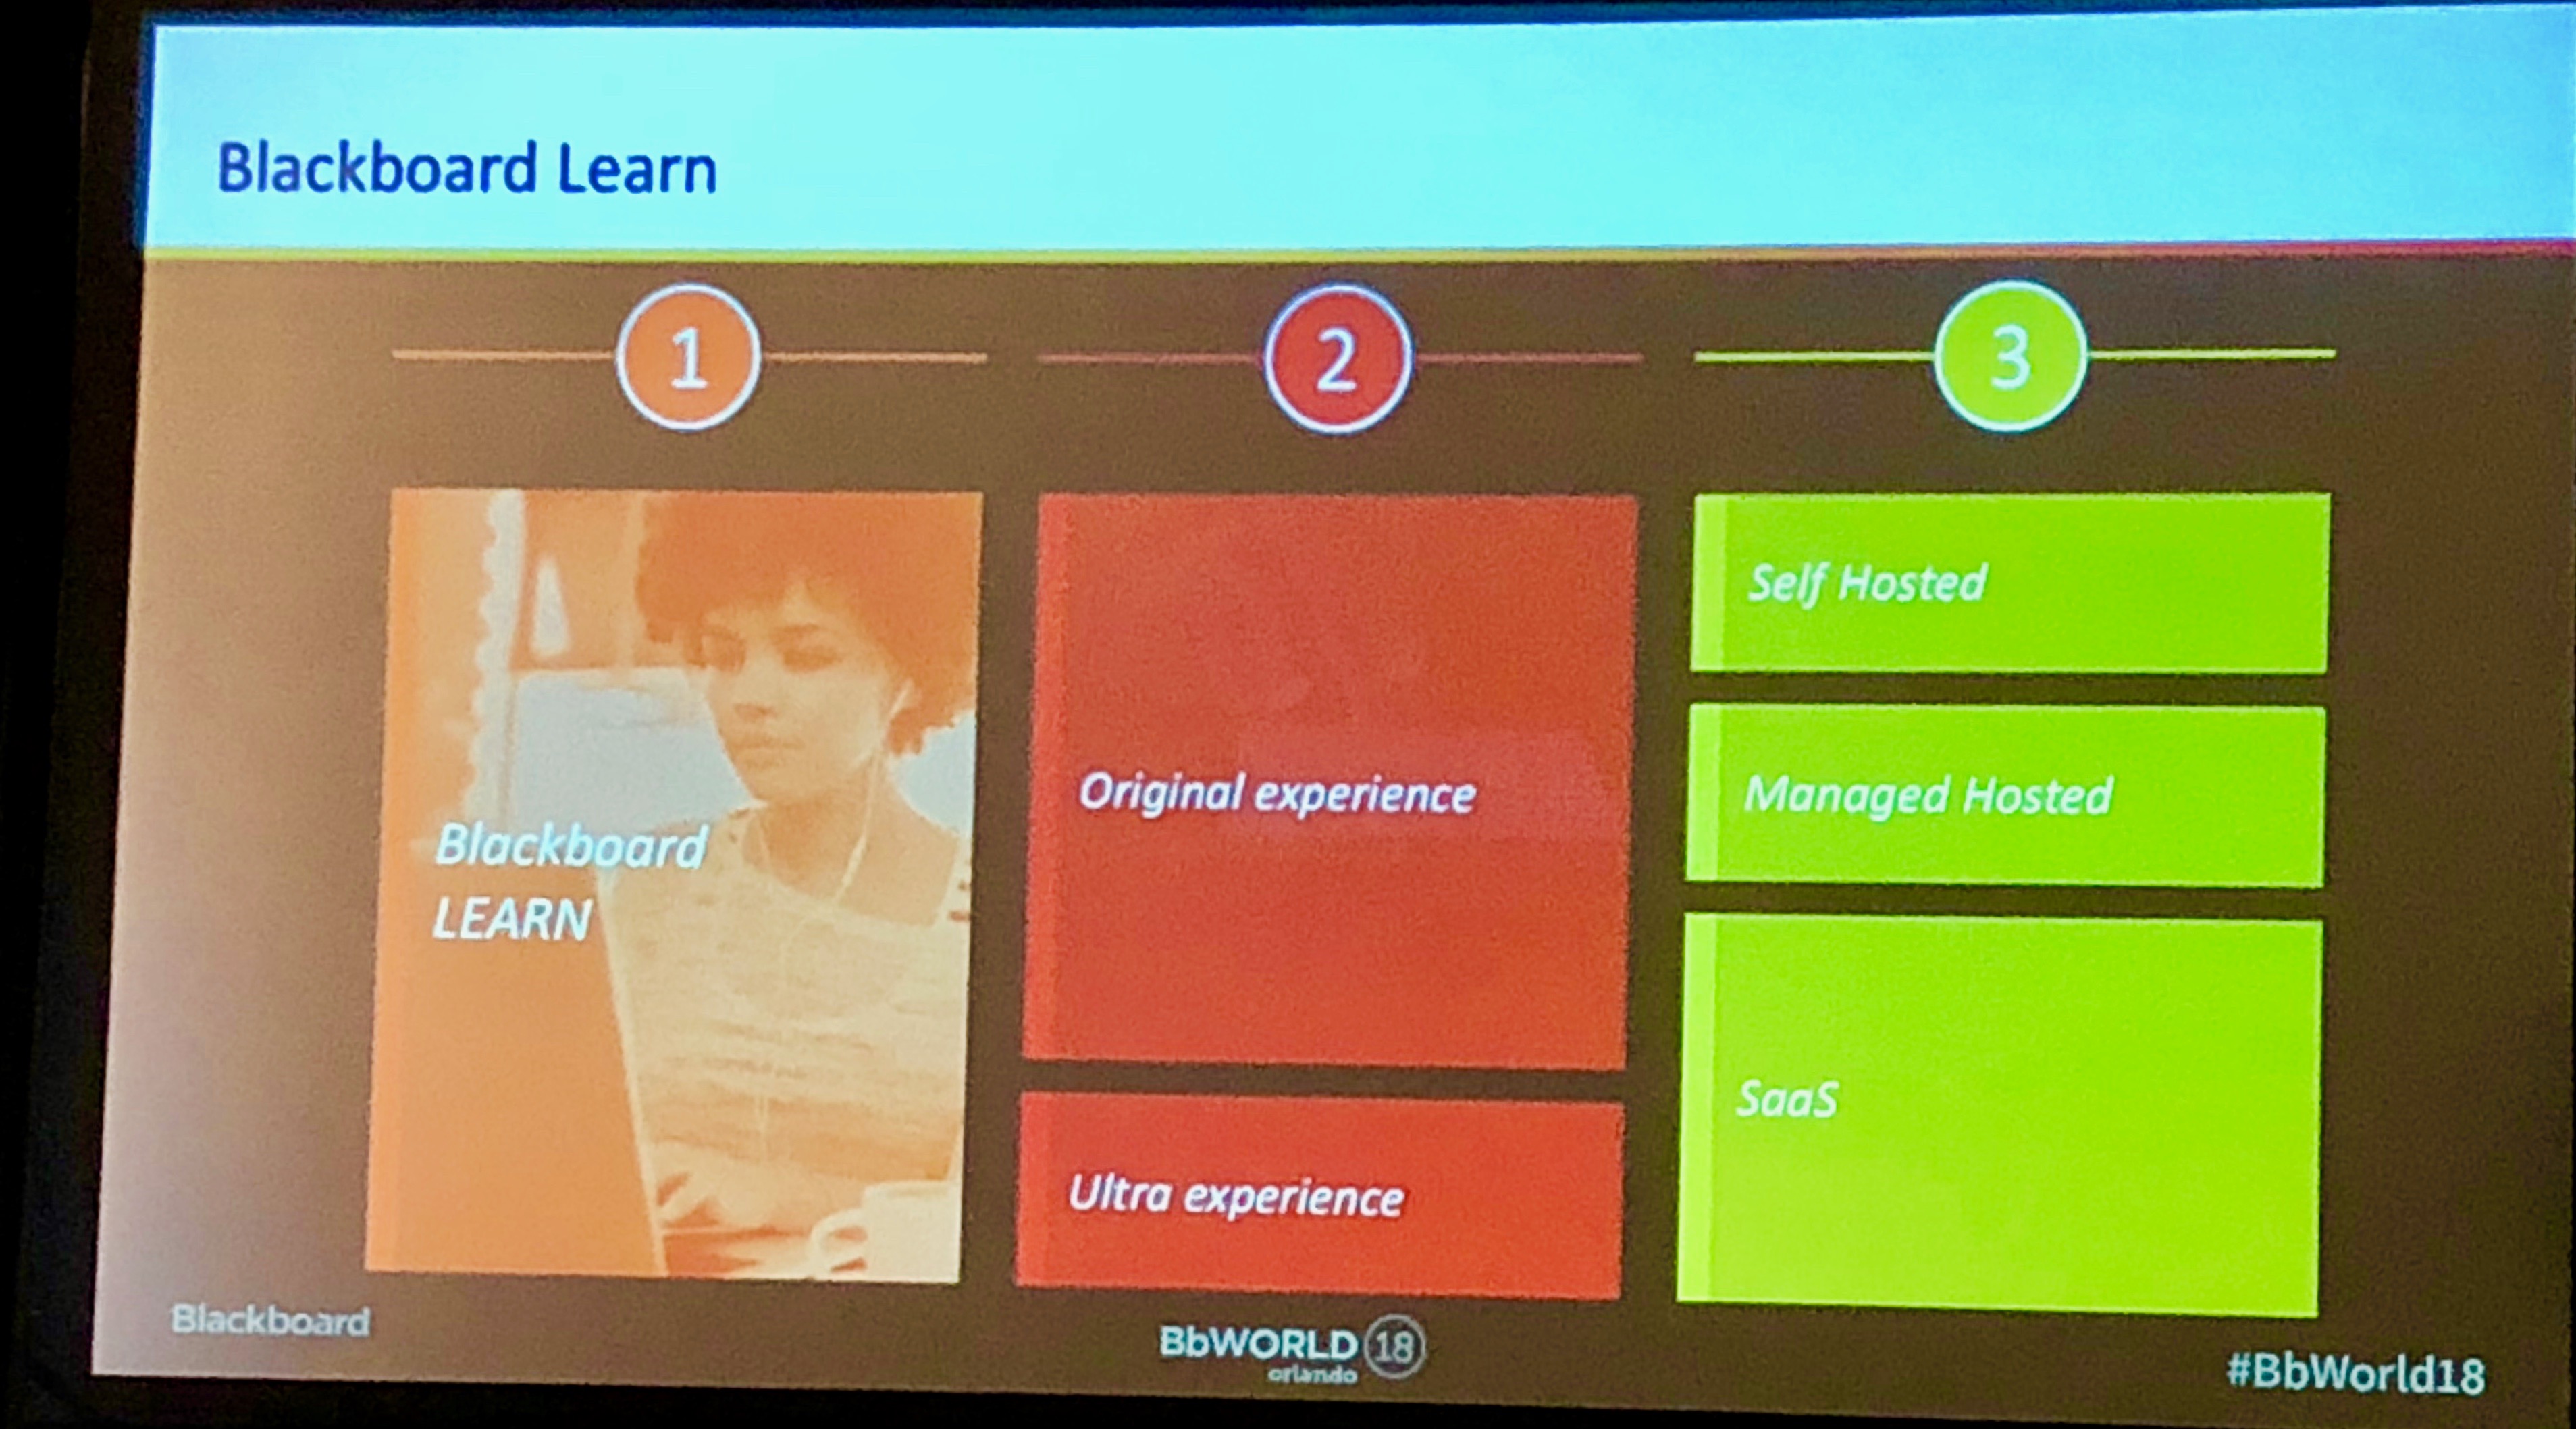
    The second issue is that Blackboard Learn has two experiences (Ultra and Original), three deployments (self-hosting, managed-hosting by Blackboard, and SaaS-hosting at using AWS), often resulting in three different dates for full delivery of new features.

    Slide from BbWorld18

    Keeping in mind that the Original Experience is available on all three deployment models but Ultra is available only in SaaS, here is the view of the final delivery groupings for the courses:

    • Learn Original on self-hosting and Learn Original on managed-hosting, which the bulk of their customers use, is the first case.
    • Learn Original on SaaS-hosting, which represents the bulk of their 383 customers on Learn SaaS announced at the conference, is the second case.
    • Learn Ultra, which represents some subset of the 62 customers announced as “Ultra in production”, is the third case.

    Of course there is significant overlap in terms of common code, such as the micro-services running in the SaaS environment for both experiences, or shared source code between deployment options. But from a feature delivery perspective, the full release often has three different delivery dates – Original SH & MH, Original SaaS, and Ultra.

    This is good news or bad news, depending on your perspective. For Blackboard’s customers, it means more options without forced migrations. Blackboard staff stated several times in presentations and in hallway conversations that none of the deployment options or experiences have any plans to go end-of-life or even into maintenance mode. But on the other hand, Blackboard will not achieve many of the benefits of becoming a cloud product company until they can move the majority of development purely onto SaaS.

    SaaS Better Indicator Than Ultra of Client Retention

    The third issue, which is related to the first two, is that we believe ((OK, OK. I admit that Michael should get credit for seeing this issue more clearly than I did. Not many people read footnotes, so I feel comfortable with this admission.)) that the migration to Learn SaaS might be a better indicator – at least in the short run – than Ultra adoption of whether a school plans to stick with Blackboard. Whether or not the school enables Ultra base navigation or any courses in the Ultra Experience.

    When a school moves to Learn SaaS, they tend to sign contract extensions for 1 – 3 years to cover the new services. And the migration to Learn SaaS does not suffer from the vague terminology issues – a school either uses Learn deployed on SaaS (through AWS) or they don’t.

    For now, just treat this as clarification on the complexities of Blackboard Learn LMS options that became more apparent at the conference.

    Update 7/23: Changed header and some text in second section to focus on dates of feature delivery.

  • Revisiting 2012 Post on Barriers That MOOCs Would Face

    Revisiting 2012 Post on Barriers That MOOCs Would Face

    Inside Higher Ed published an article today, titled “Free MOOCs Face The Music”, about edX quietly adding support fees for many of their courses. Dhawal Shah and I both commented that we were not surprised by the move.

    Writing about the introduction of the fee, Dhawal Shah, founder and CEO of Class Central, a review site for online courses, said the announcement was the latest in a phenomenon he termed “the shrinking of free.” Regardless of MOOC provider — be it edX, Coursera, Udacity or FutureLearn — “all have cut back on what was originally free in MOOCs.”

    Phil Hill, co-founder of Mindwires Consulting and an author of the e-Literate blog, agreed that the edX announcement was not surprising. Early MOOC providers like edX thought they would be able to “get really big for free,” said Hill. “Magic didn’t happen, and now they’re facing reality.”

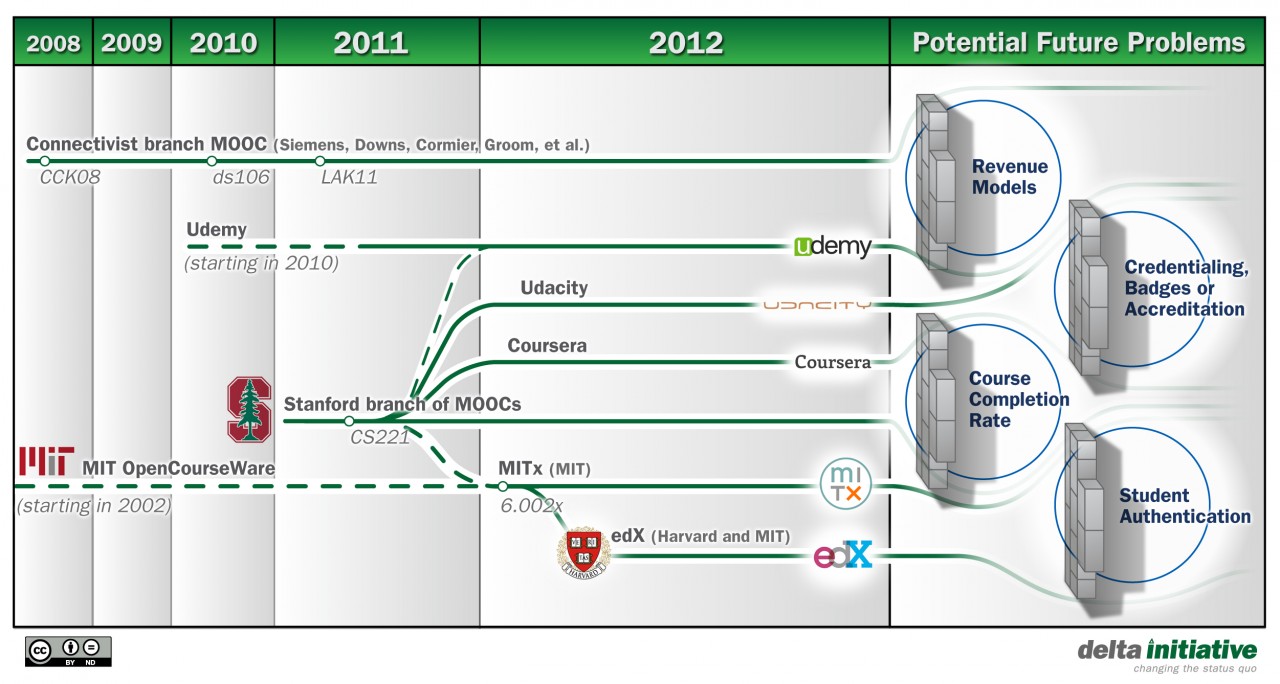
    There’s more information in the article worth reading, but I would like to revisit a post here at e-Literate from 2012 to help explain the point I made. In “Four Barriers That MOOCs Must Overcome To Build a Sustainable Model”, I noted:

    The current generation of courses has proven the feasibility of massive online enrollments, but the Kolowich article reveals that the result is based on a form of adult continuing education. The majority of students in the Udacity and Coursera courses analyzed were professionals in the software industry – hardly the target audience for those seeking a change in how we educate postsecondary students. The current MOOCs provide a nice proof-of-concept, but hardly solve significant educational problems.

    So what are the barriers that must be overcome for the MOOC concept (in future generations) to become self-sustaining? To me the most obvious barriers are:

    • Developing revenue models to make the concept self-sustaining;
    • Delivering valuable signifiers of completion such as credentials, badges or acceptance into accredited programs;
    • Providing an experience and perceived value that enables higher course completion rates (most today have less than 10% of registered students actually completing the course); and
    • Authenticating students in a manner to satisfy accrediting institutions or hiring companies that the student identify is actually known.

    Given this short timeline and the nature of investment-backed educational experiments, I think the real focus should be on whether and how MOOCs or successor models build on current scalability and openness while overcoming these four barriers.

    What have we seen since 2012?

    • Revenue Models: Coursera, FutureLearn, and edX moving towards an OPM business model, and Udacity focusing on corporate education;
    • Credentialing: All MOOCs offering some sort of verified certificates, and in the OPM cases offering actual degrees through their partner institutions;
    • Course Completion: MOOCs realizing that the two issues above lead to higher completion rates; and
    • Authentication: Verified certificates and OPM models requiring student authentication through webcams and approaches similar to online proctoring companies, and even partnering with proctoring companies.

    At this stage  pretty much everyone recognizes a blatant ‘I told you so’ post written while Michael is on vacation and unable to talk me out of it, so I’ll move along and cut off further commentary.

  • UF Online’s New Corporate Partner: Discover Financial joins Walmart with Online Education benefit

    UF Online’s New Corporate Partner: Discover Financial joins Walmart with Online Education benefit

    Last week Walmart announced a new education benefit for its employers, subsidizing undergraduate college degrees at select online programs at the University of Florida (through UF Online), Brandman University, or Bellevue University.

    The company said it estimates as many as 68,000 of its employees initially could sign up for the new college program. Walmart employs 1.5 million in the U.S. The company declined to comment on how much this initiative will cost it.

    Employees will contribute $1 per day, for 365 days every year, toward their education, so long as they’re enrolled. Walmart will cover the rest of the tab. Workers will be able to choose from the three nonprofit schools and have the option of taking classes online with the flexibility to study during the evenings or on weekends.

    Today UF Online announced another partner: Discover Financial Services, issuers of the Discover Card and Diners Club International, with its 14,000 employees.

    Discover announced a significant new education assistance benefit that provides all eligible U.S.-based employees the opportunity to earn a bachelor’s degree online from an accredited public or non-profit private university at no cost.

    Known as The Discover College Commitment, the benefit covers tuition and required fees, books and supplies needed to complete select online degrees at one of three schools – the University of Florida (via UF Online), Wilmington University and Brandman University. The benefit has no tenure requirement so employees can start participating as soon as they want regardless of how long they have been with the company, including new employees on their first day.

    The two partnerships are part of what UF Online calls their Employer Pathways, and in the process seem to be defining an alternate method of marketing and enrollment management, in contrast with most Online Program Management (OPM) assumptions.

    Employees from Walmart and Discover Financial Services have expanded opportunities to earn a bachelor’s degree from the University of Florida (UF) thanks to a new and significant investment in their education from their employers. This remarkable step by these and other large employers demonstrates the value of a UF degree and the accessibility of UF Online, UF’s online undergraduate experience. Employers will provide a robust support package covering tuition, fees, plus access to life coaching and college readiness programs.

    Discover is offering this new benefit to select programs at UF Online, Wilmington University, and Brandman University.

    Discover is covering 100% of cost for select bachelor’s degrees. Discover is proud to offer “The Discover College Commitment” program – an innovative full-ride college education benefit, providing US-based employees the opportunity to participate in one of several select high-quality, fully paid, online bachelor’s degrees.

    Both packages of education benefits is managed by Guild Education, “a tuition reimbursement and education platform that helps large employers extend education benefits, including tuition reimbursement, to workers”.

    I think these moves are more significant than just individual benefits. What we are seeing is UF Online, along with a handful of others, defining a different approach to marketing and finding potential online students, at least for undergraduate degrees. Historically, there is a common assumption that to enable a scalable online program there is a need for traditional digital marketing as the primary approach – Google AdWords, call centers, social media campaigns – with a partnership or two thrown in on the side. The origin of the OPM market is centered on providing these services in exchange for a percentage of tuition revenue, and for the majority of cases, the OPM’s spending on this marketing and enrollment management category is the most expensive service in the package. The Employer Pathways approach by UF Online has the potential to flip the student acquisition assumptions – primarily driven by employer partnerships with traditional digital marketing channels as a secondary approach.

    Walmart and Discover already have potential students identified, and the companies have the incentive to internally market these education benefits to employees. UF Online needs to support that internal marketing and feed applicants into the same application process, but they have a reduced need for general-purpose marketing. UF Online started out with Pearson Online Learning Services (formerly known as Embanet) to be their OPM partner, but in late 2015 they pushed Pearson out and decided to take over this management internally.

    I talked to Evangeline (Evie) Cummings, Associate Provost and Director of UF Online, at WCET’s Leadership Summit last week, and she described how UF Online is trying to reduce their marketing spend and instead invest more in faculty and course development. Part of that move is to spend less trying to get out-of-state students, which may pay higher tuition but still cost much more per student in acquisition costs. But the other move is to decrease the need to spend on traditional marketing channels.

    We can think of Guild Education in this case as a derivative of the unbundling version of OPM, enabling the front-end services with an alternative approach and what appears to be a lower revenue share.

    Rather than charge a transaction fee per student to the employer, Guild takes a cut of the tuition revenue from the universities it works with. This revenue-share model is an “elegant” solution for institutions that want to grow their enrollment online but don’t want to spend more on marketing, said Carlson. It’s also an attractive proposition for employers, who don’t have to pay any additional charges on top of the contribution they make to their employees’ tuition. The tuition fees are not discounted for the employers and will be charged at in-state or out-of-state rates depending on the location of the student. Neither Guild nor the three universities involved in the Walmart offer would disclose what percentage of tuition revenue Guild will take.

    The bulk of the OPM market serves master’s programs, and UF Online is centered on bachelor’s degrees with a handful of master’s, so this approach might not work across the board. But I’ll bet that there will be plenty of undergraduate online initiatives that will be looking to UF Online and wondering if they should develop similar degree pathway partnerships as the centerpiece of their student acquisition plans. The online education space is maturing and becoming a lot more interesting.