e-Literate

Present is Prologue

Category: Business & Economics

The “Business & Economics” category covers the business aspects of ed tech, including the financial health and business models of individual companies, economic aspects of selling in education that shape the available offerings, and coverage of markets and investment.

  • Textbook Authors Sue over Cengage Unlimited Royalties

    Textbook Authors Sue over Cengage Unlimited Royalties

    Back in January, I wrote of Cengage’s “all you can eat” Unlimited pricing announcement:

    We don’t know whether Cengage will be a winner from this strategy, but we do know who will be the losers: textbook authors. Cengage, of course, denies this. Cengage CTO George Moore, when asked about the contract renegotiations with the authors to make this fly, said only that “Cengage renegotiates contracts with authors all time.” Michael Hansen claimed that Cengage’s interests and their authors are aligned, and that their authors are all very concerned about the affordability of textbooks.

    Really?

    In February of 2015, Greg Mankiw—Cengage’s blockbuster economics textbook author who has made literally millions of dollars from his relationship with Cengage—expressed perplexity at the The New York Times’ call for less expensive textbooks:

    To me, this reaction seems strange. After all, the Times is a for-profit company in the business of providing information. If it really thought that some type of information (that is, textbooks) was vastly overpriced, wouldn’t the Times view this as a great business opportunity? Instead of merely editorializing, why not enter the market and offer a better product at a lower price? The Times knows how to hire writers, editors, printers, etc. There are no barriers to entry in the textbook market, and the Times starts with a pretty good brand name.

    My guess is that the Times business managers would not view starting a new textbook publisher as an exceptionally profitable business opportunity, which if true only goes to undermine the premise of its editorial writers.

    Given that Mankiw was name-checked in the Cengage Unlimited announcement press release, management must have worked something out with him to keep him happy. We are hearing whispers from the company’s competitors that not all authors were given such an opportunity and that lawsuits may follow. We’ll see whether that bears out. Regardless, though, this model does fundamentally change the relationship that the publisher has with its authors. With buffet-style pricing at a low rental price point, a model like Cengage Unlimited is likely to do to textbook authors what Spotify and other music subscription services did to musicians. There may still be a handful of superstar authors whose books are such outsized hits that they can still command royalties and large advances. But the vast majority of authors will see their income shrink. They either will get smaller royalty agreements or will be paid once on a fee-for-services basis so that the company can own the content outright. My guess is that there will be a lot more of the latter than the former. Keep in mind that copyright negotiations for a textbook or textbook-equivalent involve more than just the author(s). There may be literally hundreds of permissions to track for photographs, videos, animations, and so on. To the degree that “good enough” wins out over “better enough”, publishers will be under strong pressure to own as much of their content outright as they can.

    Today’s Inside Higher Ed headline: Textbook Authors Sue Cengage Over Subscription Model.

    To be clear, I don’t know if, contractually, this lawsuit has merit or what is likely to happen with this particular suit. But the handwriting is on the wall. If textbook prices come down, then textbook royalties also have to come down.

    Regardless, all of this is transitional. As students are asking, “Why should we pay all this money for content that is increasingly available online for free?”, textbook publishers are asking themselves the same question. Rights management is an expensive nightmare for them. Their businesses would be much more manageable if they could use either OER, fee-for-service content that they own outright, or both. Their biggest challenge is that faculty are used to using a particular textbook and may have some attachment to the particular author. If the publishers replace that book with one that doesn’t have all of those royalty entanglements, then faculty are more likely to look around at competitors’ offerings since, hey, if they have to rework their class for a book anyway, they might as well look around. If it weren’t for that problem, I suspect that publishers would be swapping out titles more quickly.

  • Portentous Changes in Instructure’s Executive Management

    Portentous Changes in Instructure’s Executive Management

    Instructure just announced the hiring of a new president. Dan Goldsmith is a software executive with experience in SaaS, international markets, and business-to-business sales, but not with education. He “will have broad responsibilities overseeing sales, marketing, product, customer experience, engineering and business development.” At the same time, COO Mitch Macfarlane is leaving. So this is a major reorganization. Taken together with the earlier departures of the company’s long-time sales and marketing executives, there has been a near complete turnover and reorganization of their top-level management.

    To some extent, this is to be expected. People do start to cash out after an IPO. But the turnover and reorganization at Instructure seems quite significant—at a company that has stood out in the industry for having a tight, highly functional management team.

    We’ll have more to say about these changes in the coming weeks. For now, I’ll predict that 2018 and 2019 will continue to be eventful in the higher education LMS space.

  • OPM Market May Be Growing, But It’s Not Without Chaos

    OPM Market May Be Growing, But It’s Not Without Chaos

    There has been growing interest in the Online Program Management (OPM) market, as more schools try to develop a strategy and revenue model for online programs (particularly for master’s level), and as 2U continues its rapid rise in the stock market (with a nearly $4.8 billion market cap). Typically the description of this market is that the total annual revenue is somewhere between $1.5 – $2.5 billion and that it is growing. The implications are that we have a land grab as companies get rich off the new programs.

    The reality, however, is more complicated. The OPM market may be growing, but it is chaotic and messy. Consider the following problems within the market:

    • This is not an easy market, as many programs take millions of dollars of investment by the OPM provider before an account becomes profitable, often 3 – 5 years down the road.
    • 2U’s Semester Online initiative, targeted at the undergrad market as a consortium, shut down in 2014 due to the departure of several founding member institutions and due to low enrollment.
    • Later that same year Cal State Online shut down in all but name, along with its usage of Pearson as its OPM partner.
    • In 2015 Synergis Education pulled out of its work with USC’s Master of Integrated Design, Business and Technology program, to be eventually replaced by 2U.
    • In 2016 the University of Florida Online (UF Online) canceled its contract with Pearson and pivoted to a new approach not using an OPM partner.
    • After raising $230 million from Bertelsmann in 2015, HotChalk has failed to bring in any new clients of the scale of Concordia University, and in 2016 the company paid a $1 million settlement (though not admitted any fault) based on a federal investigation and lawsuit.
    • Sometime in 2016/17, the nonprofit OPM Educators Serving Educators from Excelsior College shut down.
    • In 2017 after a management shake-up, DeVry Education Group (now Adtalem) pulled out of the OPM market and got rid of its Integrated Education Solutions group.
    • In late 2017 the Eastern Michigan University’s chapter of the American Association of University Professors filed a complaint against EMU’s contract with Academic Partnerships, although an arbitrator sided with the school earlier this year.
    • Also in late 2017 Greenwood Hall – a call center-based fee-for-service OPM provider – collapsed in dramatic fashion, with AnswerNet eventually buying the remaining assets.
    • There has been growing pushback on the mainline revenue-sharing model, where full-service OPM providers make 50% or even more of tuition dollars from online programs. This has led to the rise of unbundled, fee-for-service category of OPM providers.

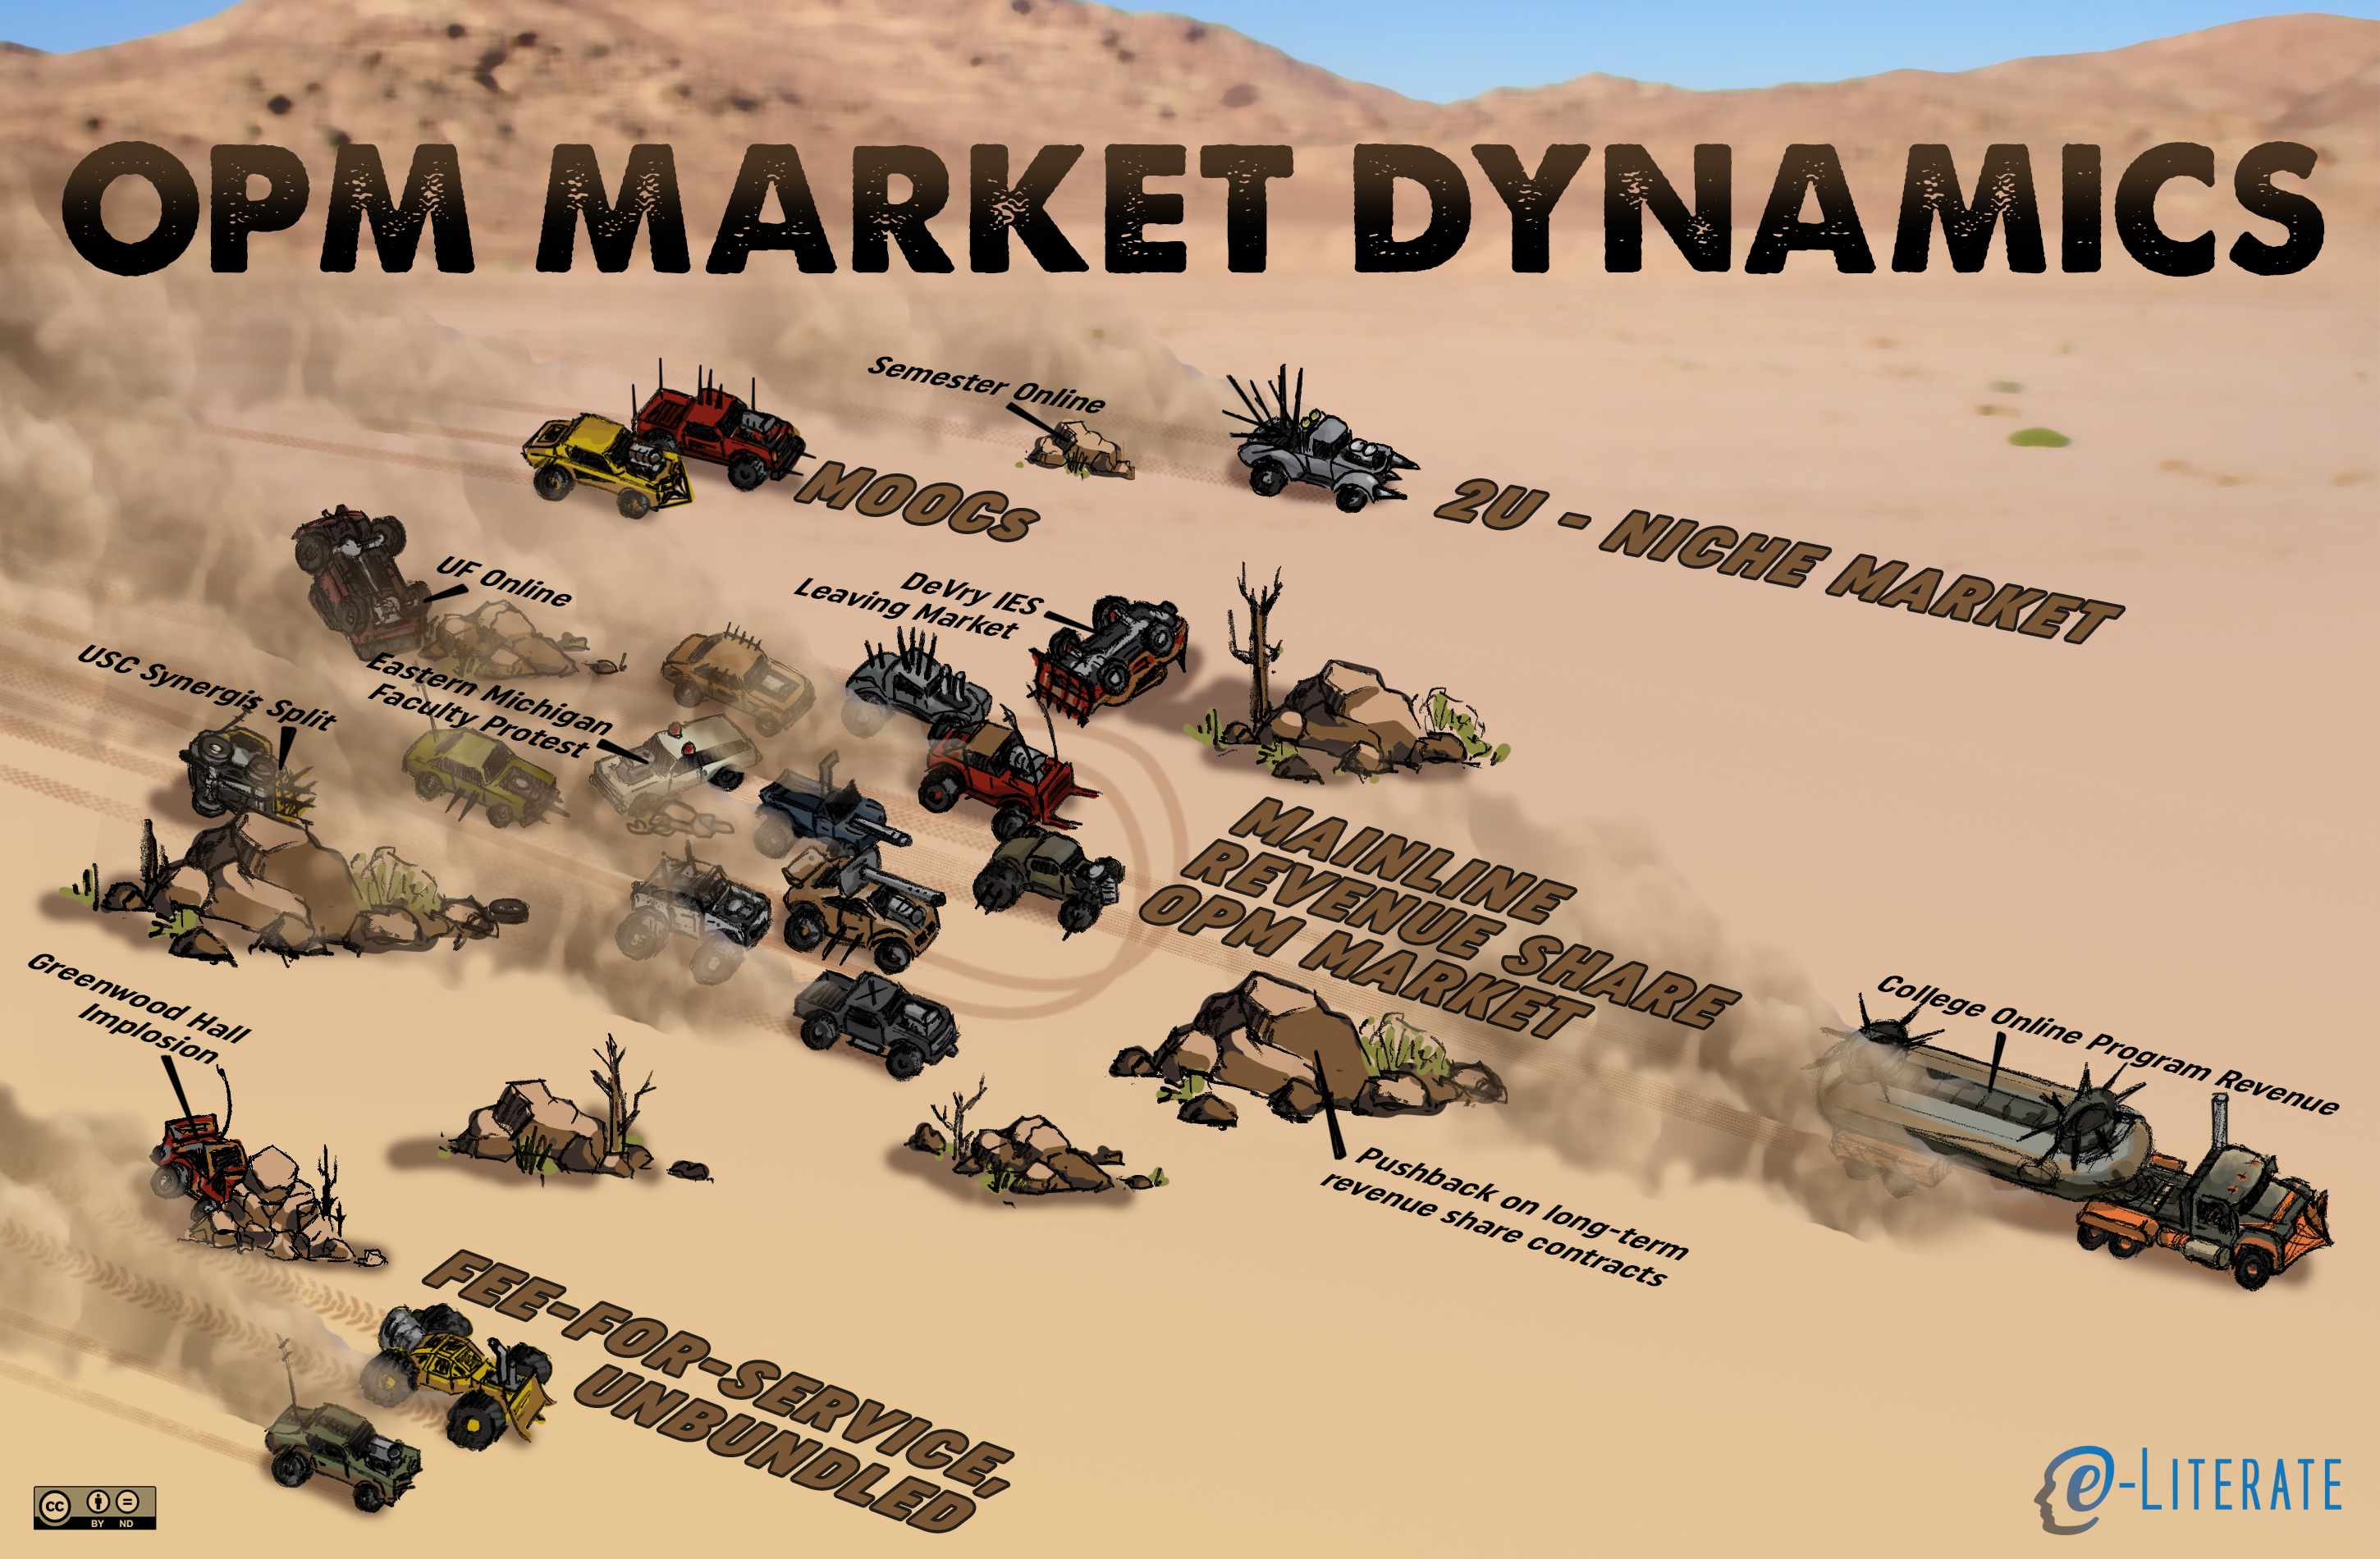
    The picture one gets is of a chaotic market that is not for the faint of heart, and one that will likely see further consolidations and category changes. 2U, for its part, has been successful partially due to a niche strategy where they go after elite master’s programs and mostly avoid direct competition or engagement with the rest of the market. And recently we have started to see the MOOC providers become OPM providers – where the primary revenue for Coursera and FutureLearn are based on revenue sharing with online programs, albeit with lower sharing rates and with very different marketing approaches. In other words, there seems to be several efforts to enter into the same OPM race, but if possible to avoid being in the mainline rev-share OPM market. The Toecutter would feel right at home.

    The Mad Max view of OPM market dynamics

    Not even represented here is the movement of former for-profit institutions (e.g. Grand Canyon University, the parent company of Kaplan University) becoming OPM providers.

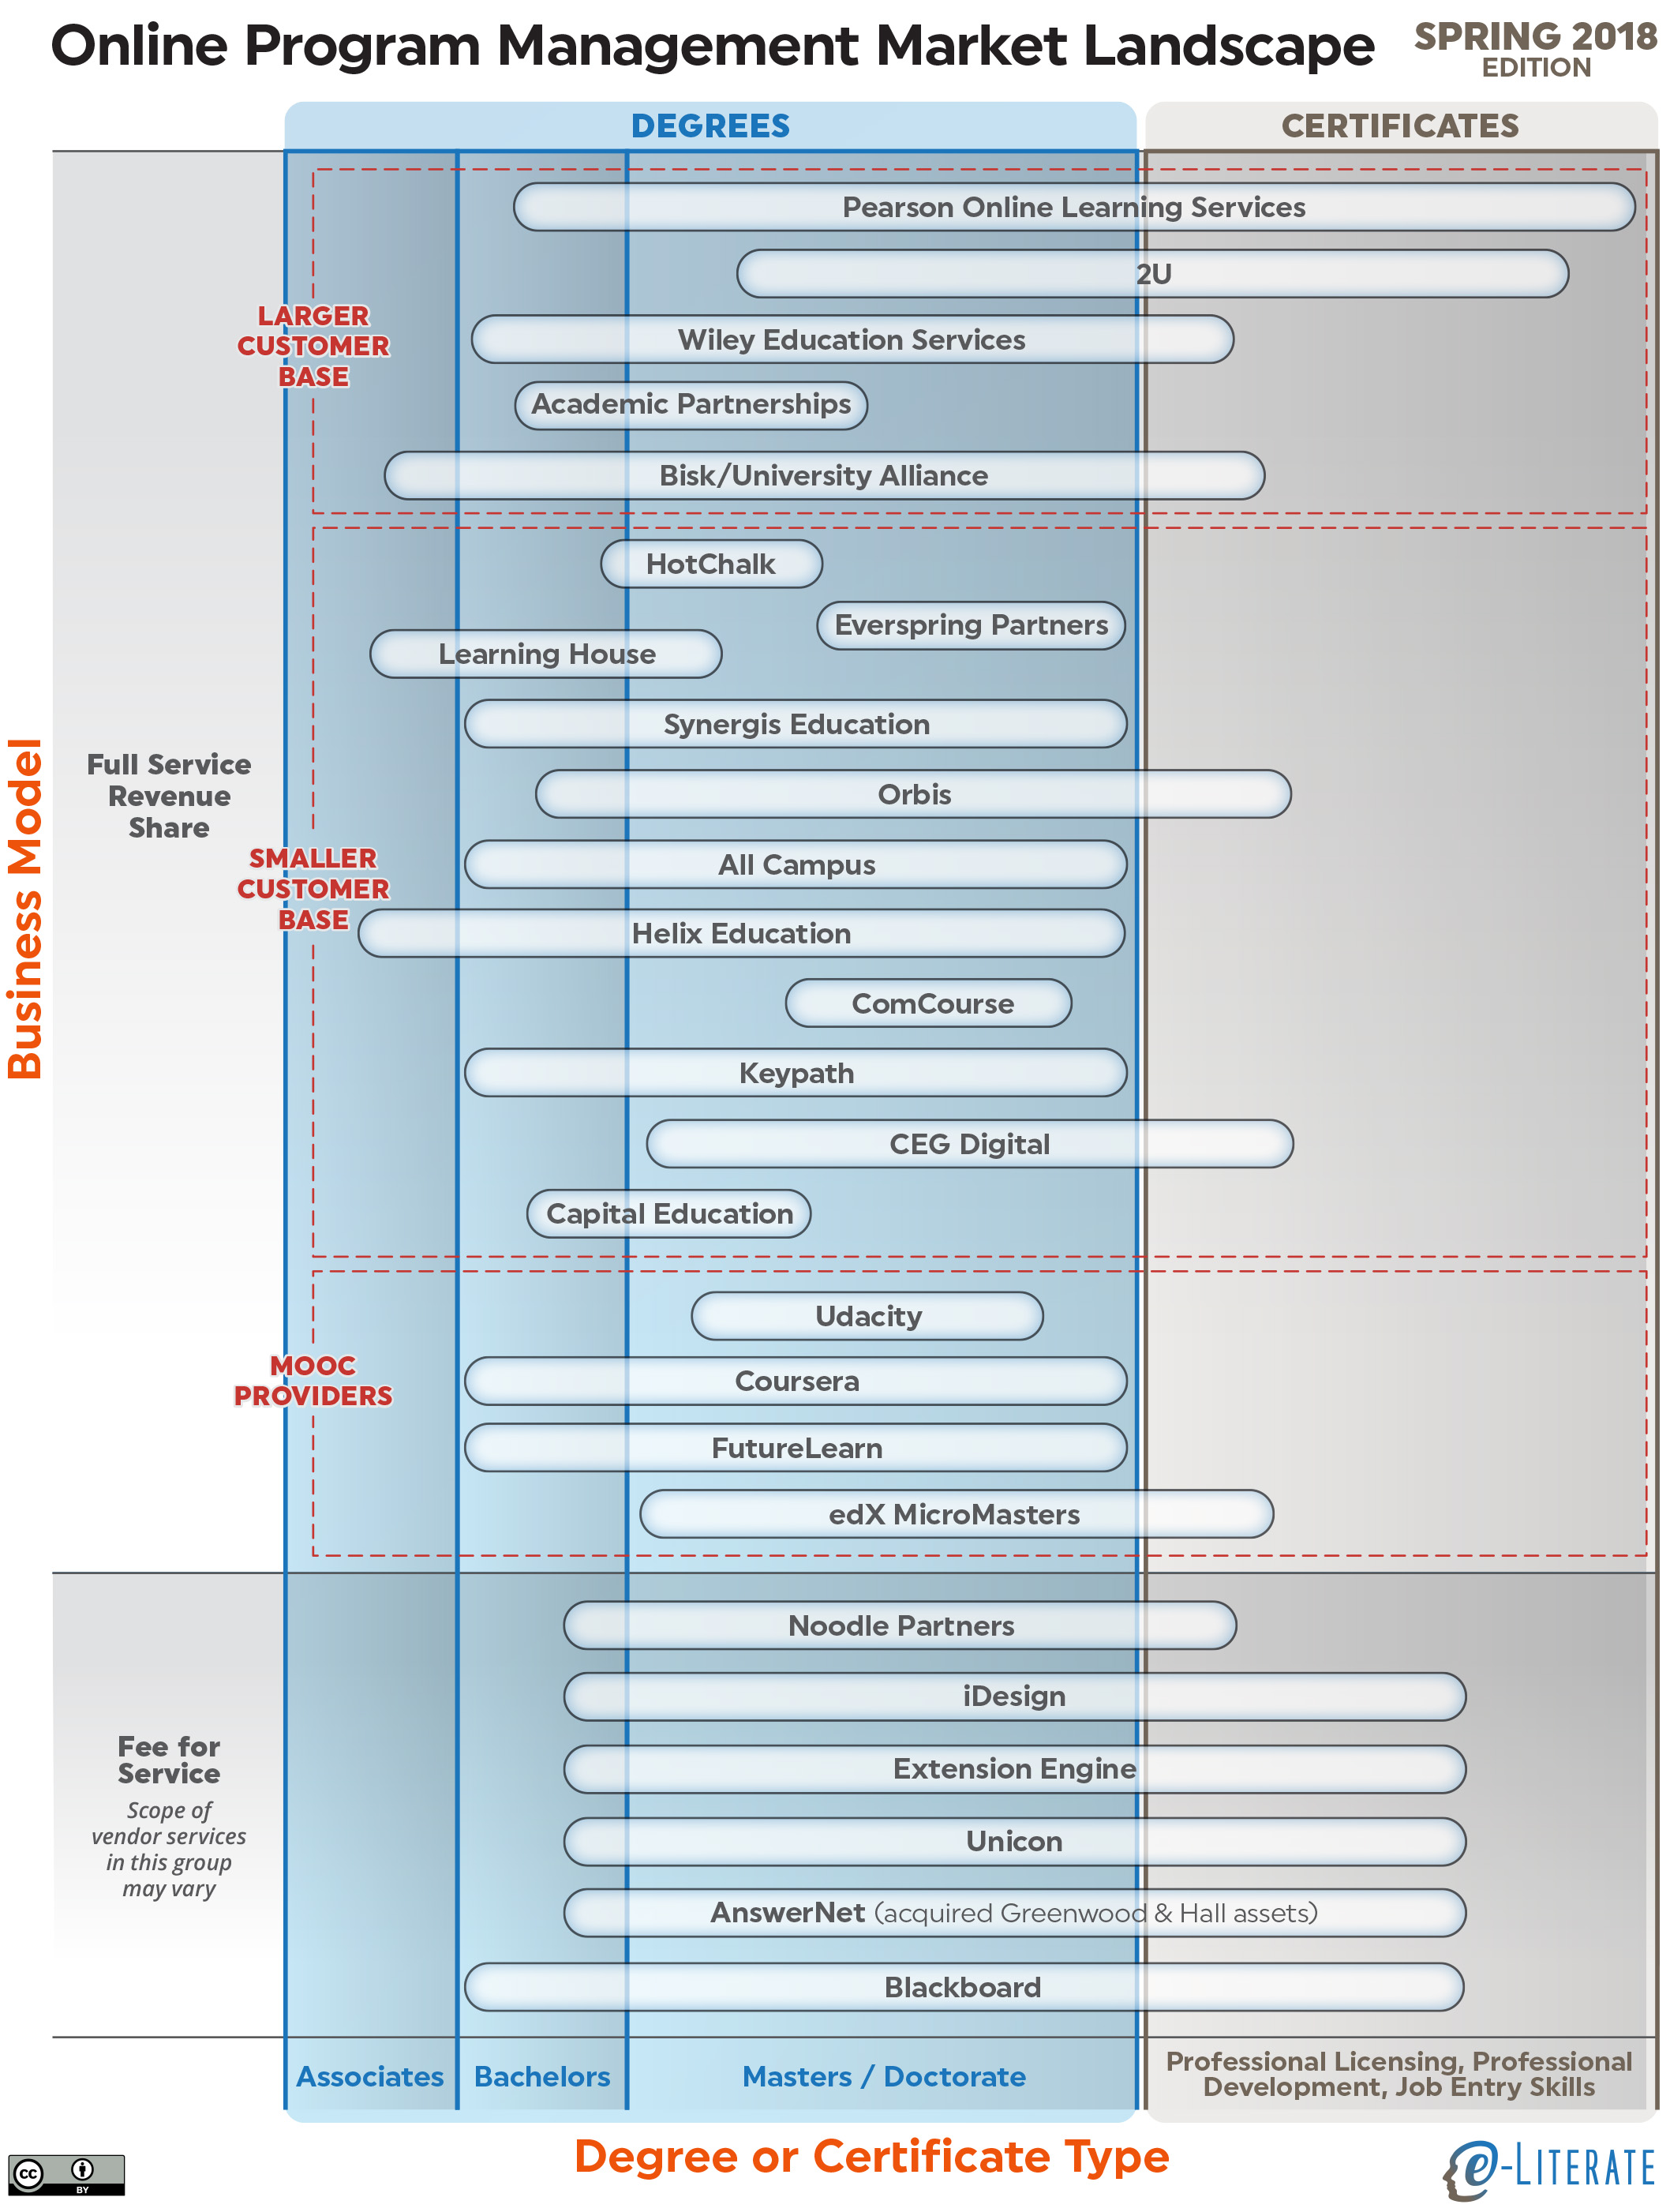
    This means that our landscape view of the market is temporal in nature – expect more shake ups and category changes as the OPM market continues to grow in new ways.

    Market landscape of OPM vendors

  • The ASU + GSV Conference was More GSV than Ever—And That’s Good

    The ASU + GSV Conference was More GSV than Ever—And That’s Good

    I’ve been struggling with how to characterize this year’s ASU + GSV Summit. Part of the problem is that it’s just become harder to sum up, for three reasons. First, the conference has gotten so big that it’s hard to see enough of it to get a representative sample. Second, as it has become a “must attend” conference for certain circles, it becomes harder for me to clear time away from meetings with people I know—both planned and unplanned—to be a fly on the wall. I can partly deal with that problem by bringing e-Literate colleagues who can be extra pairs of eyes and ears.

    But the third problem is harder. As the conference and the culture around it mature, the trends become harder to identify because they’re no longer fashion. We’re past the Year of the MOOC and the Year of Personalized Learning and all of that. Some of the less patient money has left, and some of it has refocused on corporate talent management. (Good luck with that; I don’t think it’s any easier than edtech.) A lot of the hype has faded into the background. The conversations seem more real and more focused on tackling important educational problems in realistic ways.

    Don’t get me wrong; there are still 12-year-olds in $300 jeans talking to 22-year-olds in $3,000 suits about how their math app is going disrupt education, and a few random dudes—and they are still often dudes, despite a sincere and concerted effort to make the conference more diverse—walking around wearing tinfoil headbands and loudly declaring, “I CAN READ STUDENTS’ MINDS!”

    But it’s easy to get distracted by the spectacle and miss the big picture. One way to look at the summit is as a giant peer review machine. Yes, with so many submissions, the quality will be uneven. And yes, sometimes a bad product will make it through the peer review process. And yes, you may find the process and the culture to be alien and unsettling if you’re not from that world. But from what I can see, the peer review machine is getting better in the sense that the pitches from startups to investors increasingly seem to focus on things that actually make sense in terms of developing products that are educationally useful.

    Coincidentally, I was reviewing some of the videos of the lightning talks from our Empirical Educator Project (EEP) summit this morning as I was thinking about this post. I was struck by how the presentation from RealizeIT, which is the type and size of company that would typically pitch at ASU + GSV, was not hugely different from the best of the pitches at that summit:

    The main difference is that, for the EEP crowd, the presentation focused on the collaborative research with University of Central Florida and others to improve student impact, while a good GSV pitch might pivot off the impact visualizations to talk about how their evidence of impact has led to increased sales. Having the latter conversation between companies and funders is an important piece in the ecosystem that was missing before the ASU + GSV conference. Trying to have the former type of conversation doesn’t work easily in the same forum with the latter type, partly for reasons of cultural differences. In the early years of ASU + GSV, the conference organizers—again, with the best intentions—worked very hard to try to host both conversations, with the result often being strong negative reviews from the academics. In more recent years at the summit, the academic needs seem to be coming in more organically via the companies as intermediaries and self-selecting academics who are, for lack of a better term, bi-cultural.

    The one trend that did stand out at ASU + GSV, which I think is related to the above, is a lot of activity around Online Program Management (OPM) companies. Something fairly deep is happening in this space. Right now, most of the buzz is around the debate over whether the future of OPM business models is in revenue share or fee-for-service. I think that’s a red herring, created in part by the bad blood between some individuals at Noodle Partners—one of the leading proponents of the fee-for-service model—and 2U—the darling of the revenue share crowd. The truth is that, while there is some overlap in competition, what we are seeing increasingly is a range of different companies, many but not all of which are currently labeled as “OPMs,” that offer different bundles of services and different financing models that are best suited for solving different kinds of problems. The common thread is that there is a growing range of service businesses that help colleges and universities develop strong, student-centered degree and certificate programs, either by creating new ones or strengthening existing ones. We don’t have a good term or set of subcategories for this class of businesses, of which traditional OPM is one subcategory. (And some of these business are pretending that they are not service businesses for a variety of reasons, but that’s another story.)

    To me, this squishiness in the OPM market is a sign that more and more schools are serious enough about learning to be systematically better at supporting student success that they are increasingly willing to pay for help. And that change in prioritization is potentially good for everyone. And ASU + GSV has become a good vantage point for spotting that kind of change—if you look hard enough.

  • Rio Salado College As Exemplar: A critical external view

    In yesterday’s post I described how a review of two courses at Rio Salado College indicated reasons to question the use of this school in the ASU / BCG case study report on Digital Learning ((Disclosure: Our e-Literate TV series was funded in part by the Bill & Melinda Gates Foundation who also funded the ASU / BCG study.)). The report, titled “Making Digital Learning Work: Success Strategies From Six Leading Universities and Community Colleges”, has the following description [emphasis added]:

    How can the use of digital technologies in postsecondary education impact students’ access to education, student outcomes, and the return on investment for students and institutions? What are the biggest challenges for an institution seeking to implement high-quality digital learning opportunities? What promising practices enable an institution to achieve impact at a larger scale? [snip]

    The answers, at least in part, lie in case studies of six colleges and universities: Arizona State University, the University of Central Florida, Georgia State University, Houston Community College, Kentucky Community and Technical College System, and Rio Salado Community College. The first three institutions in this list are public research universities, representing different geographic populations and access missions. The other three institutions include two community colleges and a state-wide community college system.

    These six institutions have a strong track record of using digital learning to serve large, socioeconomically diverse student populations, and each has been a pioneer in innovating to expand access to postsecondary education, improve student outcomes, and provide higher education at an affordable cost.

    Let’s look at the track record of Rio Salado College in terms of aggregate academic student outcomes to see how appropriate it is to include them as an exemplar in such a case study-based report. For much of my analysis, I looked at the 862 public 2-year colleges fully reporting data in the Fall 2016 IPEDS data set.

    Reduced Expenditures

    The primary claim made in the ASU / BCG report is that Rio Salado is has reduced costs.
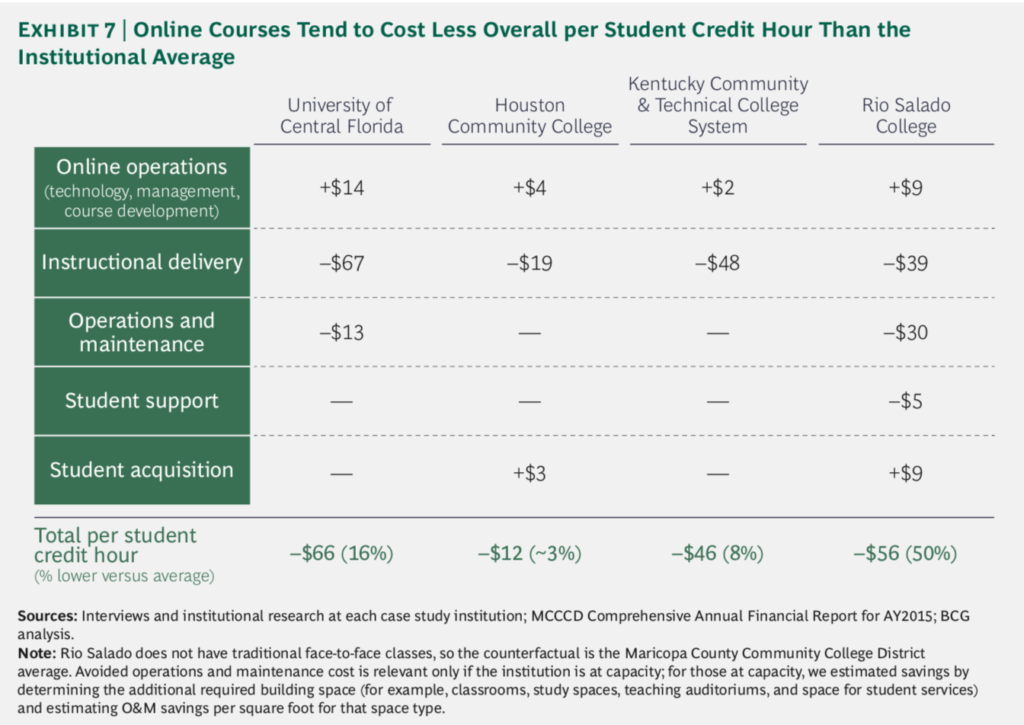
    This claim does hold up to scrutiny, as Rio’s $89 of instructional delivery costs per student credit hour and $16 of student services costs are 10th and 9th lowest in the country for the 862 colleges I reviewed.

    The primary outcomes claims made in the case study quickly brush off the standard metrics for Rio.

    Rio Salado’s success is not defined solely by improvements in graduation and retention rates. In particular, the college has a high transfer-out rate (32% compared to an average of 19% for other MCCCD colleges [ed. – the other schools in the Maricopa County Community College District]), and the students who transfer to Arizona universities from Rio Salado have a 74% four-year graduation rate—3 percentage points higher than the average for other MCCCD transfer students. At Rio Salado itself, students’ course-level success rates have slowly been improving over time, to about 64% in 2016.

    Graduation and Retention Rates

    It is all well and good to point out the importance of transfer students, but we should not ignore graduation and retention rates. And we should explore whether the data supports the phrase “improvements in graduation and retention rates”.

    The report describes Rio’s investment in a suite of advising tools.

    Obtaining these advisory tools required an initial investment of $1 million, but the tools pay for themselves by increasing Rio Salado’s term-to-term retention by 7%, increasing ROI through improved student progress and the additional tuition dollars that the institution receives from retained students.

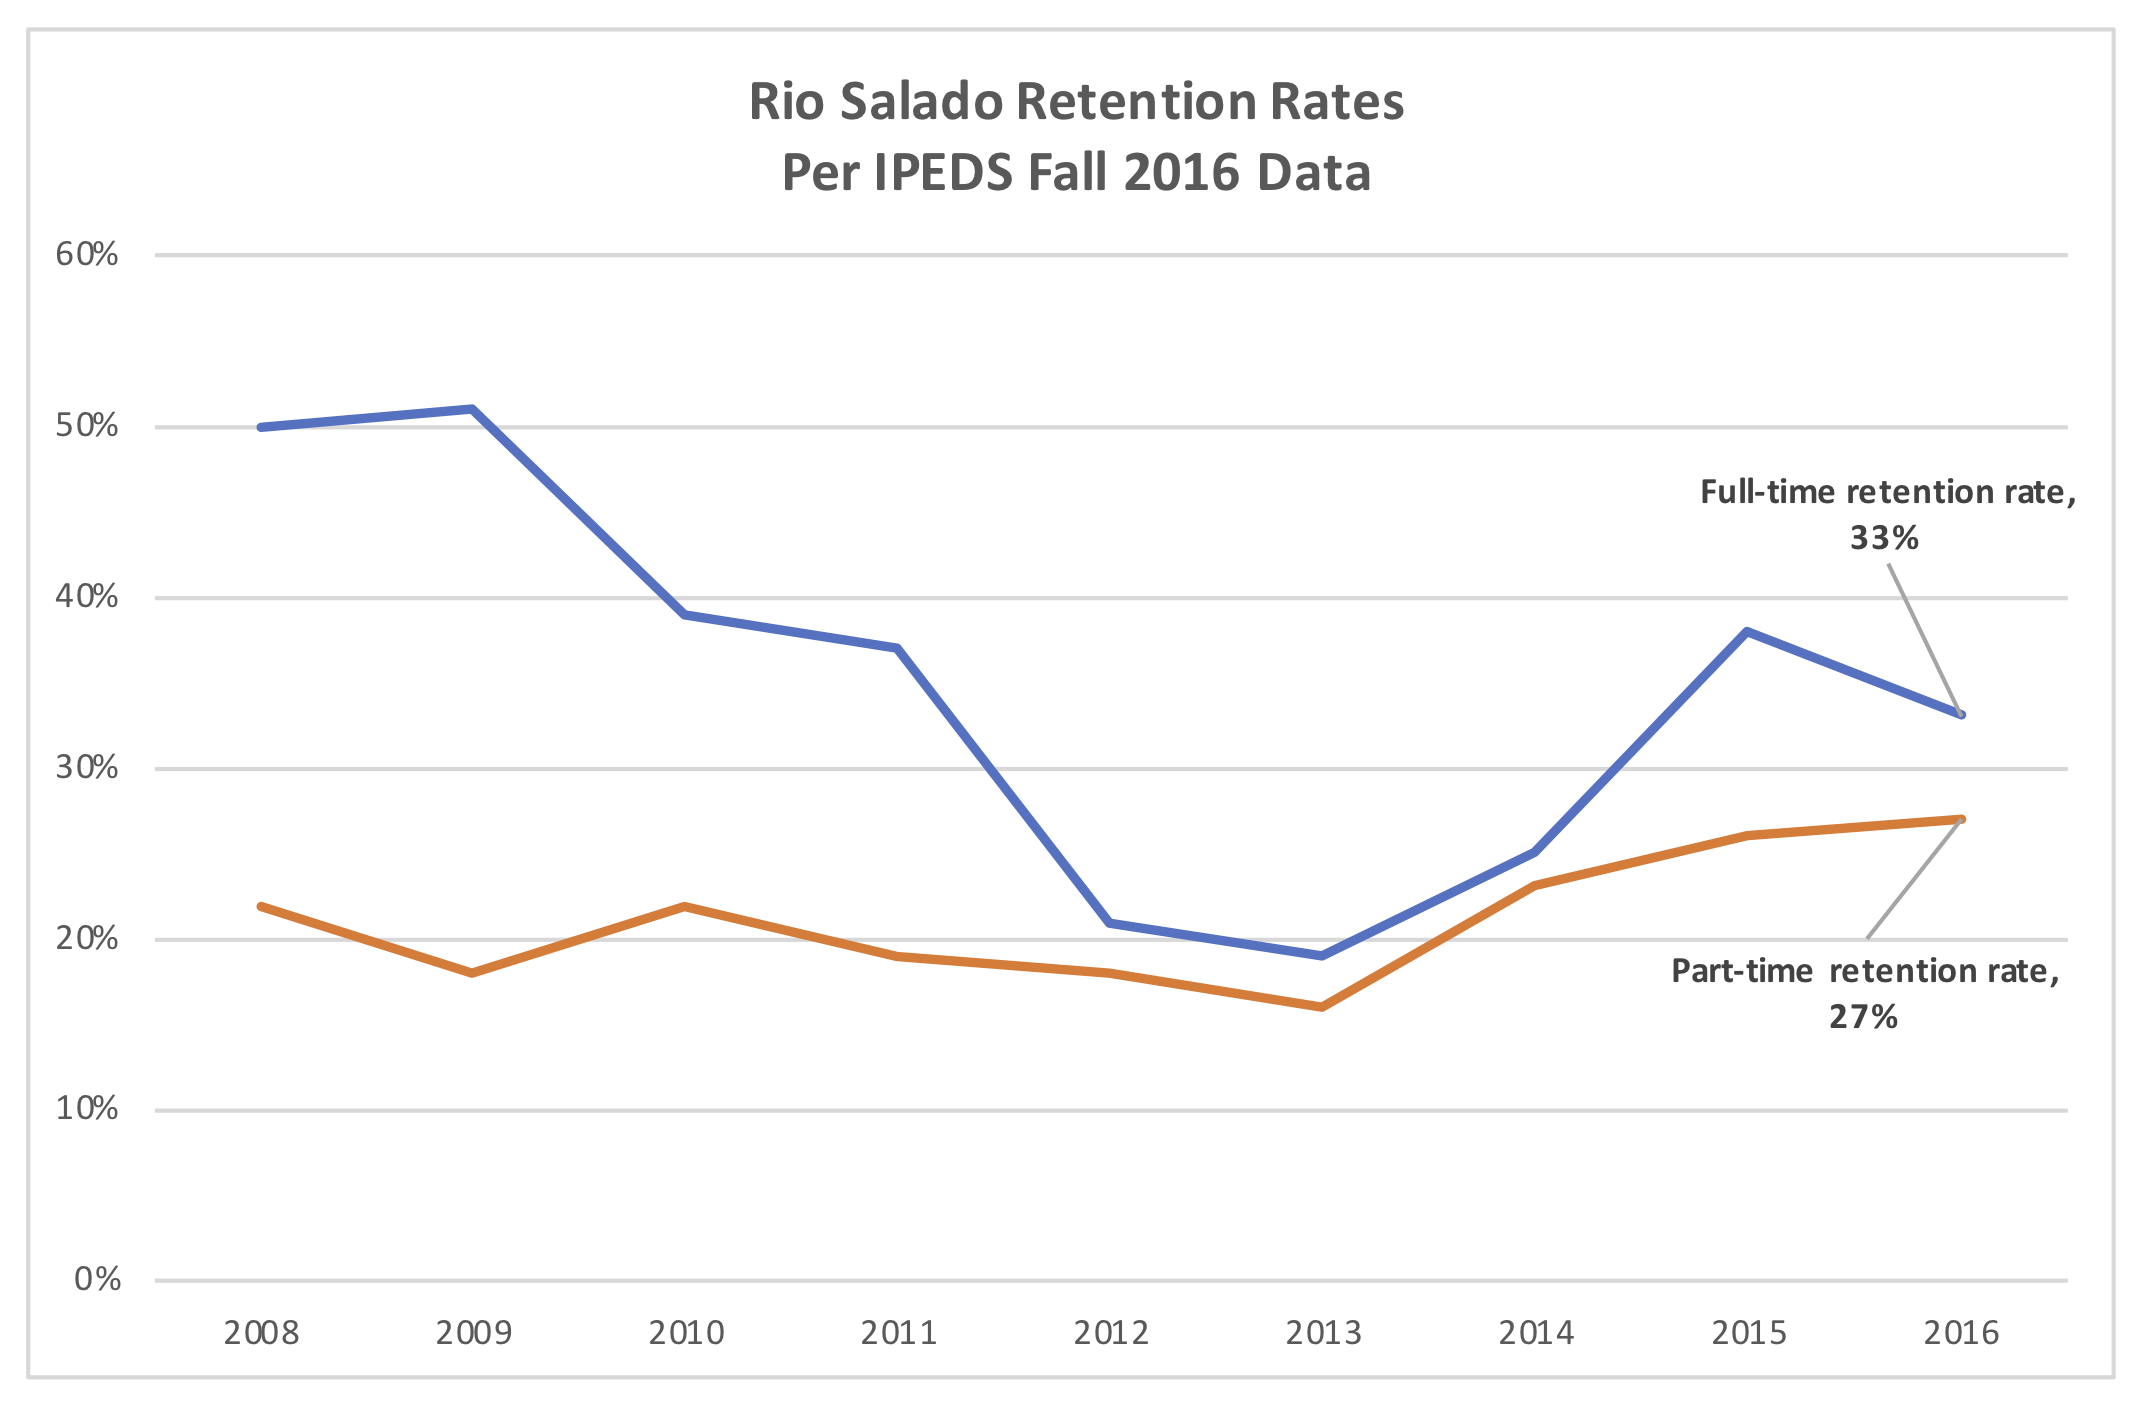
    Looking at IPEDS data, we can see Year 1 to Year 2 retention rates (not quite the same as term-to-term), and it shows improvement since 2013. Unfortunately, Rio’s retention rates for full-time and part-time students are both in the bottom 10% of all community colleges at 33% and 27%, respectively. And the full-time rate is lower than it was prior to 2011.
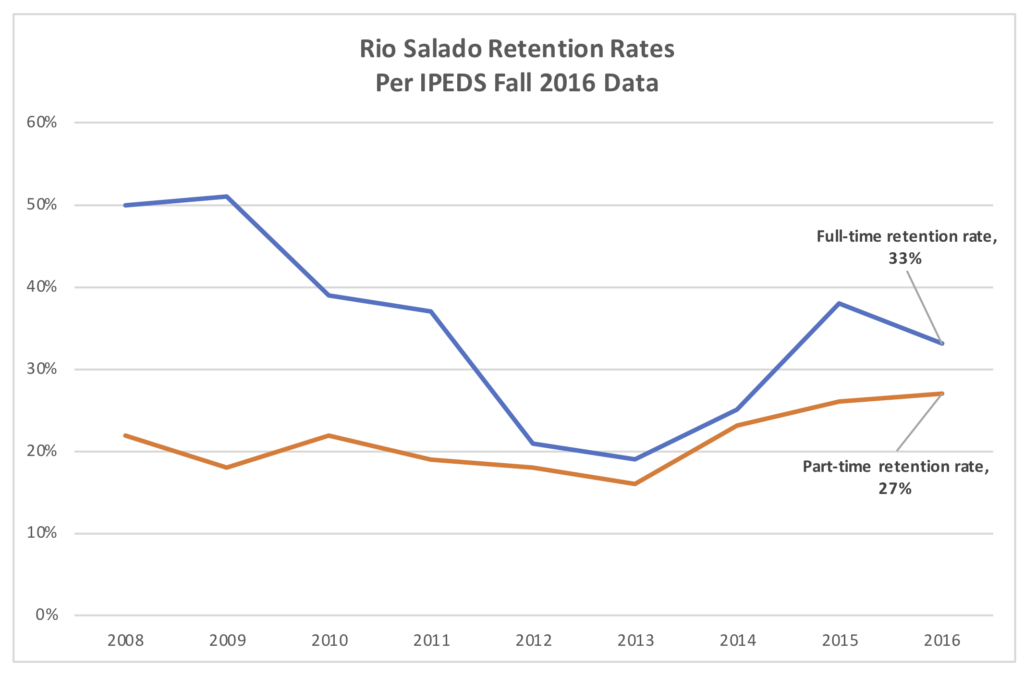
    Rio Salado Year 2 Retention Rates

    While the ASU / BCG report does not mention graduation rates directly, there have been several claims made about Rio’s numbers in other publications.

    The problem is that Rio Salado’s 4-year graduation rate for first-time full-time students as reported in IPEDS is 5% – the second lowest of any public 2-year college in the nation. How can we resolve this discrepancy?

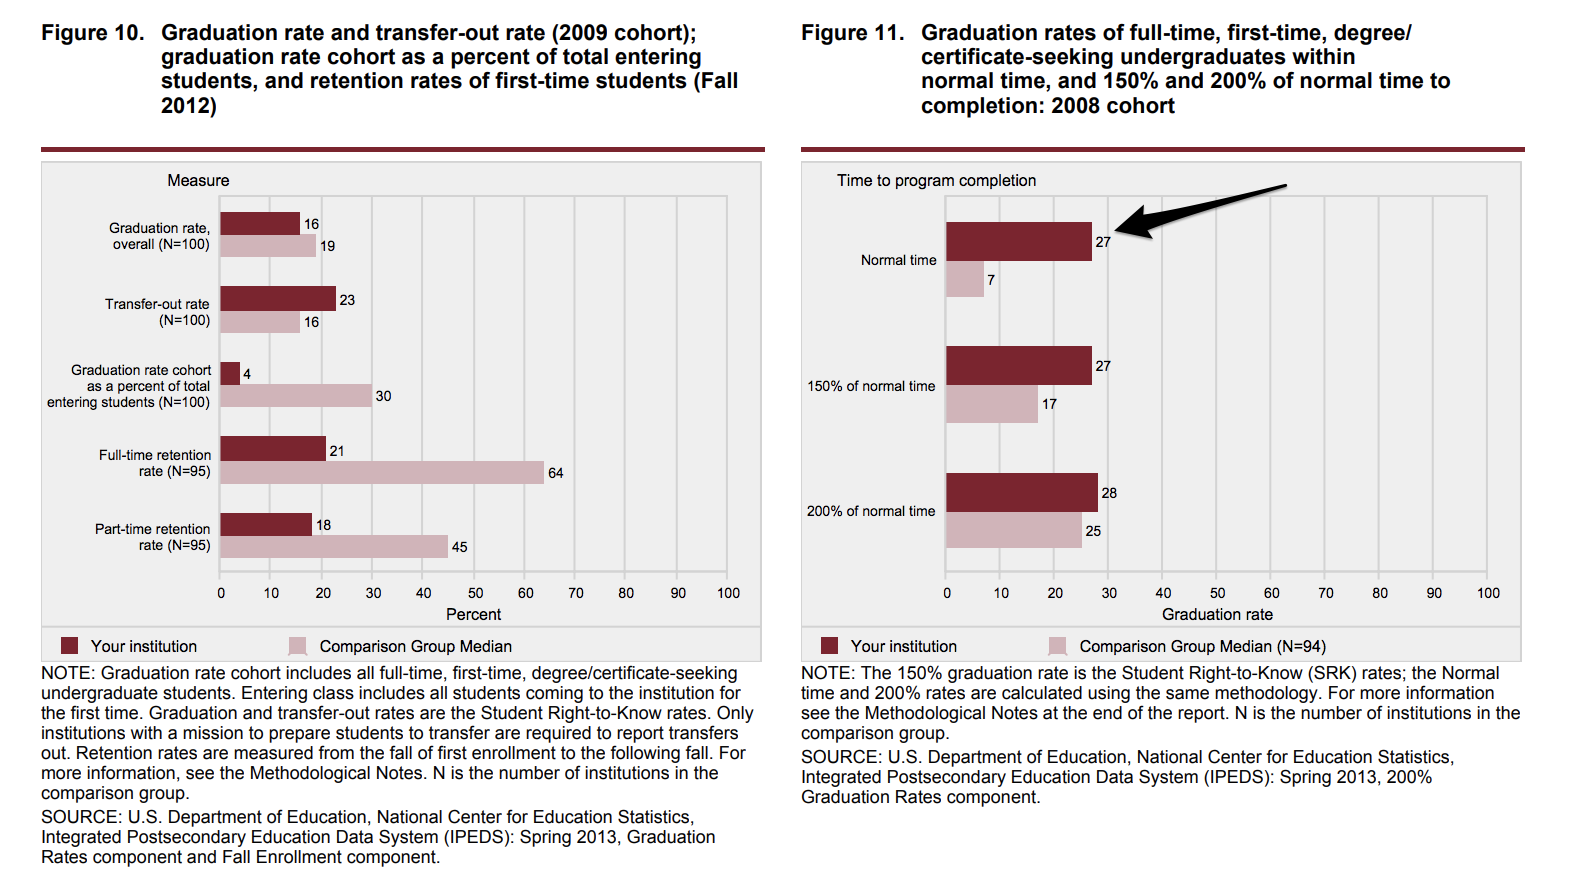
    The key to understanding the claims in these four articles is to follow the two links, which both point to a customized IPEDS Feedback Report from 2013 for Rio against their selection of 100 peer institutions.
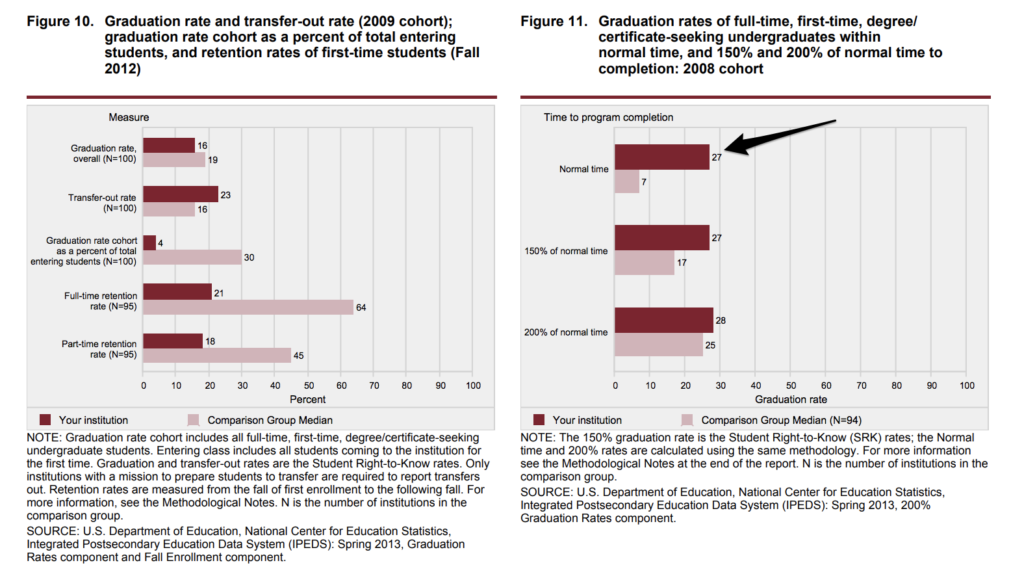
    Figures 10 and 11 from IPEDS report

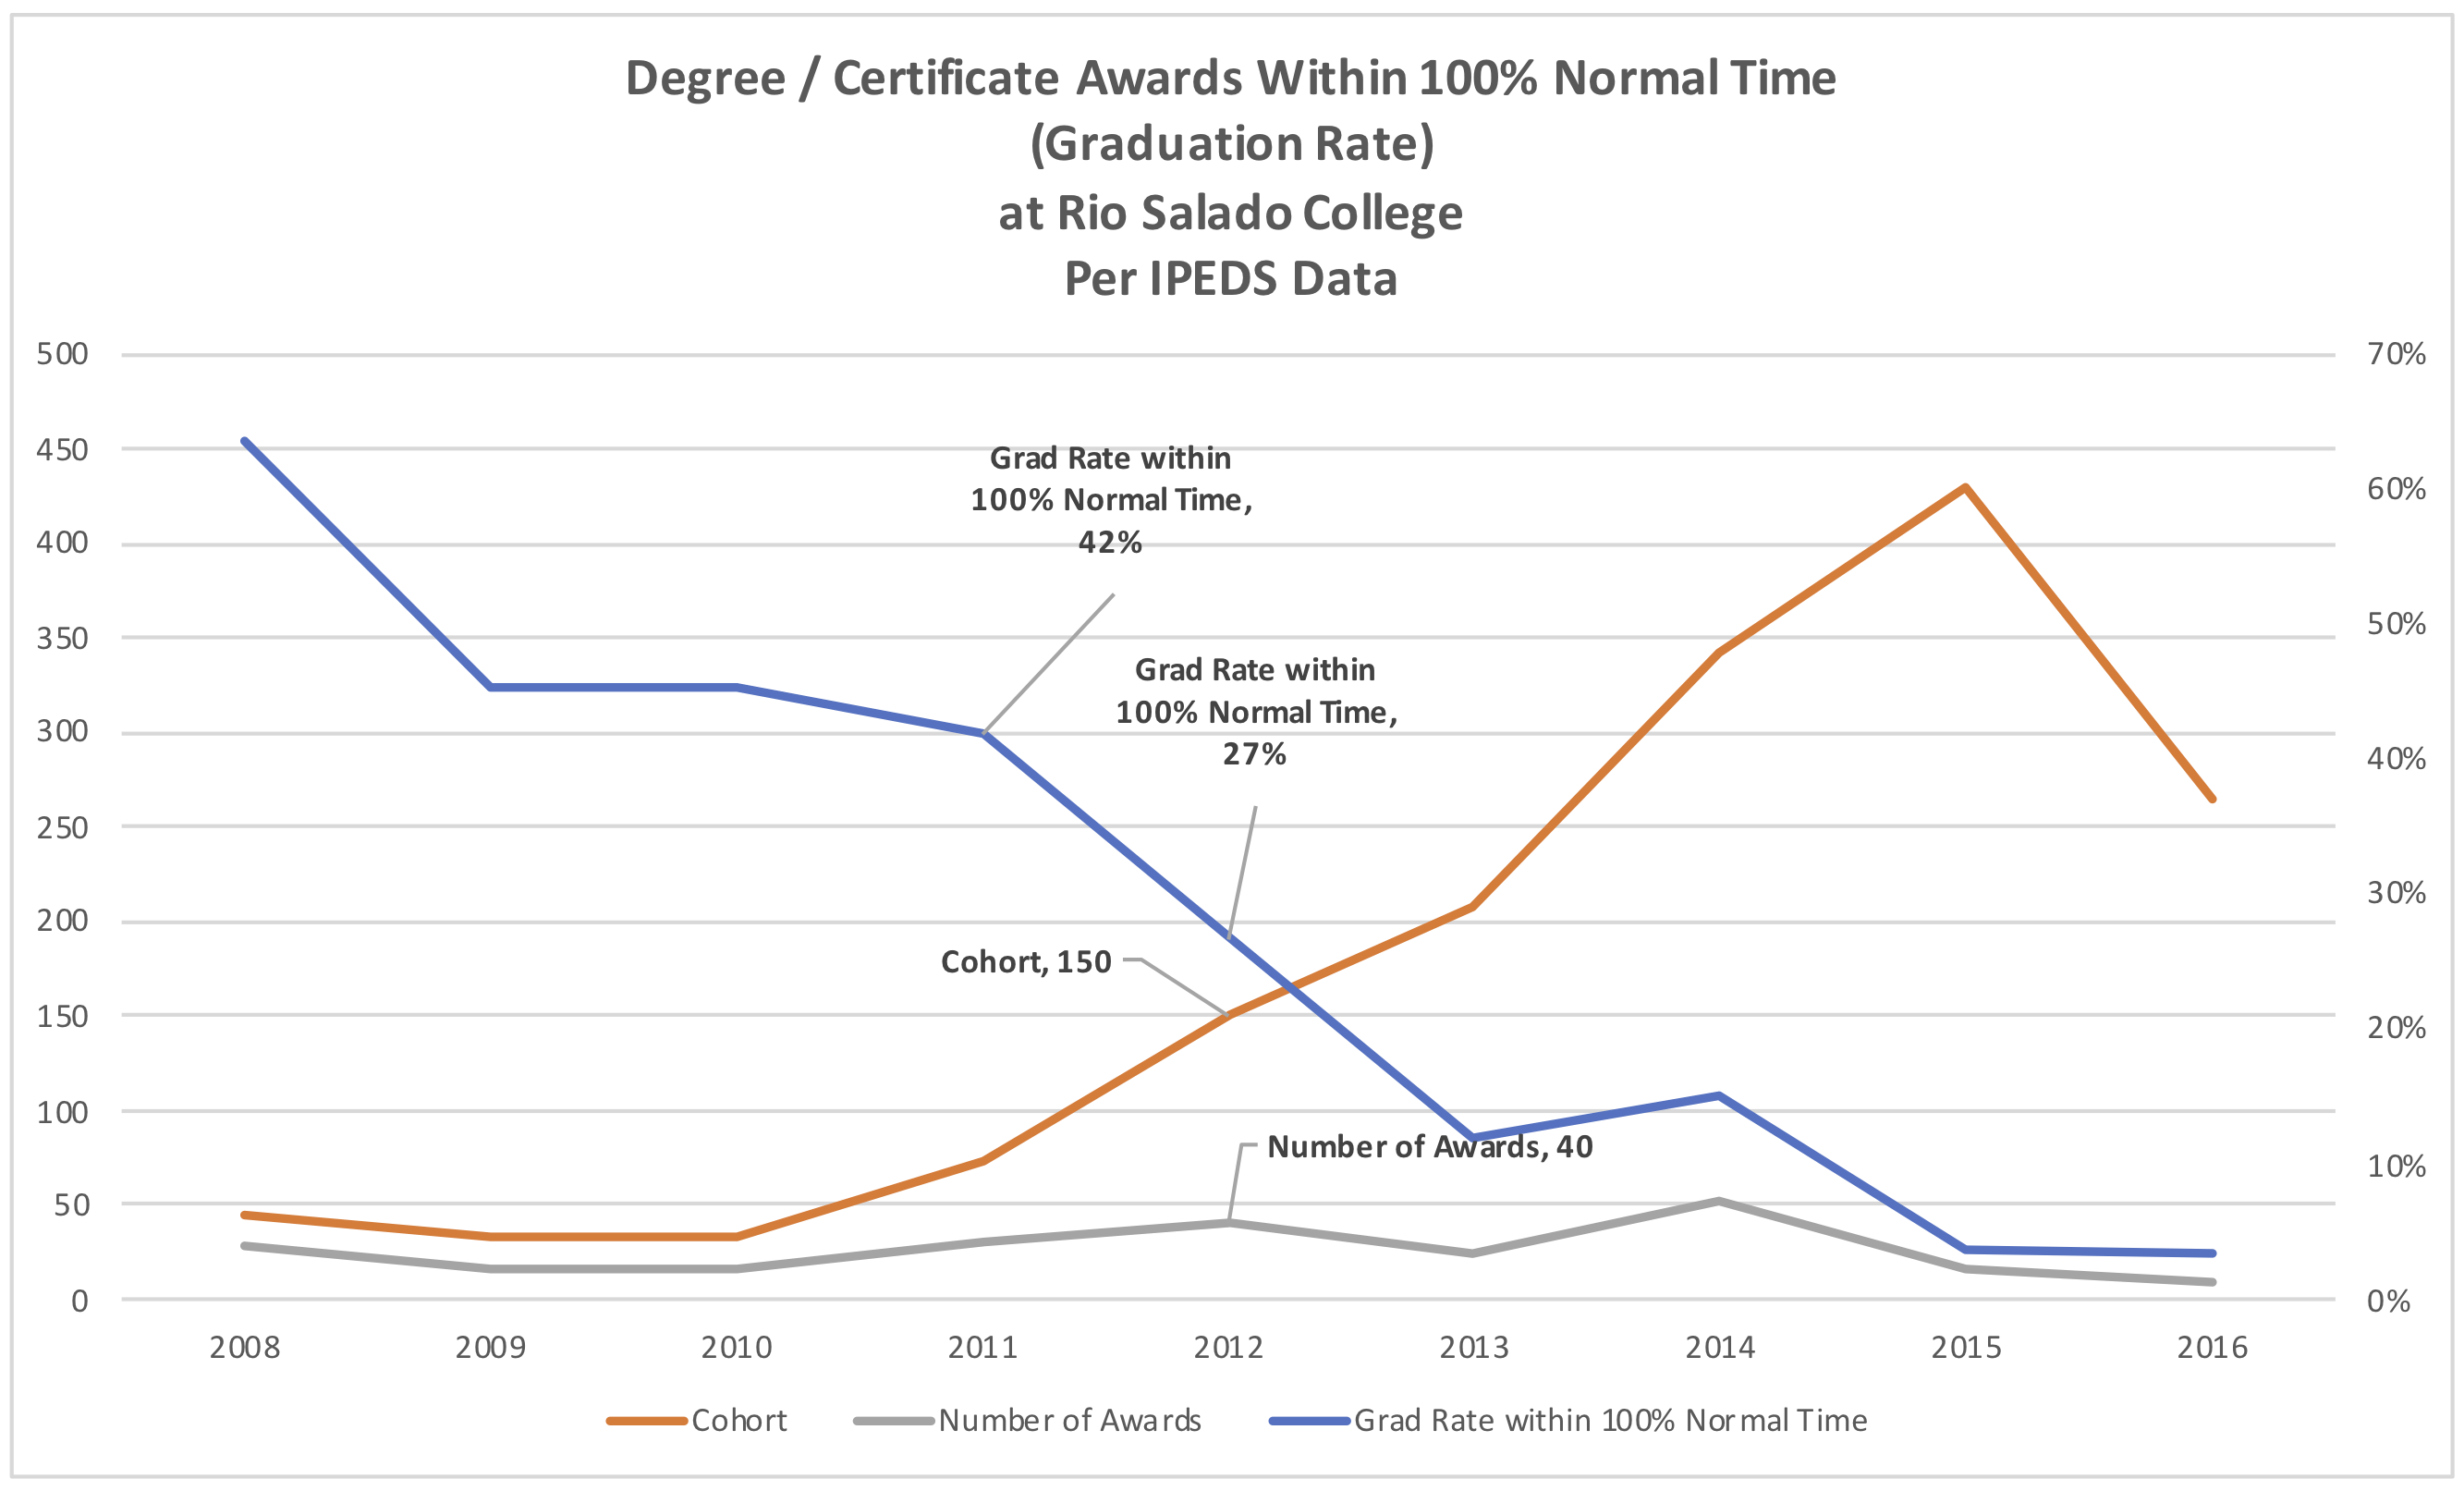
    This measure captures any award – degree or certificate – for a small cohort of entering full-time students at Rio from 2009. If you trace that data through IPEDS, you see that this measure is for a 150-student cohort (in 2012) out of the 45,000+ students at Rio.
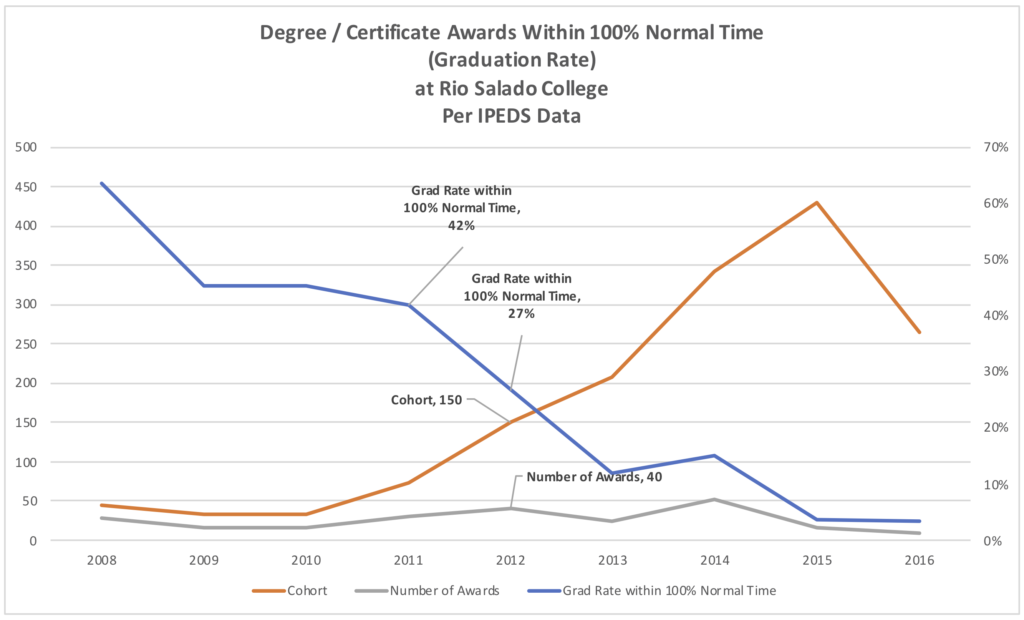
    Using this specific metric, you can find the 42% graduation rate in 2011, and the “four times greater” rate of 27% in 2012, both as the rate plummets from 64% in 2008 to 3% in 2016.

    Using broader, up-to-date metrics for graduation and retention rates as well as the new IPEDS outcomes measures (which allows comparison outside of just full-time first-time cohorts), we see that Rio Salado College has some of the lowest student outcomes measures in the country.
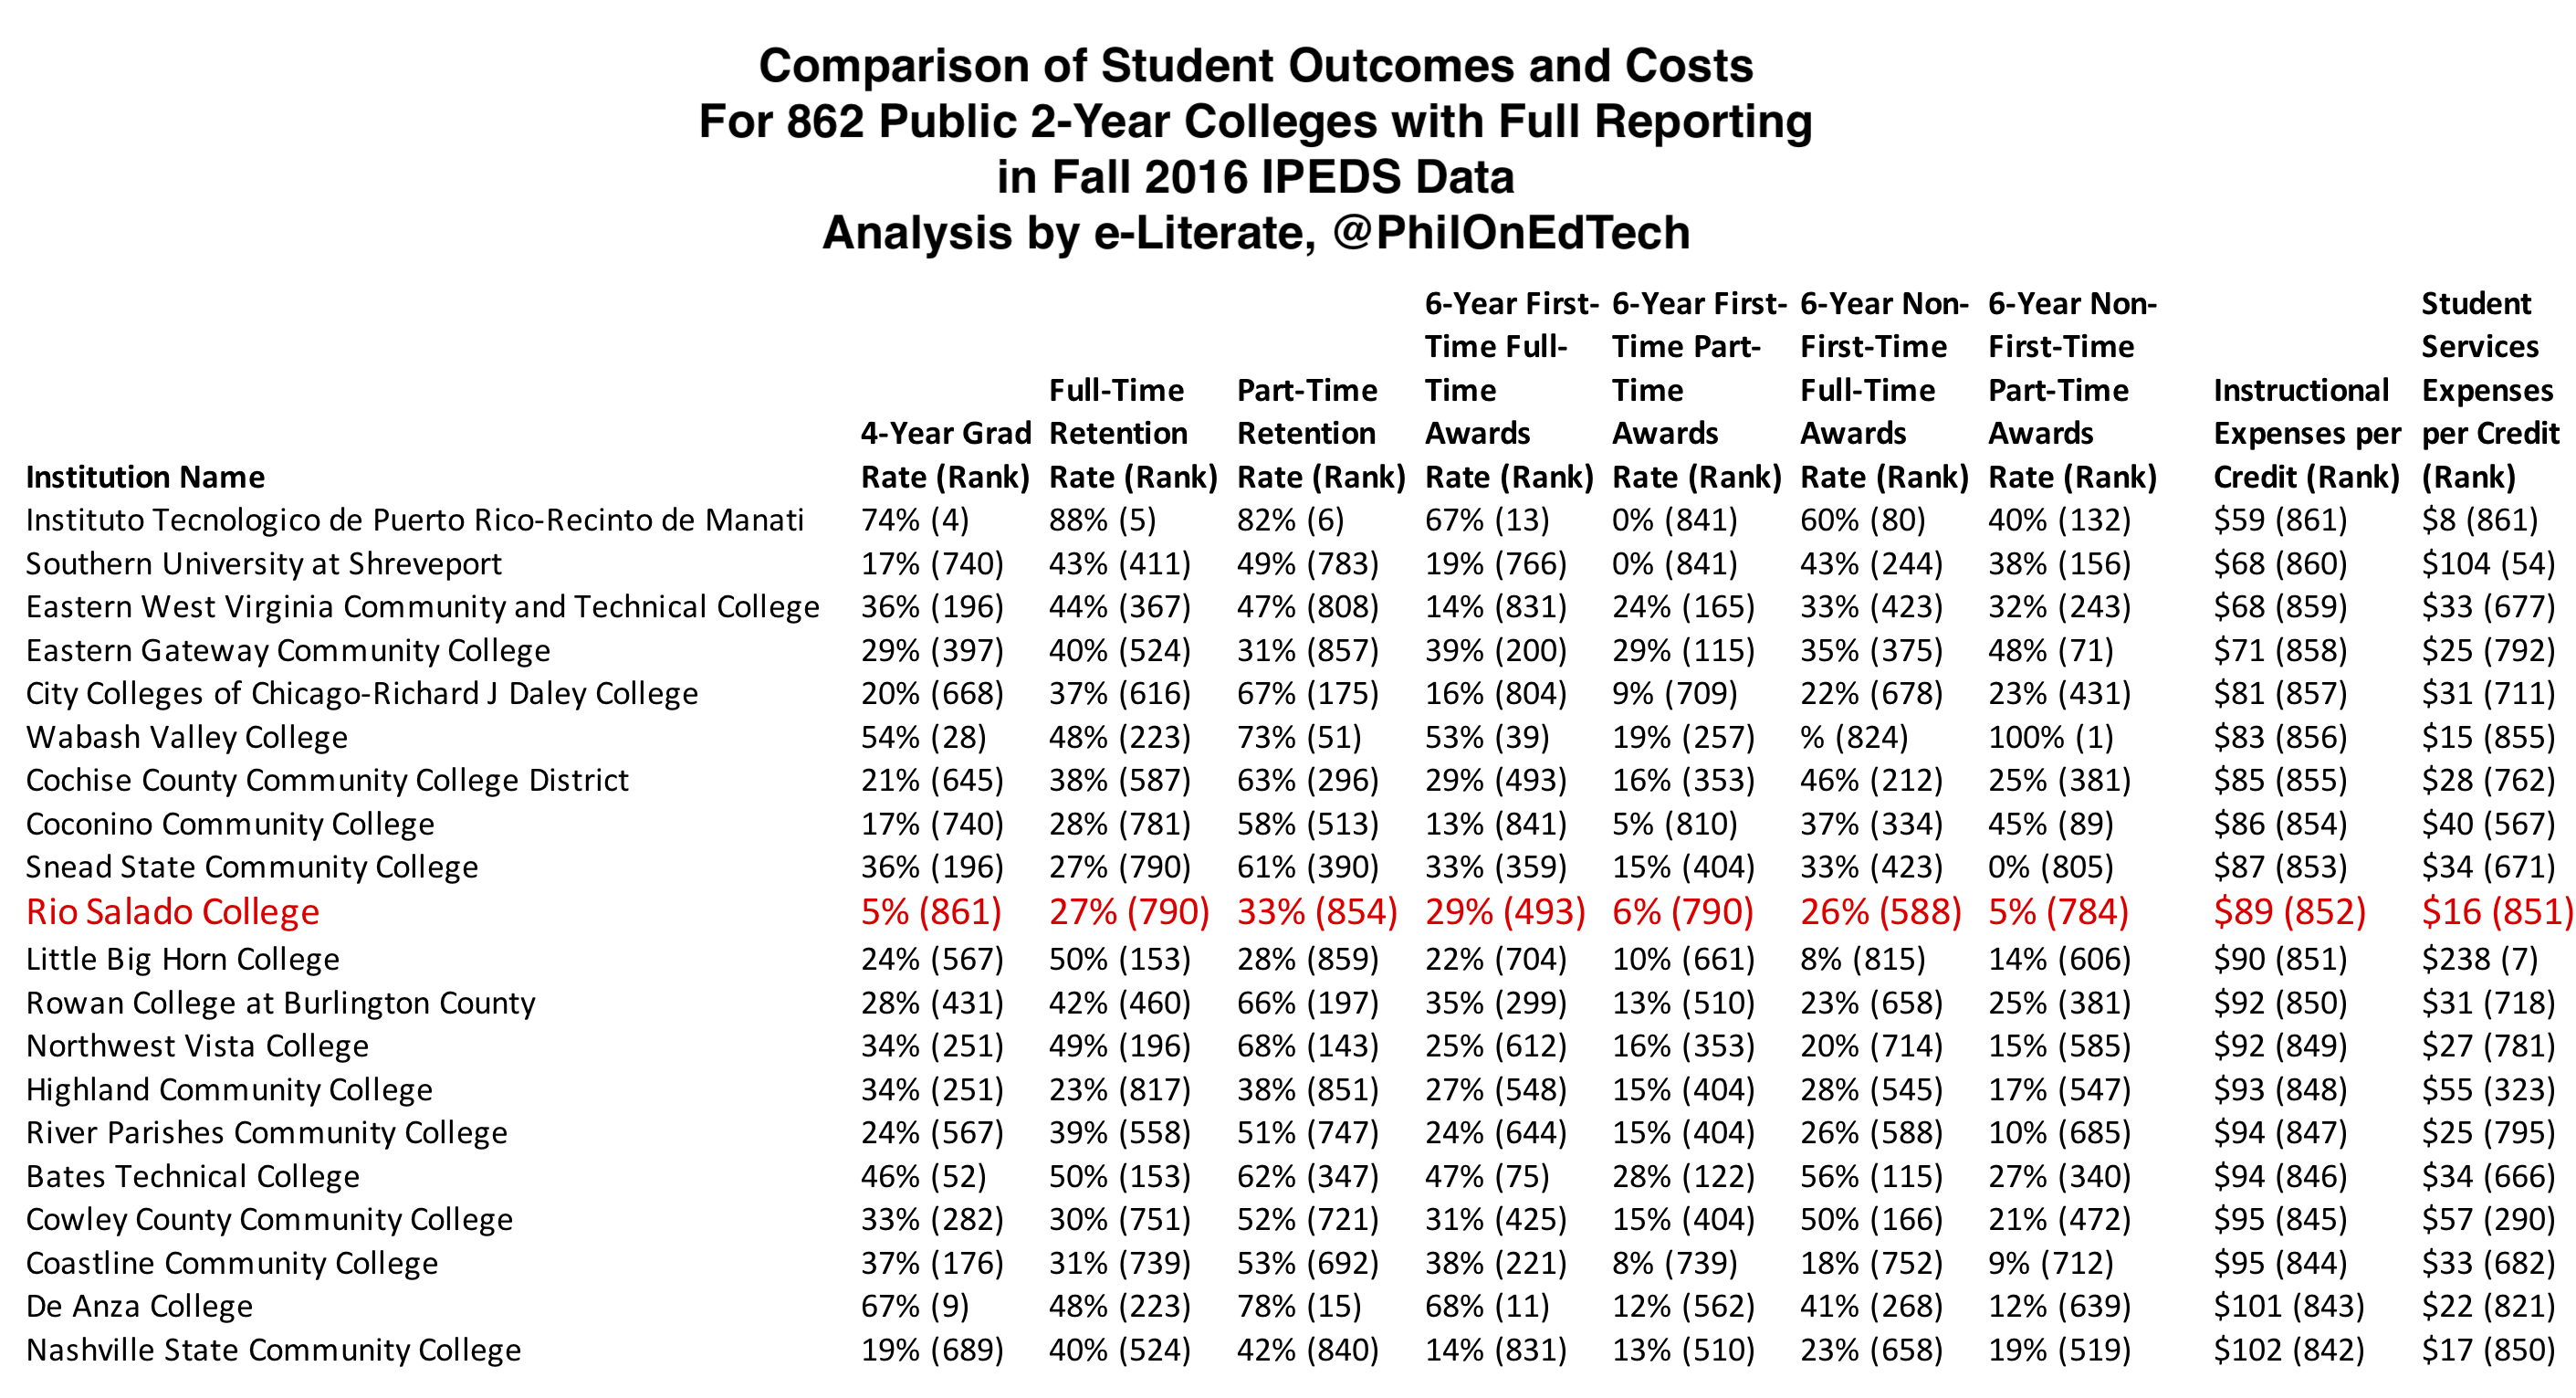
    For all but two measures (6-year First-Time Full-Time Awards and 6-year Non-First-Time Full-Time Awards), the performance is in the bottom 10% of all colleges in the study. For those two awards measures, the performance is in the bottom half of the country and represents just 11% of the student body.

    Transfer Rates

    What we are left with are reports about high transfer rates and subsequent success rates 3% higher than other transfers out of the same district. The IPEDS data set now includes transfer rates in its new Outcomes Measures section, and it is true that Rio Salado College does transfer out a significant portion of students. For all cohorts defined below, Rio is in top 20% of public 2-year institutions.

    • First-Time Full-Time Students: 39% transfer rate, Rank 170 out of 862
    • First-Time Part-Time Students: 47% transfer rate, Rank 112 out of 862
    • Non-First-Time Full-Time Students: 46% transfer rate, Rank 196 out of 862
    • Non-First-Time Part-Time Students: 59% transfer rate, Rank 121 out of 862

    Note that this data indicates that students transferred to another institution and are still enrolled there. This data does not indicate what portion of the transfers were planned versus students deciding to move on for other reasons. Nevertheless, for a community college, especially one with very close ties to ASU (I have been told that a large percentage of Rio students are ASU students trying to fill out their schedule based on saving money and more convenient schedules), this is a favorable metric.

    I cannot provide independent confirmation on the subsequent success rates, so we’ll accept that claim at face value.

    Case Study Questions

    I should note that Rio Salado College does provide accurate information on the metrics mentioned in this post, both through IPEDS reporting and through their Research & Planning section of the web site. The picture that emerges from the aggregate outcomes data is of a large school that:

    • transfers out greater than average percentage of students;
    • is just below average for awarding certificates for full-time students;
    • is among the poorest performing in the country for retaining students;
    • is among the poorest performing in the country for awarding degrees; and
    • is among the poorest performing in the country for awarding certificates for part-time students.

    At best, this is a school with mixed results that should not simply be labeled a success without caveats or explanations.

    One question we should ask is whether it is appropriate to hold up a school with some of the lowest student outcomes measures in the country as an exemplar. Yes, Rio Salado has found a way to spend as little as possible on instruction and student support services, and yes, a lot of students transfer out, but that is not enough. We need greater evidence of student success if we are to use them as a case study for others to emulate. And we also need a more robust genre of a case study that looks across, at a minimum, a relatively standard set of publicly-available information, and deeper dives where appropriate, to understand educational practices and their impacts on students. These case studies should present information in context – the good and the bad – since education is complex and challenging, and a clear focus on evidence will benefit all parties in the end.

  • Rio Salado College As Exemplar: A critical internal view

    Rio Salado College As Exemplar: A critical internal view

    10 days ago Arizona State University (ASU) and the Boston Consulting Group (BCG) released a report, supported by the Bill & Melinda Gates Foundation (BMGF) ((Disclosure: Our e-Literate TV series was funded in part by the Bill & Melinda Gates Foundation.)), titled “Making Digital Learning Work: Success Strategies From Six Leading Universities and Community Colleges”. The basic idea [emphasis added]:

    How can the use of digital technologies in postsecondary education impact students’ access to education, student outcomes, and the return on investment for students and institutions? What are the biggest challenges for an institution seeking to implement high-quality digital learning opportunities? What promising practices enable an institution to achieve impact at a larger scale? [snip]

    The answers, at least in part, lie in case studies of six colleges and universities: Arizona State University, the University of Central Florida, Georgia State University, Houston Community College, Kentucky Community and Technical College System, and Rio Salado Community College. The first three institutions in this list are public research universities, representing different geographic populations and access missions. The other three institutions include two community colleges and a state-wide community college system.

    These six institutions have a strong track record of using digital learning to serve large, socioeconomically diverse student populations, and each has been a pioneer in innovating to expand access to postsecondary education, improve student outcomes, and provide higher education at an affordable cost.

    The methodology is a case study of each school, and the report then takes a stance on what other institutions should do.

    Now is the time for leaders to champion the potential of digital learning to open the doors of higher education wider and to improve student outcomes, while operating more efficiently and at lower cost. The journey of each college or university will be unique, but the set of promising practices described in this report may serve as a useful guide for all institutions.

    There are multiple methods to evaluating a school; it turns out that some are more meaningful than others, and it is always helpful to start with what students experience in actual courses. The ASU / BCG report provides useful context on course design.

    At Rio Salado, 22 full-time faculty chairs develop courses with the support of a central team that includes subject-matter experts, instructional designers, media support staff, and production staff. About 1,500 adjunct faculty members teach the courses, which they can personalize by adding an introductory message or video for each module.

    It turns out that I have access to two courses – ENG102 (First Year Composition) and EED200 (Foundations of Early Childhood Education) – and this gives an opportunity to better understand the student experience. What these courses indicate, however, is a troubling lack of meaningful interaction between faculty and students.

    Looking at ENG102, the course materials is Rio Salado developed courseware embedded in their custom course management system, RioLearn. The materials appear to be quite extensive, and all materials are available at the start of the term in 14 lessons. To find actual due dates, students have to go to the gradebook, as no specific dates are included in the courseware.

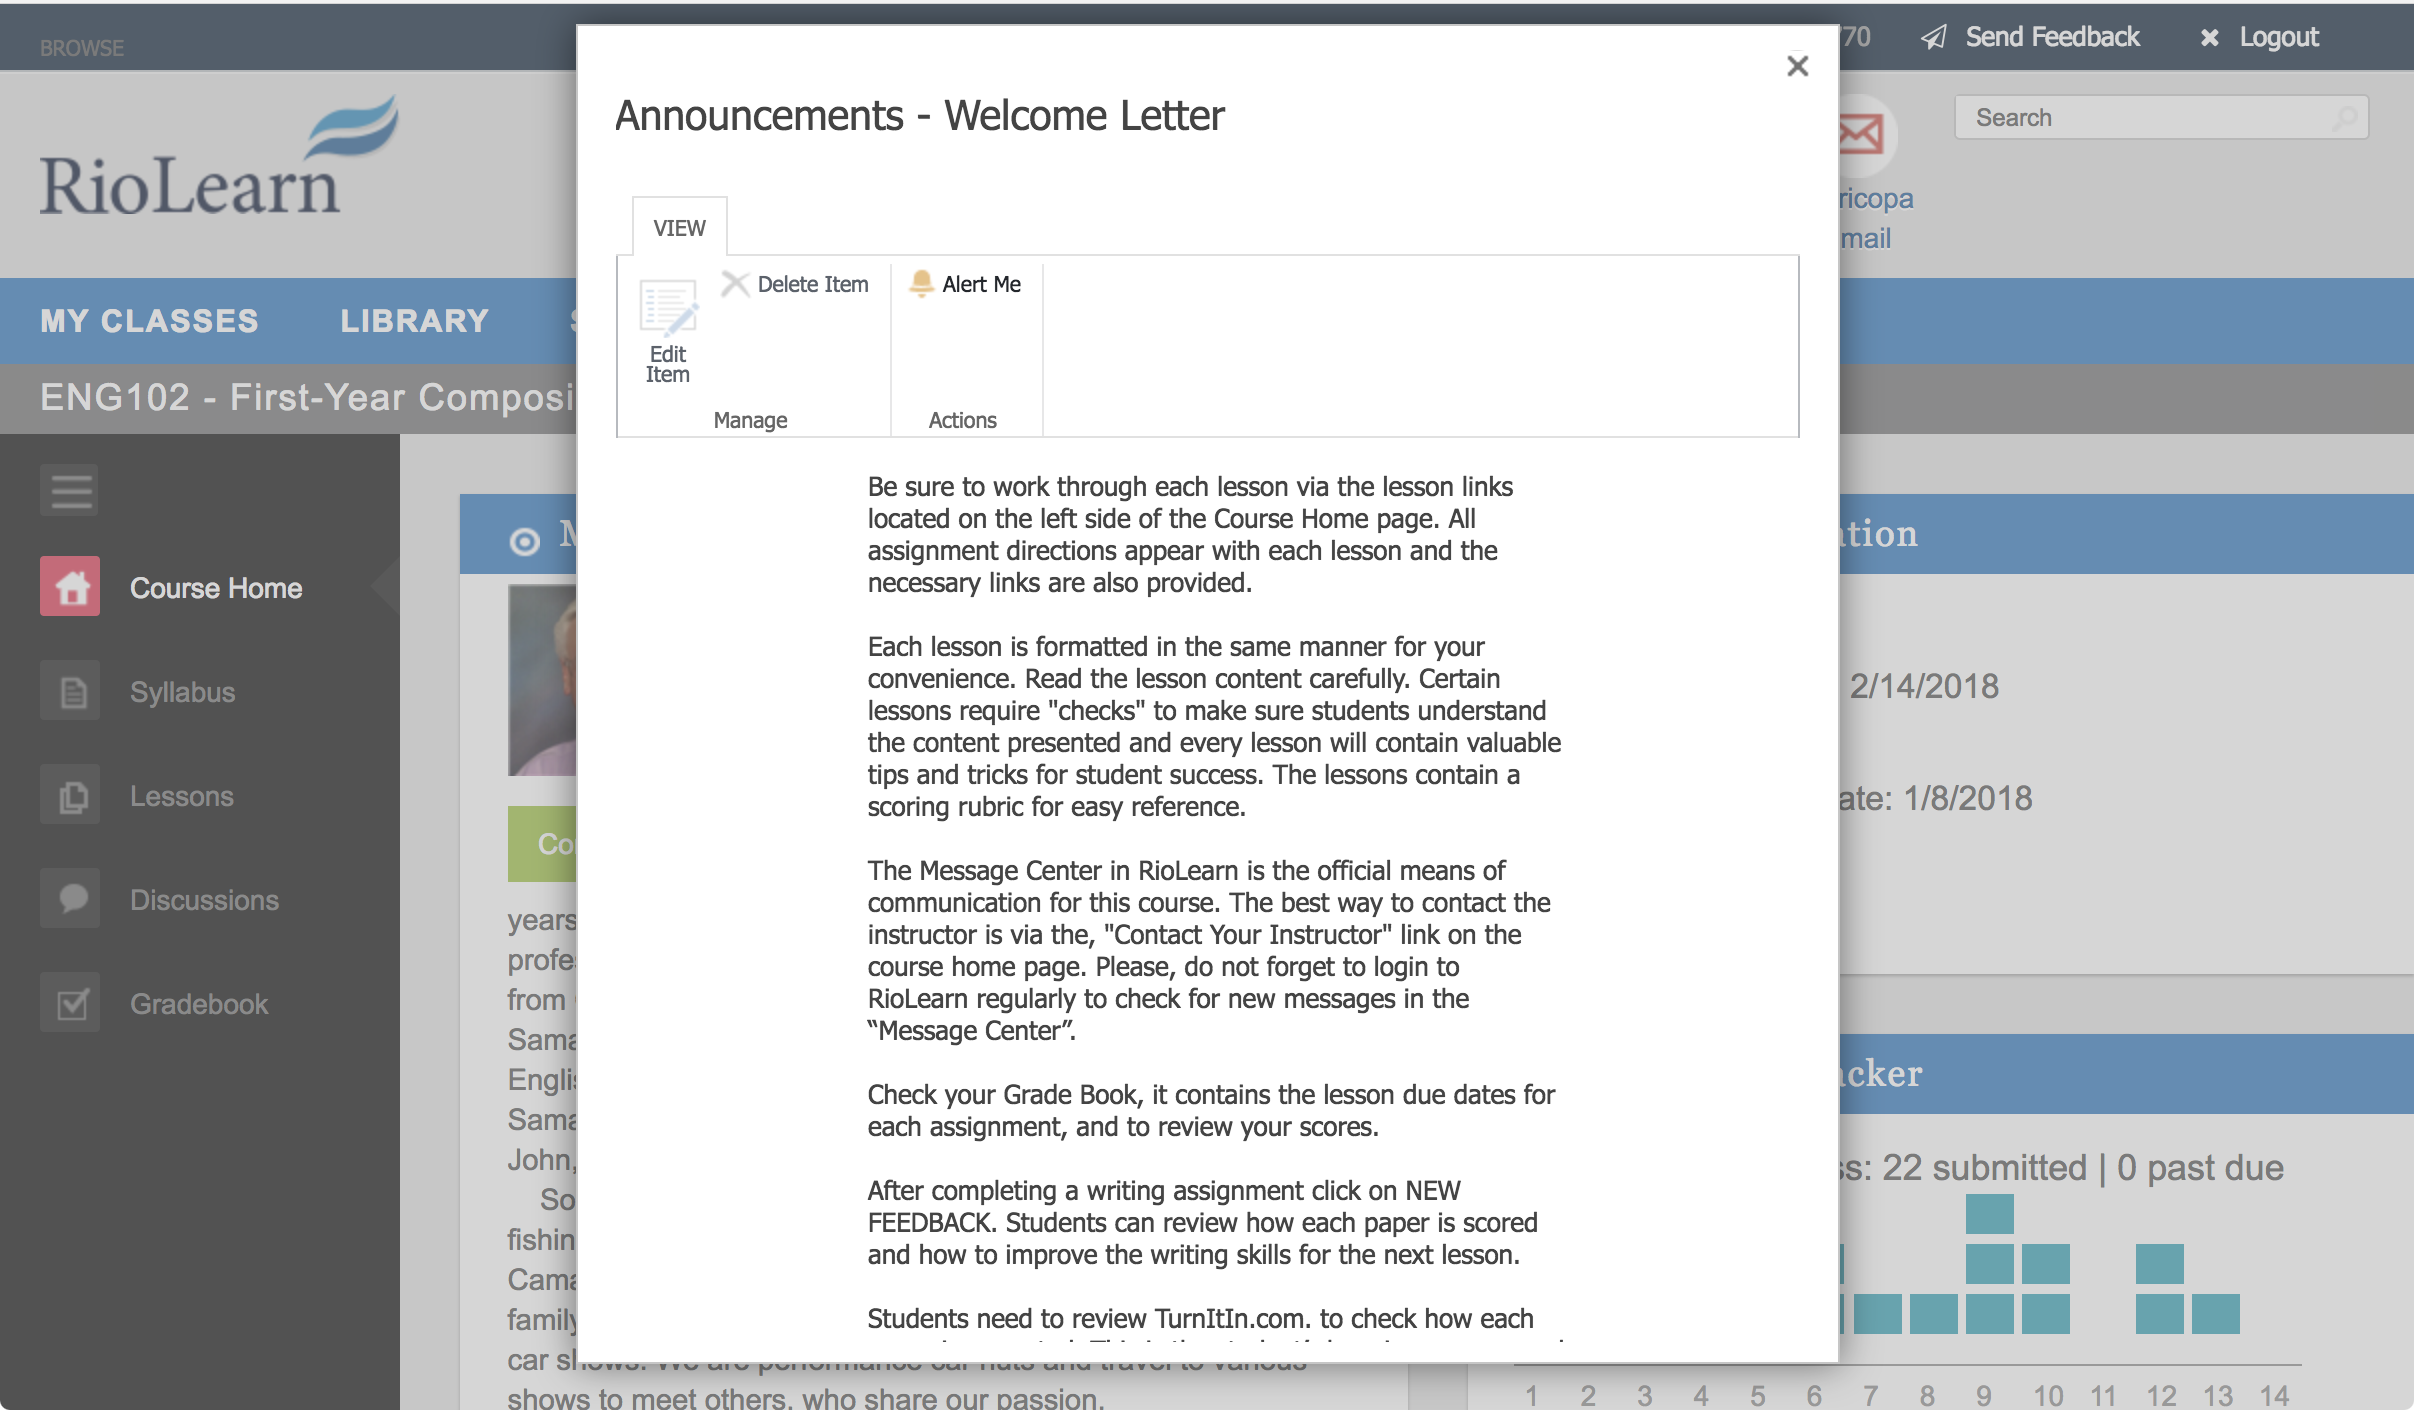
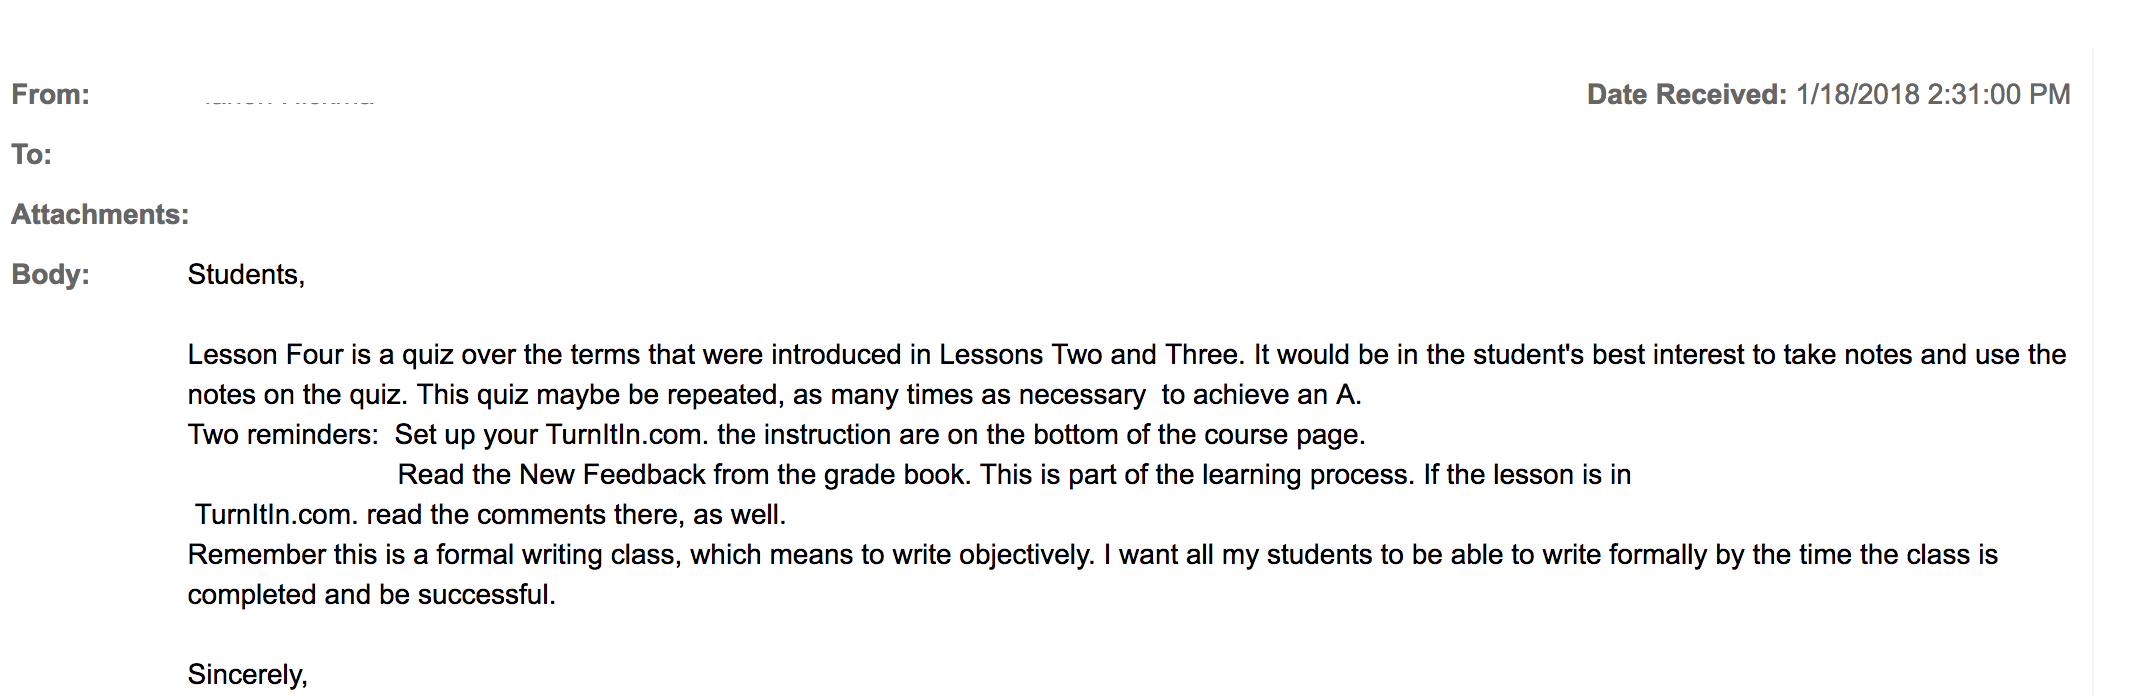
    Course Welcome Message

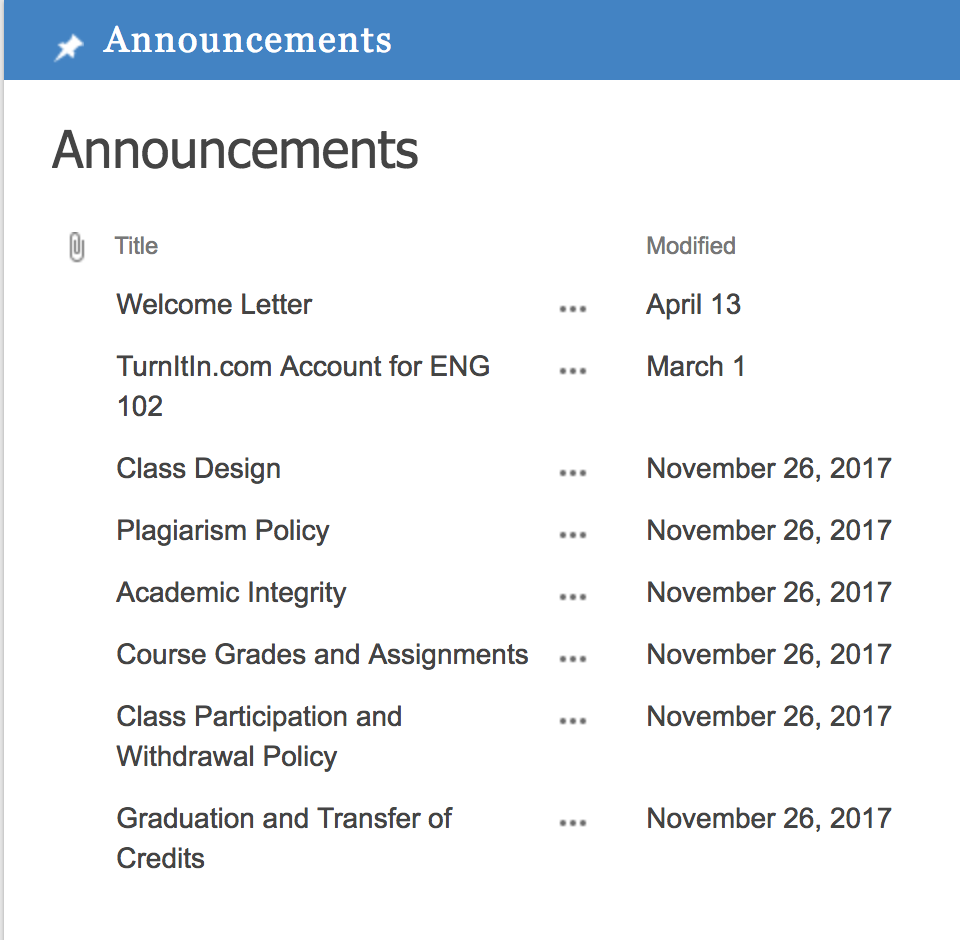
    The instructor sent out several announcements at the beginning of class, a welcome letter, and then one reminder or update message at the beginning of each month. That’s it for instructor-initiated interactions.

    Course announcements

    Sample Message

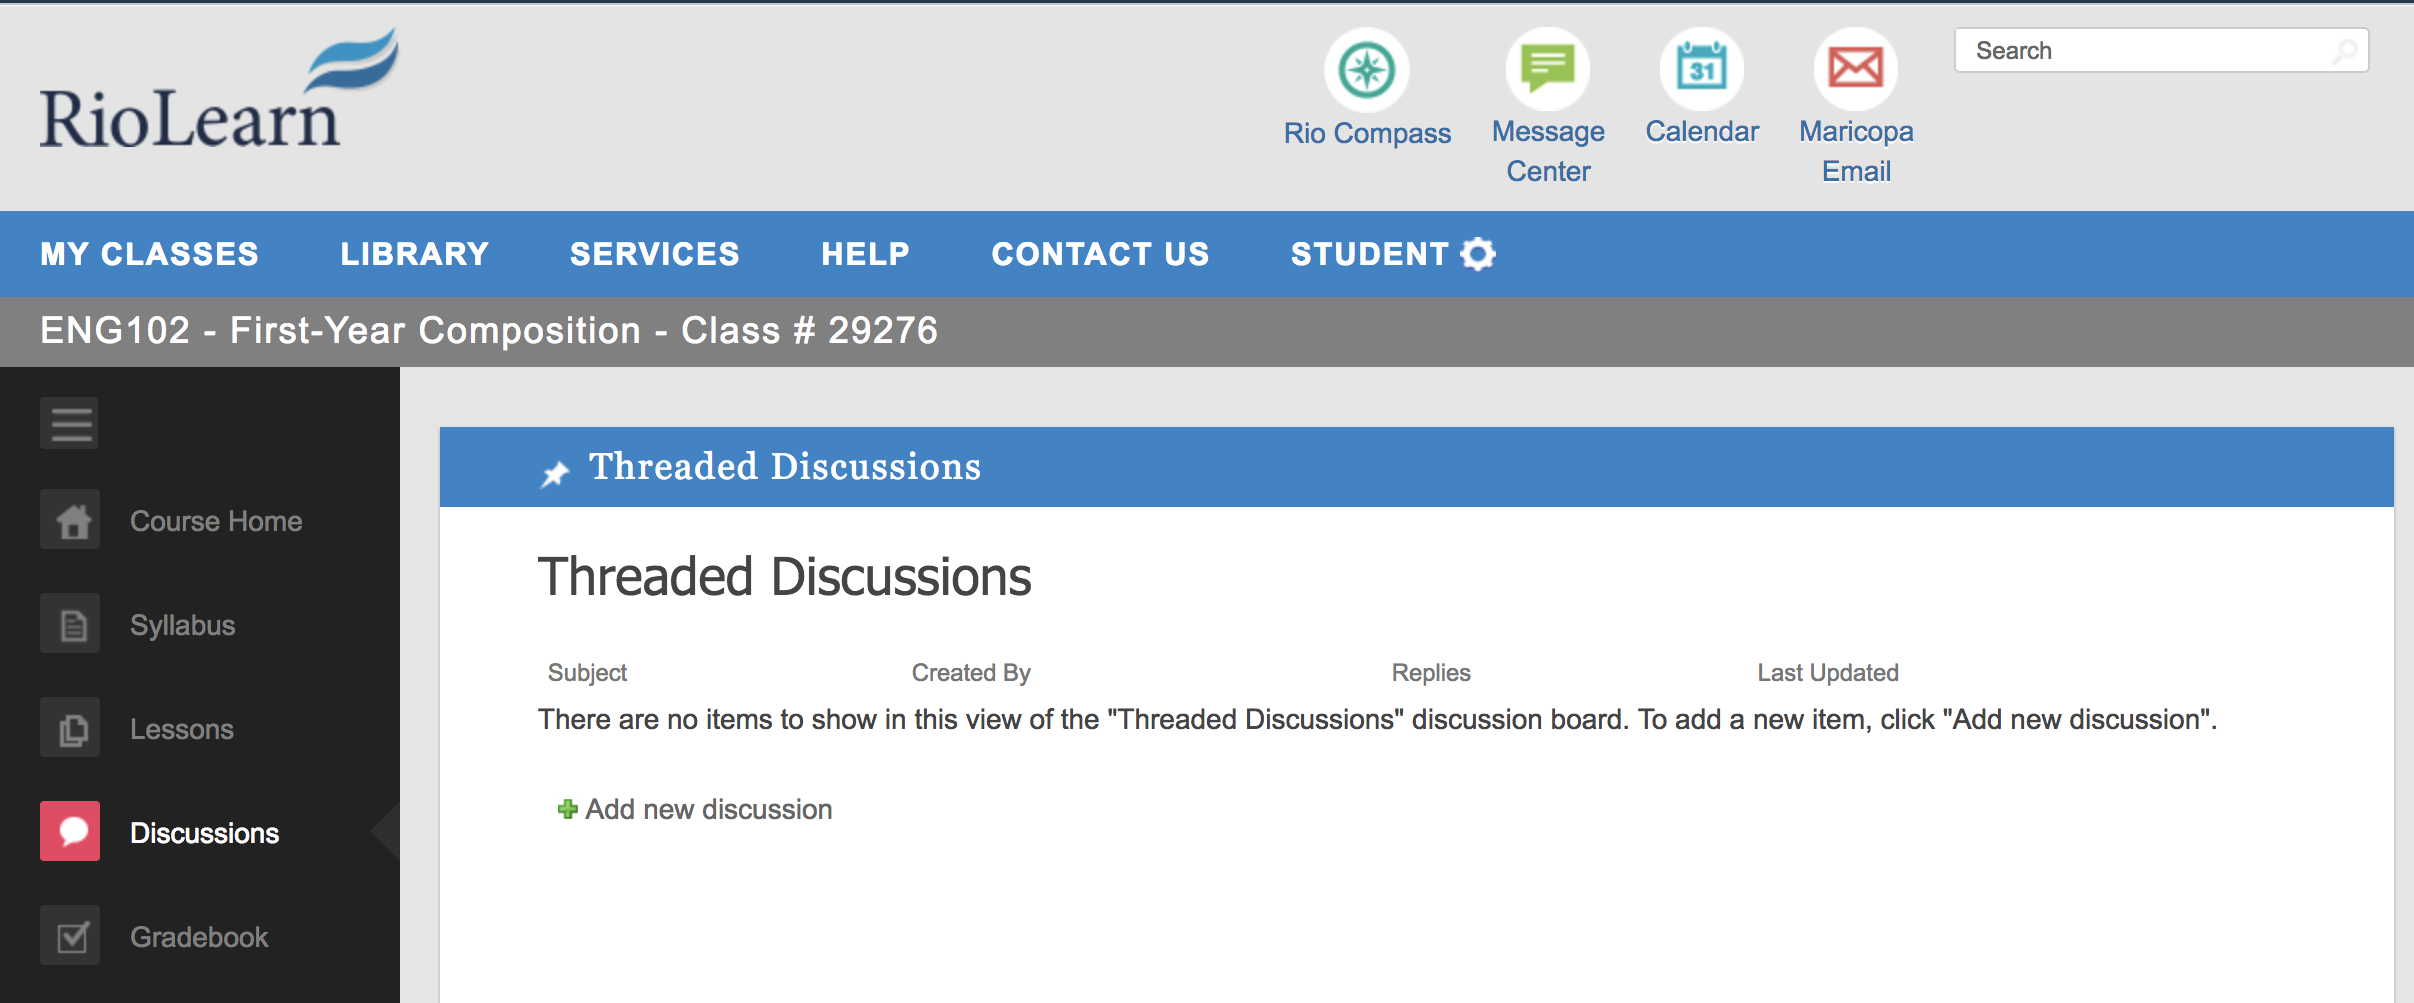
    There were no student-to-student discussions, as the discussion board was unused for the course. There was one peer-review activity, but otherwise no interactions between students. I have been a frequent critic of threaded discussion boards, but it is certainly better to have something instead of nothing.

    Discussion Tool

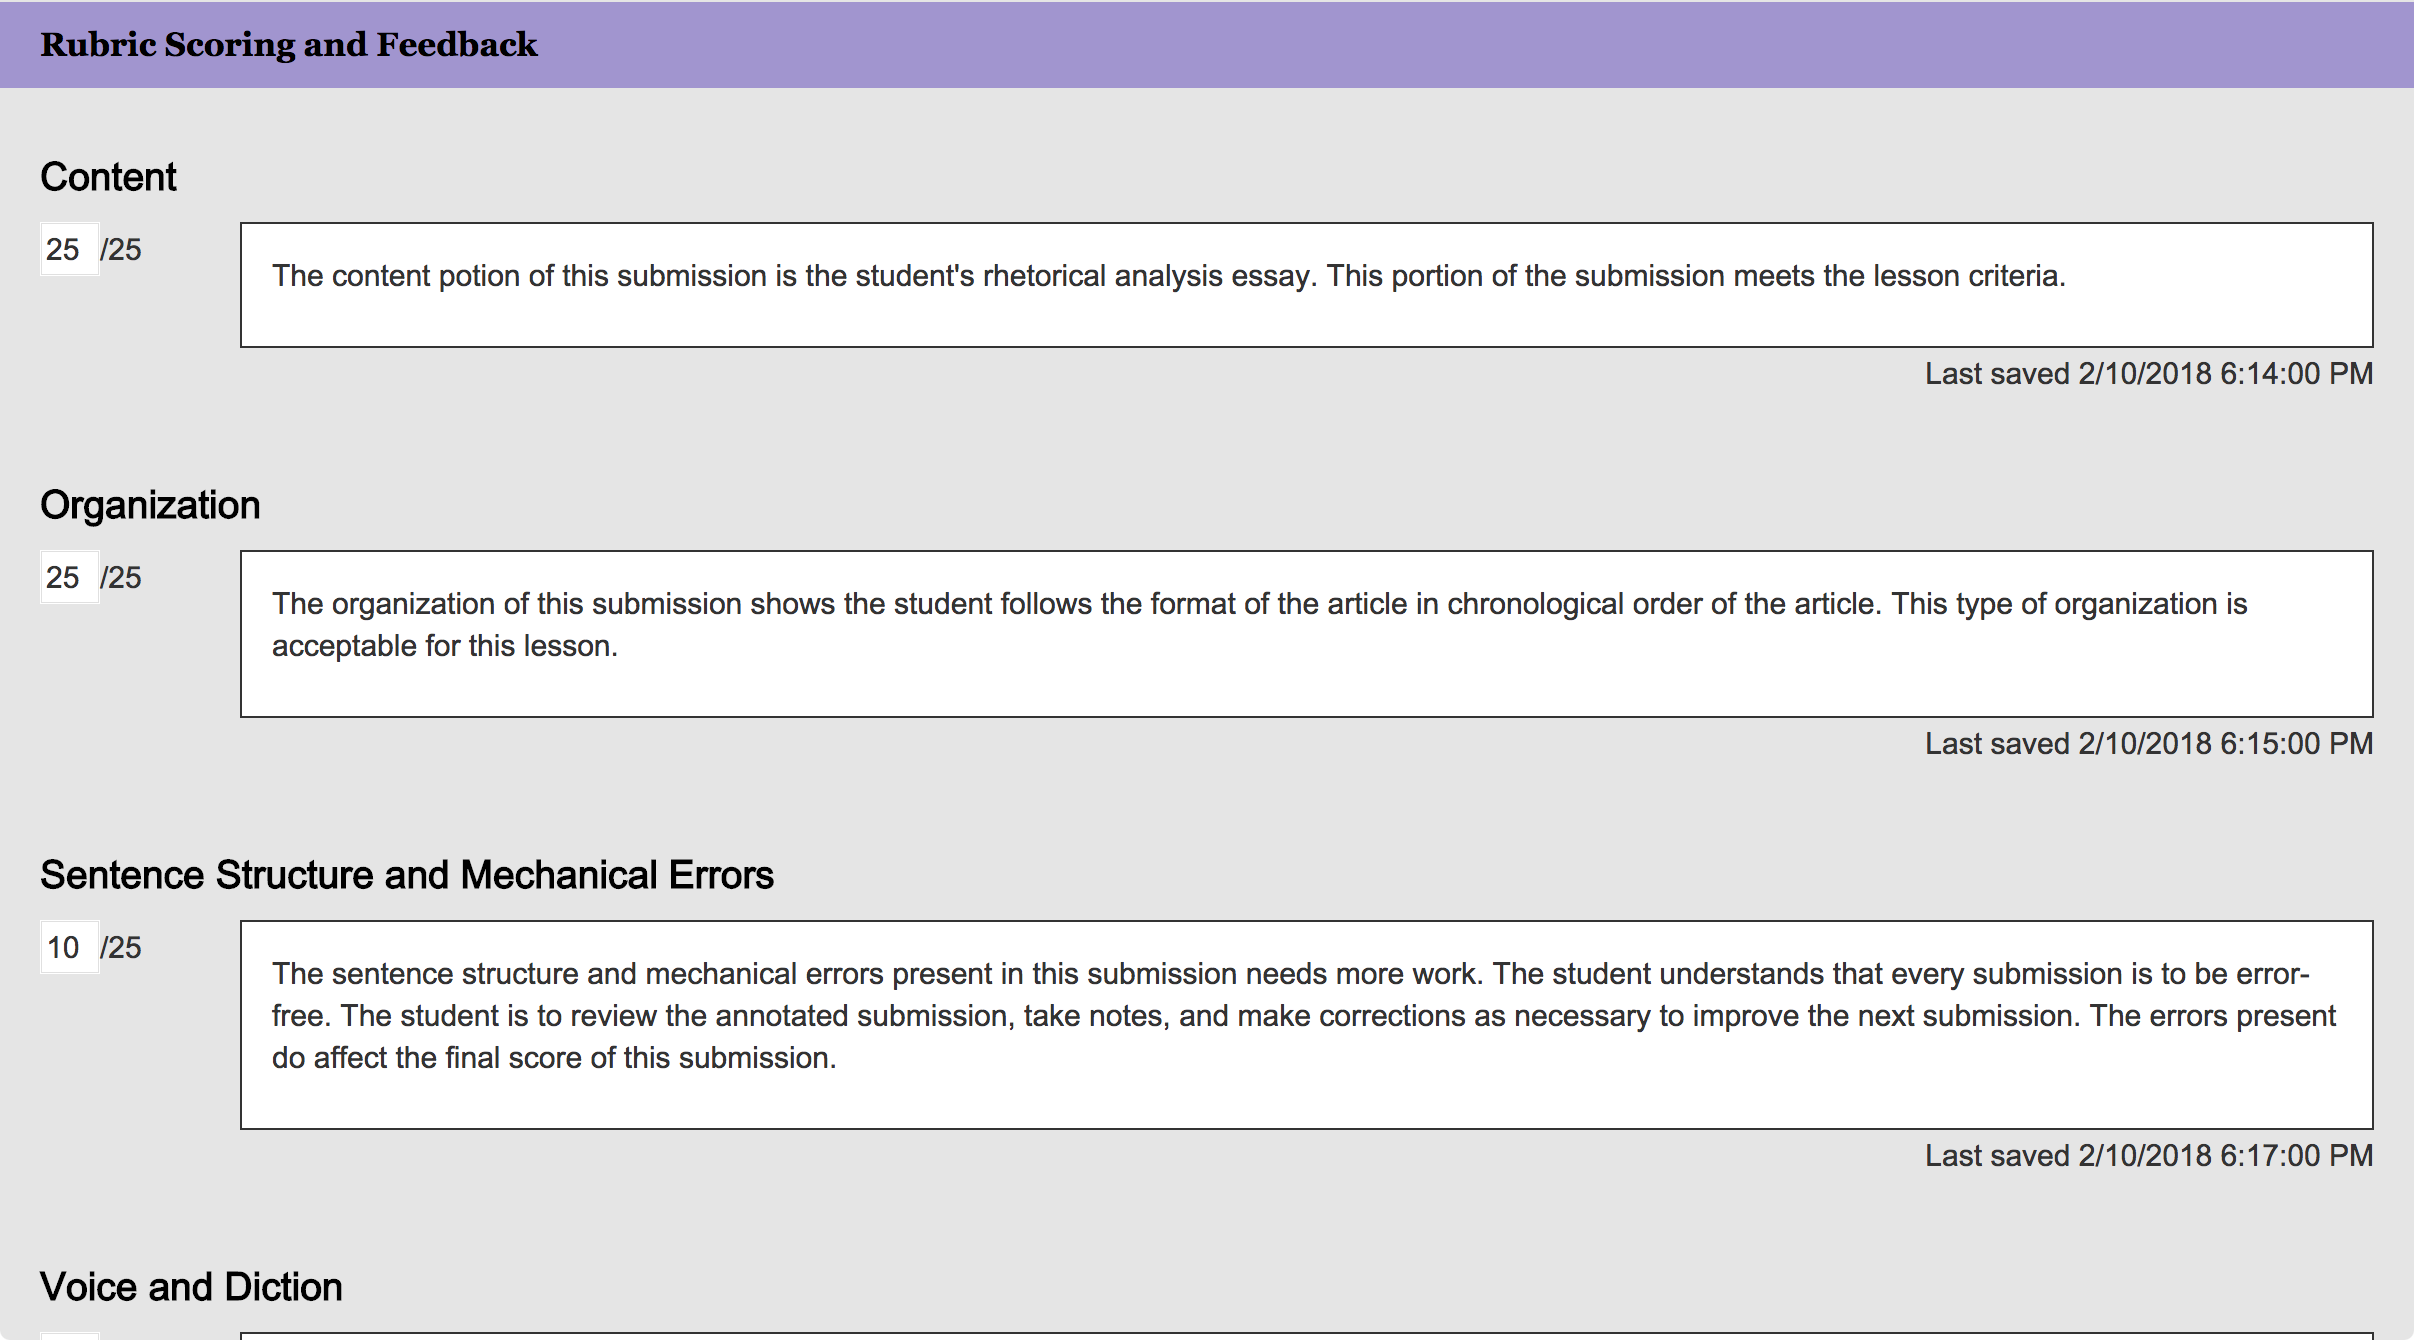
    The rest of the interactions came in two categories: grading of assignments and responses to student-initiated messages. The primary feedback method in these two courses was faculty usage of the custom-developed Feedback Tool, which uses rubrics to grade assignments.

    Lesson Feedback

    There were several assignments that included annotated mark-ups of the submitted papers, which appear to be the most useful feedback from instructors.

    A review of EED200 shows the same course structure – few instructor-initiated interactions, use of rubric grading as feedback on assignments, and specific responses when students send questions in through the Message Center.

    For both courses, the instructors typically responded to student messages within a day or two.

    This approach is troubling, as both courses appear to not meet the “regular and substantive interaction” regulation for credit-bearing online courses. I have been critical about the vague standards and the egregious application by the Department of Education’s Office of Inspector General audit of Western Governors University, but these complaints do not mean that the regulation has no point. The idea is that course design and facilitation should be implemented to ensure that students are not left to figure out static course materials and to be responsible for initiating most forms of interaction. As stated in a 2014 Dear Colleague Letter on the subject of regular and substantive interaction based on competency-based education (CBE) approaches [emphasis added]:

    We do not consider interaction that is wholly optional or initiated primarily by the student to be regular and substantive interaction between students and instructors. Interaction that occurs only upon the request of the student (either electronically or otherwise) would not be considered regular and substantive interaction.

    Some institutions design their CBE programs using a faculty model where no single faculty member is responsible for all aspects of a given course or competency. In these models, different instructors might perform different roles: for example, some working with students to develop and implement an academic action plan, others evaluating assessments and providing substantive feedback (merely grading a test or paper would not be substantive interaction), and still others responding to content questions.

    The problem with case studies is that the selection of cases to study may not be representative or appropriate to prove one’s thesis. It is possible that I happened to look in detail at two courses that are aberrations. But even so, this view is troubling, as these are centrally-developed courses (not subject to the whim of individual instructors), and both courses have little meaningful provisions for faculty-student or student-student interactions. The instructors were responsive to messages, but that is not enough to back up claims of high-quality courses. The dissonance between these two courses and what is described in the ASU / BCG report led me to take a critical look at the data.

    For the next post, I’ll take the external view and look at aggregate public data on Rio Salado College on academic outcomes.

  • Comparing the First Ten Years of Blackboard and Instructure in LMS Market

    Comparing the First Ten Years of Blackboard and Instructure in LMS Market

    Last year Blackboard celebrated their 20th anniversary as a company, and this year Instructure celebrated their 10th. Yes, the company with Canvas, the “new” LMS solution, is a decade old. To gain historical perspective, it is interesting to compare each company’s first ten years in business in terms of primary financials – revenue and income – and performance in their core North American Higher Education market.

    We can only go so far in comparing the companies on this basis, however, due to different circumstances.

    • Most importantly, Blackboard helped create the LMS market and therefore had significant portion of its expansion in a greenfield situation, picking up clients who had not previously used an institution-wide LMS. Canvas entered the market well after saturation, with greater than 90% of institutions already having a standard LMS.
    • Blackboard developed its product line pre-cloud, with on-premise hosting being the primary deployment model. Canvas was cloud-native, developed on top of AWS infrastructure.
    • Blackboard’s growth was heavily based on corporate acquisition of competitors – Prometheus, WebCourse, WebCT in the first decade – while Instructure’s growth has been almost exclusively organic.
    • Both companies sold in more than just the North American Higher Ed (NAHE) LMS market, even if that was the core. Blackboard acquired two companies in 2000 and launched a card-reader transaction business, and they played somewhat in the K-12 and corporate learning space. Instructure developed Bridge for corporate learning, Arc for video platform, and it has a heavy presence in the K-12 LMS market.

    Interestingly, both companies went public in Year 7 (Blackboard in 2004, Instructure in 2015).

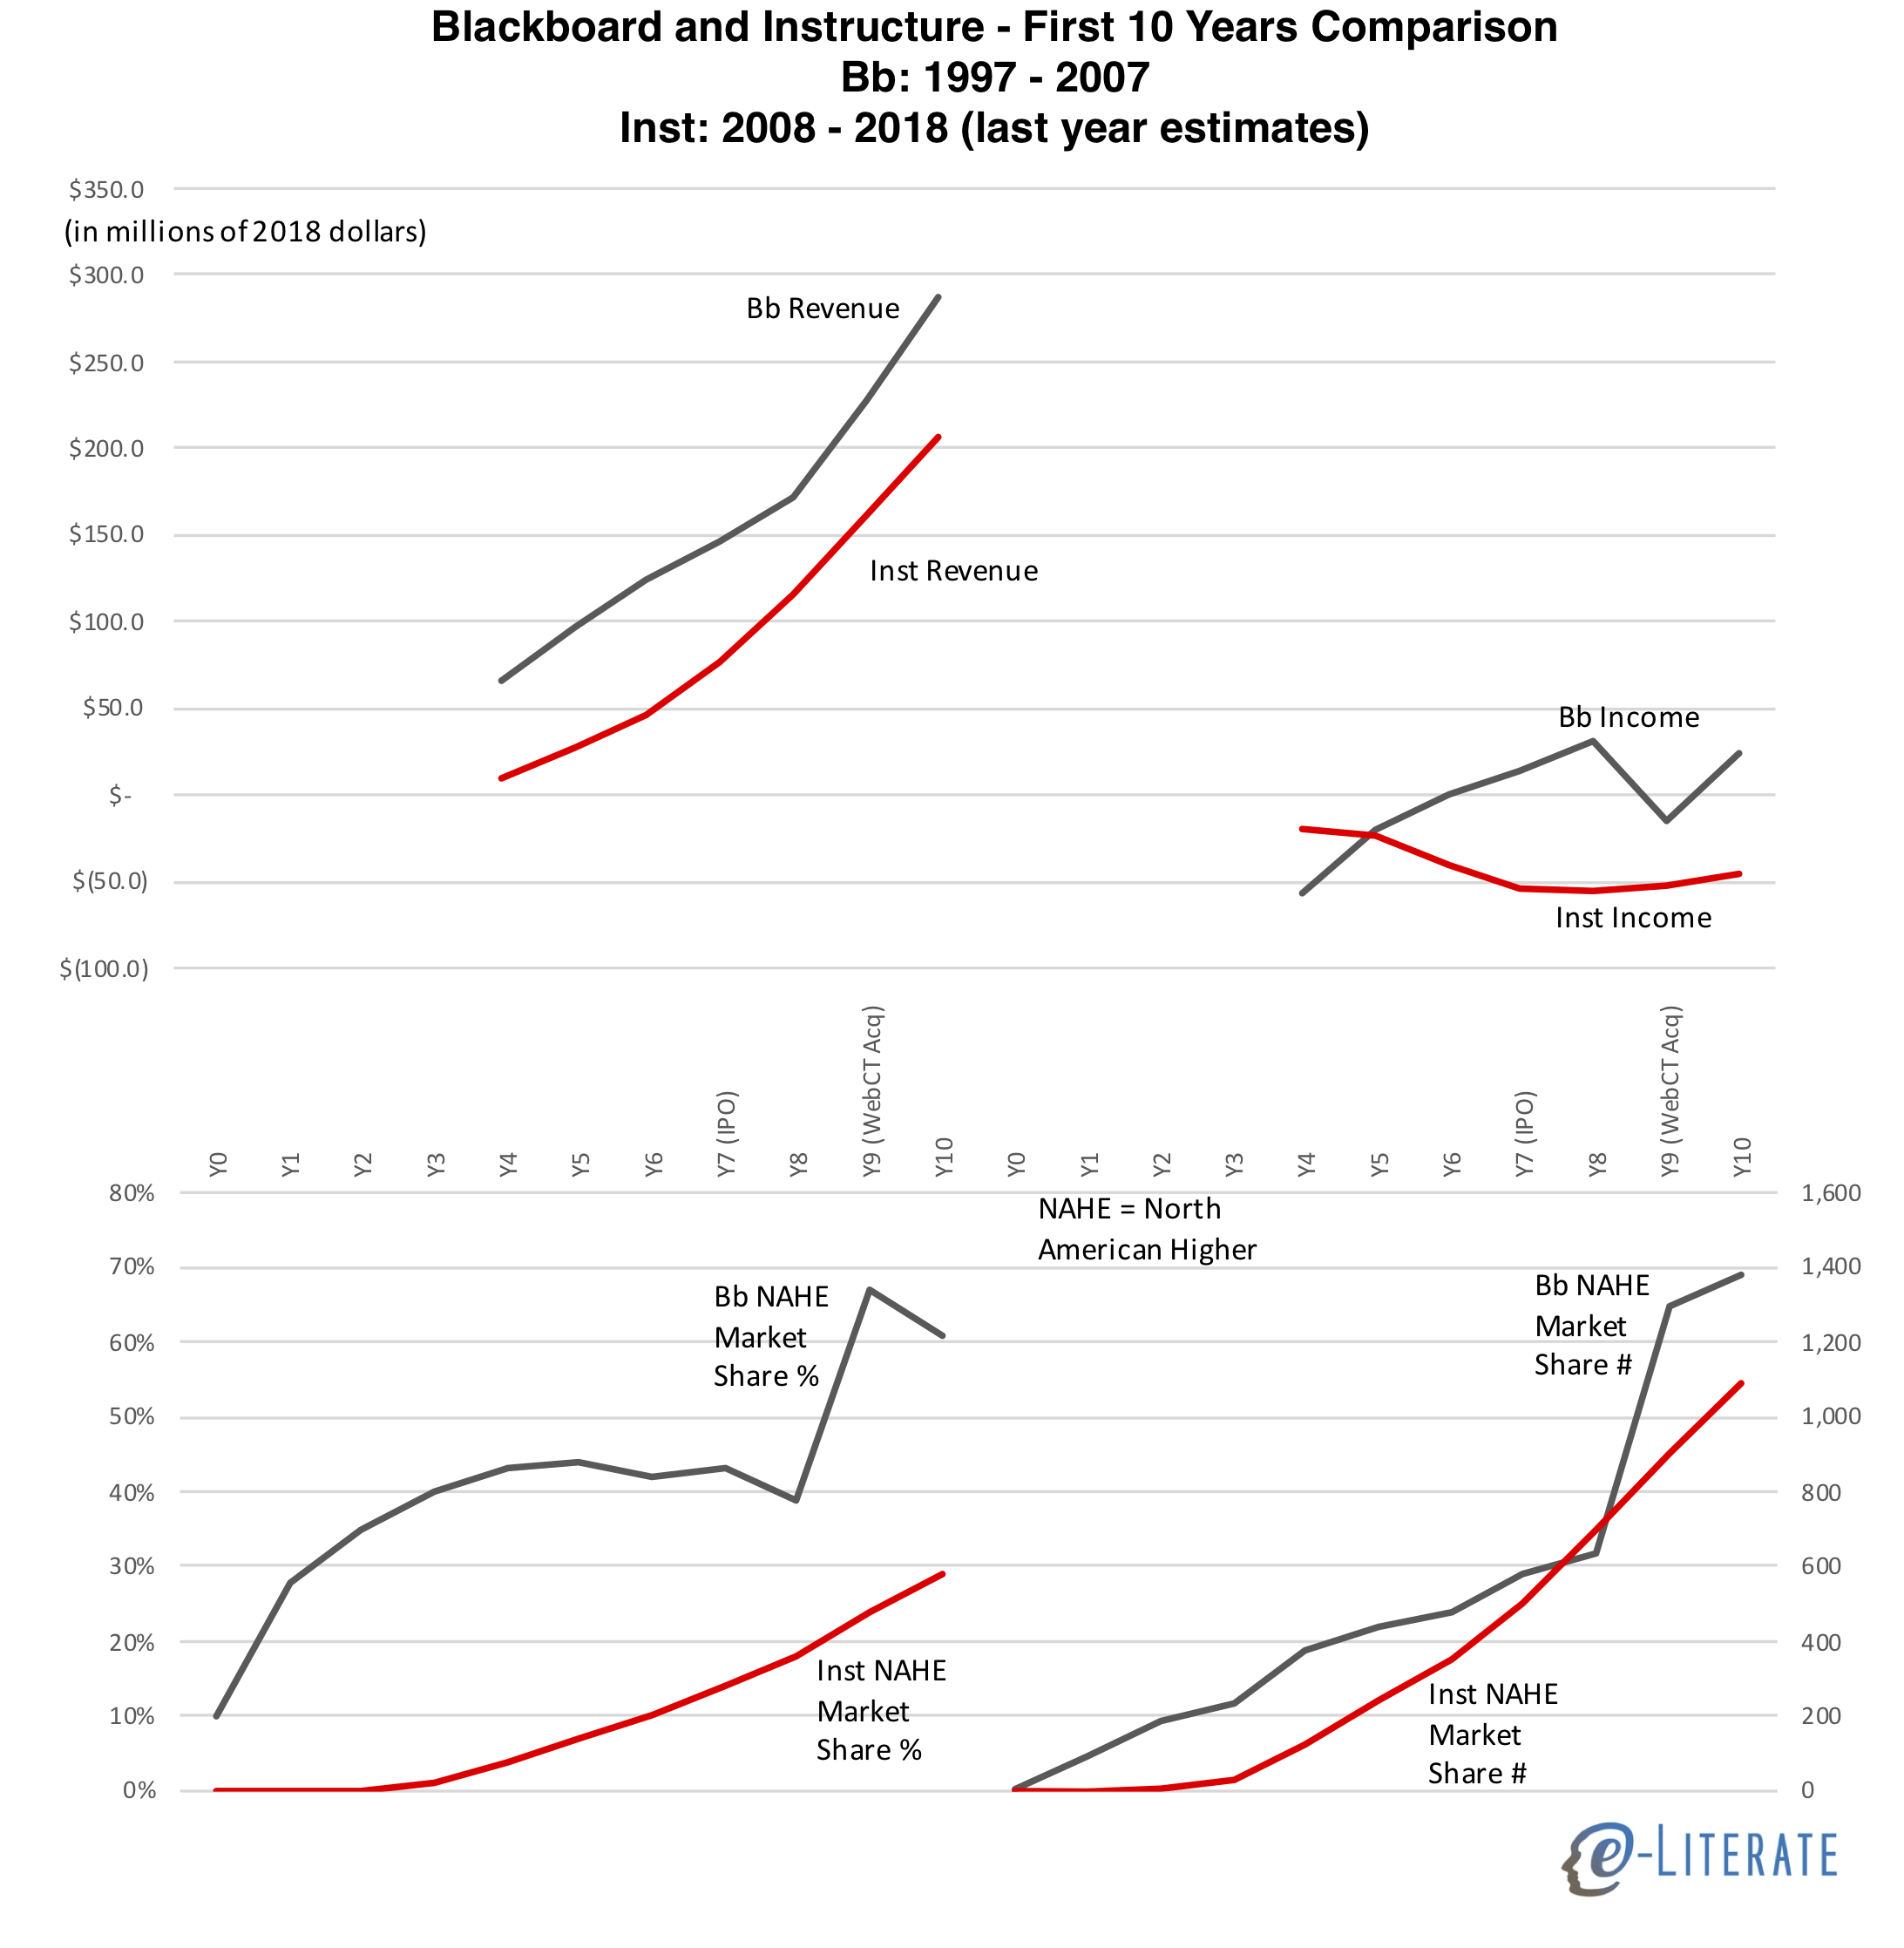
    With that in mind, let’s compare revenue, operating income – both derived from public SEC filings and adjusted to 2018 dollars – and market share in their core NAHE market. The financial data comes from public filings, and data for 2018 for Instructure are estimates based on their outlook presented in the most recent quarterly earnings release. Market share data is based on our LMS Market Analysis service and associated financial analysis for premium subscribers.

    Blackboard and Instructure revenue and income in 2018 dollars, and north american higher ed market share in percentage and numbers

    Some notes:

    • Blackboard raised ~$185 million in venture financing pre-IPO while Instructure raised ~$95 million (both in 2018 dollars). Part of this difference can be attributed to the much higher costs associated with pre-cloud enterprise software deployment models.
    • Blackboard’s revenue was higher than Instructure’s at similar points, and their operating income was mostly positive after Year 6. Instructure has maintained a significant loss each year from operations. One way to explain this difference is that Blackboard’s used funds for corporate acquisitions, thus fueling growth, while Instructure invested funds into sales & marketing and organic growth. This is not the whole story, but it is a big difference between the two companies.
    • In market share represented as a percentage, Blackboard’s growth was much faster, but this was in a period where the market was developing and not all schools had a standard LMS. When viewing this market share in raw numbers, we see that Instructure’s growth would have exceeded Blackboard’s were it not for the Year 9 WebCT acquisition.
    • Blackboard was already showing organic market declines (in NAHE market share %) and slowdowns in raw numbers outside of the immediate WebCT acquisition of customers. Instructure’s organic growth shows no signs yet of slowing down, is less lumpy and more predictable.