e-Literate

Present is Prologue

Category: Business & Economics

The “Business & Economics” category covers the business aspects of ed tech, including the financial health and business models of individual companies, economic aspects of selling in education that shape the available offerings, and coverage of markets and investment.

  • The Strayer/Capella Merger and What it Means for For-Profits

    The Strayer/Capella Merger and What it Means for For-Profits

    Strayer Education and Capella Education just announced a merger.
    STRA Capella

    Strayer has the upper hand in the merger, taking a 52% controlling interest in the new company, which will be called “Strategic Education” and will maintain Strayer’s “STRA” stock symbol. With combined enrollments of close to 80,000 students, the new company will be one of the largest for-profits in the US.

    As the company touts, there is a high degree of complementarity between the two entities. First, both kept their noses clean during the for-profit scandal era and maintained good reputation. Capella has, in fact, shown a willingness to actively collaborate with the broader university community, including not-for-profits, by sharing best practices and collaborating in research on topics like learning analytics. Strayer’s degrees are largely concentrated in business and IT, while Capella has a broader portfolio including education, health care, and criminal justice. Strayer has a number of physical campuses for classroom or blended learning, while Capella is focused on fully online. Strayer is known to be particularly good at building partnerships with employers, while Capella is known for its work in new educational trends like learning analytics and Competency-based Education (CBE). Strayer has a lot of working adults completing their undergraduate degrees while Capella has a robust set of graduate programs. Both dabble in other formats like code academies, and Capella has 51 certificate programs.

    Assuming the merger goes through, both schools will continue to operate largely separately as independent brands. Faculties are specifically called out as remaining separate, though credits will be tranferrable from one institution to the other. The areas singled out for “consolidation” (read: layoffs) are “executive and corporate functions, certain marketing capabilities and IT operations.” Corporate headquarters will be in Virginia, where Strayer’s headquarters currently are, but IT will be run out of Minnesota, where Capella is.

    When we look at this merger in the context of both Purdue’s acquisition of Kaplan, DeVry’s internal restructuring, and University of Phoenix’s transition of ownership and leadership, some trends in the for-profit space begin to emerge. ((Disclosure: University of Phoenix was recently one of our consulting clients.))

    Still on the defensive

    Despite the hype about the Trump administration being friendlier to for-profits than the Obama administration, the truth is that we continue to see defensive moves. University of Phoenix’s old PE owner decided to sell the business, and the leadership brought in by the new owner promptly closed 20 campuses. DeVry fired its CEO after closing 14 campuses and settling a slew of state and Federal lawsuits. ((Disclosure: DeVry has recently been a consulting client of ours.)) Kaplan decided to get out of the for-profit university business altogether. (What is left over of that company after the sale to Purdue, and what it will become going forward, is still unclear.) And the most immediate effect of the Strayer/Capella merger will be cost cutting in redundant operations.

    In other words, Education Secretary Betsy DeVos has not changed the laws of physics. These institutions were under pressure before and are still under pressure now. We should not be surprised to see more closures like Corinthian Colleges and ITT Tech, particularly of second- and third-tier for-profits. They may not be driven by active prosecutions, but the damage to the sector has already been done. Government intervention wasn’t the sole cause of the collapse of Corinthian; lack of cash on hand played a role.

    The questions going forward are (a) is the for-profit crash bottoming out, and (b) if so, what does their next act look like? It’s too early to tell regarding the first question, but we are getting some interesting hints regarding what the leadership of some of the larger for-profits think possible answers to the second one is.

    Course design, analytics, and employer connections

    A few details of the Strayer/Capella announcement stand out. The first one comes out of the rhythm of a merger announcement like this one. There’s a format of “Company A brings strength X while company B brings complementary strength Y.” The announcement touts one of Strayer’s strength as “close relationships with employers” that complements Capella’s “competency-based learning infrastructure, assessment capabilities and track-record of improving student success.” To begin with, these are real strengths of the respective companies rather than made-up talking points. Strayer is good at employer partnerships and does fairly extensive profiling of their students’ career goals and paths. Capella, for its part, was giving talks about their learning analytics work way back in the early days, before there were even products on the market.

    The bit about CBE, which comes up several times in the released materials, requires a bit of unpacking. Capella offers two flavors of what they label Competency-Based Education: “FlexPath,” which is a fully self-paced program in the style of Western Governors University or SNHU’s College for America, and “Guided Path,” which Capella labels as CBE despite the fact that it is instructor-facilitated, delivered within a term structure for a class cohort, and charged by the credit. What they really mean by CBE in this case is what Phil calls “CBE lite” or what is more commonly known in academic circles as “backwards design,” where the outcomes and assessments are designed first and then the content is structured to match (rather than picking the content for the syllabus and then designing assessments after).

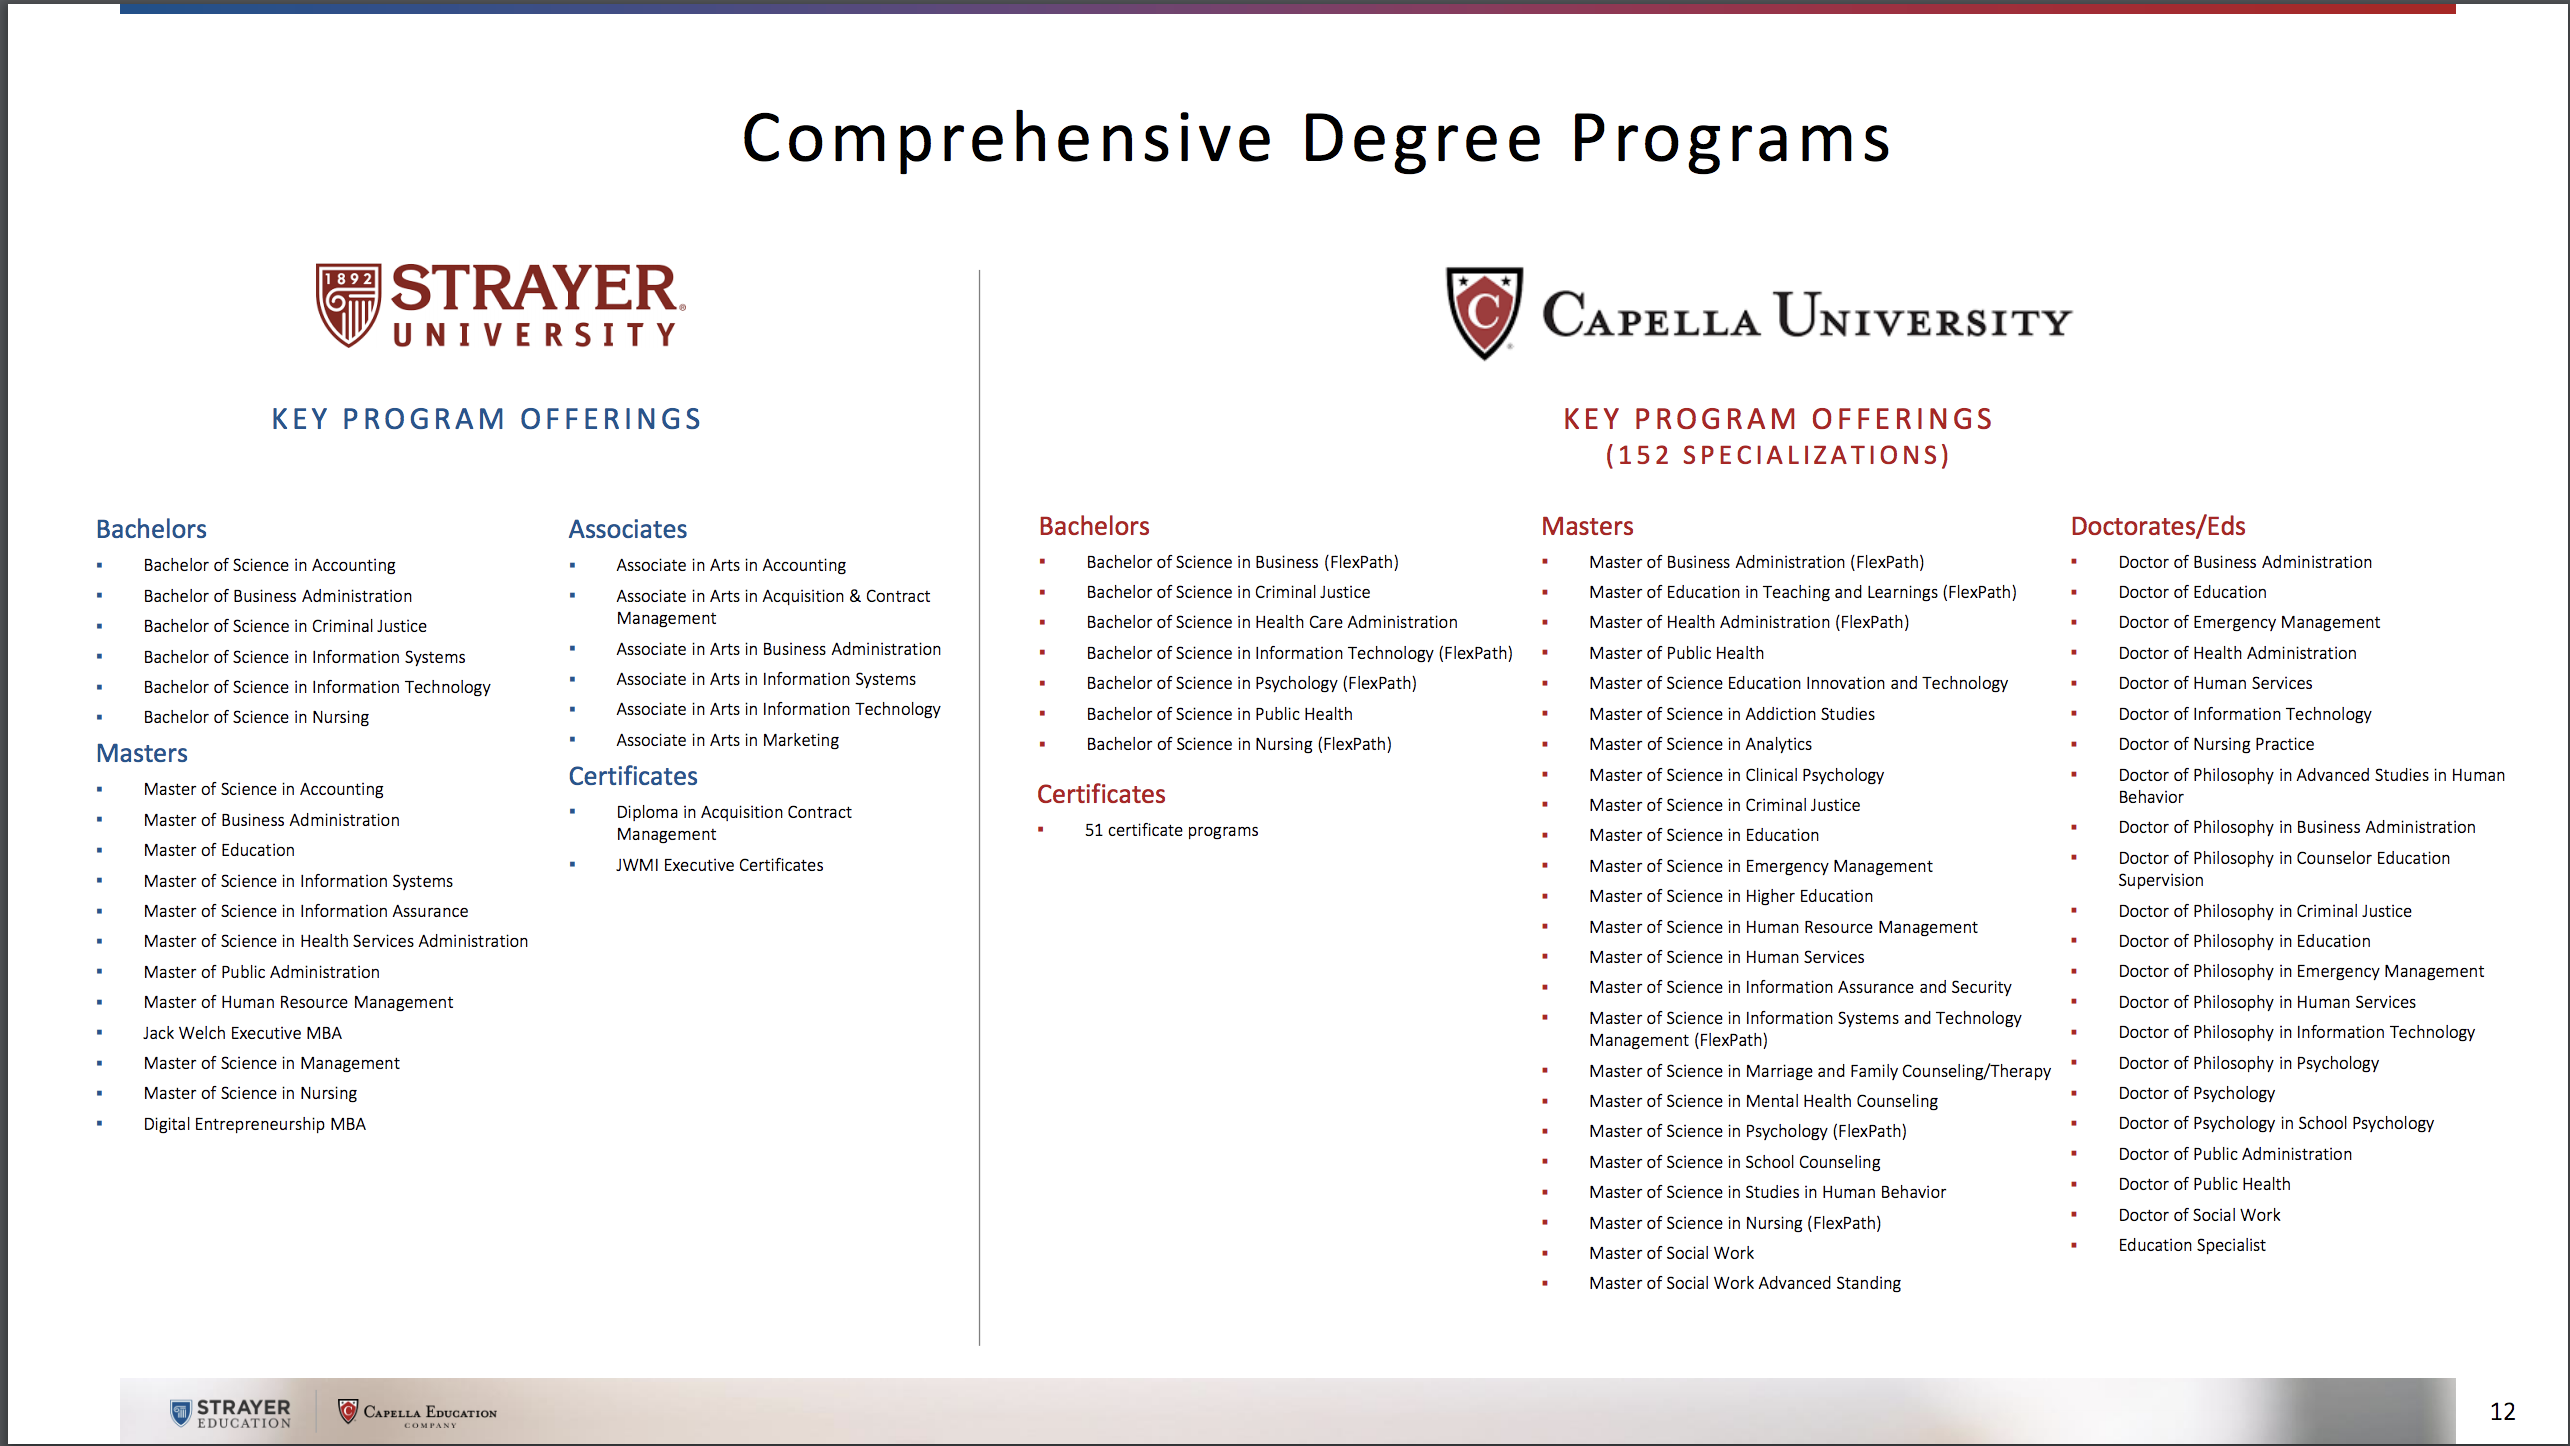
    Only a relatively small percentage of Capella’s degree programs are full CBE FlexPath programs:
    Screenshot 2017-10-30 11.45.48

    So most of these programs are not actually self-paced CBE but backwards-designed and traditionally delivered courses. That may actually be a lot more important. As Phil has written, full self-paced CBE is still struggling to take off. Backwards design, in contrast is a good practice for course designs that drive improvements in student outcomes and is also a prerequisite for various types of learning analytics and adaptive learning approaches as well as full self-paced CBE. So when Strayer touts Capella’s strength in CBE, the real value may be in the course design process and the ways in which those designs can be instrumented in the learning analytics.

    Strong connections to employers, consistent application of backwards course design principles, and analytics supported by those course designs, are three areas where the centralized structure of for-profits enables them to move more quickly than many not-for-profits. Reading between the lines, it looks like the Strayer/Capella leadership think they have found a way to compete on quality. And they may not be the only ones tacking this approach. We see signs that at least pieces of these strategies are beginning to surface elsewhere. For example, it was interesting to see that the University of Phoenix’s new owner chose a new president who was previously an executive at McGraw-Hill Education, which currently styles itself a “learning science company.”

    Kaplan is obviously different, but maybe not as different as it appears at first blush. They had a very strong learning science and analytics-driven approach to course design, driven by thought-leader Bror Saxburg (who recently left to work at the Chan-Zuckerberg Initiative). Purdue, for its part, pioneered retention early warning analytics. Despite some controversy regarding one of their research papers, the university has deep experience with using analytics to drive outcomes.

    It’s still early days, but we may be seeing the beginning of a trend among for-profits to drive toward a particular notion of a quality education as a key competitive differentiator.

  • WCET: Clarity into the successful transition of UF Online

    WCET: Clarity into the successful transition of UF Online

    At this year’s annual meeting for WCET, I was on a panel, along with EdSurge’s Jeff Young, moderated by Saint Leo University’s Jeff Borden. Kicking off the panel, Borden framed the discussion partially as learning from those outside academia. Even though I am not an academic, I have found myself making the mistake of a bias against outsiders. Almost two and a half years ago I described the emerging disaster of University of Florida Online (UF Online) – reality was exposing fundamentally flawed enrollment estimates based on institutional and vendor hubris. In this post I described another challenge:

    In the midst of the challenging startup, UF Online had to deal with the premature departure of the initial executive director. After a one-year search process, UF Online chose a new leader who has absolutely no experience in online education.

    That was probably the fifth edit of a paragraph that started closer to “UF Online somehow thought a bureaucrat from EPA should be its new leader. Next up: filling the VP of student support with DMV veteran.” I was wrong – it turns out that choosing an outsider was just what the program needed.

    Further down in the post I noted:

    At this point, it might have been worth stepping back and challenging some of the original assumptions.

    By late 2016, however, I noted a “remarkable transformation at UF Online” and how the unit shed the hubris of the initial plans and really did challenged original assumptions and came up with a new strategy.

    At another WCET session, this same UF Online executive director Evie Cummings provided more insight into the mindset that led to this transformation. Prior to coming to UF Online, Cummings was instrumental in creating and establishing the EPA Information Quality Guidelines and much of the focus was on transparency and accuracy of information shared with the public. This mindset has been brought to the University of Florida, not only leading to an honest reevaluation of original assumptions but also to what I consider exemplary public reporting on program and student outcomes at UF Online.

    Another mindset described in the session was the acceptance of those who control funding – board of governors and state legislators in this case – and figuring out how to use data and communication to bring them along into healthier decision-making.

    These approaches are evident in the UF Online annual report released earlier in the week.

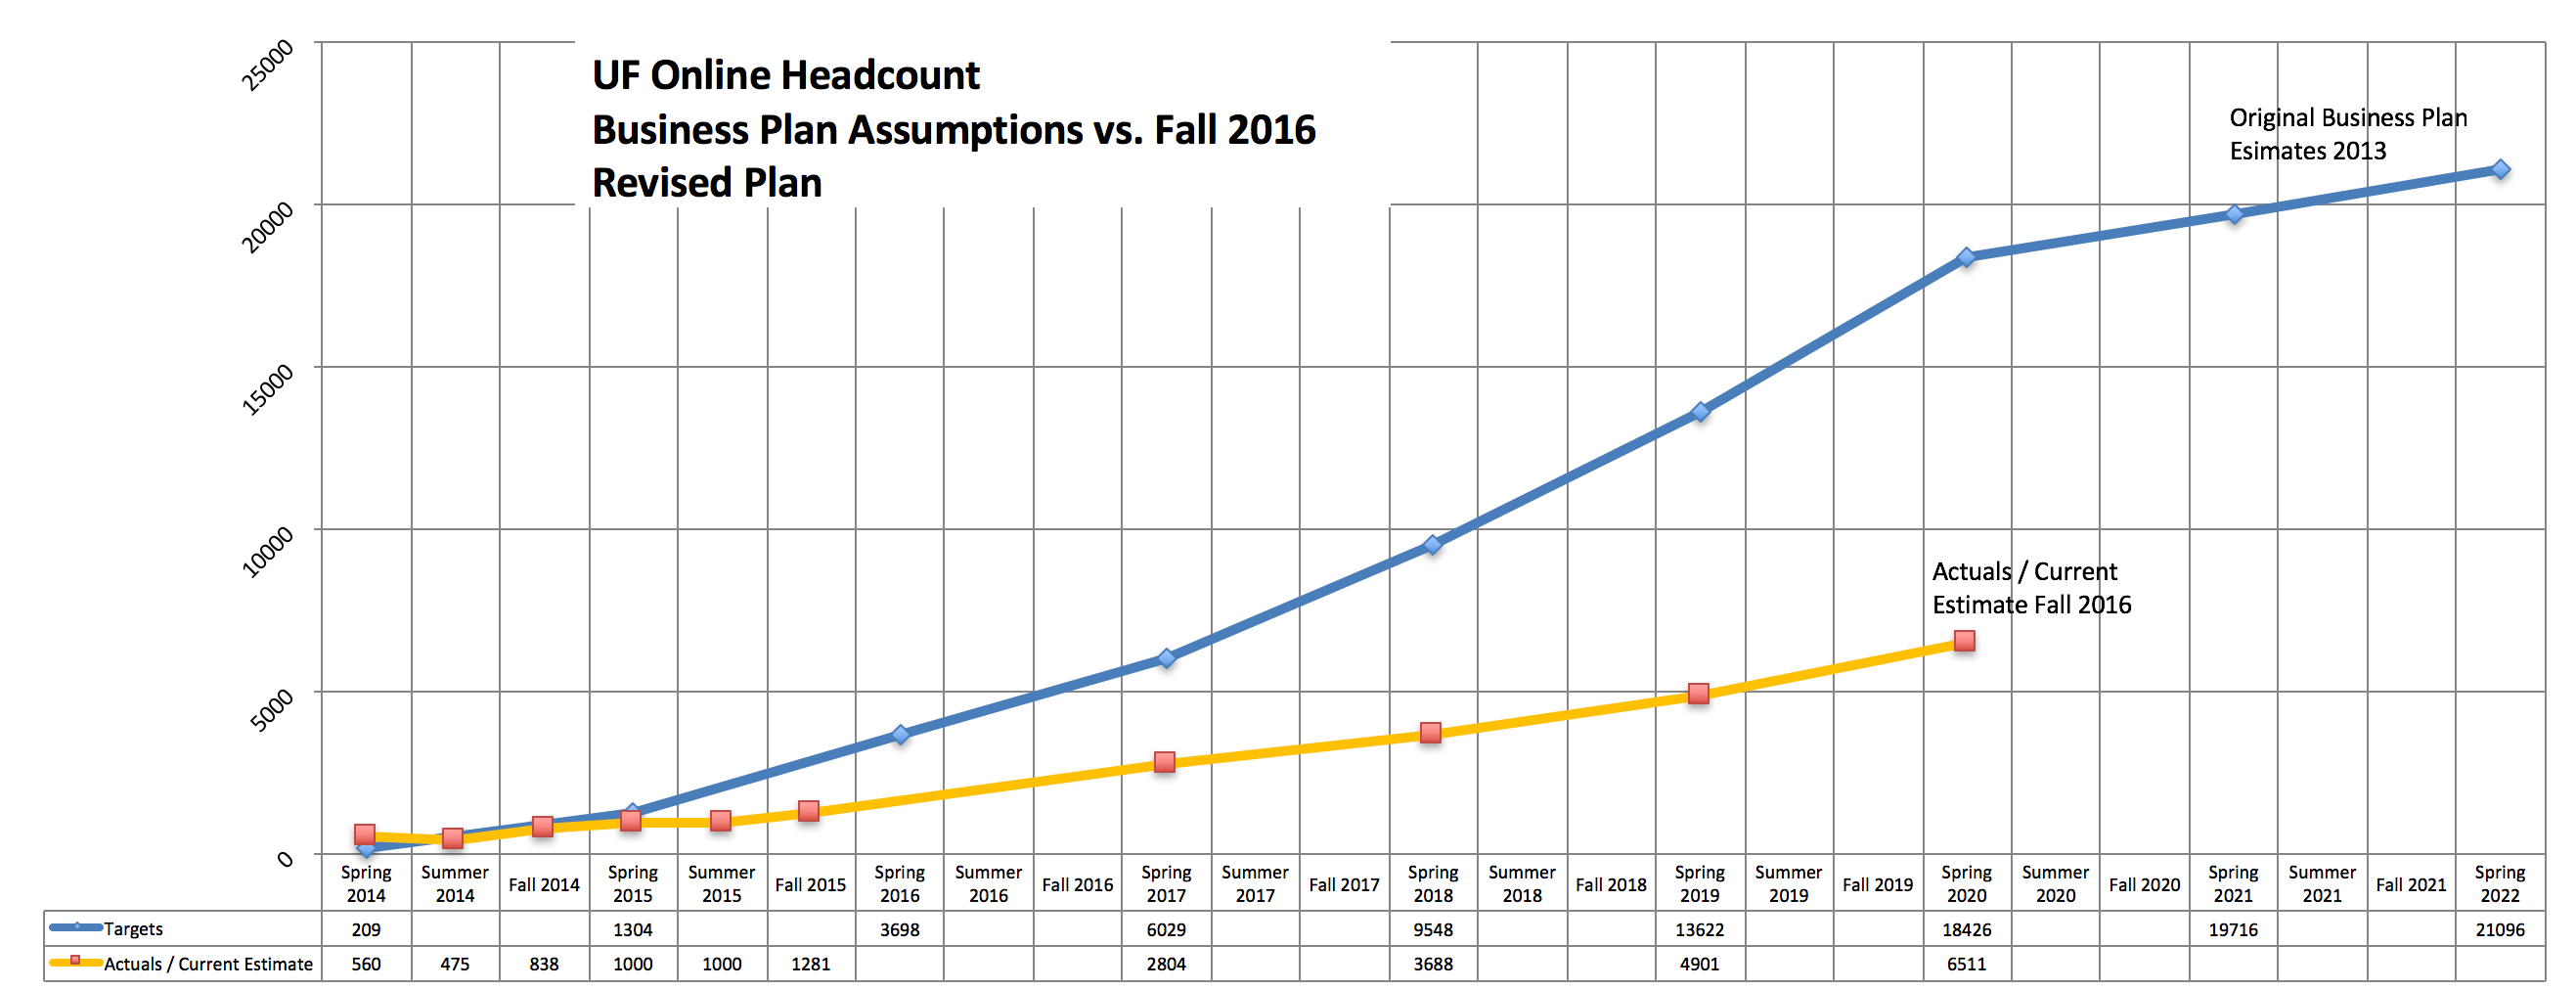
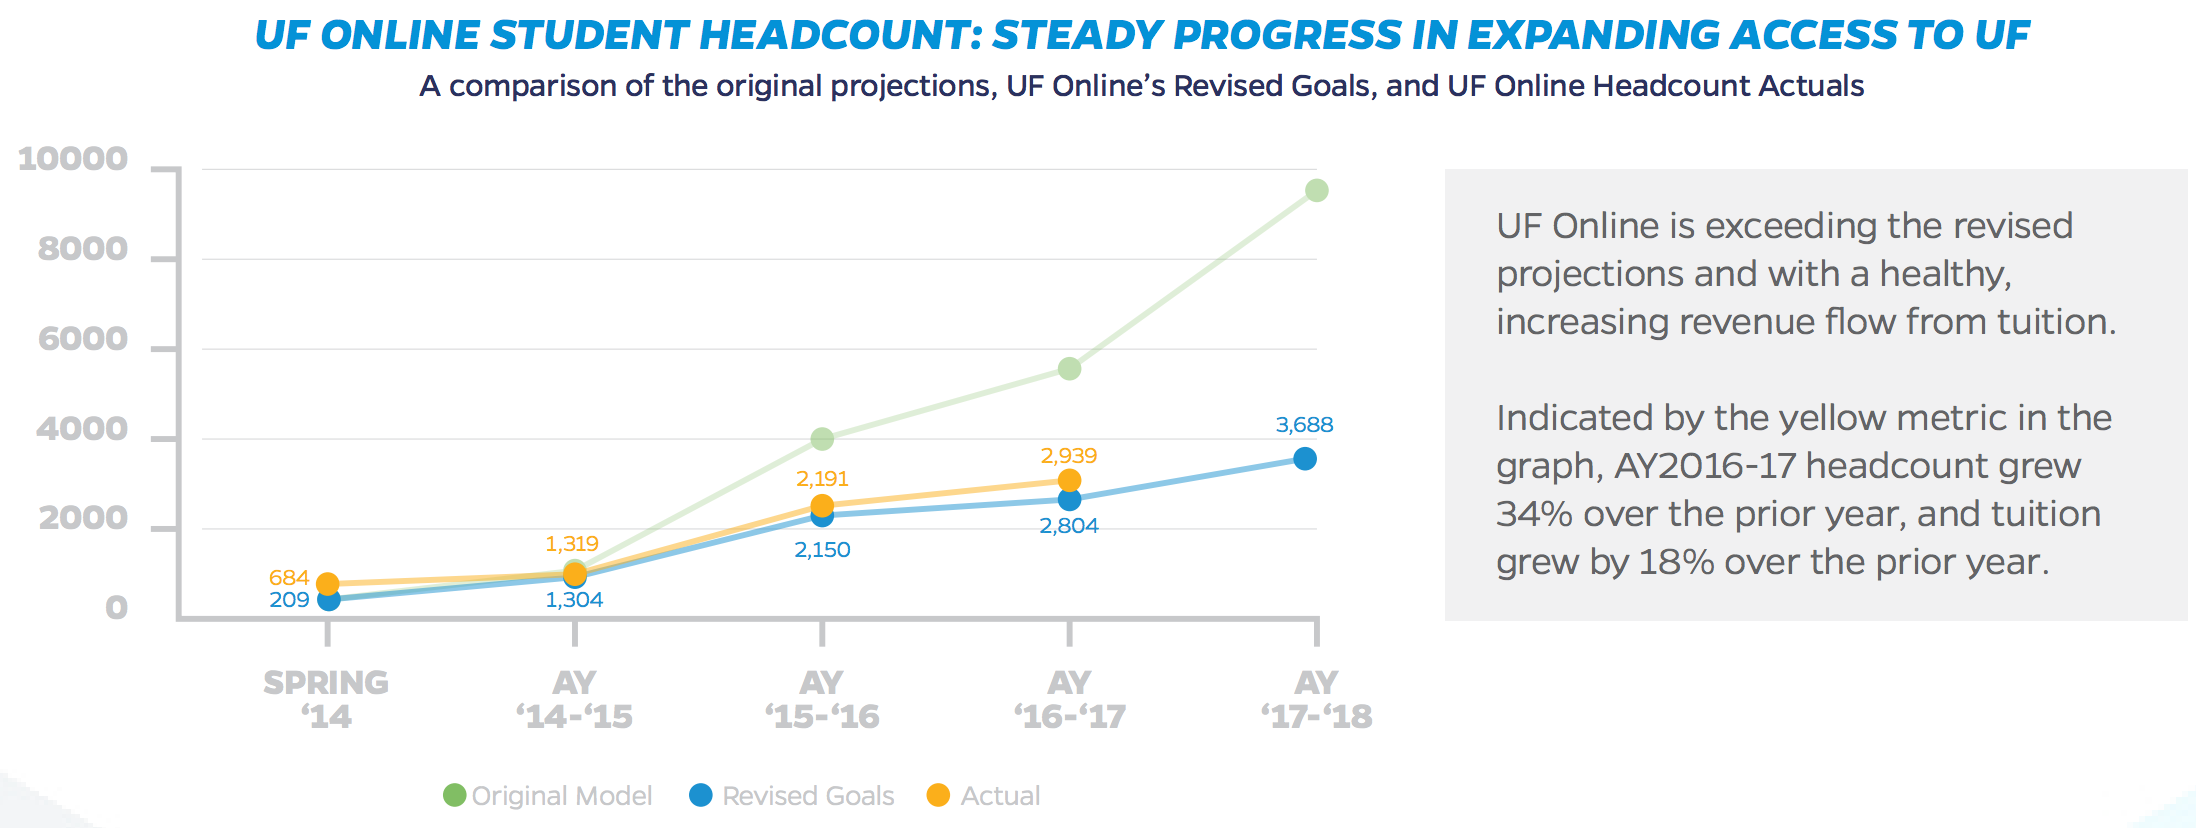
    In terms of enrollment, UF Online not only reports current status and plans, but they choose not to whitewash the past. Their report shows the original plan, the revised plan, and current results with a healthy 34% year-over-year enrollment growth.

    One side benefit – I no longer need to update the spreadsheet I had been using to describe the same information.

    Further in the report, there is a description of UF Online’s new emphasis on creating community among online students and graduates.

    Launched in 2017, the UF Online Connections Program works to foster a thriving learning community across all online students, faculty, academic advisors, and staff. Coupled with strong academic programs, a vibrant and engaged online student experience assures UF Online students not only gain the skills they need but also the connections and network to support them after they graduate. This past year, the Connections program emphasized providing community and networking opportunities with key strategic in-person events.

    They have also launched what they call UF Plaza, a virtual campus to help create social engagement, peer collaboration, and general support groups. Structures outside of the classroom focused on helping online students feel connected.

    One of my previous criticisms was the creation of Pathway to Campus Enrollment (PaCE) – automatic enrollment offers for qualified students who did not get into the main University of Florida as traditional students, with option to transition from online to campus for upper division coursework. When PaCE kicked off, the effort seemed focused mostly on institutional rather than student needs, and students were unprepared for the offer and decision. There was no provision to explain the program and help students decide if they should consider the online option.

    Now UF Online offers a mandatory PaCE Preview:

    This consists of a full day of informational sessions followed by one-on-one sessions with an advisor and concluding with first semester registration.

    They have also added remote site visits:

    We Come to You help sessions: For the first time, in March 2017, UF provided a local site visit in Coral Gables, FL to answer questions about PaCE and help students and their families to make an informed decision.

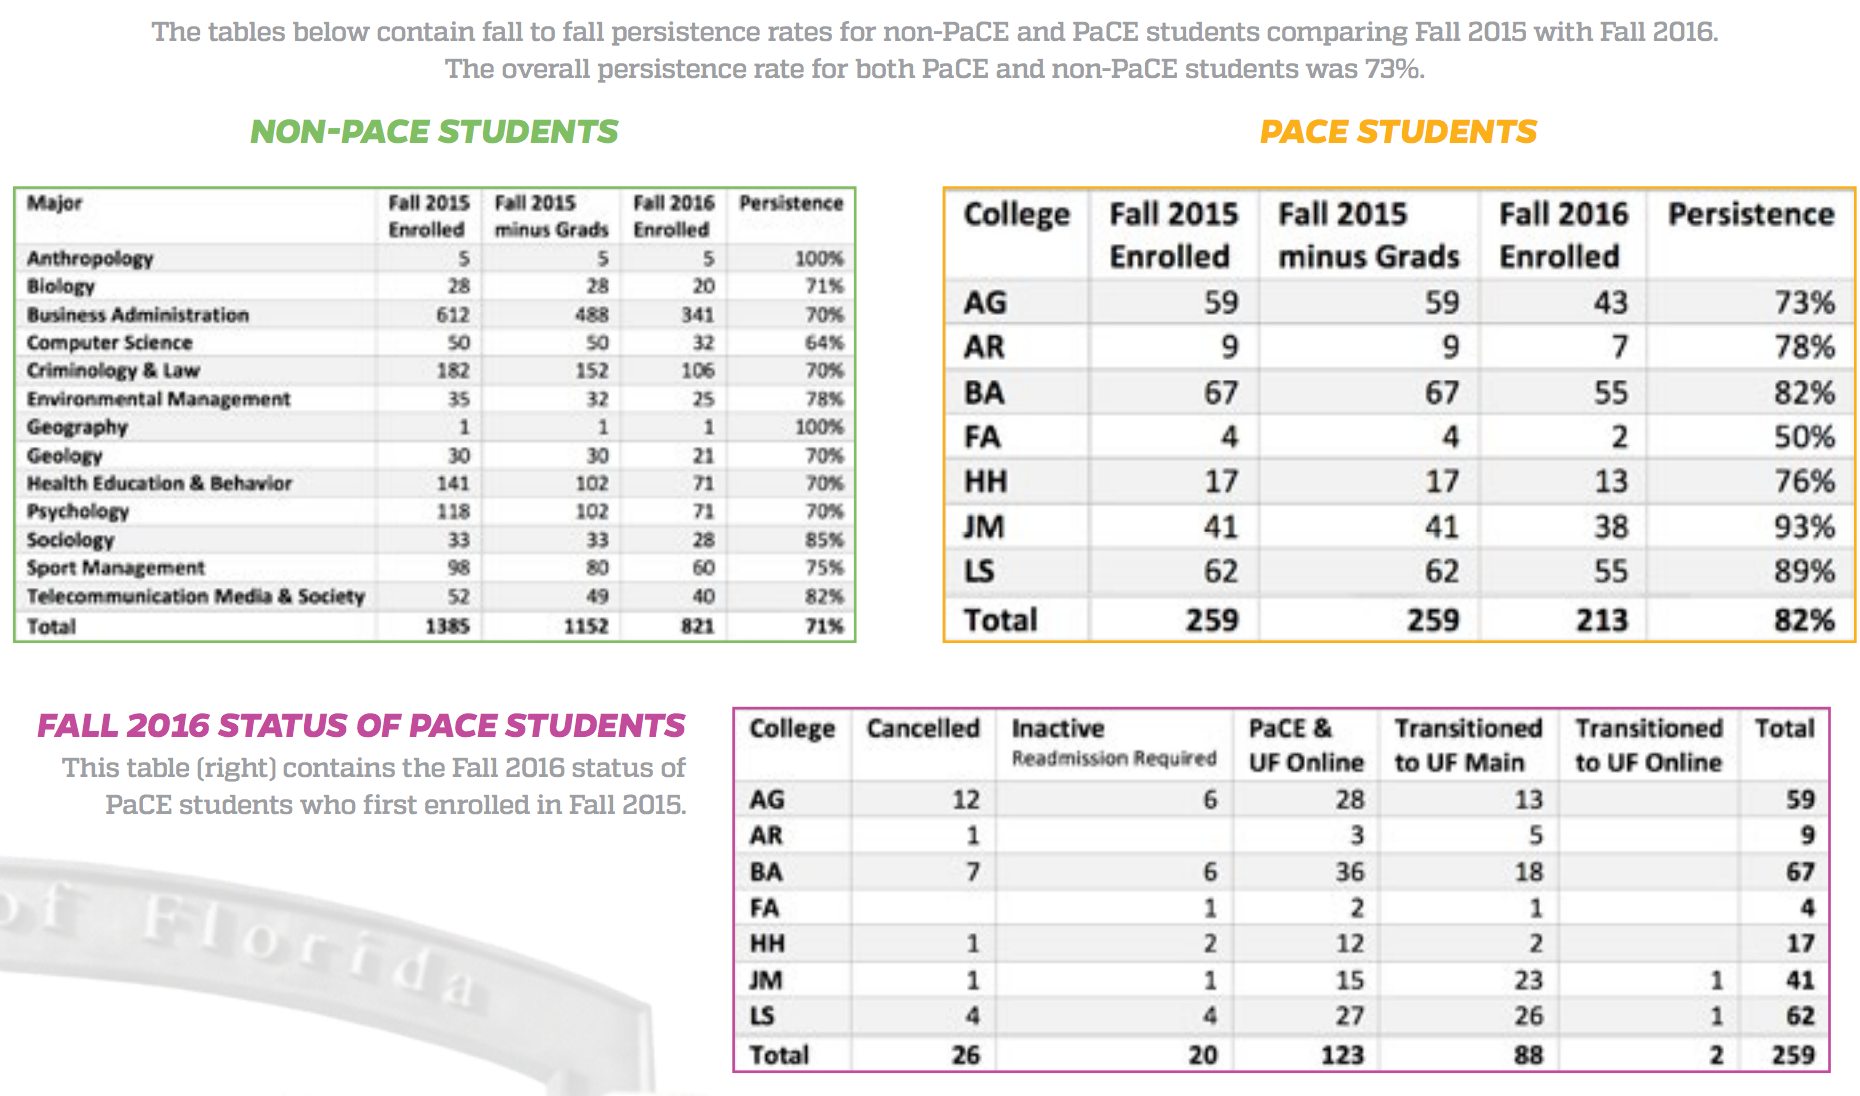
    Given that PaCE students are a different group – they did not initially apply to be an online student – it makes sense that UF Online now reports fall-to-fall persistence data for non-PaCE and PaCE student groups. And they even give a breakdown by academic program and updated status of the PaCE students who enrolled in 2015.

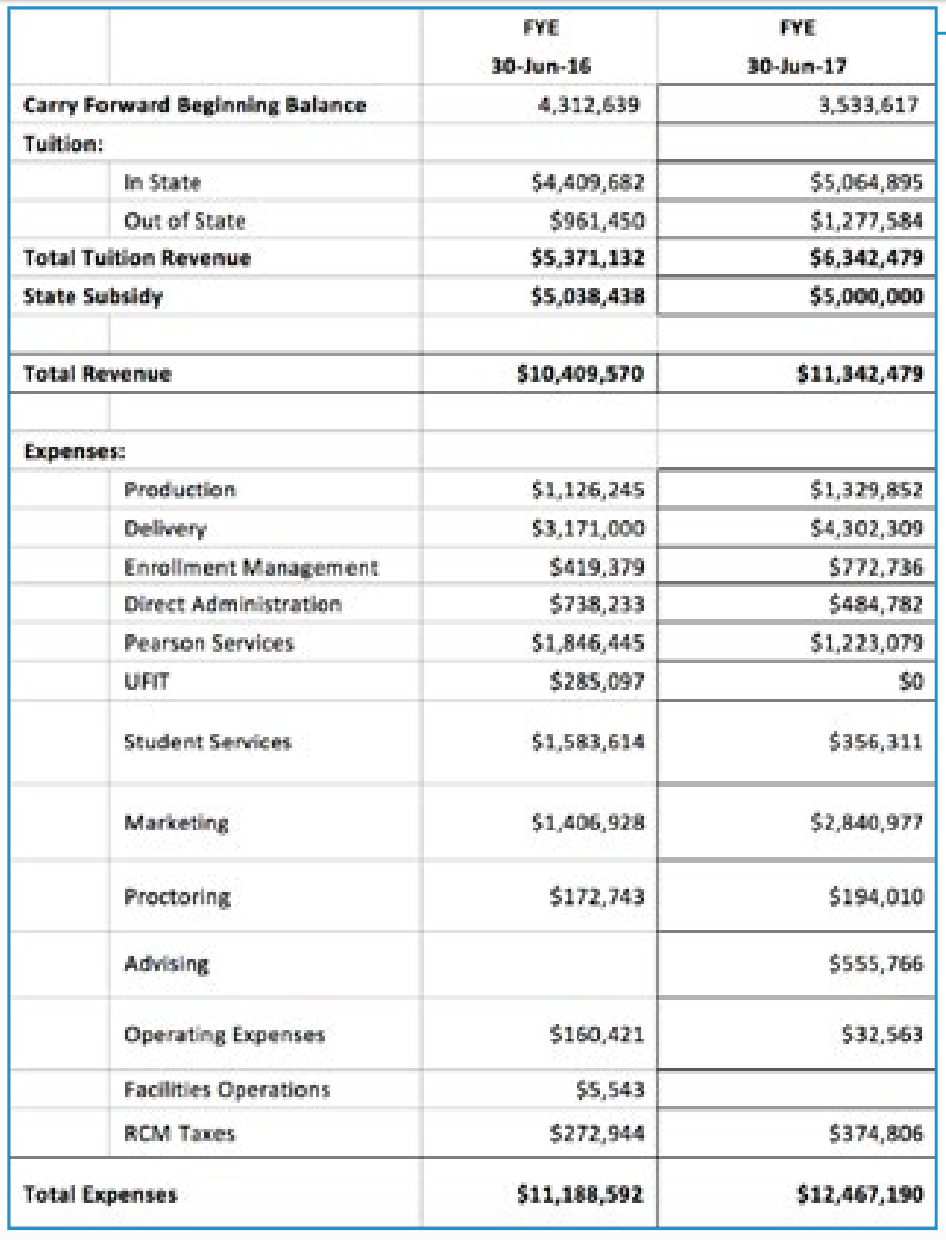
    There are also detailed financials, showing that UF Online is currently bringing in $6.3 m of tuition revenue and $5.0 m of state subsidies and spending $12.5 m.

    UF Online still has challenges – improving persistence rates, getting to break-even financials, etc. And they are not the only online program with this level of success. What makes UF Online so interesting to watch is that they made some hard choices to get past faulty original planning assumptions, they are very transparent in sharing their information publicly, and this is a very positive case of higher education embracing and learning from an outsider.

  • Unizin Membership Now Set As Annual Fee Of Up To $427.5k

    Unizin Membership Now Set As Annual Fee Of Up To $427.5k

    I’ve been meaning to provide an update on Unizin now that the consortium is three years old (started officially in July 2014). Thanks to public documents from the University of Minnesota, one of the 11 founding members, we now have additional clarity on the ongoing costs to remain a member of Unizin.

    Membership Fees

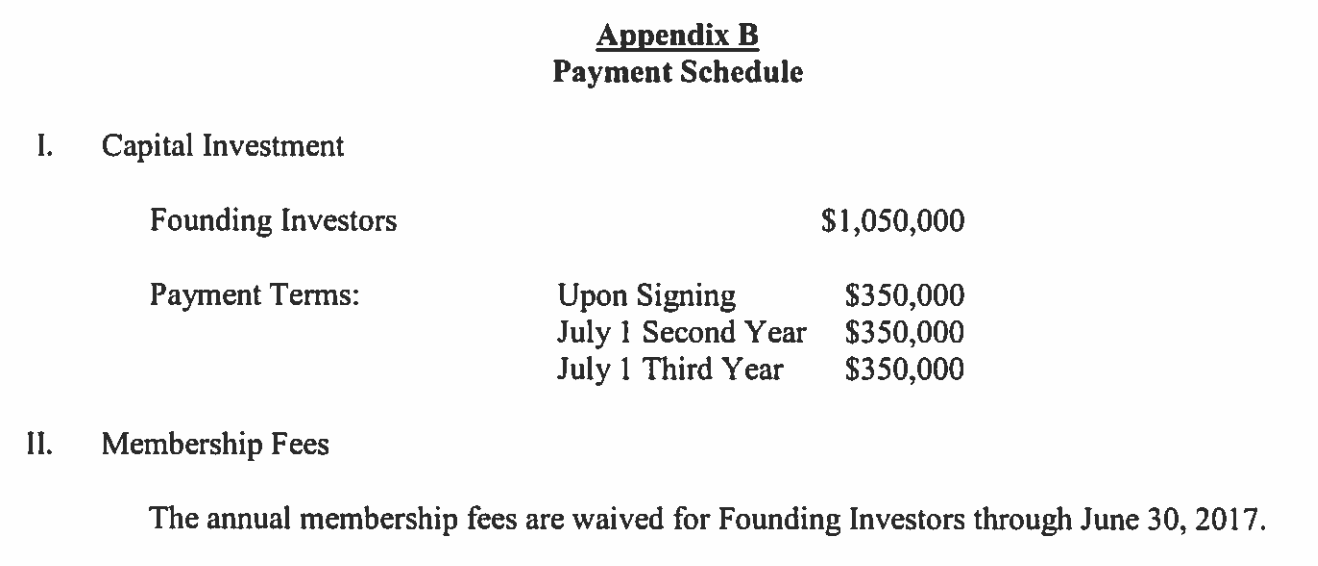
    For some background, Colorado State University staff back in April 2014 described the $1,050,000 initial fee in their meeting minutes for the University Technology Fee Advisory Board:

    3. Will this decrease overall costs on our end through collaboration?
    a. We are investing $1 million up front, but there is about a 7-year payback. We are investing in a $10 million product since the other 9 universities are putting their money in as we are too. This will absolutely decrease our costs.

    One year later, when the Florida State University System joined Unizin as associate members, we noted this item from the University of Florida / Unizin Consortium Membership Agreement:

    We noted at e-Literate in our article from 2015:

    Does this mean that founding institutions that “invested” $1.050 million over three years will have to start paying annual fees of $100,000 starting in June 2017? That’s my assumption, but I’m checking to see what this clause means and will share at e-Literate.

    Update (7/17): I talked to Amin Qazi today (CEO of Unizin) who let me know that the annual membership fee for institutional members (currently the 11 schools paying $1.050 million) has not be determined yet.

    Fast forward to 2017 and we have an answer. The University of Minnesota has to submit purchases over $1 million to its board of regents for consent, and at the July 2017 meeting the new Unizin membership fees were presented:

    To Unizin, Ltd. for $1,282,500 for a three-year renewal of membership in the higher education consortium for the Office of Information Technology (OIT) for the period July 1, 2017, through June 30, 2020. The annual payment of membership fees will be covered from OIT’s central O&M funds. The FY18 budget includes planning and funding for this expense.

    That equals $427,500 per year for the next three years for the 70,000+ enrollment university. What this now makes clear is that the up-front investment in Unizin was not a one-time fee broken up into three easy payments. Unizin member has an ongoing annual fee set in three-year periods.

    I again asked Amin Qazi for clarification, including whether all Unizin members were now paying the higher fee ($427.5k vs. $350k for initial three years). Amin confirmed via email:

    Unizin is a non-profit organization and seeks to cover its costs. We have found that our cost to provide our services and tools somewhat scale with the size of the institution. The Unizin Founding Member Fees have been adjusted after the initial three year period. So while larger institutions do pay more, smaller institutions pay less. We anticipate further adjustments as we grow and are able to recognize even greater economies of scale.

    I would then assume that the University of Minnesota, along with University of Michigan and Penn State University, are paying at the highest level and more than $350k, and that smaller schools like the University of Iowa and the University of Nebraska are paying less than $350k.

    LMS Fees

    The same University of Minnesota document also describes their costs for the Canvas ((Disclosure: Instructure is a subscriber to our market analysis service.)) LMS based on the Unizin agreement.

    To Unizin, Ltd. for $5,023,000 for a purchase of Canvas Learning Management System (LMS) for the Office of Information Technology (OIT) for the period July 1, 2017 through June 30, 2022. [snip]

    Unizen [sic], on behalf of its member institutions, conducted a competitive Request for Proposal followed by a detailed evaluation process. Through this process Canvas by Instructure was selected as a Learning Management System (LMS). The University then conducted a two year pilot of Canvas and a majority of the stakeholders preferred Canvas to the University’s current LMS, Moodle. Most of the Big Ten schools have adopted or are adopting Canvas.

    The University receives an additional 30% discount by purchasing Canvas through Unizen [sic] rather than purchasing directly through Infrastructure [sic] and 3% caps on annual increases, rather than 5%, has been negotiated.

    This five-year deal comes out to $12 – $14 per student per year. The document does not specify what level of support they have chosen, although they describe a “dedicated test server”.

    New Associate Members

    In other news, Unizin announced in July that the University of Nebraska system has joined as associate members.

    The Unizin Consortium is thrilled to welcome the full University of Nebraska system, bringing the total number of institutions in the consortium to 25. With the addition, the University of Nebraska at Kearney, University of Nebraska at Omaha, and University of Nebraska Medical Center join Unizin Founding Member the University of Nebraska Lincoln.

    Note that associate members do not pay the same amount as full members. In Florida, the State University System deal costs each associate member $100k per year.

    We’ll likely give updates at e-Literate after the EDUCAUSE conference on how Unizin has evolved in terms of services and potential new members. But for now we at least have more clarity on the financial terms of the consortium.

  • Response on LMS Market Size Analysis

    Response on LMS Market Size Analysis

    Josh Kim wrote a post yesterday at Inside Higher Ed questioning some claims about the LMS market size.

    The first result that comes up in Google is from Zion Market Research. Their estimate is that the global LMS market is valued at $5.19 billion in 2016, and expected to reach $19 billion by 2022.

    According to Statista, the LMS market in 2016 was valued at $3.21 billion. CNBC claims that the learning management system market is worth $5.2 billion today, and will grow to $16 billion in four years.

    Can these numbers be right?

    Josh then did a quick analysis based on Instructure’s revenue and came up with much smaller numbers.

    If we assume that the cost of Canvas is about average for LMS companies, we can get an estimate of the total market size by multiplying Instructure’s revenues by five. This gives us an estimate for the total size of the LMS market $555 million.

    He extended this by 50% based on Instructure growth to give an estimate of $555 – $832 million, which is way below the big numbers claimed by Zion, MarketsandMarkets, and other market analysts.

    The biggest difference here is that all of these analysts combine corporate learning markets with academic LMS usage, and corporate learning platforms account for somewhere between $2 – $4 billion, with best estimates (although outdated) coming from Bersin. This point has already been pointed out in the comments at IHE.

    tl;dr – the ~$5 billion number is reasonable if you combine academic and corporate LMS markets.

    There are two caveats, however.

    • First, the market growth claims are marketing fluff to generate interest in buying the reports, as companies love to show growth potential to investors. Anything close to $20 billion in a few years is ludicrous.
    • Second, as Michael commented on this approach based on a post I wrote criticizing MarketsandMarkets:

    If anything, my Phil understates the case here. Lumping higher ed, K12, and corporate LMSs into the same category is a little bit like lumping railroad cars together with automobiles because they are both called cars, have wheels, and carry things and/or people from one place to another. On top of that, nobody has decent data on the size of the global market, never mind the growth of it. MarketsandMarkets’ “analysis” effectively gives us made-up numbers about a mythical automobile/train car market.

    So a better question is what is the size of the global academic LMS markets, combining K-12 and postsecondary?

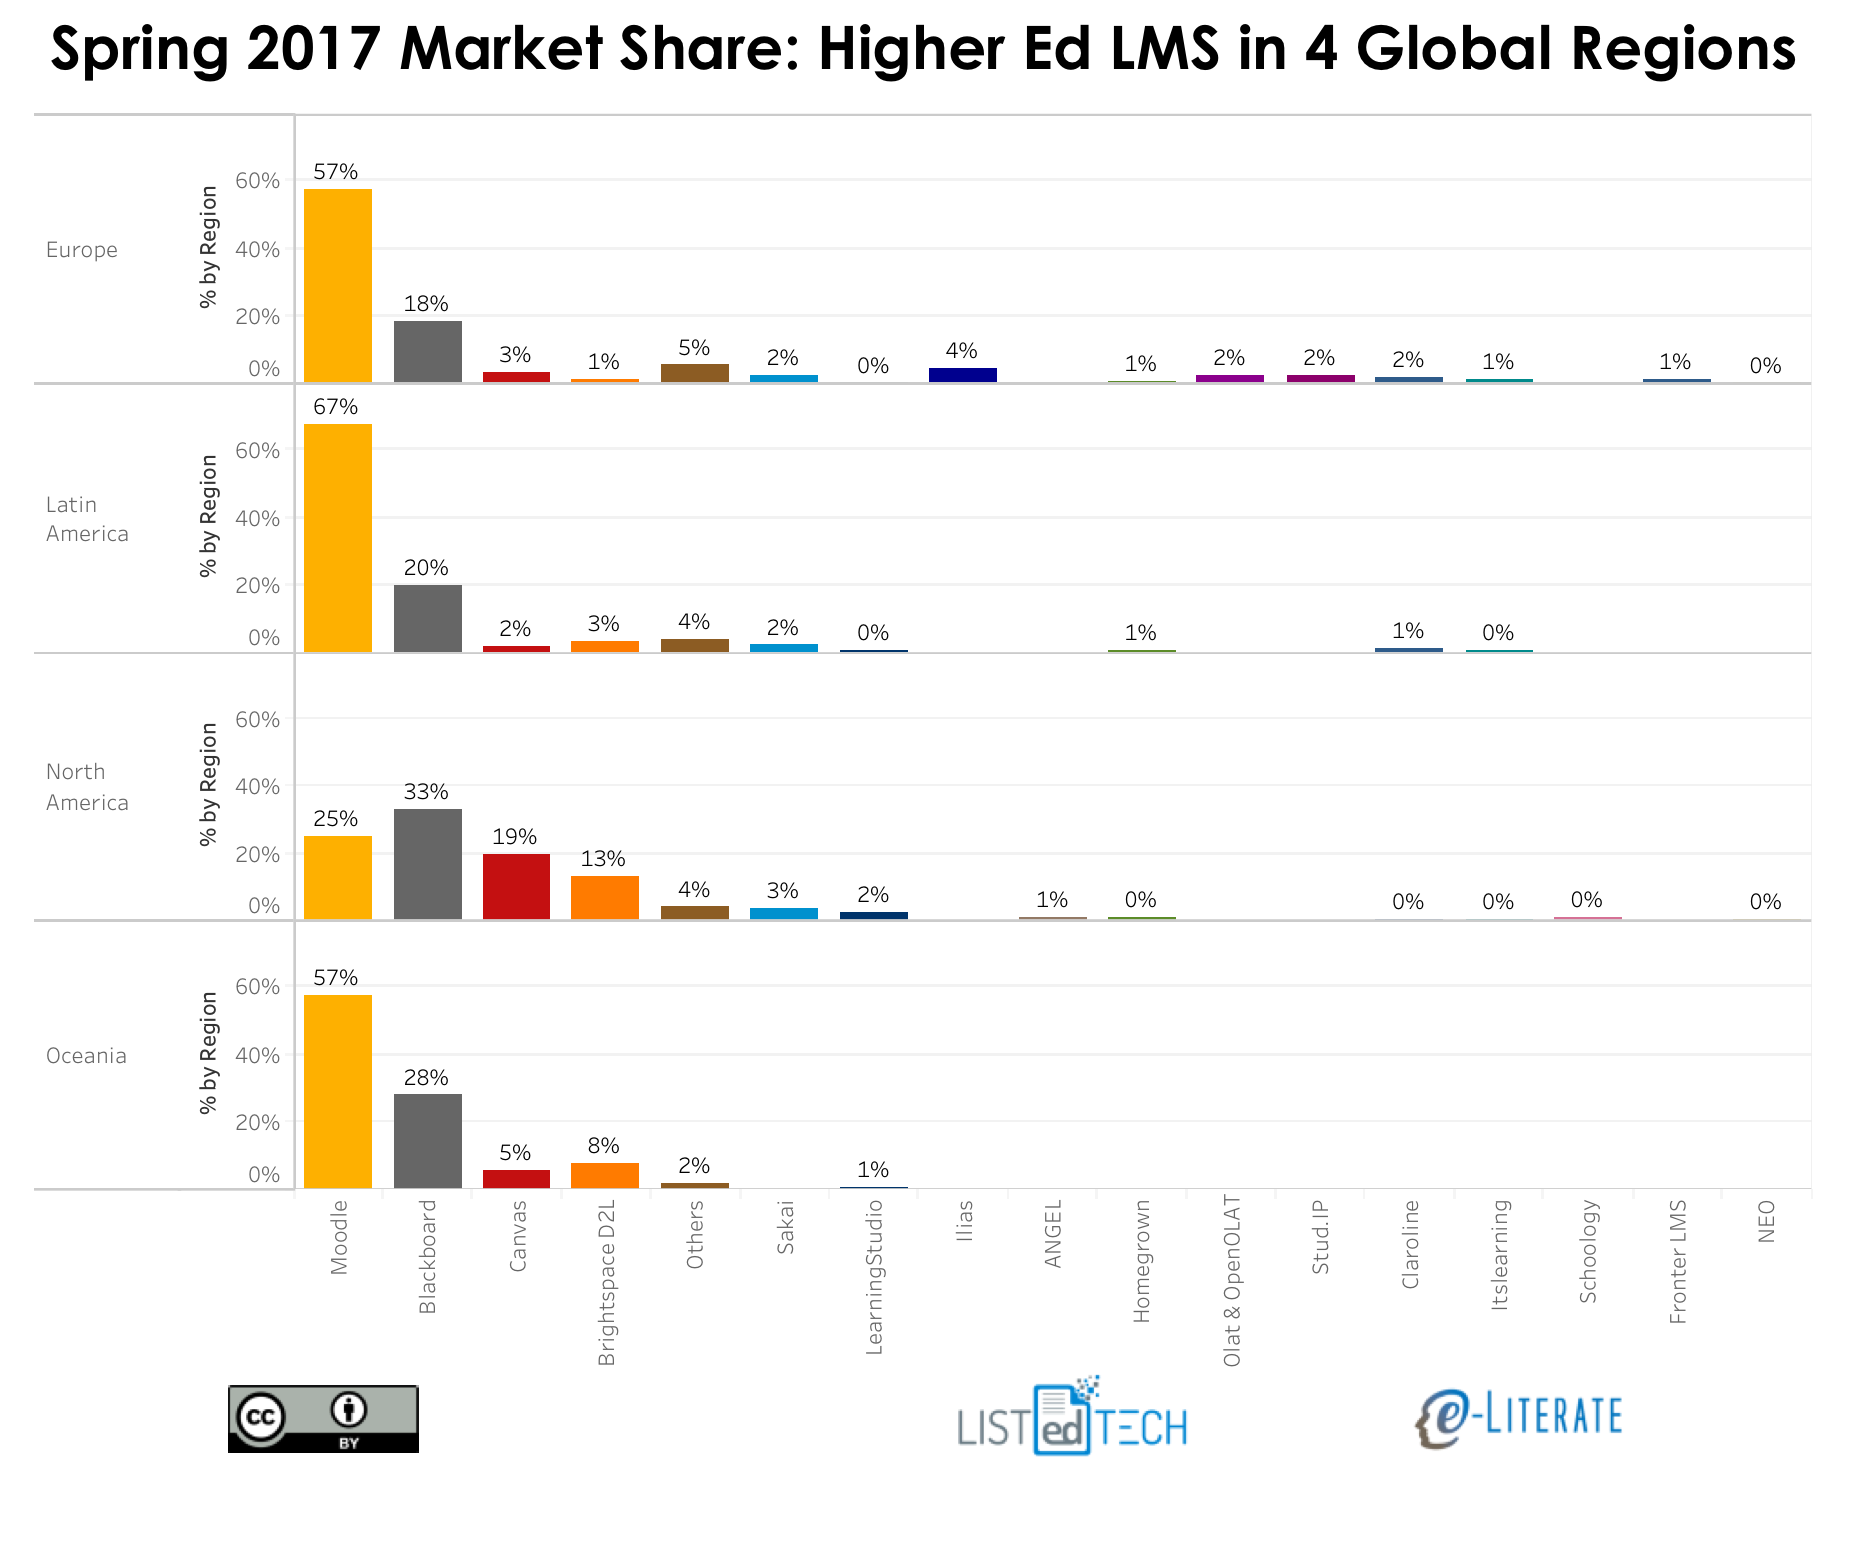
    One issue from the IHE post is that Josh used our 20% market share as basis for extrapolating Instructure’s market share, but that number is only for North American higher education. Globally, Instructure’s market share is much smaller as shown in our recent analysis (data provided by our partners LISTedTECH).

    Furthermore, while Canvas by Instructure and Schoology seem to be leading vendors for new adoptions in the K-12 market, at least in the US, no one has reasonable measures of market share in this area. Long and short – we need a different approach than extrapolation from Instructure alone.

    LISTedTECH estimated the global LMS market just in higher education as $1.7 billion based on (# of students) * (average cost of LMS per student) = annual spending approach. In the US, the best estimates I’ve seen in that K-12 learning platform markets are worth 30 – 40% of higher ed market. This likely is smaller globally, as anecdotally there is not a big emphasis on LMS usage outside North American and Northern Europe. So one very rough estimate is that academic LMS market is worth approximately $2 billion per year.

    If you want to use the company revenue method, then I would use additional data. Blackboard’s LMS revenue is likely $450 – $550 million per year based on reviews of corporate debt filings and extrapolation from their time as a public company. D2L’s revenue is smaller than Instructure’s, so let’s assume the two companies combined have $200 million revenue. Note that in all of these companies this is global revenue for K-12 and higher ed combined. The question is how to scale this $700 million combined revenue from all three companies. Is it reasonable that global spending for academic LMS could be 2 – 3x larger than this number? When you add in all of the Moodle hosting – both Moodle Partners and unofficial Moodle hosting – as well as Chinese market adoption, European providers, and K-12 players like Schoology and Powerschool/Haiku, this seems at least believable.

    So my highly-researched, thoroughly-documented estimate of the global academic LMS market is $1.5 – 2.0 billion per year. And it is forecast to grow to $8.2134526 billion by June 3, 2022.

    Note to investors – ignore that forecast.

  • Some Ed Tech Perspective on UC’s Billion-Dollar Payroll System Fiasco

    Some Ed Tech Perspective on UC’s Billion-Dollar Payroll System Fiasco

    In 2011 the University of California laid out plans for a new payroll system called UCPath (for Payroll, Academic Personnel, Timekeeping, and Human Resources). The goal of the $170 million project was to save a reported $100 million per year eventually and to replace a 30-year-old Payroll Personnel System (PPS) that runs separately for each of the 11 UC locations with Oracle’s PeopleSoft payroll and HR systems. All systems were planned to be live by the end of 2014 and run centrally in a new UCPath processing center.

    In 2014 we described how the project had grown from $170 and 36 months to $220 million and 72 months. In spring of this year we described how the project was planned to cost $504 million and take 93 months (almost five years longer than originally planned).

    A few weeks ago the state auditor released a report claiming that the project would really cost $942 million. The $942 million does not mean that the $504 million estimate has changed since spring, but the auditor does claim that UC is not reporting the full costs of the implementation. From the audit summary on page 1:

    The Office of the President currently projects the implementation cost of UCPath to be $504 million—$334 million over its original estimate of $170 million—and it has delayed the date of UCPath’s implementation by nearly five years, to June 2019. Moreover, the $504 million estimate does not represent the full cost of the project because it includes just a fraction of the cost associated with the campuses’ implementation efforts and a shared services center, known as the UCPath Center. The full cost to the university of adopting UCPath is likely to be at least $942 million.

    Most of this information was available in the spring, but the state auditor makes a compelling, well-documented argument.

    The Worse Part

    However, this is not the big news from the audit. In my 2014 post I commented on Christopher Newfield’s analysis at Remaking the University on the claimed benefits from the project:

    What about the current estimate of benefits – is it $30 million per year as Chris described or closer to $100 million per year? One big concern I have is that the information on project benefits was not updated, presented to the regents, or asked by the regents.

    Well it turns out that was exactly the problem based on this finding from the audit:

    The Office of the President’s initial business case in 2011 asserted that UCPath would result in $753 million in cost savings, primarily from staffing reductions at the campuses. However, the UCPath project director told us that the Office of the President no longer expects to realize those projected savings. Several campuses also reported to us that they do not anticipate the staff reductions that the 2011 business case promised. In fact, in a status update to the University of California Board of Regents (regents) in July 2017, the Office of the President did not discuss any offsetting savings but rather discussed creating efficiencies and avoiding costs.

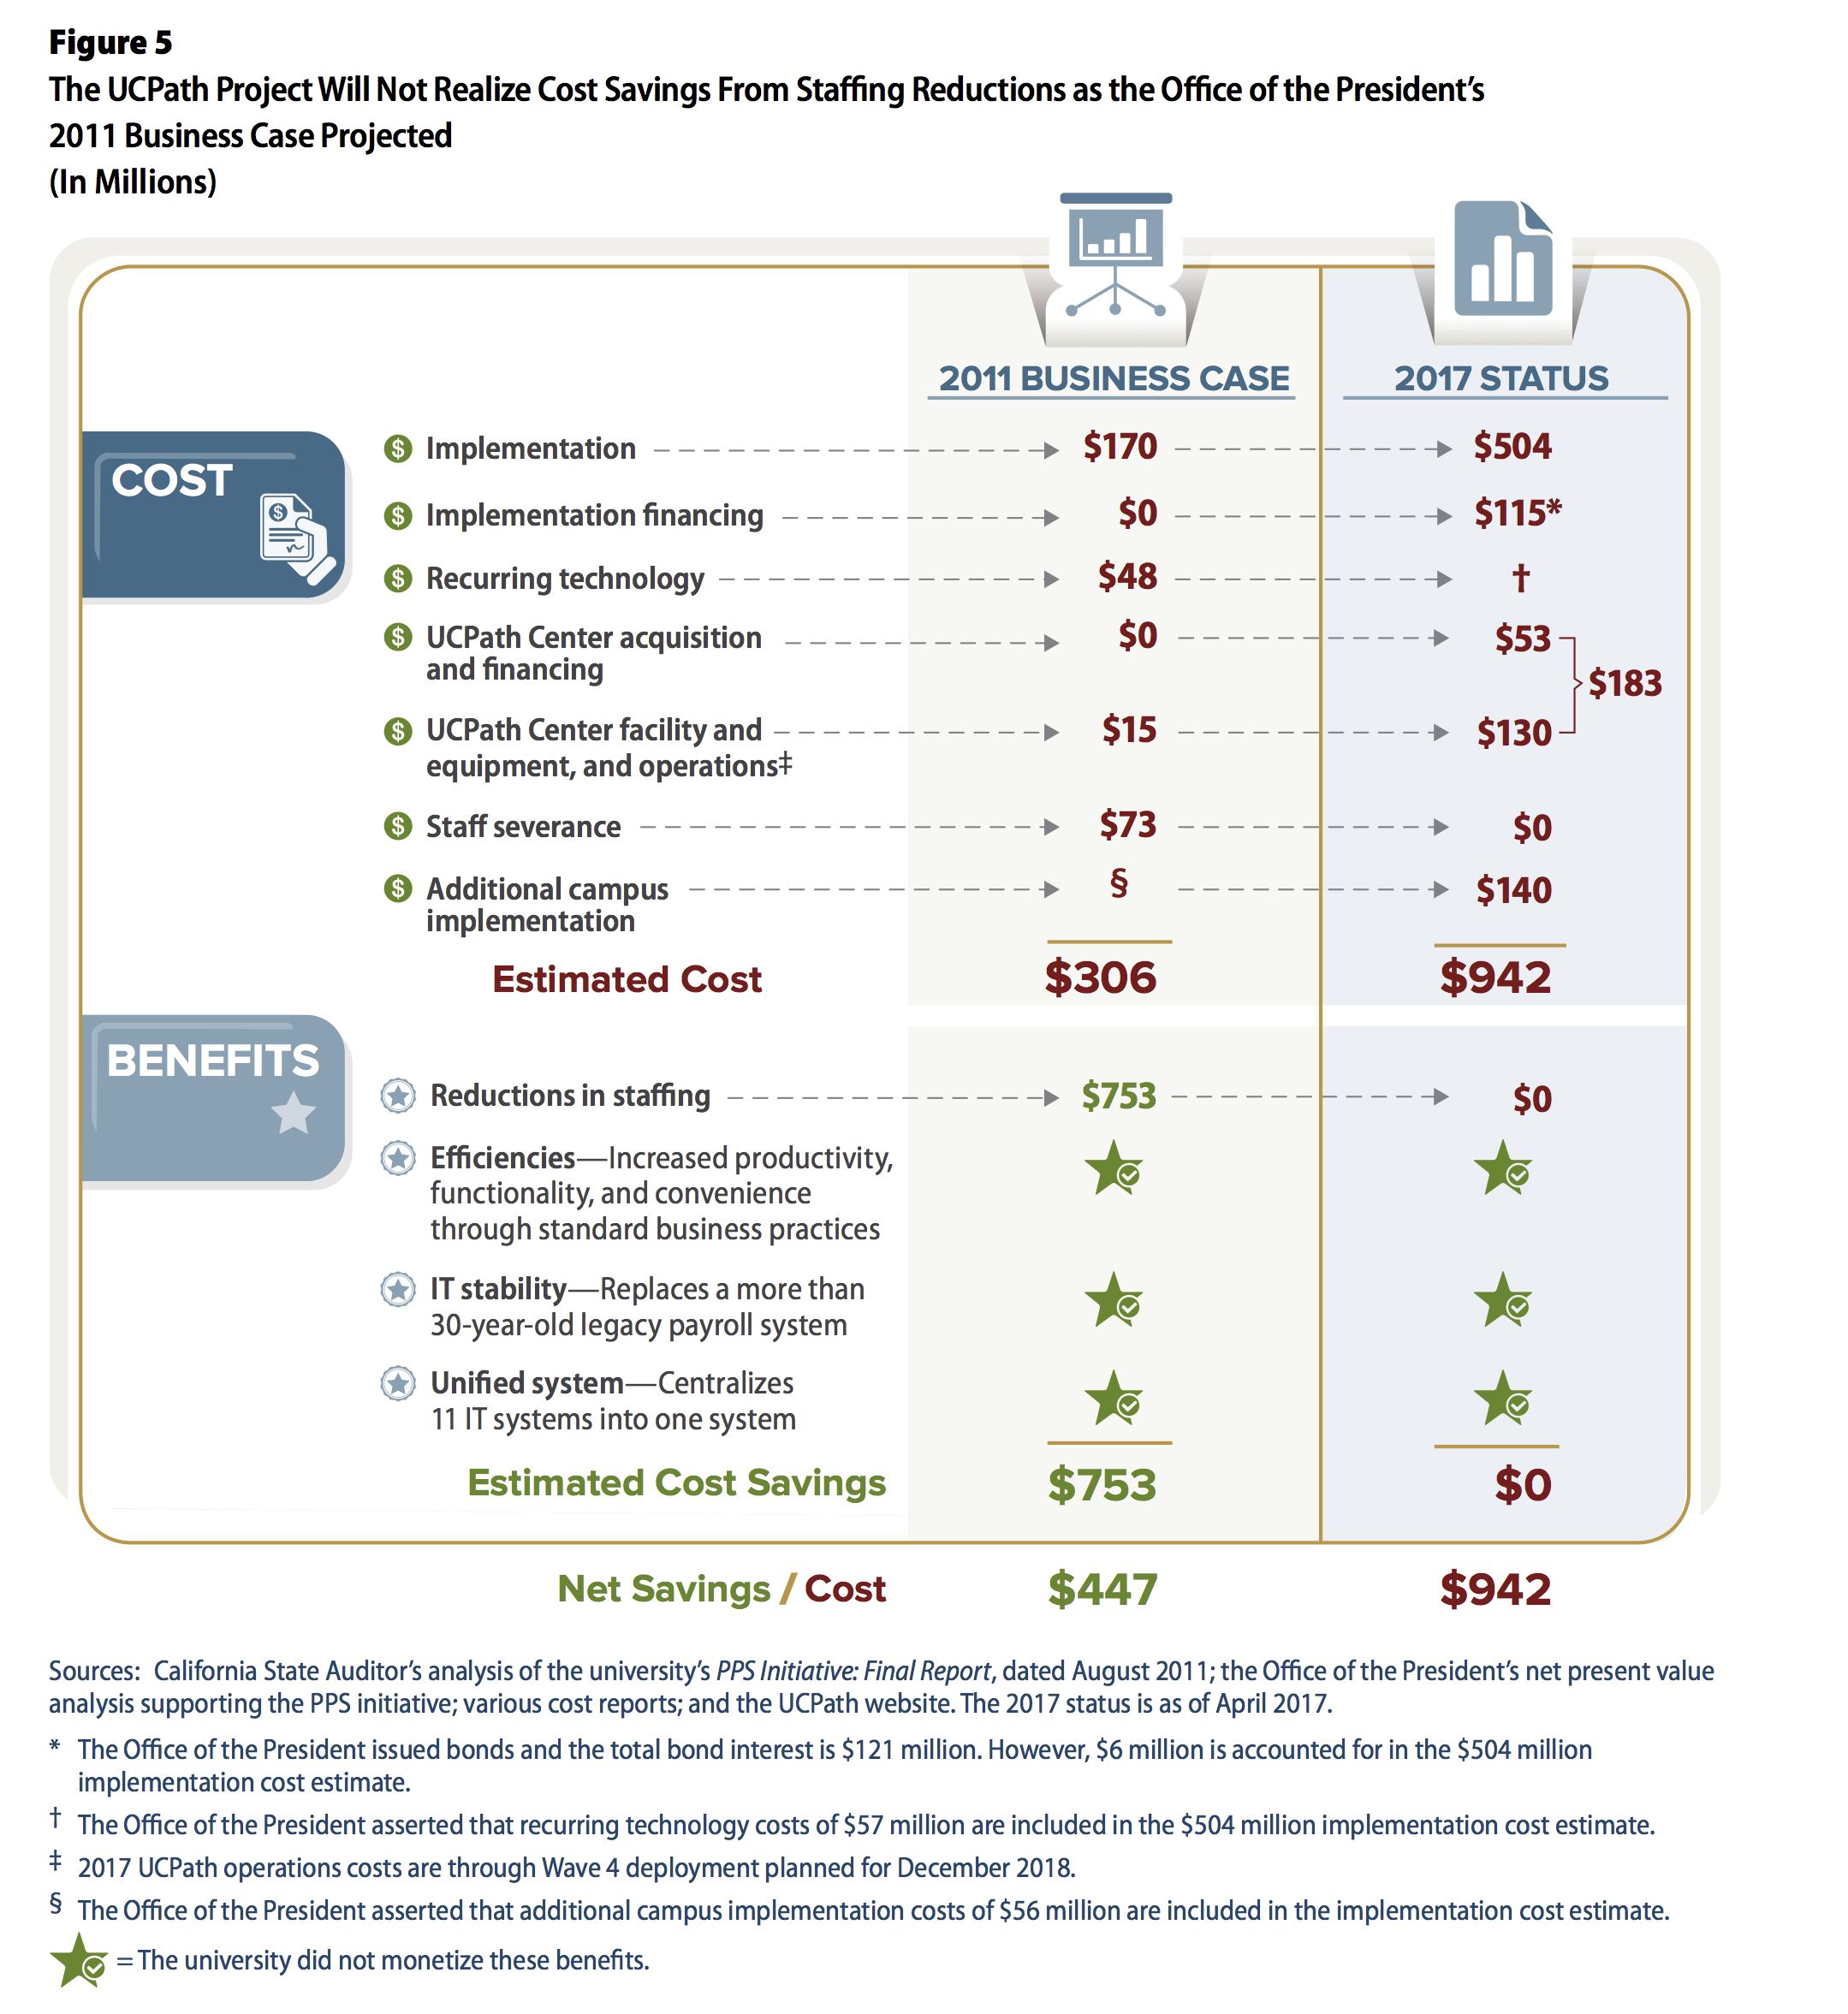
    You read that right. The $753 million in savings that was the basis for the project is not going to materialize. There clearly was a need to replace 30 year old systems, but the justification for the UCPath project and its specific approach was based on large staff cuts to be achieved by centralizing payroll for all 10 universities in the system. To get the true scale of the cost impacts of this project, look at this helpful chart from page 16 of the audit (note the $504 million in top right – that is the cost claimed by UC):

    What this means is that the net savings / cost have changed by almost $1.4 billion. Let that sink in. Billion with a ‘b’.

    UC Response

    The University of California Office of the President (UCOP) responded to the audit both formally in the audit report itself and informally through media statements. The official UCOP statement starting on page 35 of the audit mostly notes that President Napolitano was not at UC when UCPath started, that this is a necessary and complex project, claims they have already made improvements, and it disputes some of the specific recommendations as being heavy-handed. But at no point does UCOP dispute the findings. What is most problematic is the emphatic claim at the end:

    I have complete confidence in UC’s ability to continue successful implementation of UCPath, a necessary project with significant, expansive, and long-term benefits to the University.

    There is no serious re-questioning of assumptions or of UC’s ability to finish the job, despite plenty of evidence pointing to fundamental problems in the project.

    The UC response in the UCLA paper is even more problematic, as it mostly argues that the implementation only costs $504 million many other items are operational in nature.

    Claire Doan, a UC Office of the President spokesperson, said the state audit includes additional costs that should not contribute to the overall cost estimate. [snip]

    The UCPath Center will assume all payroll and human resources functions systemwide, according to the state audit. Doan added the UC believes the $130 million the state audit cited for the center’s operating cost should be included in the project’s operations budget, rather than its implementation budget, because the UC does not typically include operating expenses in project implementation costs.

    In other words, UCOP is complaining about accounting methods while not disputing the findings. UCOP wants to just look at IT implementation costs, while the state auditor is looking at “the full cost to the university of adopting UCPath”.

    Some Perspective

    We here at e-Literate are focused more on ed tech – the impact of changes to teaching and learning enabled by technology. So it might help to add some ed tech perspective on this story.

    Taking the well-grounded assumption that the project, or some form of it, was necessary, and making the assumption that UC’s original plan made some sense ($170 million for IT implementation), let’s look just at the impact of cost overruns.

    • Using the UCOP argument, the IT implementation cost overrun is currently $334 million
    • Using the state auditor argument, the total UCPath cost overrun is currently $636 million
    • Adding in the disappearance of planned savings, the change in savings / cost is almost $1.4 billion

    Keep in mind that much of the project is funded by a 20-year bond. Some comparisons using that time frame (we’ll factor in inflation and cost increases by adding 1.5x for a range):

    • Based on typical UC campus costs and extrapolating, the cost of providing an LMS for every UC campus for 20 years is likely $66 – $99 million
    • Using EDUCAUSE Core Data of $96 – $110 per student median spend in the US, the costs of centralized instructional technology support of all applications and services for every UC campus for 20 years is likely $500 –  $850 million

    The fallout from UCPath’s cost overruns and loss of planned savings likely exceeds the entire combined instructional technology budget for all 10 UC campuses. This project matters.

  • California Should Watch Arkansas Process for Creating New Online Institution

    California Should Watch Arkansas Process for Creating New Online Institution

    Two months ago I wrote a post about Governor Brown’s directive for a fully-online community college in California, noting that:

    What this points to is that for a new fully-online institution to get to some meaningful level of enrollment (let’s say 20,000) in the same ballpark as these comparison schools, I estimate it would take a full decade at the least. This is the reason, by the way, that Mitch Daniels and Purdue University made the Kaplan University deal even though Kaplan’s enrollments are dropping. Daniels did not want to wait a decade to get to meaningful enrollment numbers for an online college serving working adults – if everything works out, within a year Purdue will have a fully-online institution serving 30,000+ working adults. That is a big if, by the way.

    This estimate is probably optimistic, however, based on the outlook for eVersity, the fully-online institution being created in the state of Arkansas. The eVersity leaders have decided that they cannot wait for regional accreditation as reported at Inside Higher Ed today [emphasis added].

    When the University of Arkansas System envisioned creating the online-only institution eVersity in 2014, it planned to follow the well-worn path trodden by other public higher education systems in launching fully online institutions: building on the accreditation of the system’s other universities before seeking independent approval from the regional accreditor.

    But come January, eVersity will seek approval from the Distance Education Accrediting Commission — a national body that overwhelmingly accredits for-profit and nonprofit online institutions — rather than the Higher Learning Commission, which accredits all other public institutions in Arkansas and many nonprofit colleges in 18 other states.

    One of the primary factors shaping eVersity’s decision is speed. The regional accreditor told the university that it could take roughly six years for HLC to award its stamp of approval, while DEAC — assuming it affirms eVersity in January — will have acted in just under two years. Institutional accreditation is required for eVersity students to gain access to federal financial aid, and to ensure that their credentials are valued by employers and others.

    The challenge with national accreditation includes severe limitations on students being able to transfer credits out of the school.

    On the issue of speed, [senior policy analyst at the Center for American Progress] Flores noted that institutions waiting for regional accreditation can often apply for federal aid during the candidacy stage of their application, and that students who attend regionally accredited institutions will have a much easier time transferring their credits than those who attend nationally accredited ones. Flores said eVersity seemed like “a little bit of an odd fit” for DEAC, which typically accredits smaller for-profit institutions that don’t offer federal aid.

    The IHE article (very well-written, by the way) described the path chosen by previous fully-online institutions.

    A more conventional route to regional accreditation, however, is to start as a division of an already regionally accredited campus, said Goldstein. This is what the University of Maryland University College did before obtaining independent regional accreditation. Colorado State University Global Campus also went this route.

    [Chief academic and operating officer of eVersity] Moore said that eVersity decided not to do that, as it did not want to be under the academic and administrative control of another University of Arkansas System institution. “We wanted the ability to be nimble and responsive and not burdened by legacy systems, practices and policies. There are certainly advantages to built-in infrastructures, but they also come with a cost,” said Moore.

    Think about the implications – if a state wants a new, fully-online institution to serve working adults, there seems to be four choices before there is meaningful impact in numbers of students enrolled in institution:

    • Establish new, separate institution, choose regional accreditation, be patient in realistic enrollment growth, and expect 10 – 15 years for meaningful impact
    • Do the above but choose national accreditation and limit transfer ability and possibly impact enrollment, and expect 6 – 11 years
    • Establish division of another school using their accreditation, then spin off for separate institution later on, and risk getting caught up in traditional institution’s legacy policies and practices (unknown timescale)
    • Pull a Mitch Daniels and buy an existing online (or mostly online) institution through creative process, risk not being approved due to transfer of control, and risk getting caught up in the online institution’s legacy policies and practices – and expect 2 – 3 years if the bet works out

    California likely faces similar choices with the fully-online college directive being evaluated this fall. This is a legacy-building project, but there will be real pressure to not have to wait 10 – 15 years to start getting meaningful impact. eVersity from Arkansas is going through this same process ahead of time, and the California team should learn lessons by watching what works and doesn’t work in this case.

    More broadly, the IHE article ends with a key point about accreditation needing to change.

    Russell Poulin, director of policy and analysis at the WICHE Cooperative for Educational Technologies, said that accreditors needed to figure out how to accredit new providers more quickly, without compromising on quality. “Accreditation is slow and innovation is fast; we are starting to see political and business pressure to find alternatives,” he said.

    Read the entire IHE article. This subject is important.

  • Enrollment Implications Regarding Directive for Online Community College in California

    A month ago Governor Jerry Brown directed Eloy Oakley, Chancellor of the California Community College System (CCCS) ((Disclosure: The Online Education Initiative from CCCS is a client of MindWires. The views in this and future posts represents my independent views and not OEI’s.)) to “take whatever steps are necessary” to establish a fully-online college. At first glance this directive appears to be a solution in search of a problem, so it is worth looking beyond the headline see what is motivating this move.

    In an article from Community College Daily:

    Noting that the system has significantly expanded the number of online courses, Brown said, “I believe it is time now for our community colleges to increase even further the availability of online courses and degree programs – and make college far more accessible and affordable.”

    Reaching more students

    “The governor has been interested in realizing the promise of online education for a number of years,” Oakley said in an interview with CCDaily. He added that Brown also wants a way to reach more nontraditional students.

    “We have literally tens of thousands of working adults with some college and no credentials and a couple of million working adults who are unemployed or underemployed,” Oakley said. “This is a wonderful opportunity to reach a population that really needs a community college to achieve economic mobility.”

    The details are not yet worked out, and Oakley is pulling together a group to advise on the options available to make this directive a reality, with the recommendations due in November. Oakley’s comments clearly establish access for nontraditional students to be the ultimate driver. In an interview with Inside Higher Ed, Oakley commented further:

    “Part of this is the governor’s desire to reach more students in California through a technology platform,” said Eloy Ortiz Oakley, chancellor of the California Community College system. “The 114 campuses are designed in a traditional manner, so we’re reaching a traditional population that is students coming out of high schools.”

    But a new online-only college could reach students those traditional brick-and-mortar campuses are currently missing — adults who are unemployed or underemployed, he said.

    To achieve these goals of reaching more working adult students, there are some real challenges to address.

    View of CCCS Enrollment Mix

    It is worth viewing the historical headcount numbers available from the Chancellor’s office, focusing on age group to get a better understanding of the status quo.

    The headcount for CCCS peaked in 2009 at 2.93 million students and has since dropped to the current 2.36 million level, a reduction of 19%. Across the state, colleges are looking for ways to increase, or at least slow the decrease, in overall enrollment.

    What is most striking in the data, however, is the shift from older students (age 25 and above, or “adults”) to younger students (age 24 and blow, or “traditional”) for the community college system, with the mix roughly reversed from 25 years ago. Chancellor Oakley and Governor Brown are right to note that the older student population is not being served well, at least if we use actual enrollment as a proxy. And the situation is getting worse, not better. However, while the majority of students in CCCS are 24 or younger, there are also a large number of older adult students. In other words, there appears to be an overlap between the students in the current 114 colleges and the target students for the new fully-online college. This will present quite a challenge for Oakley and other planners to make the following statement from the IHE interview a reality.

    “We don’t want to cannibalize the system, and we wouldn’t want to create a college to take enrollment from other colleges,” Oakley said. “Any solution would have to complement what we do, and it has to have an opportunity to share revenue with the colleges and really enhance their ability to serve students.”

    This statement is sounds good on paper and will be crucial in terms of getting at least tacit support from the current colleges to the creation of a new, full-online college. But the data shows there is not a clear and easy path to serve adult, non-traditional students without affecting existing colleges.

    National Trends

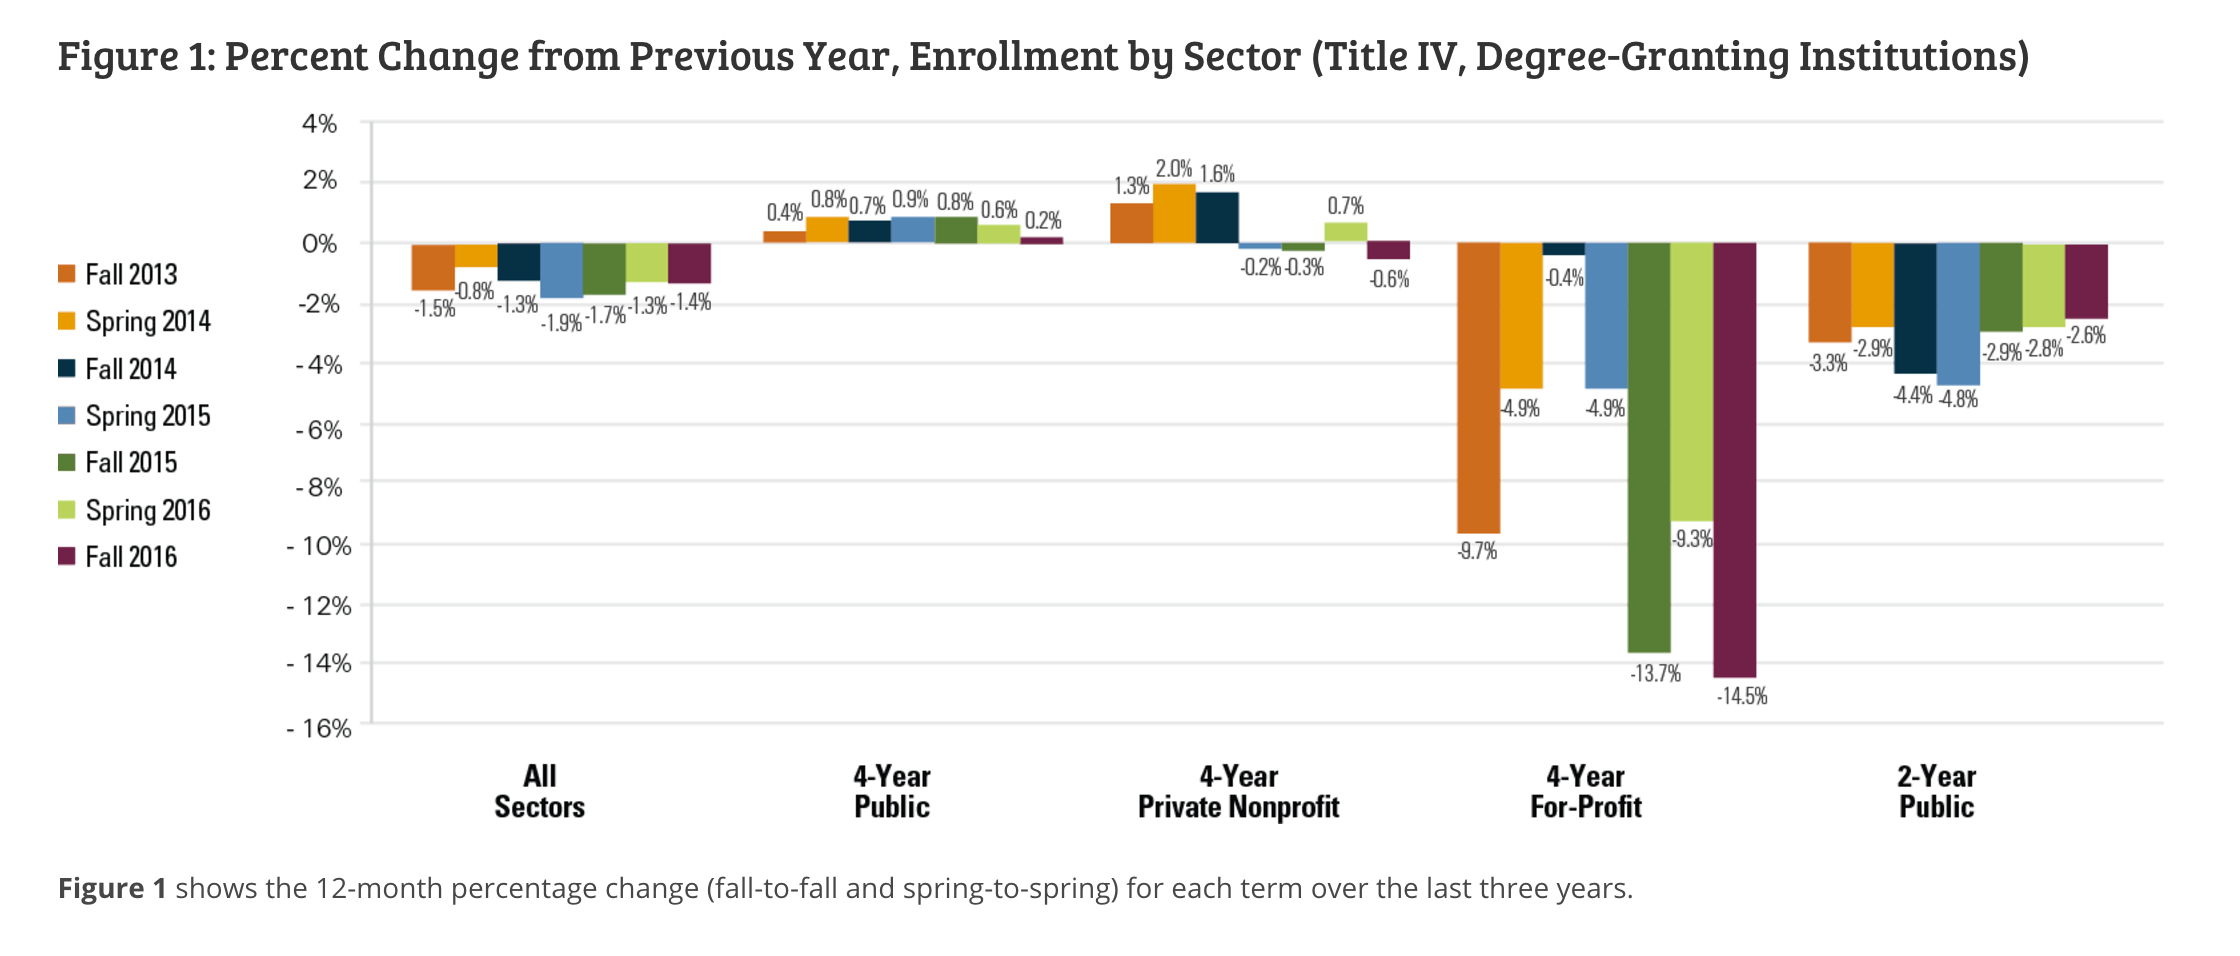
    In this situation California is not alone. The National Student Clearinghouse research for Fall 2016 shows first that community college (2-year public) enrollments have been dropping nationwide.

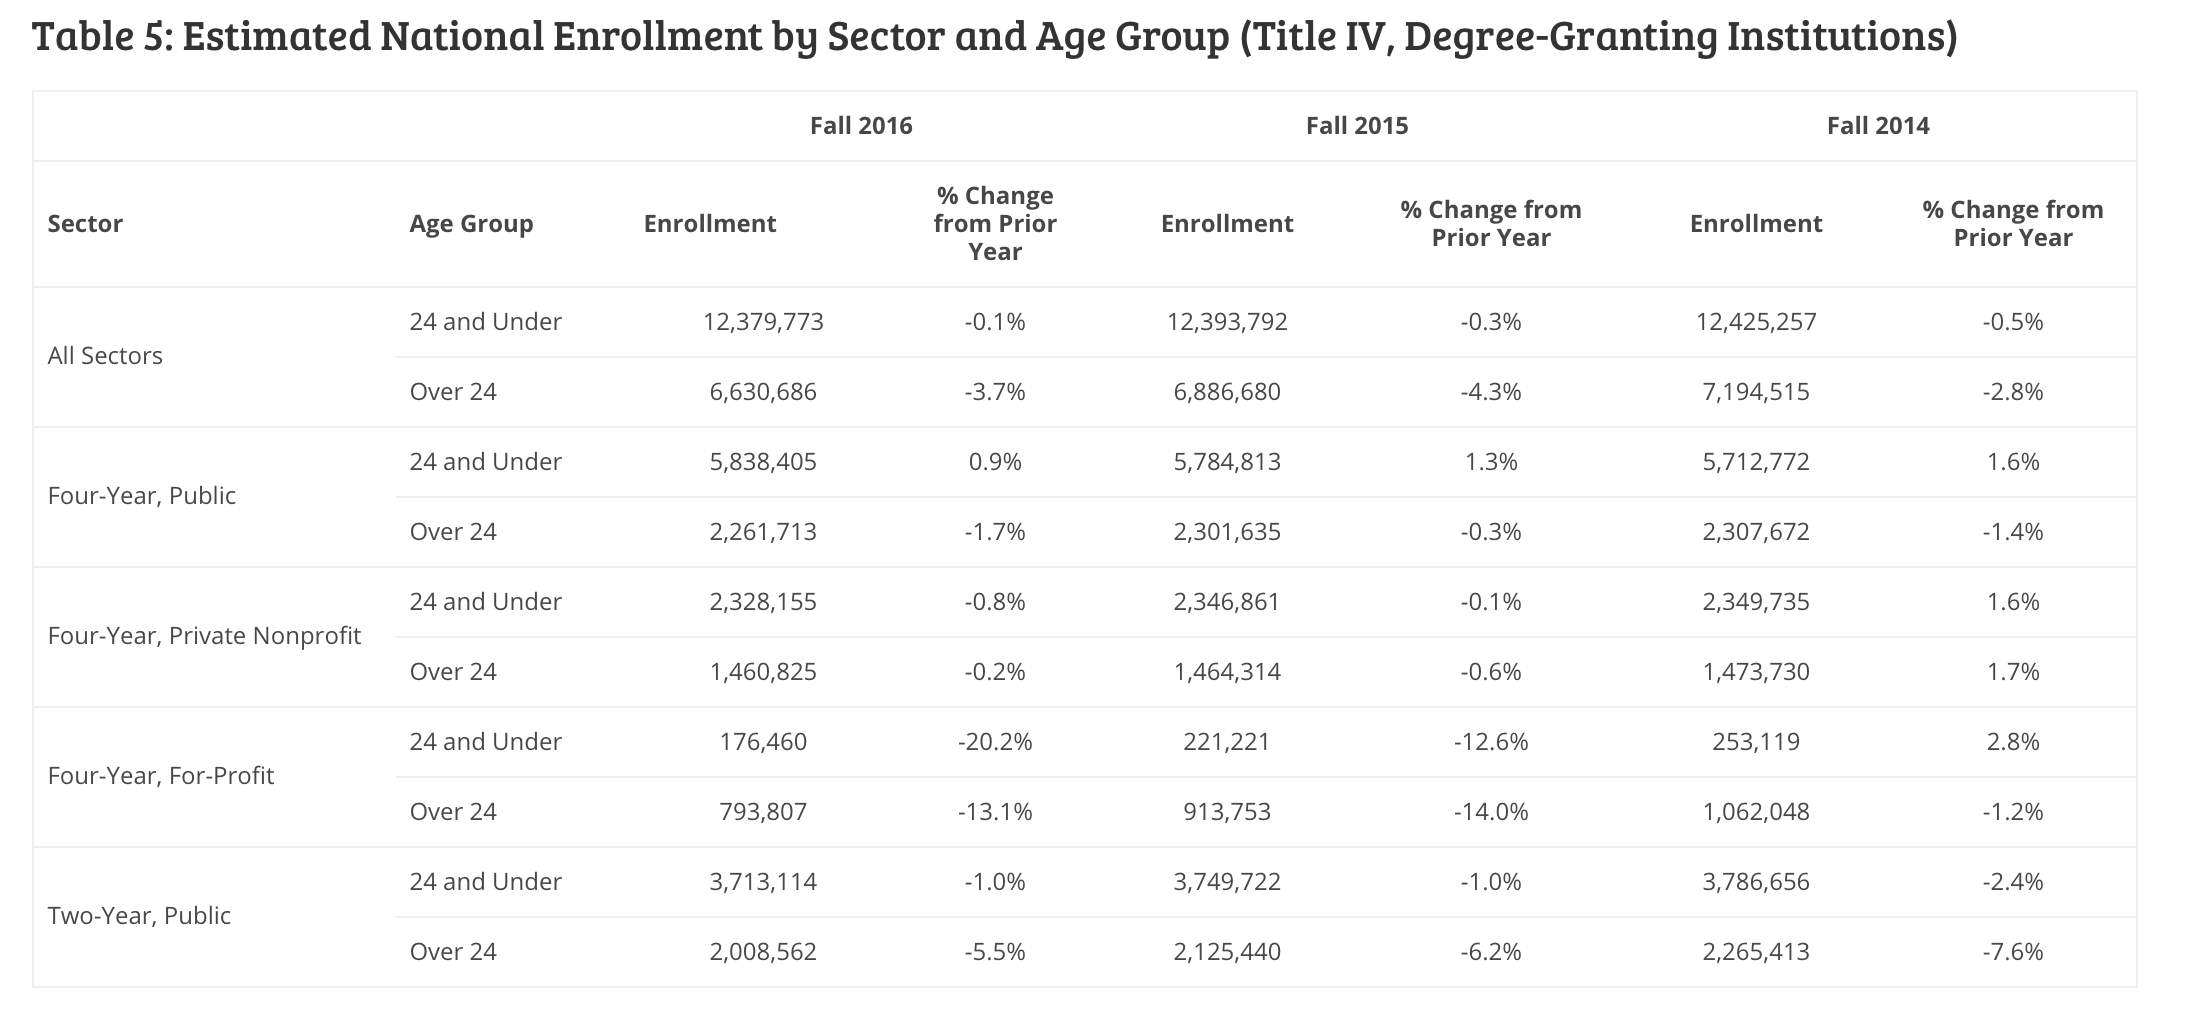
    And just like in California, adult student enrollment has been dropping much faster than 18-24 year old enrollment. 24 and under groups have dropped 1.0 – 2.4% per year while 25 and above groups have dropped 5.5 – 7.6% per year (see bottom two rows).

    This will be another challenge for the CCCS planning team, as there is no indication that California is screwing up while other states have the same problem figured out – the reduction in community college enrollments, particularly for adult students, appears to be a nationwide demographic trend.

    Comparison Colleges

    Assuming that the plan works out and they find new enrollment opportunities that don’t cannibalize existing college student groups, it is also worth considering how large this college might become. I pulled together the IPEDS data for several of the top-growing online undergraduate colleges ((The comparison colleges might not be exclusively online, but they have become at least predominantly online.)) to get some idea of what the best-case scenario might be in terms of enrollment growth. This data looks at fall enrollment numbers which will be lower than full-year headcount numbers.

    Once we get past the “holy crap, look at Southern New Hampshire University’s (SNHU) growth”, there are a few observations to make.

    • We’ll have to see where SNHU goes, but there has traditionally been a ceiling to the size of online enrollment per institution of around 80,000 – 100,000. The primary exception has been the University of Phoenix that reached a quarter of a million online students back in 2010, but their enrollment has been dropping since then and are more of the exception that proves the rule. All others have peaked well under 100,000 students. Just this spring Liberty University experienced their first recent enrollment drop, leading to staff layoffs.
    • The maximum growth rate of these cherry-picked successful schools ranges from ~1,200 / year for Excelsior to ~7,700 / year for SNHU (note that Rio Salado at ~1,400 / year is the only public institution). Add to this the fact that all of these schools have been around for decades. No accreditation issues, no time-consuming establishment of core leadership team, etc.
    • There is a big difference in dealing with institutional issues and statewide issues, particularly in California. One in five US community college students in the US do so in California, and the statewide issues tend to come in large numbers. Statewide issues tend to come in hundreds of thousands while institutional issues tend to come in tens of thousands.

    What this points to is that for a new fully-online institution to get to some meaningful level of enrollment (let’s say 20,000) in the same ballpark as these comparison schools, I estimate it would take a full decade at the least. This is the reason, by the way, that Mitch Daniels and Purdue University made the Kaplan University deal even though Kaplan’s enrollments are dropping. Daniels did not want to wait a decade to get to meaningful enrollment numbers for an online college serving working adults – if everything works out, within a year Purdue will have a fully-online institution serving 30,000+ working adults. That is a big if, by the way.

    None of this analysis is to argue that CCCS should not try to establish a fully-online college. The goal of better serving nontraditional populations – adult students with and without jobs – is worth pursuing on its own merits.

    The numbers do argue, however, for a realistic view on the challenges they face:

    • Fighting against national demographic trends for adult students of community colleges;
    • Trying to avoid cannibalizing enrollment from existing California Community Colleges;
    • Having the patience to support the schools while it take years to grow to a size with meaningful enrollment levels; and
    • Accepting that best case this approach probably recovers less than 10% of the enrollment drop since 2009.

    I would hope that the CCCS planning efforts take the hard numbers into consideration when searching for different options to satisfy the governor’s directive.